
 Body Fat Measurement Market | 2026-2036
Body Fat Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Body Fat Measurement Market Analysis
The capital-intensity divergence between clinical imaging systems and consumer wearables is reorganizing competitive dynamics across the Body Fat Measurement Market. Hologic sustains premium positioning through its DEXA technology leadership in hospital networks. Tanita specializes in bioelectrical impedance scales for home users and health clubs across Asia. Omron leverages its cardiovascular device distribution to extend reach into pharmacy and retail channels.
Body fat measurement encompasses techniques that quantify adipose tissue mass relative to total body composition through electrical, optical, radiographic, or hydrostatic methods. DEXA systems employ dual-energy X-ray absorptiometry at 70-140 kVp to deliver whole-body composition analysis with precision near 1% for fat mass. Bioelectrical Impedance Analysis devices dominate unit volume due to sub-hundred-dollar price accessibility, though DEXA retains the margin pool in clinical reimbursement environments. Optical and infrared technologies are gaining traction in fitness assessment applications where non-contact speed outweighs absolute accuracy requirements.
FDA 510(k) clearance pathways shape device commercialization timelines for manufacturers targeting US hospitals, while EU MDR requirements are elevating clinical evidence standards for DEXA and impedance analyzers in European markets. Japan's PMDA maintains distinct approval categories that InBody navigates for its domestic professional segment. Stakeholders must weigh regulatory investment against channel strategy as home-user segments face lighter oversight but fiercer price competition.
Market Dynamics
DEXA reimbursement compression is restructuring competitive positioning across the Body Fat Measurement Market, forcing manufacturers to recalibrate between premium clinical channels and high-volume consumer segments.
Growth Catalysts
- Fitness chain biometric screening:North American health clubs are embedding body composition stations into membership workflows, creating pull-through demand for connected impedance devices.
- EU MDR clinical evidence requirements:Elevated standards for DEXA and impedance analyzers are filtering out marginal competitors, consolidating volume among established certificate holders.
- Home health monitoring infrastructure:Post-acute care programs in Japan are reimbursing remote body composition tracking for metabolic syndrome patients.
Market Restraints
- Input cost volatility:Rare earth magnet pricing for DEXA X-ray tube assemblies fluctuates with Chinese export quota adjustments.
- Technical limitation:Bioelectrical impedance accuracy degrades significantly with hydration variance, limiting clinical diagnostic utility.
- Regulatory friction:FDA 510(k) clearance timelines for novel optical sensing modalities extend 14-22 months versus 6-9 months for predicate device pathways.
Strategic Opportunities
- Underpenetrated geography:Brazil's private health network expansion creates first-mover positioning for DEXA operators outside São Paulo and Rio corridor.
- Technology convergence:Integration of photoplethysmography with bioelectrical impedance is enabling single-device cardiovascular-metabolic screening.
- Distribution innovation:Direct-to-consumer subscription models for impedance scale hardware-plus-analytics bypass traditional retail margin structures.
Industry Challenges
- Skill gap in radiologic technologists:DEXA operation certification requirements exceed available training pipeline capacity in secondary US hospital markets.
- Capex intensity:Full-body DEXA systems require shielded room construction and lead apron inventory, raising facility readiness costs.
- Integration complexity:Electronic health record interoperability for body composition data lacks standardized APIs across Epic, Cerner, and MEDITECH deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Fat Measurement Market |
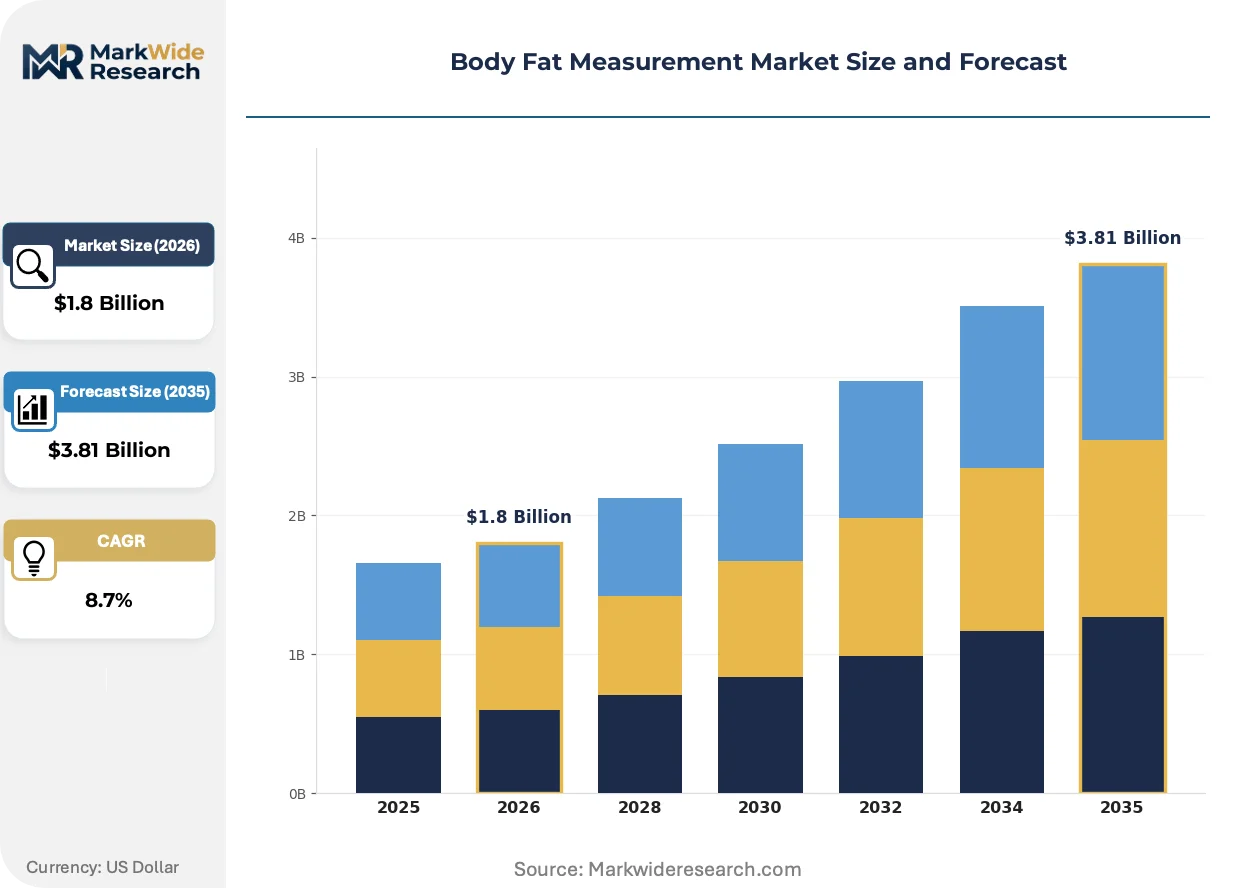
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioelectrical Impedance Analysis, Calipers, DEXA, Hydrostatic Weighing Technology: Infrared, Acoustic Waves, Electrical Impedance, Optical Application: Fitness Assessment, Clinical Diagnosis, Nutritional Guidance, Sports Training End User: Health Clubs, Hospitals, Home Users, Research Institutes |
| Companies Covered | Omron Corporation, Tanita Corporation, InBody Co., Ltd., Beurer GmbH, Hologic, Inc., GE Healthcare, seca GmbH & Co. KG, COSMED Srl, Bodystat Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Fat Measurement Market Emerging Trajectories
Multi-frequency bioelectrical impedance is displacing single-frequency architectures as the default engineering choice for mid-market devices. Three distinct vectors are compressing development cycles and reshaping competitive differentiation.
Segmental impedance analysis is displacing whole-body measurement in athletic performance applications. Professional sports teams and Olympic training centers in Australia and South Korea are adopting eight-point electrode configurations that isolate trunk and limb composition. This precision is compressing demand for hydrostatic weighing facilities and forcing equipment manufacturers to recalibrate sensor density without crossing into DEXA price bands.
EU MDR Article 10 clinical evaluation requirements are extending evidence generation timelines for impedance analyzers seeking CE marking. Manufacturers must now submit peer-reviewed validation studies against reference methods rather than predicate device equivalency. German notified bodies are applying this most stringently to devices claiming diagnostic rather than wellness classification, pushing some applicants toward self-certified fitness-grade positioning.
Pharmacy channel purchasing is consolidating around bundled diagnostic station contracts. US retail health clinics are negotiating multi-parameter kiosk deployments that include blood pressure, glucose, and body composition in single procurement events. This bundling is marginalizing standalone scale vendors and rewarding cardiovascular device suppliers with existing formulary relationships and field service infrastructure.
Body Fat Measurement Market Segmentation
Technology heterogeneity across the Body Fat Measurement Market creates distinct margin architectures. Each segment demands specialized regulatory pathways and channel strategies that reshape competitive economics.
Product Type:
Margins concentrate in hospital-grade imaging systems, while consumer-accessible devices compete on volume throughput.
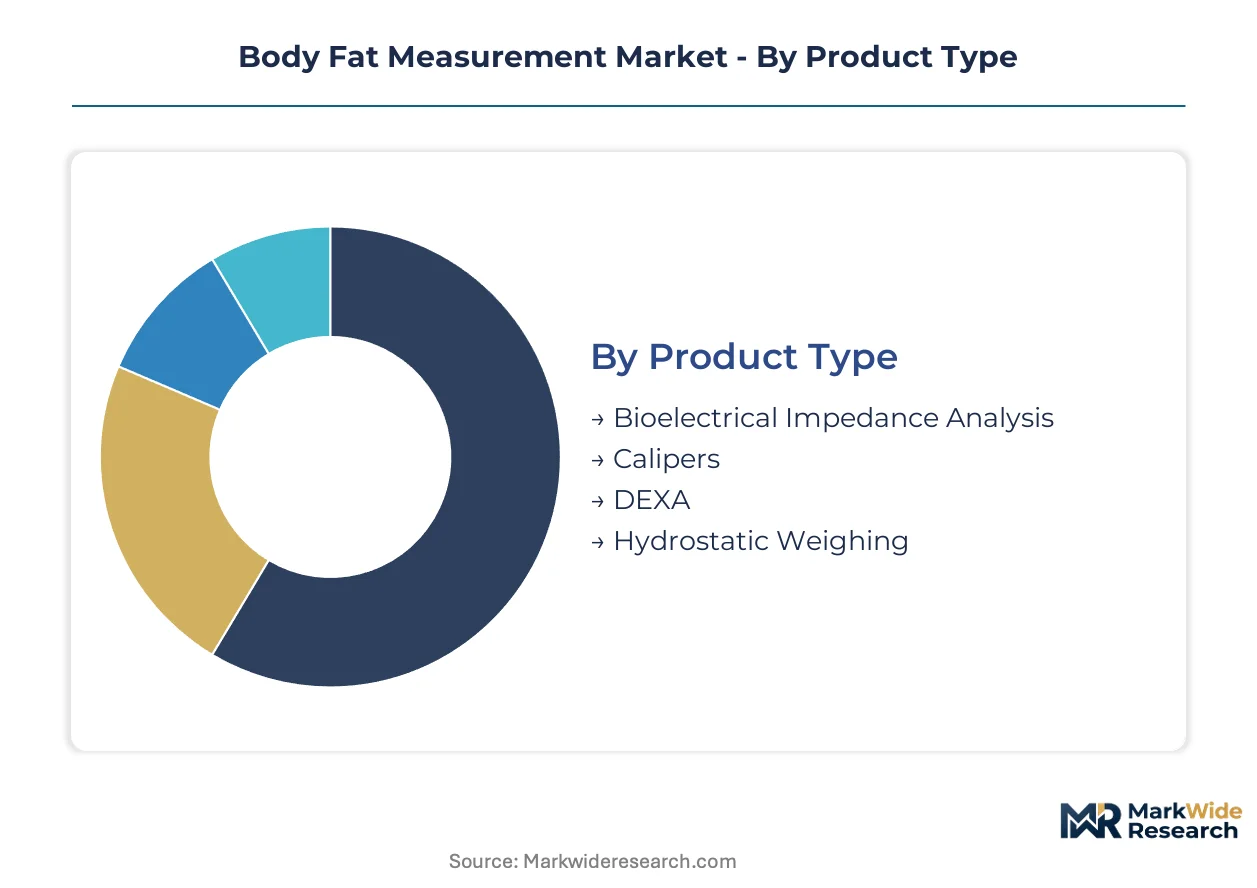
- DEXA:Dual-energy X-ray absorptiometry systems operate at 70-140 kVp to deliver whole-body composition analysis with precision near 1% for fat mass. Demand clusters in US hospital networks where Hologic maintains premium positioning through reimbursement relationships. FDA 510(k) clearance timelines extend commercialization cycles for new entrants.
- Bioelectrical Impedance Analysis:Sub-hundred-dollar price accessibility drives unit volume dominance across home and fitness channels. Tanita scales penetrate Asia-Pacific health clubs while Omron leverages cardiovascular distribution into pharmacy retail. Hydration variance limits clinical diagnostic utility.
- Calipers:Manual skinfold measurement tools serve budget-conscious fitness operators and educational institutions with minimal capital requirements.
- Hydrostatic Weighing:Underwater densitometry facilities face displacement by segmental impedance analysis in athletic performance centers across Australia and South Korea.
The dominant share belongs to Bioelectrical Impedance Analysis, while DEXA is closing the gap fastest through hospital procurement consolidation.
Technology:
Engineering choices determine whether devices pursue clinical certification or fitness-grade positioning under divergent regulatory burdens.
- Electrical Impedance:Multi-frequency architectures displace single-frequency designs as the default mid-market engineering standard. EU MDR Article 10 requirements extend evidence generation timelines for manufacturers seeking diagnostic classification.
- Optical:Photoplethysmography integration enables single-device cardiovascular-metabolic screening. Fitness assessment applications in North American health clubs prioritize non-contact speed over absolute accuracy.
- Infrared:Non-contact thermal measurement suits rapid screening protocols where throughput outweighs precision requirements.
- Acoustic Waves:Emerging modality faces FDA clearance timelines of 14-22 months for novel sensing pathways versus 6-9 months for predicate devices.
Electrical Impedance holds installed base leadership, though Optical is expanding most quickly through pharmacy channel bundling.
Application:
End-use economics split between reimbursed clinical workflows and discretionary consumer spending with divergent price elasticity.
- Clinical Diagnosis:Metabolic syndrome monitoring in Japan's post-acute care programs reimburses remote body composition tracking. DEXA reimbursement compression is forcing manufacturers toward premium channel defense.
- Fitness Assessment:North American health clubs embed body composition stations into membership workflows, creating pull-through demand for connected impedance devices.
- Sports Training:Eight-point electrode configurations isolate trunk and limb composition for Olympic training centers. Segmental analysis precision compresses demand for hydrostatic weighing.
- Nutritional Guidance:Dietitian practices adopt portable impedance devices for office-based counseling with lighter regulatory oversight than hospital deployments.
Clinical Diagnosis commands pricing power, yet Fitness Assessment is gaining share fastest through biometric screening program expansion.
End User:
Procurement authority and technical sophistication create distinct sales motion requirements across customer types.
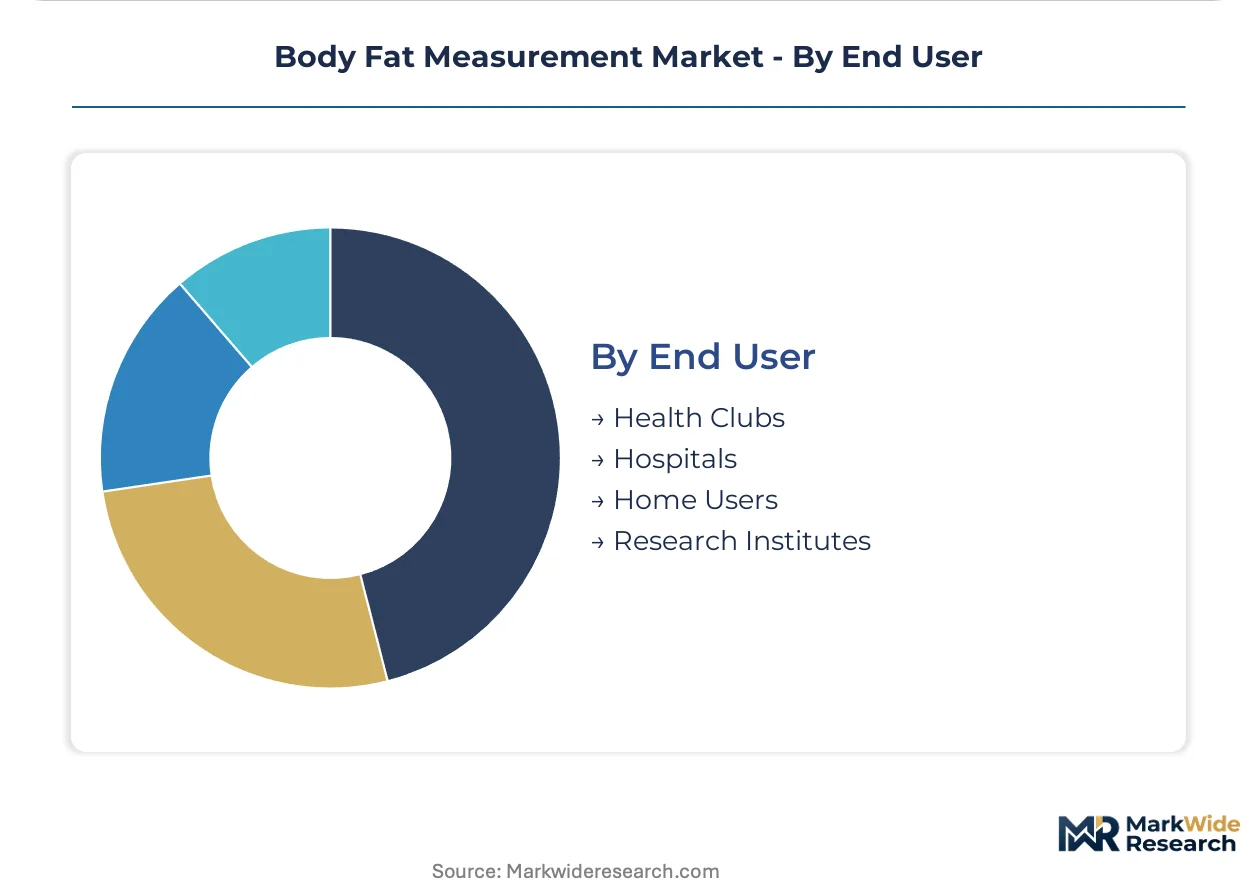
- Hospitals:Full-body DEXA systems require shielded room construction and lead apron inventory, raising facility readiness costs. Skill gaps in radiologic technologist certification exceed training pipeline capacity in secondary US markets.
- Health Clubs:Fitness chains negotiate multi-parameter kiosk deployments bundling blood pressure, glucose, and body composition. This procurement pattern marginalizes standalone scale vendors.
- Home Users:Direct-to-consumer subscription models for hardware-plus-analytics bypass traditional retail margin structures. Price competition intensifies with minimal regulatory friction.
- Research Institutes:Validation study requirements for EU MDR clinical evidence filter toward established certificate holders with peer-reviewed publication records.
Hospitals retain the highest per-unit revenue, while Health Clubs are climbing the fastest through membership workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical-grade DEXA systems command premium pricing in German hospital procurement while sub-hundred-dollar impedance scales dominate volume flows through Chinese e-commerce channels. This pricing-power asymmetry between reimbursed medical infrastructure and direct-to-consumer retail channels shapes regional competitive dynamics across the Body Fat Measurement Market.
United States
Fitness chains embed biometric screening stations into membership workflows across 24 Hour Fitness and LA Fitness locations. FDA 510(k) clearance pathways extend commercialization timelines for novel optical sensing modalities to 14-22 months. Hologic anchors premium positioning through DEXA reimbursement relationships concentrated in Northeast hospital networks.
Germany
seca GmbH manufactures clinical-grade instruments from Hamburg while Beurer anchors consumer-grade production in Ulm. EU MDR Article 10 clinical evidence requirements filter marginal competitors from diagnostic-class device applications. Bavarian notified bodies apply stringent validation standards to impedance analyzers claiming metabolic syndrome monitoring indications.
Japan
Post-acute care programs reimburse remote body composition tracking for metabolic syndrome patients through home health monitoring infrastructure. PMDA maintains distinct approval categories that InBody navigates for its domestic professional segment. Tokyo-based distributors consolidate procurement for Olympic training centers adopting segmental impedance analysis.
China
Domestic manufacturers capture volume share in sub-hundred-dollar connected scale segments through Tmall and JD.com distribution. NMPA regulatory pathways for DEXA systems require clinical trial data against reference methods. Shenzhen hardware clusters compress development cycles for multi-frequency bioelectrical impedance architectures.
Brazil
Private health network expansion outside São Paulo and Rio corridor creates first-mover positioning for DEXA operators. ANVISA registration timelines for imported medical devices extend 18-24 months for novel imaging modalities. São Paulo state hospitals concentrate procurement authority for metabolic syndrome screening programs.
Body Fat Measurement Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Body Fat Measurement Market. DEXA specialists command margin pools in reimbursed clinical environments while impedance scale manufacturers compete on volume throughput in consumer channels. The vendor base fragments across imaging system integrators, precision electronics fabricators, and cardiovascular device distributors extending into adjacent categories. Two dominant competitive moves reshape positioning: pharmacy channel bundling of multi-parameter diagnostic kiosks and direct-to-consumer subscription models bypassing retail margin structures.
Among Japanese and Korean precision electronics specialists, Omron Corporation, Tanita Corporation, and InBody Co., Ltd. occupy positions spanning consumer wellness through professional sports applications. These companies exemplify the impedance-analysis archetype that dominates unit volume through health club and home-user channels. German clinical instrumentation manufacturers including seca GmbH & Co. KG and Beurer GmbH represent contrasting positioning across diagnostic-grade and consumer-grade regulatory classifications. Hologic, Inc. anchors the premium imaging tier through DEXA technology relationships with US hospital networks.
| Leading Market Players |
|---|
| Omron Corporation |
| Tanita Corporation |
| InBody Co., Ltd. |
| Beurer GmbH |
| Hologic, Inc. |
| GE Healthcare |
| seca GmbH & Co. KG |
| COSMED Srl |
| Bodystat Ltd. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for DEXA X-ray tube assemblies concentrate pricing power with rare-earth magnet suppliers in China, while bioelectrical impedance scale manufacturers in Shenzhen compress margins through rapid inventory turns. This divergence between capital-intensive clinical imaging and high-volume consumer electronics shapes procurement economics across the Body Fat Measurement Market.
Pricing Analysis
The customization-premium spread between configured-to-order DEXA systems and standard impedance scales reaches multiples of ten, with hospital-grade imaging commanding per-unit transactional pricing while consumer devices follow subscription-plus-hardware models. Price differentiation rests on FDA 510(k) certification tier and after-sales service bundling for clinical installations. Cost compression in the home-user segment intensifies because Chinese e-commerce platforms aggregate demand and eliminate distributor markups. Health clubs exhibit moderate price sensitivity, prioritizing connectivity and EHR integration over absolute acquisition cost.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Hamburg for DEXA system components have tightened container availability on the Asia-Europe trade lane, compressing delivery windows for German clinical manufacturers. Supply concentrates in China for rare-earth magnets and PCB assemblies, Germany for precision sensors and calibration equipment, and Japan for electrode materials and signal processing chips. Raw material dependencies include neodymium for DEXA magnets, copper for impedance electrodes, and medical-grade plastics for housing assemblies. Single-source vulnerability in Chinese rare-earth exports poses structural risk. Distribution runs through hospital GPOs in the United States, pharmacy retail chains in Europe, and direct-to-consumer platforms in Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Body Fat Measurement Market represents an early-cycle expansion story, with fitness chain biometric screening programs creating infrastructure pull-through that precedes mass consumer adoption. Penetration remains below saturation thresholds across pharmacy retail and home health monitoring segments.
For Market Incumbents: Shield installed base relationships in hospital networks by accelerating CE marking pathways for multi-frequency impedance analyzers ahead of EU MDR enforcement tightening. Vertical integration into electrode manufacturing reduces exposure to copper price volatility and secures supply continuity for high-volume fitness channel contracts.
For New Entrants and Emerging Players: Differentiate on segmental analysis precision for athletic performance applications, where eight-point electrode configurations command premium positioning against whole-body measurement alternatives. Brazil's private health network expansion outside São Paulo and Rio presents the most penetrable geography for DEXA operators. A direct-to-consumer subscription model bypasses retail margin extraction and captures recurring revenue from home users.
For Investors and Strategic Acquirers: Long-term, this sits as a preventive-health infrastructure play because metabolic syndrome monitoring programs in Japan and post-acute care reimbursement expansion create durable demand for connected body composition tracking. Acquisition targets should emphasize impedance device manufacturers with existing pharmacy formulary relationships and field service infrastructure. The signal to watch is FDA guidance tightening on wellness-versus-diagnostic device classifications, which would accelerate consolidation toward certificate holders.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercialization timelines for novel optical sensing modalities in US hospital networks. |
| EU MDR Article 10 Compliance | Elevates clinical evidence standards that filter marginal competitors from diagnostic-class applications. |
| Hospital System Partnership | Secures procurement authority through GPO contracts and reimbursement relationships with Hologic. |
| Software Companion Development | Enables EHR interoperability for Epic and Cerner deployments in fitness chain biometric screening. |
| Reimbursement Strategy | Positions DEXA systems for metabolic syndrome monitoring in Japan's post-acute care programs. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, fitness chain operations directors, and GPO contracts managers, then refined against secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across technology segments and top-down macroeconomic triangulation anchored volume estimates.
Variance decomposition across technology type, application use case, end-user procurement authority, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included fitness chain biometric screening deployment schedules, EU MDR certificate issuance timelines, and rare-earth magnet export quota adjustments.
Material uncertainties — reimbursement compression in US hospital networks, hydration variance degrading impedance accuracy, and ANVISA registration delays for Brazilian DEXA imports — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and supply chain continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
South America Respiratory Monitoring Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
Clinical Alarm Management Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Urine Monitoring Systems Market
Patient Monitoring
Europe Fetal and Neonatal Monitoring Market
Patient Monitoring
Healthcare Biosensors IoT Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
North America Body Temperature Monitoring Market
Patient Monitoring
Canada Patient Monitoring Devices Market
Patient Monitoring
Wireless Patient Monitoring Market