
 North America Remote Patient Monitoring Systems Market | 2026-2036
North America Remote Patient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Remote Patient Monitoring Systems Market Analytics
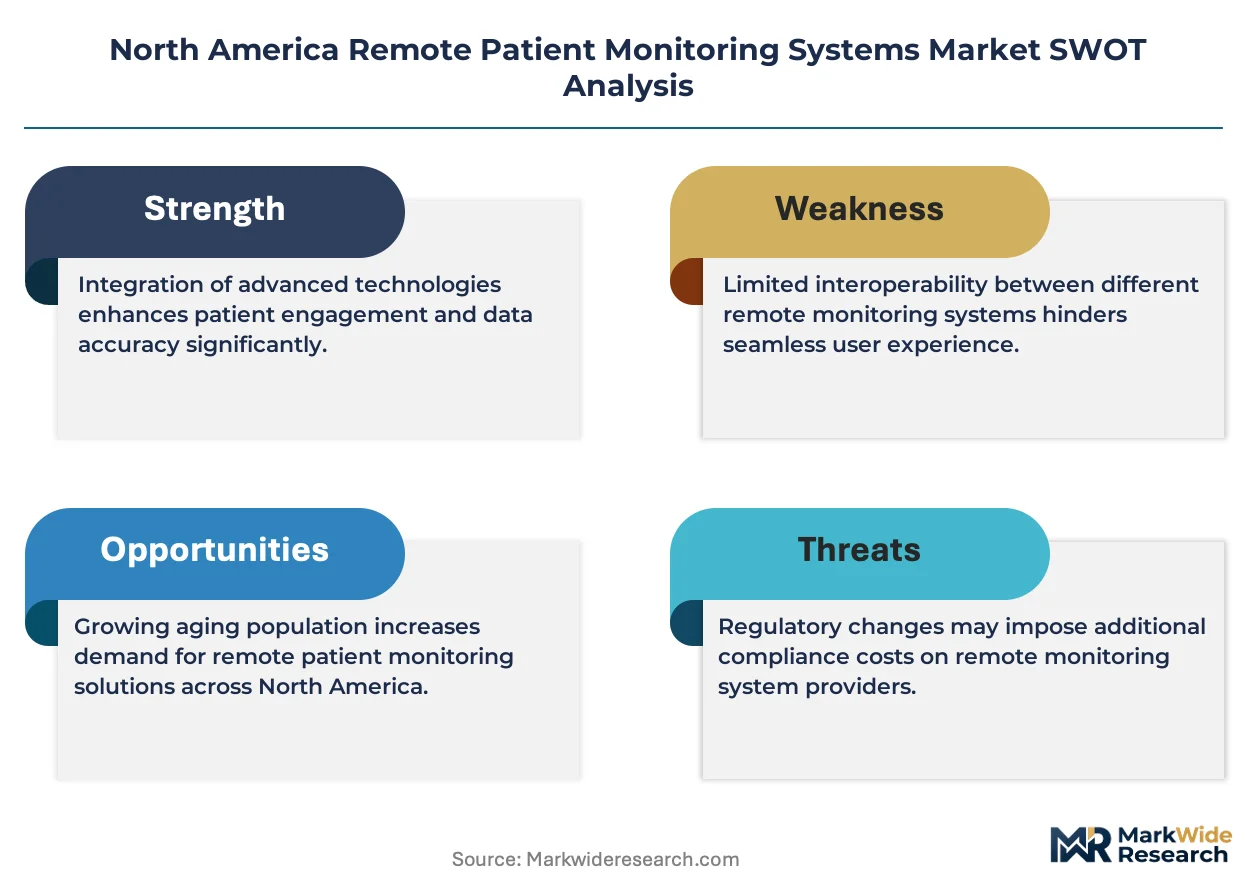
The gap between premium sensor-integrated platforms and basic vital-sign monitors is broadening. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor the premium tier with continuous glucose monitoring and automated data relay. Dexcom competes through tight integration with insulin delivery systems and real-time analytics. Medtronic differentiates via its deep cardiac rhythm portfolio and hospital system partnerships.
Remote patient monitoring systems encompass wearable biosensors, in-home diagnostic peripherals, cloud-based data aggregation software, and patient-facing mobile interfaces that transmit physiological data to clinical decision-makers for asynchronous care management. These systems typically operate through Bluetooth Low Energy pairing to hub devices, with cloud architectures enabling FDA 21 CFR Part 11-compliant audit trails for remote therapeutic monitoring billing. Wearable devices currently lead hardware revenue, while software solutions capture expanding margin pools through recurring SaaS licensing. Cellular-connected in-home monitors represent the fastest-growing technology segment as rural health clinics seek reliable connectivity beyond Wi-Fi coverage gaps.
FDA governs device clearance and Software as a Medical Device validation, while CMS shapes reimbursement through remote therapeutic monitoring codes and chronic care management fee schedules. The Office for Civil Rights enforces HIPAA security rule compliance for cloud data architectures, creating compliance costs that favor scaled platform vendors over point-solution entrants. Stakeholders must monitor CMS reimbursement rate adjustments and state-level telehealth parity legislation to calibrate channel investment between health system direct sales and payer-sponsored population health programs.
Market Dynamics
CMS reimbursement expansion for remote therapeutic monitoring codes is restructuring provider economics, shifting capital allocation from acute facility investments toward distributed ambulatory monitoring infrastructure.
Growth Catalysts
- Chronic Care Management Fee Schedules:CMS reimbursement tiers incentivize health systems to enroll high-risk patient populations in continuous monitoring programs, expanding device deployment volumes.
- Bluetooth Low Energy Hub Architectures:Wearable biosensors paired to cellular-connected home hubs enable reliable data transmission in rural coverage gaps, opening underserved geographies.
- Integrated Delivery Network Consolidation:California and Texas-based IDNs are standardizing RPM procurement across multi-hospital footprints, creating volume commitments that accelerate vendor scale.
Market Restraints
- HIPAA Security Rule Compliance Burden:Cloud data architecture audit requirements impose fixed costs that disadvantage point-solution entrants against scaled platform vendors.
- Semiconductor Component Concentration:Biosensor microcontrollers and BLE modules face supply bottlenecks from concentrated Asian foundry capacity, creating lead time volatility.
- Wi-Fi Coverage Reliability Constraints:Rural health clinic deployments remain constrained by broadband infrastructure gaps, forcing costlier cellular fallback architectures.
Strategic Opportunities
- Mexico Nearshoring Expansion:Assembly and final device configuration shifting to Baja California and Chihuahua reduces logistics costs for US Southwest distribution.
- Behavioral Health Integration:Mood disorder and medication adherence monitoring represents underpenetrated application white space with distinct reimbursement pathways.
- State Telehealth Parity Legislation:Texas and Florida mandate commercial payer reimbursement equivalence, reducing patient cost barriers and expanding addressable populations.
Industry Challenges
- FDA 21 CFR Part 11 Validation Timelines:Software as a Medical Device audit trail requirements extend product development cycles and compress launch windows.
- Clinical Workflow Integration Complexity:EHR interoperability with Epic and Cerner systems demands specialized health IT talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Remote Patient Monitoring Systems Market |
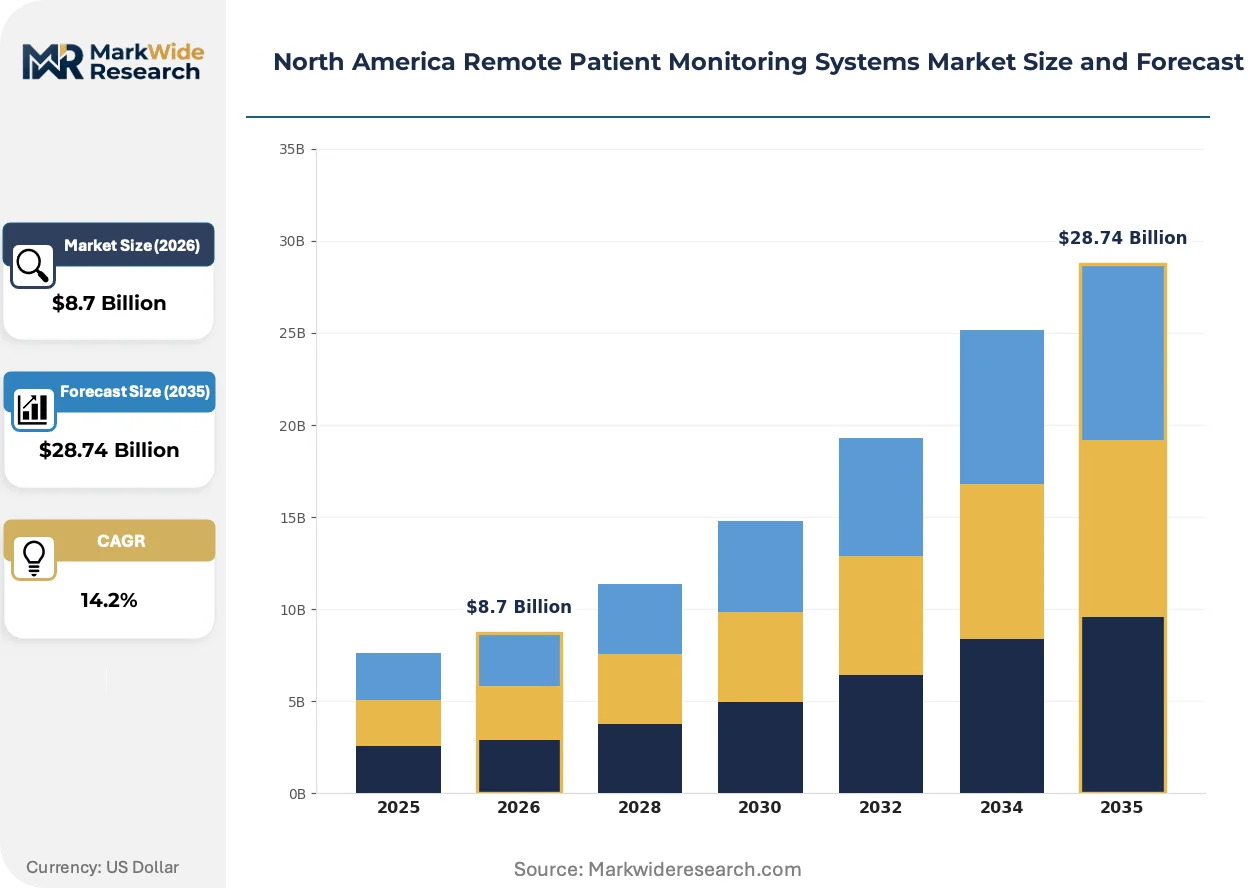
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, In-home Monitors, Software Solutions, Mobile Applications Technology: Bluetooth, Wi-Fi, Cellular, Satellite End User: Healthcare Providers, Patients, Family Caregivers, Telehealth Services Application: Chronic Disease Management, Post-operative Care, Emergency Monitoring, Preventive Health |
| Companies Covered | Abbott Laboratories, Medtronic, Dexcom, Koninklijke Philips N.V., Boston Scientific, GE Healthcare, Baxter International, BIOTRONIK SE & Co. KG, OMRON Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Remote Patient Monitoring Systems Market Evolving Landscape
Edge computing architectures and AI-enabled triage algorithms are compressing the latency between physiological anomaly detection and clinical intervention, redefining care coordination workflows.
Continuous glucose monitoring platforms with automated insulin dosing integration are decentralizing diabetes management from endocrinology clinics toward primary care and patient self-direction. Federally qualified health centers in Texas are deploying these systems for Medicaid populations. The shift is compressing specialist referral volumes while elevating primary care reimbursement capture.
FDA's streamlined Software as a Medical Device pre-certification pathway is accelerating algorithm-based diagnostic tool deployment. Predicate device reliance is diminishing for AI-augmented arrhythmia detection. Cardiac monitoring vendors are reorienting R&D toward iterative software updates rather than hardware generation cycles.
Subscription-based device-as-a-service models are displacing capital purchase arrangements among mid-size physician practices. Third-party financing entities assume hardware depreciation risk while capturing recurring SaaS margins. This restructuring is most visible in Arizona and Colorado independent practice associations seeking to preserve liquidity for EHR modernization.
North America Remote Patient Monitoring Systems Market Segmentation
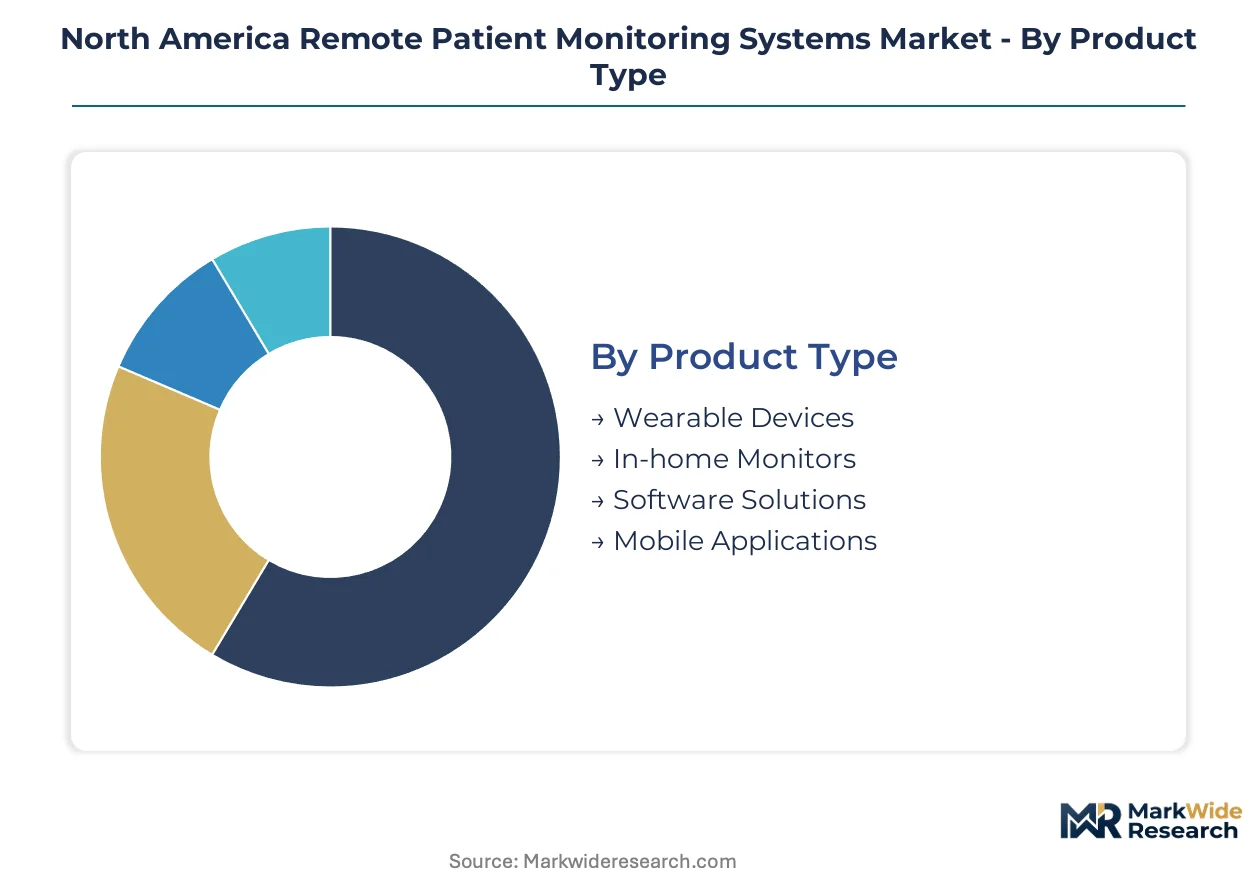
Segmentation in remote patient monitoring reveals how FDA clearance pathways and CMS reimbursement codes differentially shape vendor economics across hardware and software categories. Product architecture choices directly determine which regulatory frameworks apply and which billing codes providers can leverage.
Product Type:
Wearable devices carry the heaviest FDA 510(k) burden for biosensor accuracy validation, while software solutions face streamlined SaMD pre-certification with lighter clinical trial requirements.
- Wearable Devices:Continuous glucose monitors and cardiac biosensors incorporate microelectromechanical accelerometers and photoplethysmography sensors. Texas and California IDNs are standardizing procurement across multi-hospital footprints, driving volume commitments for vendors with established FDA predicates.
- In-home Monitors:Cellular-connected hub devices pair with peripheral diagnostics for blood pressure, pulse oximetry, and weight measurement. Rural health clinics in Arizona and New Mexico deploy these where Wi-Fi coverage fails, though semiconductor lead times from Asian foundries create supply volatility.
- Software Solutions:Cloud aggregation platforms with FDA 21 CFR Part 11 audit trails capture recurring SaaS margins through RTM billing integration.
- Mobile Applications:Patient-facing interfaces for data visualization and medication reminders face lighter regulatory scrutiny but demand HIPAA Security Rule compliance for cloud architectures.
Wearable devices sit at the top of the volume ranking, with in-home monitors climbing the fastest as rural connectivity gaps force cellular fallback architectures.
Technology:
Connectivity choice determines deployment feasibility across the urban-rural divide and shapes total cost of ownership for health system capital planning.
- Bluetooth:Low Energy 5.0 protocols enable wearable-to-hub pairing with minimal power draw. Abbott and Dexcom ecosystems standardize on this for glucose monitor smartphone integration, though range limitations confine use to patient-proximate relay devices.
- Cellular:LTE-M and NB-IoT modules eliminate Wi-Fi dependency for in-home monitors. Federally qualified health centers in Texas deploy these for Medicaid populations where broadband infrastructure remains underdeveloped.
- Wi-Fi:Higher bandwidth supports video-enabled telehealth encounters but fails in rural coverage gaps, restricting deployment to urban and suburban markets.
- Satellite:Emerging connectivity for extreme rural and tribal health applications carries premium hardware costs and latency constraints that limit commercial viability.
Bluetooth anchors current installed base volumes, while cellular is gaining share fastest as reimbursement expansion reaches underserved geographies.
End User:
Procurement authority and billing code eligibility fragment across stakeholder types with divergent technical sophistication and capital constraints.
- Healthcare Providers:Hospital systems and physician practices purchase integrated platforms with EHR connectivity to Epic and Cerner systems. CMS chronic care management fee schedules incentivize enrollment of high-risk populations, expanding device deployment volumes.
- Patients:Direct-to-consumer purchases concentrate in continuous glucose monitoring for Type 1 diabetes self-management, with subscription models displacing capital purchases.
- Family Caregivers:Informal care networks adopt simplified alert systems for aging-in-place scenarios, representing price-sensitive demand with limited technical support capacity.
- Telehealth Services:Virtual-first providers bundle RPM devices with care delivery, capturing RTM reimbursement through integrated billing workflows.
Healthcare providers command the largest procurement volumes, with telehealth services expanding most quickly as virtual care models mature.
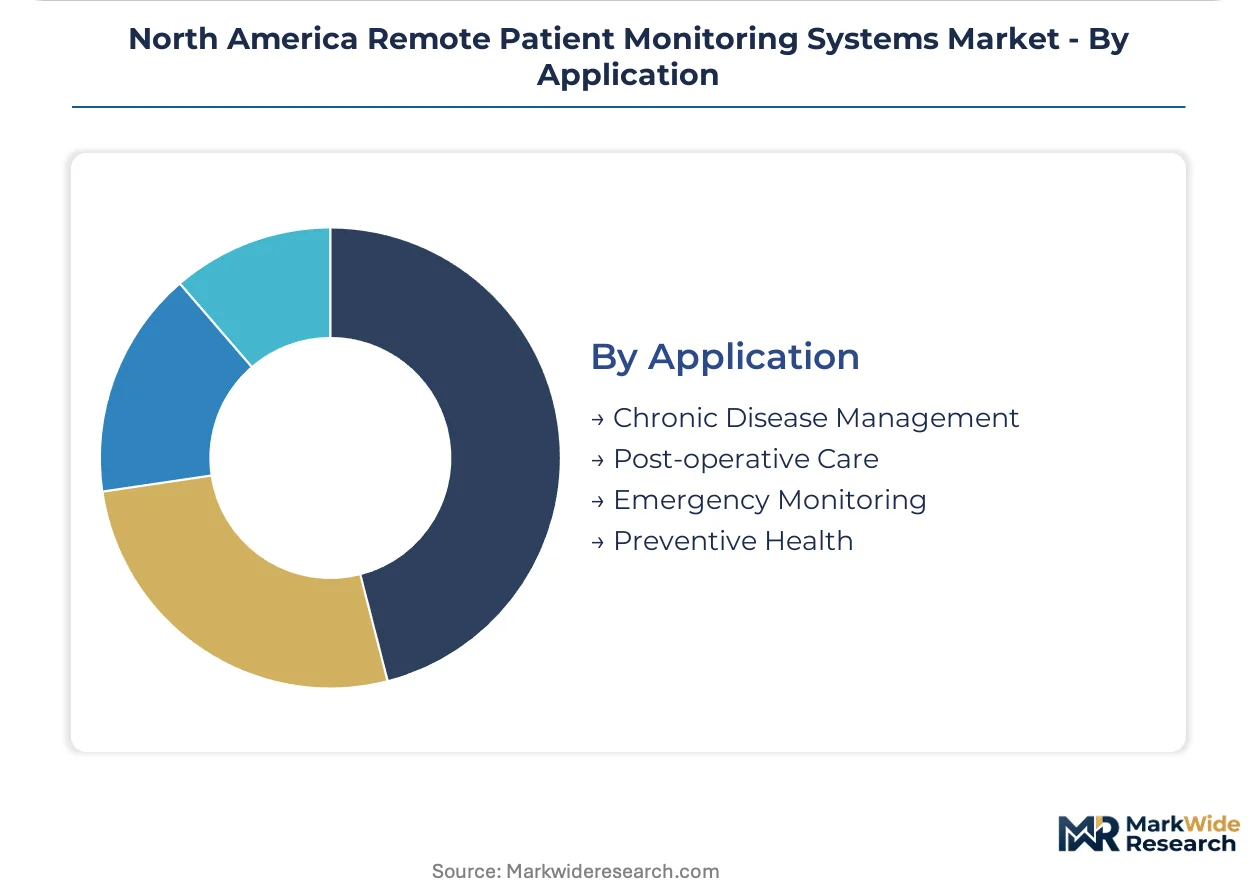
Application:
Clinical use case determines monitoring intensity, data throughput requirements, and which CMS billing codes apply for reimbursement capture.
- Chronic Disease Management:Continuous monitoring for diabetes, heart failure, and hypertension generates the highest device utilization rates. Texas and Florida Medicaid programs are scaling these programs for high-cost patient cohorts.
- Post-operative Care:Time-limited monitoring for surgical recovery reduces readmission penalties under CMS value-based programs. Orthopedic and cardiac surgery bundles increasingly include RPM discharge protocols.
- Emergency Monitoring:Fall detection and acute event alerting systems serve aging populations with limited caregiver presence.
- Preventive Health:Wellness-oriented monitoring for prediabetes and early cardiovascular risk remains underpenetrated with limited dedicated reimbursement pathways.
Chronic disease management leads by installed base, with post-operative care showing the steepest expansion trajectory as surgical bundles incorporate remote recovery protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the majority of device deployment volumes, while Canadian procurement patterns favor cost-conscious cellular-connected platforms for rural health networks. Mexico's nearshoring momentum is reshaping final assembly logistics for Southwest US distribution.
United States
California and Texas integrated delivery networks are standardizing RPM procurement across multi-hospital footprints, creating volume commitments that accelerate vendor scale. FDA 510(k) clearance pathways for Software as a Medical Device streamline product entry for algorithm-based diagnostic tools. The Greater Boston cluster anchors cardiac biosensor R&D concentration with deep hospital system partnerships.
Canada
Ontario and Quebec health authorities prioritize cellular-connected in-home monitors for remote Indigenous communities where broadband infrastructure remains underdeveloped. Health Canada regulates device clearance with requirements that parallel FDA frameworks but with distinct labeling standards. The Toronto-Waterloo corridor concentrates health IT talent pools for EHR interoperability development.
Mexico
Baja California and Chihuahua assembly operations are capturing final device configuration work previously routed through Asian logistics hubs. The country's national medical device regulator enforces labeling and post-market surveillance aligned with USMCA trade compliance. Mexico City Metro anchors distribution coordination for US Southwest health system supply chains.
North America Remote Patient Monitoring Systems Market Competitive Landscape
Top-tier vendors anchor the premium sensor-integrated tier, while mid-scale specialists compete on cellular connectivity and SaaS licensing economics. The market exhibits consolidated characteristics at the high end with Abbott, Medtronic, and Dexcom commanding hospital system procurement standards, while point-solution entrants face HIPAA compliance cost barriers. Two strategic archetypes dominate: integrated ecosystem builders leveraging FDA-cleared device portfolios, and software-centric platforms capturing recurring margins through RTM billing integration. Competitive moves concentrate on strategic partnerships with Epic and Cerner for EHR interoperability, plus geographic expansion through Mexico nearshoring to reduce logistics costs.
Among US-based diversified health technology conglomerates, Abbott Laboratories and Medtronic occupy positions as ecosystem anchors with deep cardiac rhythm and glucose monitoring portfolios. Dexcom exemplifies the tight-integration archetype through its positioning alongside insulin delivery systems. Koninklijke Philips N.V. represents the European-based diversified competitor with North American market presence. These three companies sit within the premium tier where FDA predicate device histories and hospital system relationships create defensive positioning against point-solution entrants.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Dexcom |
| Koninklijke Philips N.V. |
| Boston Scientific |
| GE Healthcare |
| Baxter International |
| BIOTRONIK SE & Co. KG |
| OMRON Healthcare |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in California and Texas concentrate procurement authority through multi-hospital standardization, locking in subscription-based device-as-a-service models that displace capital purchases among mid-size physician practices. This buyer concentration feeds pricing power toward scaled platform vendors while squeezing point-solution margins through volume commitment leverage.
Pricing Analysis
Bundled SaaS-plus-hardware subscriptions separate from unbundled per-device transactions across the market. Three-tier pricing structure across premium sensor-integrated, standard cellular-connected, and economy basic vital-sign tiers reflects FDA clearance depth and EHR interoperability certification. Cost compression in the economy tier is intensifying because semiconductor lead time volatility forces vendors to absorb inventory carrying costs. Family caregivers and rural federally qualified health centers exhibit highest price sensitivity, while hospital systems with CMS chronic care management capture show lowest sensitivity due to reimbursement pass-through.
Supply Chain Analysis
FDA 21 CFR Part 11 validation and HIPAA Security Rule certification gate supplier qualification, favoring incumbent platform vendors with established audit trail architectures. Biosensor microcontrollers and BLE modules draw from concentrated foundry capacity in Taiwan, South Korea, and China, creating single-source vulnerability for advanced node semiconductors. Tariff exposure on Chinese electronics components elevates landed costs for economy-tier device assemblers. Distribution runs through Mexico City Metro coordination hubs for Baja California and Chihuahua final configuration, reducing logistics costs for US Southwest health system delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where CMS remote therapeutic monitoring code expansion functions as the primary demand amplifier, restructuring provider capital allocation toward distributed ambulatory infrastructure.
For Market Incumbents: Deepen EHR interoperability moats through specialized Epic and Cerner integration talent acquisition, defending against software-centric platforms capturing RTM billing margins. Fortify hospital system partnership exclusivity clauses to block point-solution entrants from achieving scale. Prioritize backward integration into biosensor microcontroller sourcing to mitigate Taiwan foundry concentration risk.
For New Entrants and Emerging Players: The gap between premium Abbott-Dexcom ecosystems and economy vital-sign monitors creates white-space opportunity in behavioral health monitoring for mood disorder and medication adherence applications. Target Texas and Florida Medicaid populations where state telehealth parity legislation reduces patient cost barriers. Pursue device-as-a-service financing partnerships with third-party entities to bypass capital purchase friction among Arizona and Colorado independent practice associations.
For Investors and Strategic Acquirers: Hospital systems with captive GPO structures are the most active acquirer in this space, seeking software-centric platforms with RTM billing integration to complement hardware deployments. Five-to-ten year viability hinges on CMS reimbursement rate sustainability rather than technology differentiation alone. Acquisition target archetype: mid-scale SaaS platforms with FDA SaMD pre-certification and existing Epic connectivity. The signal to watch is state-level telehealth parity legislation momentum as inflection indicator for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Pre-Certification Pathway | Accelerates algorithm-based diagnostic deployment for cardiac monitoring vendors reorienting R&D toward software cycles. |
| Hospital System Partnership | California and Texas IDN standardization creates volume commitments that accelerate vendor scale through multi-hospital procurement. |
| Software Companion Development | Cloud aggregation platforms with 21 CFR Part 11 audit trails capture recurring SaaS margins through RTM billing integration. |
| Reimbursement Strategy | CMS chronic care management fee schedules incentivize enrollment of high-risk populations, expanding device deployment volumes. |
| Mexico Nearshoring Expansion | Baja California and Chihuahua assembly reduces logistics costs for US Southwest health system distribution coordination. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged hospital purchasing committees, biomedical engineers, GPO contracts managers, and telehealth platform operators across California, Texas, Ontario, and Quebec. Secondary sources include FDA 510(k) filings, Health Canada device clearance databases, CMS Medicare reimbursement data, and hospital procurement contract disclosures. Bottom-up device deployment estimates triangulate against top-down health system capital expenditure tracking.
Granularity-level modeling extends to product type, connectivity technology, end-user procurement authority, and clinical application intensity across the projection horizon. Segmentation dimensions include wearable versus in-home versus software-only architectures, Bluetooth versus cellular versus Wi-Fi connectivity, and chronic disease management versus post-operative versus emergency monitoring use cases. CAGRs derive from installed base growth rates adjusted for device replacement cycles and reimbursement code expansion trajectories. Forecast inputs incorporate semiconductor lead time volatility and state telehealth parity legislation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for satellite connectivity in extreme rural and tribal health applications would alter the outlook for cellular versus Wi-Fi deployment splits. Forecasts reflect assumptions regarding CMS reimbursement sustainability and FDA SaMD pathway efficiency. A model refresh is warranted upon material change in remote therapeutic monitoring code valuation or semiconductor supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
AI in Remote Patient Monitoring Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
Brain Monitoring Systems Market
Patient Monitoring
France Patient Monitoring Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Global Blood Pressure Monitoring Devices Market
Patient Monitoring
Mobile Heart Monitoring Market
Patient Monitoring
Middle-East and Africa Hemodynamic Monitoring Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Wearable Patient Monitor Market