
 Global IOT Sensors in Healthcare Market | 2026-2036
Global IOT Sensors in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global IOT Sensors in Healthcare Market Outlook
The EU AI Act is pivoting compliance costs upward for any connected sensor that processes patient biomarkers or diagnostic signals. Medtronic Plc leverages its vertically integrated manufacturing footprint to absorb these certification burdens internally. Abbott Laboratories anchors its competitive position through deep specialization in glucose monitoring ecosystems. Texas Instruments competes by controlling critical semiconductor supply for low-power biomedical sensor architectures.
IoT sensors in healthcare are compact transducers that convert physiological signals—temperature, pressure, motion, or proximity—into digital data streams for clinical decision systems, typically operating at power budgets below one milliwatt to enable wearable or implantable deployment. Temperature sensors and pressure sensors occupy the largest installed base across remote patient monitoring networks, while motion sensors represent the fastest-expanding category as fall-detection and rehabilitation tracking applications multiply. Bluetooth technology dominates current device pairings, though LoRaWAN is gaining structural share in hospital campus deployments where extended range and reduced gateway density lower total infrastructure cost.
FDA clearance pathways in the United States, CE marking under the EU MDR, and PMDA device reviews in Japan collectively determine which sensor platforms achieve commercial access in the highest-reimbursement markets. ISO 13485 quality management standards and IEC 60601 electrical safety requirements further constrain design choices for manufacturers seeking multi-regional approval. Stakeholders must monitor how interoperability mandates from ONC in the United States and the European Health Data Space initiative reshape data architecture requirements before committing to fixed sensor-platform investments.
Market Dynamics
Hospital procurement departments now mandate continuous glucose monitoring integration into electronic health records, forcing sensor manufacturers to prioritize interoperability certification over raw performance specifications.
Growth Catalysts
- Chronic Disease Management Expansion:Hospital systems in the United States, Germany, and Japan are deploying remote patient monitoring networks for diabetes and cardiovascular conditions, creating pull-through demand for multi-parameter sensing platforms.
- EU AI Act Compliance Deadlines:The European Union's artificial intelligence regulation is accelerating sensor platform upgrades as manufacturers race to certify diagnostic signal processing algorithms before enforcement phases begin.
- LoRaWAN Infrastructure Buildout:Hospital campuses are replacing Bluetooth gateway density with single LoRaWAN base stations, reducing total connectivity infrastructure cost by half while extending coverage to parking structures and remote clinics.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea control fabrication capacity for ultra-low-power biomedical microcontrollers, exposing sensor manufacturers to single-source risk during geopolitical disruptions.
- EU MDR Certification Timelines:European medical device regulation review periods now stretch 18-24 months for novel sensor modalities, freezing product launch schedules and consuming capital without revenue generation.
- Silver Electrode Cost Volatility:Electrochemical glucose sensors depend on silver-silver chloride reference electrodes, with metal price swings directly compressing gross margins on disposable test strip production.
Strategic Opportunities
- India Preventive Care Networks:The country's national health mission is subsidizing village-level diagnostic infrastructure, creating first-mover advantage for wearable vital sign monitors priced below 50 USD.
- Fall Detection in Japanese Elderly Care:METI funding for aging-in-place technologies is accelerating adoption of 9-axis inertial measurement units in home care settings previously served only by institutional monitoring.
- Continuous Blood Pressure Sensing:Photoplethysmography algorithms combined with MEMS pressure transducers are converging toward cuffless ambulatory hypertension management, opening reimbursement codes currently reserved for traditional sphygmomanometry.
Industry Challenges
- Embedded Firmware Security Certification:FDA premarket submissions now require documented software bill of materials and vulnerability management protocols, extending development cycles by 8-12 months for resource-constrained engineering teams.
- Legacy Hospital IT Integration:HL7 FHIR interoperability mandates from the Office of the National Coordinator force sensor platforms to support multiple health data exchange versions simultaneously, fragmenting R&D priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IOT Sensors in Healthcare Market |
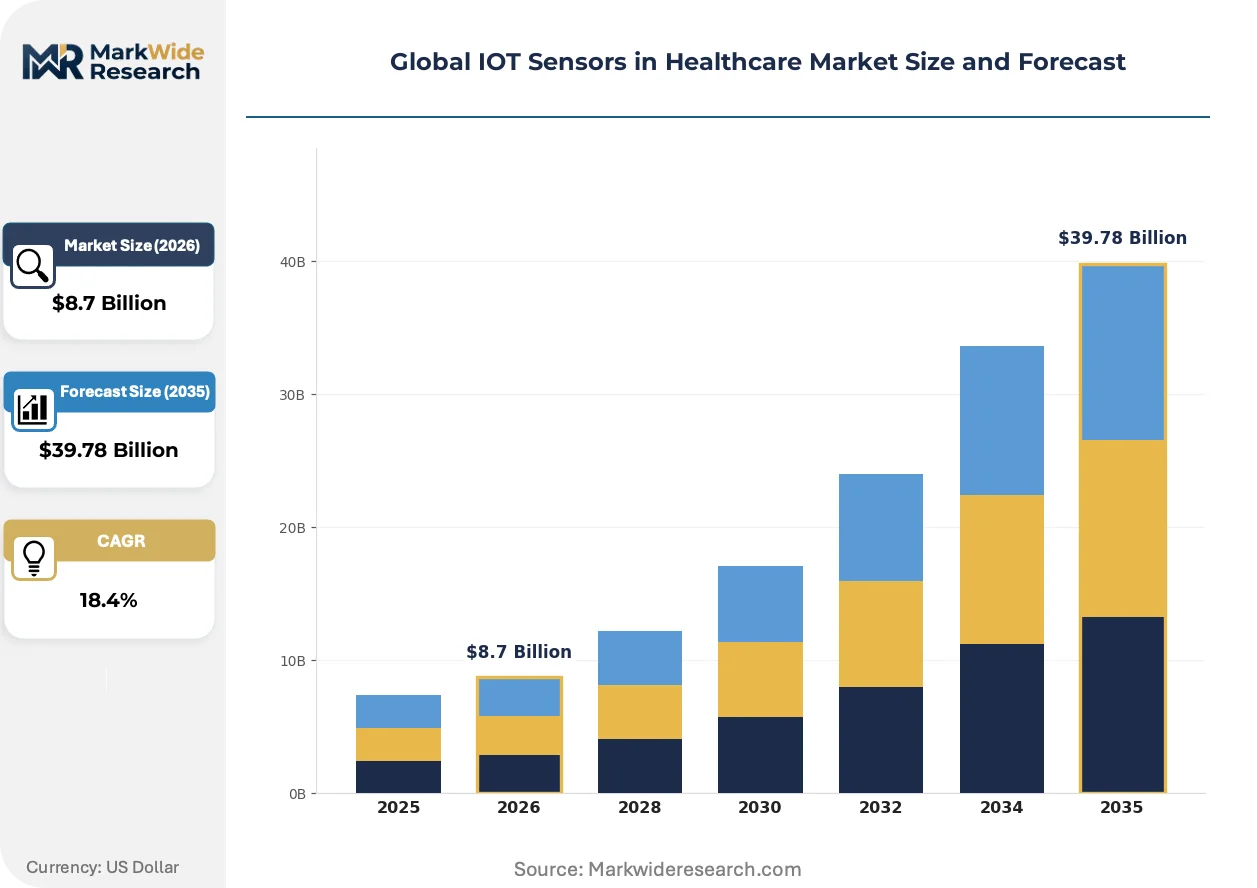
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Motion Sensors Application: Remote Patient Monitoring, Chronic Disease Management, Fitness Tracking, Medication Management Technology: Bluetooth, Wi-Fi, Zigbee, LoRaWAN End User: Hospitals, Homecare, Clinics, Research Institutions |
| Companies Covered | Medtronic Plc, GE Healthcare, Abbott Laboratories, Koninklijke Philips N.V., Boston Scientific Corporation, Honeywell International, Texas Instruments, STMicroelectronics, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IOT Sensors in Healthcare Market Strategic Shifts
Sensor fusion architectures are collapsing multiple physiological measurements into single semiconductor packages, while regulatory frameworks in major economies simultaneously tighten algorithmic transparency requirements.
Photoplethysmography is overtaking traditional pulse oximetry in consumer-grade wearables. Apple and Samsung smartwatches now embed multi-wavelength LED arrays capable of deriving heart rate variability, blood oxygen saturation, and peripheral perfusion indices from fingertip or wrist placement. Hospital-grade pulse oximeter manufacturers are responding by compressing price points and emphasizing clinical validation datasets that consumer devices cannot replicate.
The EU AI Act's risk classification system is restructuring how sensor manufacturers document diagnostic algorithm performance. Class IIa medical devices with embedded machine learning now require post-market monitoring plans and algorithm change control protocols. German notified bodies are processing these submissions first, creating a certification bottleneck that delays market access for competitors lacking established European quality management systems.
Hospital procurement departments are unbundling sensor hardware from data analytics subscriptions. Texas Medical Center and Mayo Clinic now issue separate RFPs for physical device supply and cloud-based clinical decision support, forcing vendors to compete on discrete value propositions rather than integrated platform pricing. This bifurcation is most visible in the United States, where group purchasing organizations negotiate device contracts while hospital IT departments retain analytics vendor selection authority.
Global IOT Sensors in Healthcare Market Segmentation
Sensor modality, connectivity protocol, and care setting collectively determine reimbursement eligibility, regulatory pathway, and procurement authority in healthcare IoT deployments. Manufacturers must align platform architecture with specific segment requirements to avoid costly redesign cycles during certification.
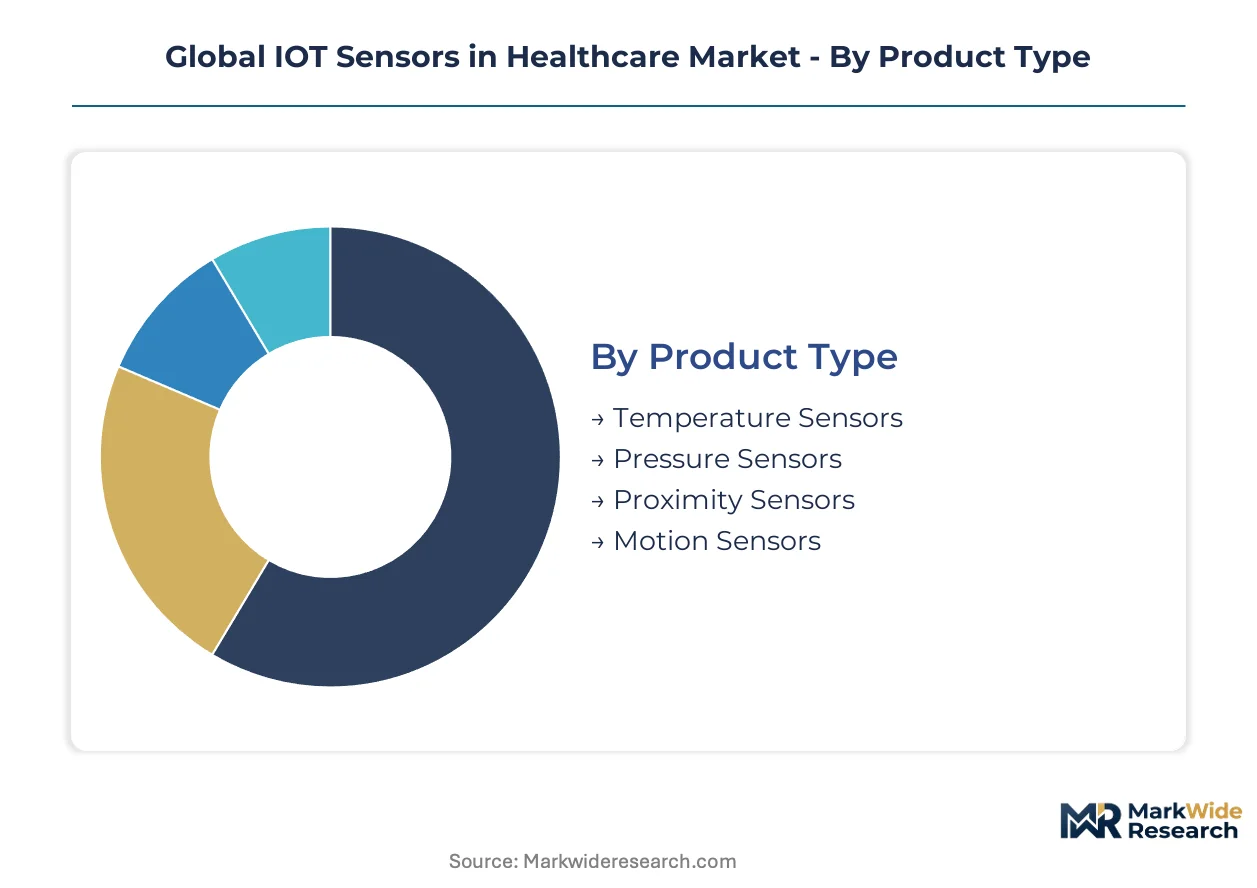
Product Type:
Temperature and pressure transduction dominate current semiconductor foundry output for biomedical applications, while motion sensing architectures are displacing legacy inertial platforms in fall-detection systems.
- Temperature Sensors:Thermistor and thermopile arrays measure core body temperature through skin-contact or tympanic placement. Hospital systems in Germany and Japan specify continuous temperature monitoring for post-surgical recovery wards, with FDA-cleared devices commanding premium reimbursement.
- Pressure Sensors:MEMS capacitive and piezoresistive elements track blood pressure, intracranial pressure, and respiratory mechanics. Texas Medical Center procurement mandates dual-source pressure sensor supply for ventilator fleets, creating volume concentration among qualified vendors.
- Proximity Sensors:Capacitive and infrared detection modules enable contactless medication dispensing and hand-hygiene compliance monitoring. These deploy primarily in hospital infection control programs.
- Motion Sensors:Accelerometer-gyroscope fusion enables gait analysis, fall detection, and sleep staging. METI-funded elderly care programs in Japan are accelerating 9-axis IMU deployment in home settings.
Mature deployment sits with temperature sensors in acute care monitoring. Newer deployment is concentrated in motion sensors for aging-in-place applications.
Application:
Clinical reimbursement codes and consumer willingness-to-pay create divergent margin structures across use cases, with chronic disease management capturing the steepest expansion trajectory.
- Remote Patient Monitoring:Multi-parameter telemetry streams vital signs to centralized nursing stations or cloud platforms. Mayo Clinic and Cleveland Clinic operate proprietary RPM networks requiring device-level HL7 FHIR certification.
- Chronic Disease Management:Glucose, blood pressure, and cardiac rhythm sensors integrate with care coordination platforms. Hospital systems in the United States now mandate EHR integration as a procurement prerequisite.
- Fitness Tracking:Consumer-grade wearables measure activity, sleep, and recovery metrics. These devices operate outside medical device regulations in most jurisdictions.
- Medication Management:Smart pill bottles and blister packs track dosing adherence through capacitive or mechanical sensors. Pharmacy benefit managers in the United States are piloting sensor-enabled adherence programs for high-cost specialty drugs.
Revenue concentration favors chronic disease management platforms with recurring data subscriptions. Emerging volume is shifting toward medication management as pharmaceutical manufacturers assume sensor costs for adherence programs.
Technology:
Power budget, range requirements, and gateway infrastructure economics determine connectivity selection, with hospital campuses reassessing Bluetooth density versus LoRaWAN coverage.
- Bluetooth:Low-energy protocols dominate wearable and bedside device pairings. Smartphone integration enables consumer-grade deployment without dedicated infrastructure.
- Wi-Fi:Higher throughput supports imaging-integrated sensors and firmware-over-the-air updates. Hospital IT departments prefer Wi-Fi for stationary devices within existing network coverage.
- Zigbee:Mesh networking extends coverage in multi-room installations without additional gateway hardware. Zigbee deploys in European hospital retrofits where Wi-Fi spectrum is congested.
- LoRaWAN:Sub-gigahertz transmission achieves kilometer-range coverage with single base stations. Hospital systems in Germany and the United States are replacing Bluetooth gateway density with LoRaWAN for campus-wide and remote clinic connectivity.
Installed base concentration remains with Bluetooth in consumer and bedside applications. Infrastructure investment is flowing toward LoRaWAN for enterprise-scale healthcare networks.
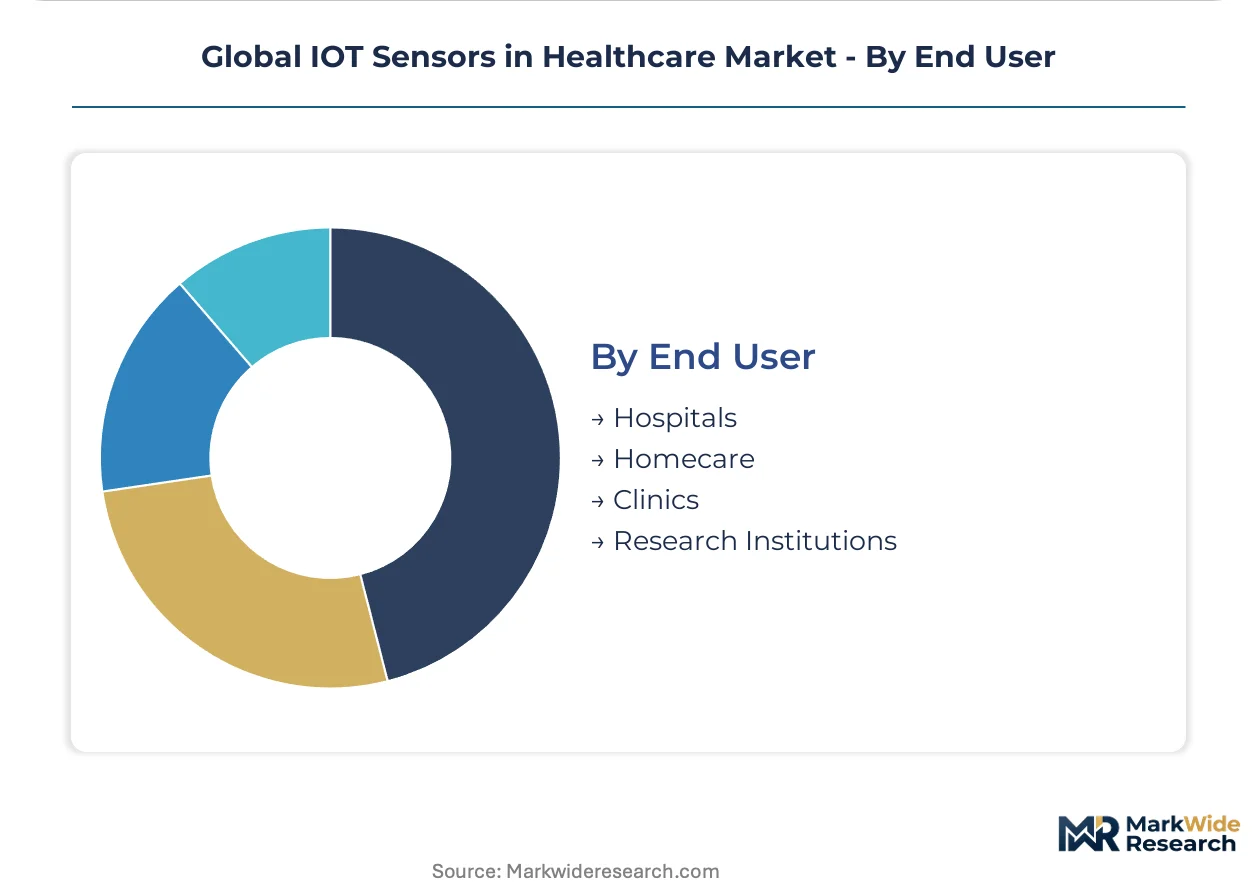
End User:
Procurement authority, technical integration capability, and patient acuity create distinct specification requirements across care settings.
- Hospitals:Acute care settings demand ISO 13485-certified devices with IEC 60601 electrical safety compliance. Group purchasing organizations negotiate sensor hardware contracts separately from analytics subscriptions.
- Homecare:Aging-in-place and post-acute recovery settings prioritize simplicity and cellular backhaul. Japanese METI subsidies and United States Medicare remote patient monitoring reimbursement codes are expanding addressable volume.
- Clinics:Ambulatory settings require portable, multi-patient devices with rapid sanitization protocols. Federally qualified health centers in the United States represent price-sensitive volume for basic vital sign monitors.
- Research Institutions:Academic medical centers deploy experimental sensor modalities for clinical trial endpoints. These users tolerate higher unit costs and shorter product lifecycles for novel biomarker access.
Certification investment concentrates in hospital-grade platforms. Volume expansion is accelerating in homecare as reimbursement frameworks mature for distributed monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina concentrates FDA-cleared sensor development alongside venture capital flows exceeding two billion dollars annually for connected health startups.
United States
Mayo Clinic and Cleveland Clinic operate proprietary remote patient monitoring networks requiring device-level HL7 FHIR certification. The FDA maintains accelerated breakthrough pathways for AI-enabled diagnostic sensors. Minneapolis anchors Medtronic's vertically integrated manufacturing campus for implantable cardiac sensors.
Germany
University hospital networks in Berlin and Munich specify continuous multi-parameter sensing for post-surgical recovery wards. The EU AI Act and MDR impose 18-24 month certification timelines for novel sensor modalities. Stuttgart hosts Bosch Sensortec's MEMS fabrication for pressure and motion transducers.
Japan
METI subsidizes 9-axis inertial measurement units for aging-in-place elderly care programs nationwide. The PMDA reviews device submissions alongside reimbursement code determinations from the Central Social Insurance Medical Council. Tokyo-Osaka corridor concentrates semiconductor packaging for ultra-low-power biomedical microcontrollers.
India
The National Health Mission subsidizes village-level diagnostic infrastructure priced below fifty dollars per wearable unit. CDSCO streamlined medical device rules in 2017, though state-level procurement variability persists. Bengaluru and Hyderabad host contract manufacturers assembling temperature and pulse oximetry sensors for export markets.
South Korea
Samsung's smartwatch division sources multi-wavelength photoplethysmography arrays from domestic LED foundries. The MFDS aligns with FDA breakthrough designation reciprocity for pre-certified sensors. Suwon and Pangyo technopolis clusters integrate sensor fusion with consumer electronics supply chains.
Global IOT Sensors in Healthcare Market Competitive Environment
United States producers anchor one tier; European and Asian specialists hold differentiated positions in component supply and system integration. The vendor base concentrates around vertically integrated medical device conglomerates, semiconductor foundries with healthcare verticals, and pure-play sensor specialists. Three archetypes dominate: diversified conglomerates absorbing regulatory burdens internally, semiconductor suppliers controlling critical chip architectures, and focused diagnostics platforms building ecosystem lock-in. Consolidation pressures intensify through hospital procurement unbundling of hardware from analytics subscriptions, while strategic partnerships proliferate around interoperability certification.
Among diversified medical technology conglomerates, Medtronic Plc and Abbott Laboratories exemplify archetypes of vertically integrated certification management and deep specialization in chronic disease monitoring ecosystems respectively. Texas Instruments occupies a position anchoring semiconductor supply for low-power biomedical architectures. These three entities represent distinct competitive vectors: integrated manufacturing scale, diagnostic platform depth, and critical component control.
| Leading Market Players |
|---|
| Medtronic Plc |
| GE Healthcare |
| Abbott Laboratories |
| Koninklijke Philips N.V. |
| Boston Scientific Corporation |
| Honeywell International |
| Texas Instruments |
| STMicroelectronics |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up sensor specialists now dominate mid-tier glucose monitoring supply, concentrating procurement leverage and enforcing strict margin discipline across contract manufacturing partners in Taiwan and Malaysia. This ownership structure compresses payment terms to 60 days while demanding volume commitments that lock in pricing stability for hospital group purchasing organizations.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to ISO 13485-certified temperature sensors needed within eight weeks, while spot inventory of uncertified components trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared devices with full traceability from CE-marked equivalents and unvalidated Asian imports. Cost compression in economy-tier pressure transducers is intensifying because silver electrode volatility and foundry allocation fees squeeze disposable strip margins. Federally qualified health centers in the United States exhibit highest price sensitivity, while German university hospital networks prioritize certification tier over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taichung and Hsinchu limit expansion of MEMS cleanroom capacity despite capital deployment, pushing lead times for biomedical microcontrollers toward 26 weeks. Taiwan, South Korea, and Japan anchor semiconductor fabrication for ultra-low-power sensor architectures, with raw material dependencies spanning silicon wafers, silver-silver chloride pastes, and rare-earth magnetic elements for motion sensing cores. Single-source vulnerability concentrates in TSMC's 40nm specialty node for implantable cardiac sensors. Distribution runs through Medtronic's captive logistics network for hospital direct delivery, while independent distributors serve clinic and homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement unbundling of hardware from analytics subscriptions is accelerating consolidation, forcing sub-scale sensor vendors to absorb certification costs or exit. Weaker players lacking vertically integrated manufacturing face margin compression from EU MDR review timelines and FDA software documentation requirements.
For Market Incumbents: Acquire cloud-based clinical decision support platforms to re-bundle analytics with hardware and defend against pure-play software entrants. Backward integration into MEMS foundry partnerships in Taiwan secures allocation priority during semiconductor supply shocks. Prioritize algorithm change control protocols ahead of EU AI Act enforcement phases. For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass GPO contracting barriers and accelerate pilot deployments with ambulatory surgery centers. Target medication management sensors for pharmaceutical-sponsored adherence programs, where drug manufacturers assume device costs. White-space opportunity concentrates in Indian village-level diagnostic infrastructure below fifty-dollar price points. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified mid-caps with existing FDA 510(k) portfolios in Research Triangle Park and Minneapolis corridors. Long-term viability hinges on reimbursement code capture for continuous monitoring modalities. Watch for PMDA reimbursement determinations from Japan's Central Social Insurance Medical Council as inflection signal for Asia-Pacific expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | German notified body prioritization accelerates EU AI Act compliance for algorithm-enabled sensors. |
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic proprietary RPM networks require device-level HL7 FHIR certification. |
| Software Companion Development | FDA premarket submissions now mandate documented software bill of materials extending development cycles. |
| Reimbursement Strategy | Medicare remote patient monitoring codes and METI elderly care subsidies determine addressable volume. |
| FDA Submission | Breakthrough pathway designation enables accelerated review for AI-enabled diagnostic signal processing. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR notified body guidance documents, and hospital GPO contract databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at sensor manufacturers. Secondary validation drew from CMS Medicare reimbursement data, PMDA device approval registers, and semiconductor foundry capacity disclosures. Bottom-up unit economics for sensor production and top-down healthcare IT spending estimates were triangulated to anchor market sizing.
Historical volume trajectories for glucose monitoring and pulse oximetry were cross-referenced against expert panel input on LoRaWAN infrastructure deployment timelines across German and United States hospital campuses. Segmentation modeling spanned sensor modality, connectivity protocol, care setting, and regional regulatory cluster. CAGRs were derived from fitted adoption curves for chronic disease management programs and reimbursement code expansion patterns. Industry-specific forecast inputs included METI funding allocations for aging-in-place technologies and EU AI Act implementation phase dates.
The model holds under stable reimbursement frameworks and continued semiconductor foundry allocation to biomedical nodes; deviation in Taiwan geopolitical stability or FDA software documentation requirement tightening would shift volume and value projections. Forecasts reflect documented assumptions on interoperability mandate timelines and hospital procurement unbundling velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Fetal and Neonatal Monitoring Market
Patient Monitoring
Sleep Tracking Devices Market
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Multi-Item Patient Monitor Market
Patient Monitoring
Europe Hemodynamic Monitoring Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
Asia-Pacific Respiratory Monitoring Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Urine Output Monitoring Systems Market
Patient Monitoring
Germany Blood Glucose Monitoring Market