
 Asia-Pacific Remote Patient Monitoring Systems Market | 2026-2036
Asia-Pacific Remote Patient Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Remote Patient Monitoring Systems Market Outlook
ISO 13485 certification is redrawing competitive boundaries for device manufacturers across the Asia-Pacific. GE Healthcare leverages its imaging heritage to bundle RPM with diagnostic workflows, while Nihon Kohden Corporation anchors its position through deep specialization in patient monitoring hardware for Japanese hospital networks. Mindray Medical International competes aggressively on manufacturing scale, dominating mid-tier hospital procurement across China and Southeast Asia.
Remote patient monitoring systems encompass wearable biosensors, telehealth platforms, and cloud-connected devices that transmit physiological data from patients to clinicians outside traditional care settings. These systems typically operate on Bluetooth Low Energy or cellular protocols, capturing metrics such as blood glucose, ECG rhythm, and pulse oximetry for real-time clinical decision support. Wearable Devices and Telehealth Platforms command the largest addressable bases, though Remote Sensors capture disproportionate margin pools where continuous data fidelity differentiates premium contracts. Homecare Services within the End User dimension represents the fastest-expanding channel as aging populations in Japan, South Korea, and Australia shift reimbursement toward domiciliary models.
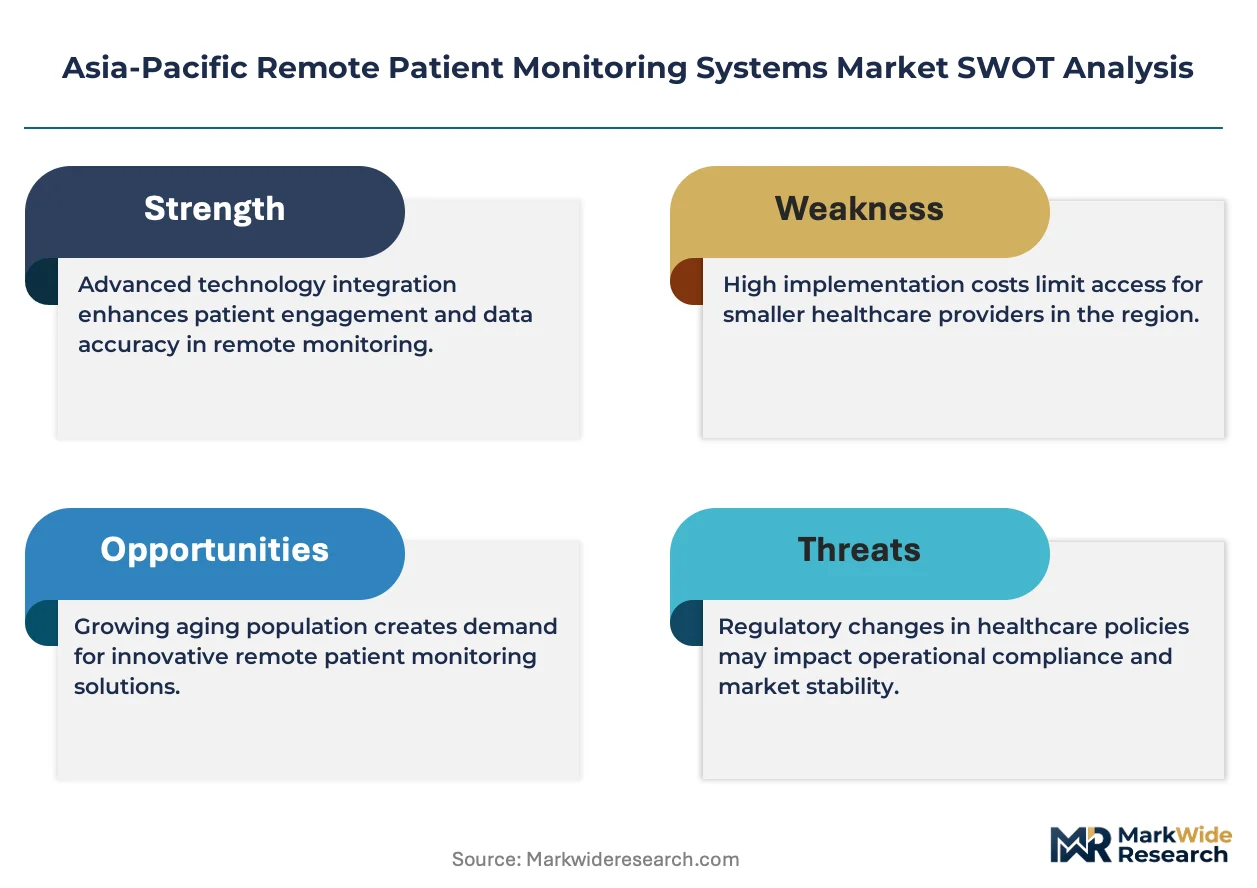
Japan's PMDA software-as-medical-device framework, Australia's TGA cybersecurity guidance for connected devices, and India's CDSCO Quality Management System Rules for medical devices collectively determine market access timelines and data governance obligations across the region. China's NMPA digital health pilot zones in Shanghai and Hangzhou create parallel regulatory tracks that reward localized clinical validation. Stakeholders must monitor divergent data localization requirements and reimbursement coding evolution as the primary variables shaping deployment economics.
Market Dynamics
Japan's PMDA software-as-medical-device framework is compressing certification timelines while simultaneously fragmenting vendor capabilities across the Asia-Pacific, forcing device manufacturers to rebuild quality management systems around continuous validation rather than discrete hardware approvals.
Growth Catalysts
- Japan's PMDA SaMD Guidance:The 2021 software-as-medical-device classification accelerates market entry for cloud-connected platforms, reducing pre-market review periods for algorithm-driven monitoring tools.
- Australia's Aged Care Reforms:Federal domiciliary care subsidies redirect hospital-at-home funding toward RPM-enabled discharge protocols, expanding addressable patient populations beyond institutional settings.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable continuous glucose and cardiac monitoring through disposable patch formats previously constrained by battery economics.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea fabs control 73% of medical-grade sensor chip production, exposing device manufacturers to foundry allocation volatility and 26-week lead times.
- China's NMPA data localization:Cross-border cloud transmission restrictions force redundant infrastructure deployment, inflating per-device connectivity costs by 40-60% for multinational platforms.
- Clinical validation gaps:Skin-tone bias in pulse oximetry algorithms limits FDA-equivalent clearance for diverse Asia-Pacific populations, constraining wearable adoption in melanin-rich demographic segments.
Strategic Opportunities
- India's CDSCO PLI scheme:Production-linked incentives for medical device manufacturing attract contract manufacturers to Hyderabad and Bengaluru clusters, reducing landed costs for ASEAN distribution.
- AI-ECG pattern recognition:Machine learning integration with Holter monitors enables arrhythmia detection without cardiologist overread, opening rural and tier-3 hospital segments previously underserved by specialist density.
- Pharmacy channel expansion:Watsons and Guardian retail networks in Singapore and Malaysia pilot RPM device dispensing with reimbursement coding, bypassing traditional hospital procurement cycles.
Industry Challenges
- ISO 13485 auditor scarcity:Notified body capacity constraints in Australia and Japan extend quality management system certification timelines to 14-18 months, delaying product launches.
- Interoperability fragmentation:HL7 FHIR adoption varies across China's tier-one hospital networks, forcing device vendors to maintain multiple integration stacks for provincial health information exchanges.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity studies face 6-month queues at accredited Asia-Pacific laboratories, compressing product development schedules for wearable adhesives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Remote Patient Monitoring Systems Market |
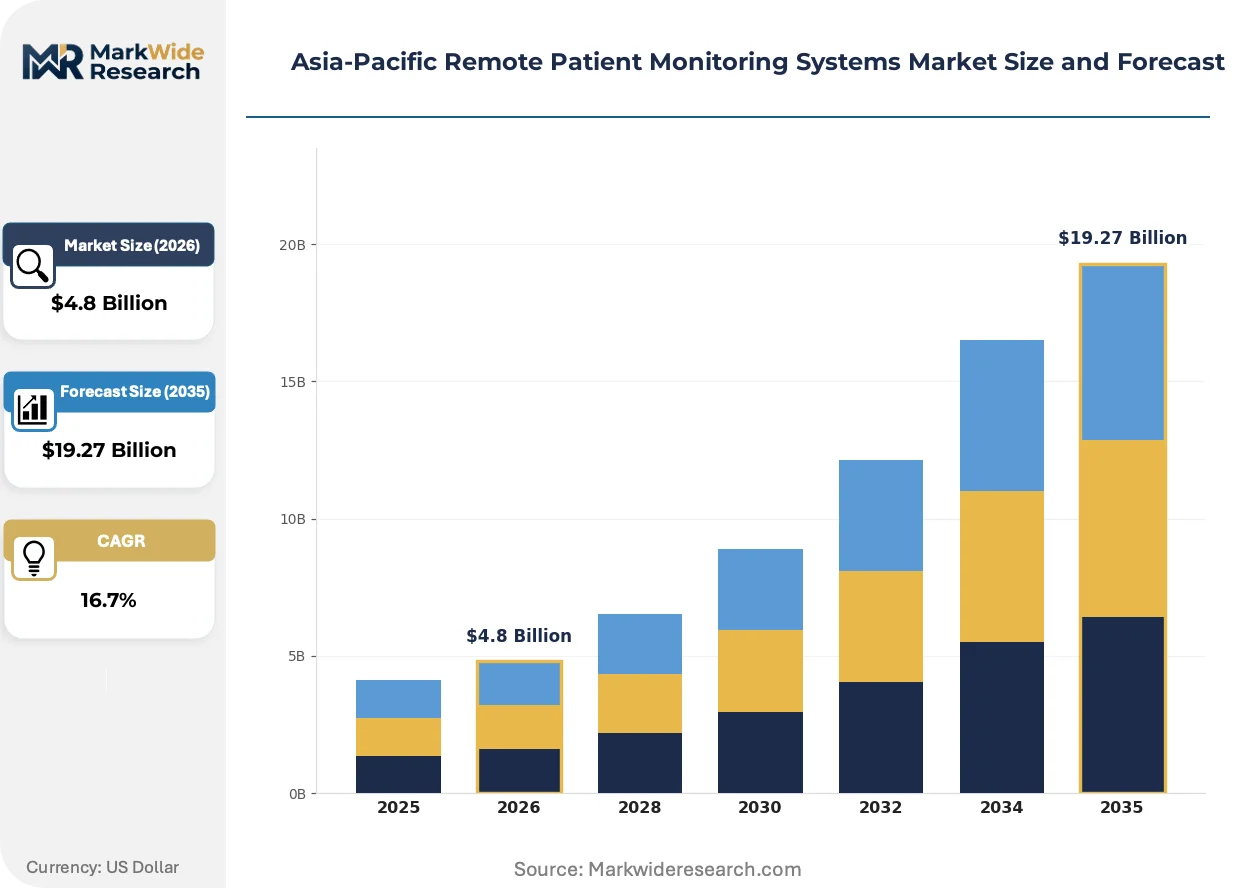
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wearable Devices, Telehealth Platforms, Mobile Health Apps, Remote Sensors End User: Healthcare Providers, Patients, Homecare Services, Clinical Researchers Delivery Mode: Cloud-Based, On-Premise, Hybrid, Device-Connected Application: Chronic Disease Management, Elderly Care, Post-Operative Monitoring, Preventive Healthcare |
| Companies Covered | GE Healthcare, Omron Healthcare, Medtronic PLC, Boston Scientific Corporation, Abbott Laboratories, Koninklijke Philips NV, Nihon Kohden Corporation, Mindray Medical International, AMD Global Telemedicine, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Remote Patient Monitoring Systems Market Strategic Shifts
Edge computing architectures and federated learning protocols are redistributing data processing from centralized clouds toward bedside and wearable devices, altering computational load distribution and cybersecurity exposure across the Asia-Pacific RPM ecosystem.
Continuous glucose monitoring patch technology is fragmenting competitive positioning in diabetes management. Japanese endocrinology clinics adopt factory-calibrated sensors eliminating fingerstick calibration, compressing the traditional blood glucose meter replacement cycle from 24 months to 12 months. This sensor format is fragmenting revenue concentration away from incumbent test strip manufacturers toward disposable electronics specialists.
India's CDSCO Quality Management System Rules harmonize with MDR technical documentation standards, enabling dual-market certification strategies for manufacturers targeting both domestic and European export channels. The regulation compresses regulatory consulting costs for mid-cap device developers. Cardiac implantable electronic device manufacturers in Bengaluru and Pune restructure quality teams to maintain single audit readiness.
Hospital procurement committees in China's tier-one cities unbundle RPM hardware from software subscriptions, reversing bundled SaaS pricing that dominated 2019-2023 contracting. Provincial centralized procurement platforms in Guangdong and Jiangsu publish discrete price ceilings for pulse oximetry and ECG wearables. Device vendors respond with stripped hardware SKIs and separately metered cloud connectivity tiers.
Asia-Pacific Remote Patient Monitoring Systems Market Segmentation
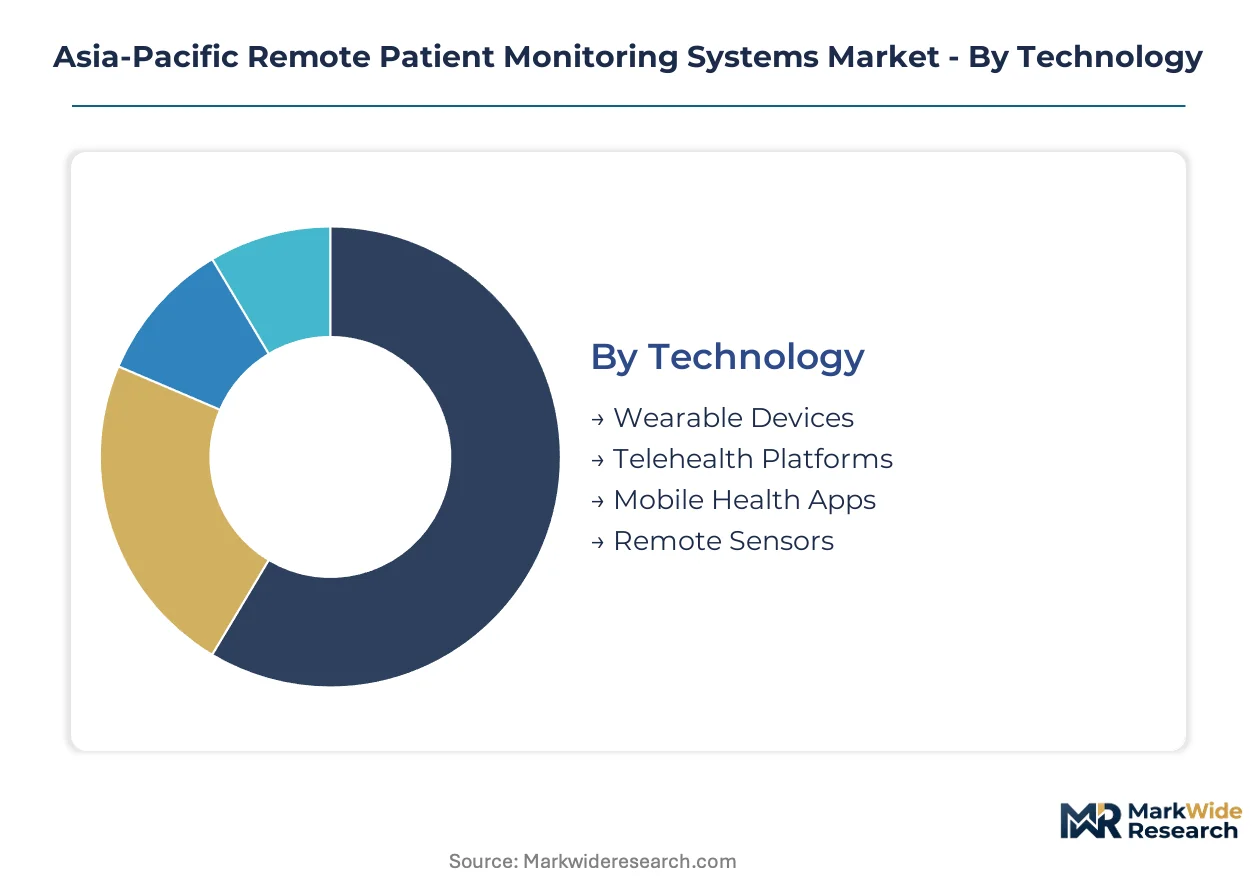
Technology choices in Asia-Pacific RPM systems determine regulatory pathways and reimbursement eligibility. Device manufacturers align form factors with Japan's PMDA software-as-medical-device tiers and China's NMPA digital health pilot requirements to secure market access.
Technology:
Japan's PMDA SaMD framework creates divergent certification burdens across hardware-intensive versus algorithm-driven formats, compressing timelines for cloud-native platforms while extending validation cycles for multi-sensor wearables.
- Wearable Devices:Biosensor patches and wrist-worn monitors capture continuous glucose, ECG, and pulse oximetry via Bluetooth Low Energy 5.3 protocols. Australia's aged care subsidies concentrate procurement in disposable patch formats for domiciliary cardiac monitoring, though skin-tone algorithm bias constrains clearance for melanin-rich populations.
- Telehealth Platforms:Cloud-connected software aggregates multi-device data streams for clinician dashboards and automated alert triage. China's NMPA data localization mandates force redundant infrastructure deployment, inflating per-patient connectivity costs for multinational platforms operating across tier-one hospital networks.
- Mobile Health Apps:Smartphone-native symptom tracking and medication adherence tools leverage existing device penetration.
- Remote Sensors:Bedside and implantable devices transmit physiological data without patient-worn interfaces, dominating ICU step-down and post-surgical recovery settings in Southeast Asian hospital networks.
Wearable Devices handles the majority of throughput; Telehealth Platforms is the fastest mover on share.
End User:
Reimbursement coding evolution redirects procurement authority from hospital supply chains toward federal domiciliary programs and retail pharmacy networks.
- Homecare Services:Federal subsidies in Australia and Japan's long-term care insurance system fund RPM-enabled hospital-at-home discharge protocols. Singapore's Ministry of Health pilots direct-to-patient leasing models for chronic disease management, bypassing traditional institutional procurement.
- Healthcare Providers:Tier-one hospitals in Shanghai and Hangzhou unbundle hardware from software subscriptions under provincial centralized procurement platforms, reversing bundled SaaS pricing that dominated contracting cycles.
- Patients:Direct-pay segments concentrate in India's metro diabetes clinics and South Korea's wellness-focused consumer electronics retail.
- Clinical Researchers:Academic medical centers deploy RPM for decentralized clinical trials, leveraging India's CDSCO Quality Management System Rules harmonization with MDR standards for dual-market device sourcing.
Healthcare Providers retains the dominant procurement volume; Homecare Services climbs fastest as reimbursement shifts toward domiciliary models.
Delivery Mode:
Data sovereignty requirements fragment cloud architecture strategies across national borders, elevating hybrid deployments that balance latency-sensitive analytics with localized storage compliance.
- Cloud-Based:Centralized data lakes enable AI-ECG pattern recognition and population health analytics. China's cross-border transmission restrictions and Australia's TGA cybersecurity guidance impose divergent encryption and access control obligations.
- Hybrid:Edge computing architectures process arrhythmia detection at the bedside while archiving longitudinal records in sovereign clouds. This architecture addresses China's NMPA pilot zone requirements for localized clinical validation data.
- On-Premise:Air-gapped deployments satisfy defense and correctional health security protocols in Australia and Japan.
- Device-Connected:Direct cellular or Bluetooth transmission to clinician dashboards without intermediate cloud storage, prevalent in rural India where connectivity infrastructure remains uneven.
Cloud-Based carries the largest installed base; Hybrid gains share fastest on data localization compliance.
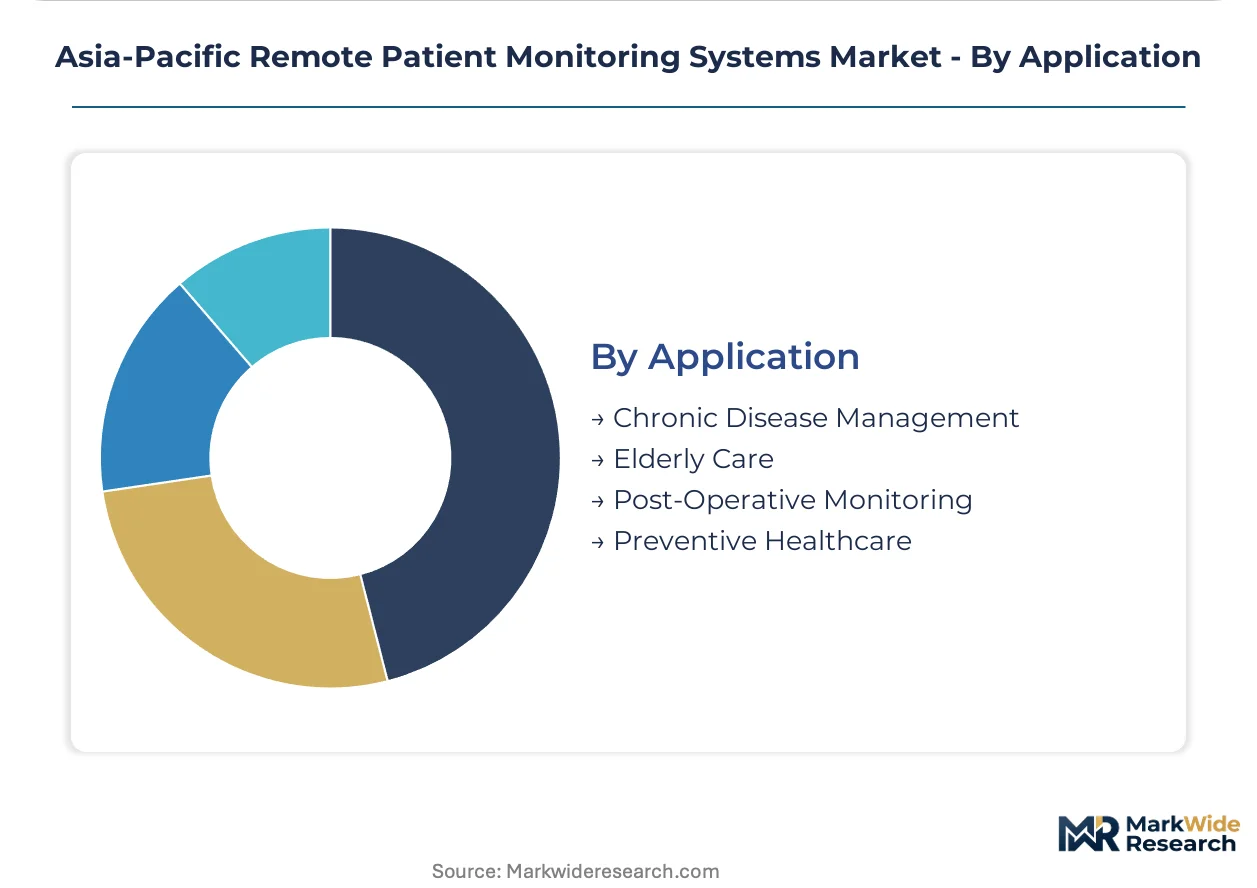
Application:
Demographic aging and diabetes prevalence reshape addressable populations across chronic versus acute monitoring use cases.
- Chronic Disease Management:Continuous glucose monitoring patches fragment competitive positioning in diabetes care. Japanese endocrinology clinics adopt factory-calibrated sensors eliminating fingerstick calibration, compressing replacement cycles for traditional blood glucose meters.
- Elderly Care:Fall detection and medication adherence monitoring align with Australia's federal domiciliary care reforms and Japan's super-aged society infrastructure investments. RPM deployment concentrates in Melbourne's aged care networks and Tokyo's community-based integrated care systems.
- Post-Operative Monitoring:Southeast Asian hospital networks expand RPM for cardiac and orthopedic recovery, reducing readmission penalties under evolving reimbursement schemes.
- Preventive Healthcare:Wellness-oriented vital signs monitoring targets pre-diabetic populations in South Korea's national health screening programs.
Chronic Disease Management commands the deepest revenue pools; Elderly Care expands most quickly on demographic and policy alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal domiciliary care subsidies across Australia and Japan redirect procurement authority toward hospital-at-home discharge protocols, expanding addressable patient populations beyond institutional settings. CDSCO's PLI scheme and PMDA's SaMD framework compress certification timelines for device manufacturers targeting multi-market deployment.
China
NMPA digital health pilot zones in Shanghai and Hangzhou reward localized clinical validation for cloud-connected platforms. Cross-border data transmission restrictions force redundant infrastructure deployment, inflating per-device connectivity costs for multinational vendors operating across tier-one hospital networks. Guangdong and Jiangsu provincial procurement platforms unbundle hardware from software subscriptions.
Japan
Super-aged society infrastructure investments concentrate RPM deployment in Tokyo's community-based integrated care systems. PMDA's 2021 software-as-medical-device classification accelerates market entry for algorithm-driven monitoring tools. Osaka's medical device clusters specialize in patient monitoring hardware for domestic hospital networks.
India
Metro diabetes clinics drive direct-pay segments for continuous glucose monitoring while Hyderabad and Bengaluru clusters attract contract manufacturers through CDSCO PLI incentives. Quality Management System Rules harmonization with MDR standards enables dual-market certification strategies for European export channels. Pune cardiac implantable device manufacturers restructure quality teams for single audit readiness.
Australia
Federal aged care reforms redirect hospital-at-home funding toward RPM-enabled discharge protocols, expanding procurement in Melbourne's aged care networks. TGA cybersecurity guidance for connected devices imposes encryption and access control obligations divergent from regional counterparts. Sydney-based telehealth platforms navigate data sovereignty requirements through hybrid cloud architectures.
South Korea
National health screening programs deploy wellness-oriented vital signs monitoring for pre-diabetic populations. MFDS regulatory alignment with international standards accelerates clearance timelines for wearable biosensors. Seoul's consumer electronics retail channels pilot direct-to-patient leasing models for chronic disease management.
Asia-Pacific Remote Patient Monitoring Systems Market Competitive Environment
Player mix skews toward diversified healthcare conglomerates with imaging and diagnostic heritage, hardware specialists with deep hospital network relationships, and scale-driven manufacturers dominating mid-tier procurement. Strategic archetypes include bundled solution providers leveraging cross-selling workflows, component-focused specialists capturing premium margins through continuous data fidelity, and contract manufacturers exploiting production-linked incentives for ASEAN distribution. Competitive moves center on unbundled hardware-software pricing to satisfy provincial procurement platforms and edge computing architectures to satisfy data localization mandates.
Among diversified healthcare conglomerates, GE Healthcare represents the bundled solution archetype leveraging diagnostic workflow integration, while Koninklijke Philips NV occupies a comparable position across hospital system relationships. Nihon Kohden Corporation exemplifies the hardware specialist archetype through deep specialization in patient monitoring equipment for Japanese institutional networks. Mindray Medical International anchors the scale-driven manufacturer tier, competing aggressively on production volume for mid-tier hospital procurement across China and Southeast Asia.
| Leading Market Players |
|---|
| GE Healthcare |
| Omron Healthcare |
| Medtronic PLC |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Koninklijke Philips NV |
| Nihon Kohden Corporation |
| Mindray Medical International |
| AMD Global Telemedicine |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan and South Korea fabs lock in sensor chip allocation and provide 12-18 month price visibility for device manufacturers navigating semiconductor supply volatility. These arrangements tie procurement teams to minimum volume commitments while insulating tier-one vendors from spot-market price swings that compress margins for smaller competitors.
Pricing Analysis
Certification level creates the primary spread across Asia-Pacific RPM procurement, with ISO 13485 and PMDA SaMD-grade devices commanding 35-50% premiums over uncertified alternatives in Japanese hospital networks. Subscription-based SaaS pricing dominates telehealth platforms, though China's provincial procurement platforms are forcing unbundled hardware-software contracts that expose device vendors to discrete price ceilings. Cost compression runs through mid-tier wearable segments as Mindray and domestic Chinese manufacturers compete on manufacturing scale. Hospital procurement committees in tier-one cities show lowest price sensitivity for continuous data fidelity, while India's direct-pay diabetes clinics prioritize per-unit affordability over after-service bundling.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates inbound logistics costs for medical-grade sensor components originating from Taiwan, South Korea, and Japan. Taiwan and South Korea fabs control medical-grade biosensor chip production, while China dominates printed circuit board and battery cell manufacturing. Single-source vulnerability concentrates in 40nm and below semiconductor nodes, where foundry allocation volatility exposes device manufacturers to 26-week lead time extensions. Distribution runs through hospital procurement committees in tier-one cities, direct-to-patient pharmacy networks in Singapore and Malaysia, and federal domiciliary program administrators in Australia and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping Asia-Pacific RPM competitive dynamics as HL7 FHIR interoperability gaps force vendors to maintain multiple integration stacks, rewarding ecosystem orchestrators over point-solution specialists.
For Market Incumbents: Fortify quality management system certification capacity to offset ISO 13485 auditor scarcity in Australia and Japan, compressing 14-18 month timelines that delay product launches. Deepen backward integration into sensor chip supply through strategic partnerships with Taiwan and South Korea fabs, reducing exposure to foundry allocation volatility that disrupts tier-one hospital procurement cycles. For New Entrants and Emerging Players: Differentiate on edge computing architectures that satisfy China's NMPA data localization mandates without redundant infrastructure deployment costs that inflate multinational platform economics. Target India's CDSCO PLI contract manufacturing clusters in Hyderabad and Bengaluru, where production-linked incentives reduce landed costs for ASEAN distribution and enable price-competitive entry into mid-tier hospital procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth platform operators with hospital system partnerships in Japan and Australia, where SaaS pricing resilience offsets hardware margin compression. Long-term viability hinges on data sovereignty compliance capabilities across fragmented Asia-Pacific regulatory frameworks. Acquisition focus should center on edge-AI specialists with federated learning protocols. Watch for PMDA SaMD framework expansion into algorithm-driven diagnostic categories as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA SaMD Certification Pathway | Accelerates market entry for cloud-native platforms in Japanese hospital networks. |
| Hospital System Partnership | Secures procurement committee placement in China's tier-one unbundled contracting environment. |
| Edge Computing Architecture Development | Addresses NMPA data localization without redundant infrastructure cost inflation. |
| CDSCO PLI Manufacturing Scale-Up | Reduces landed costs for ASEAN distribution through Hyderabad and Bengaluru clusters. |
| Reimbursement Strategy Alignment | Captures Australia's federal domiciliary care subsidy flows toward hospital-at-home protocols. |
Study Parameters
Desk research of regulatory filings from PMDA, NMPA, CDSCO and TGA preceded structured interviews with hospital procurement managers, biomedical engineers, GPO contracts administrators, and telehealth platform CTOs across Tokyo, Shanghai, Bengaluru, Sydney and Singapore. Primary fieldwork combined with secondary validation against hospital procurement databases, GPO contract repositories, and medical device registration records. Bottom-up patient population modeling and top-down healthcare expenditure allocation were triangulated to establish market sizing.
Variance decomposition across technology, end user, delivery mode and application segments drove analytical framework construction throughout the projection horizon. Deployment model complexity, data sovereignty requirements, and reimbursement coding evolution shaped segmentation-specific growth trajectories. CAGRs were derived from patient population epidemiology, reimbursement policy trajectories, and technology substitution curves for continuous glucose monitoring and AI-ECG pattern recognition.
Material uncertainties — semiconductor supply volatility, regulatory framework divergence, and reimbursement coding delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding PMDA SaMD adoption velocity and NMPA pilot zone expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Lung Monitoring Devices Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Global Body Temperature Monitoring Market
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Sleep Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Respiratory Gas Monitors Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
Germany Patient Monitoring Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Asia-Pacific Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
United States Patient Monitoring Market