
 Continuous Cardiac Monitoring Devices Market | 2026-2036
Continuous Cardiac Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Cardiac Monitoring Devices Market Analysis
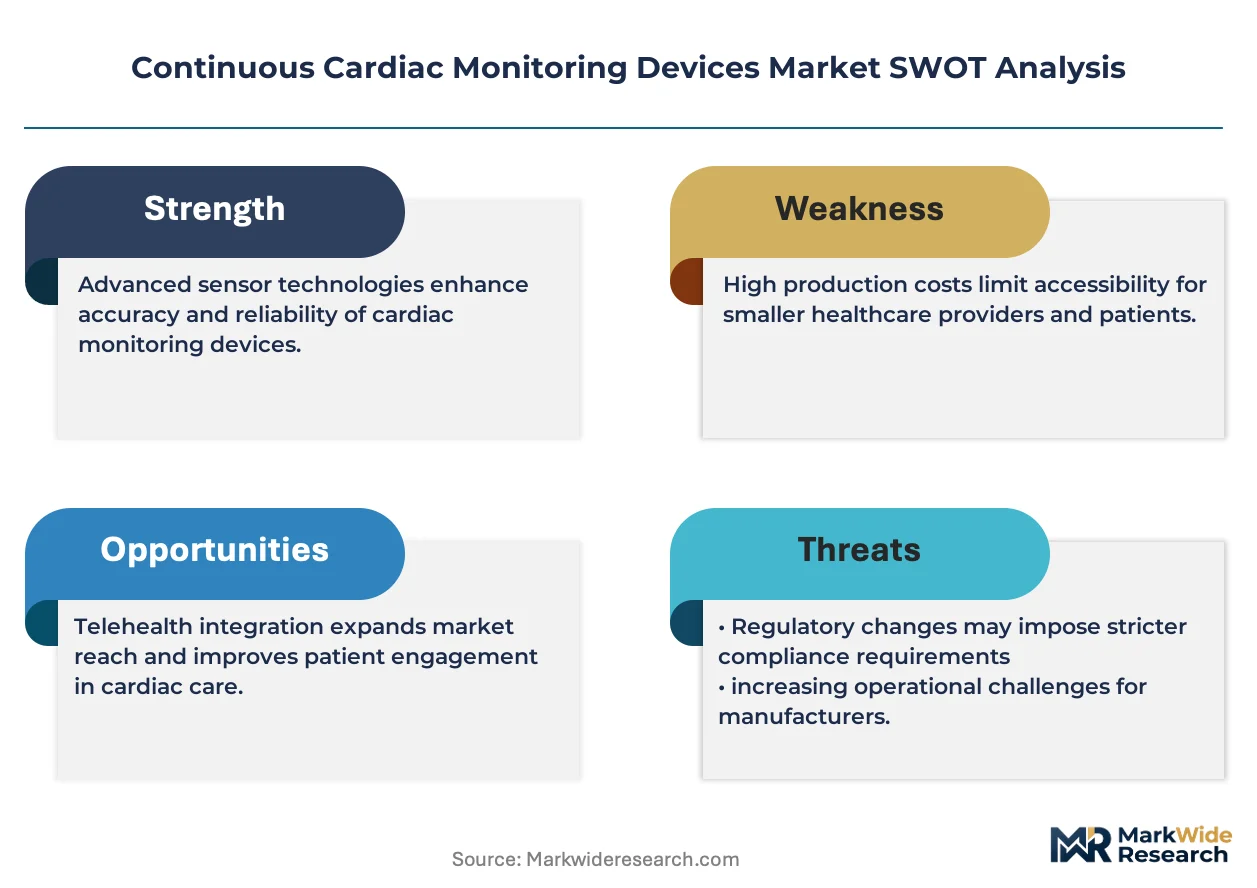
Hospital-grade telemetry certification is bifurcating the competitive landscape into acute-care specialists and consumer-facing remote monitoring platforms. Medtronic leverages its implantable loop recorder portfolio to anchor high-acuity hospital contracts across major health systems. Abbott Laboratories differentiates through extended-wear wearable patches that compete directly with traditional event monitors in outpatient cardiology.
Continuous cardiac monitoring devices encompass wearable, implantable, and handheld systems that acquire electrophysiological signals at sampling rates exceeding 250 Hz for real-time arrhythmia detection and hemodynamic assessment. These systems serve the primary commercial purpose of enabling early intervention in cardiac events while reducing dependence on intermittent in-person testing. Implantable devices command the deepest margin pools due to surgical placement requirements and long-term follow-up revenue streams, while wearable monitors represent the fastest-expanding segment as Bluetooth-enabled patches integrate with cloud-based analytics platforms. Cloud-based solutions are reshaping data architecture across the sector, allowing telemedicine providers to manage distributed patient populations without proprietary hardware investments.
FDA premarket notification pathways and ISO 13485 quality management standards govern device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device components. HIPAA compliance obligations shape data transmission architectures, particularly for cloud-based solutions handling protected health information across home care settings. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms, as predicate device pathways for machine-learning-based arrhythmia classification remain under active regulatory development.
Market Dynamics
The migration from episodic Holter monitoring to continuous patch-based telemetry is restructuring hospital procurement patterns and vendor contracting strategies across ambulatory cardiology networks.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for long-term cardiac monitoring in the United States removes cost barriers for outpatient electrophysiology services and accelerates provider adoption of wearable telemetry.
- Bluetooth Low Energy Integration:Wireless protocol standardization enables seamless data transmission from ambulatory patches to cloud analytics platforms without proprietary receiver hardware.
- Hospital Readmission Penalty Pressure:Value-based payment models in North American health systems create institutional demand for remote patient monitoring solutions that track post-discharge arrhythmia recurrence.
Market Restraints
- Implantable Device Cost Concentration:Surgical placement requirements and specialized electrophysiologist labor constrain volume expansion in loop recorder procedures.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for software-as-a-medical-device components extend certification timelines for cloud-based arrhythmia analytics platforms.
- Silver-Zinc Battery Supply:Extended-wear patch manufacturers face input cost volatility from concentrated East Asian cell suppliers.
Strategic Opportunities
- Home-Based Heart Failure Monitoring:Integration of impedance-derived hemodynamic data with ECG streams creates new reimbursement categories for telemedicine providers managing chronic cardiac patients.
- FDA AI/ML Guidance Window:Evolving predicate device pathways for machine-learning arrhythmia classification offer first-mover advantages for algorithm developers with robust training datasets.
- Rural Health Network Penetration:Underserved regions in the United States present white space for asynchronous cardiology interpretation services delivered through wearable-enabled remote monitoring.
Industry Challenges
- Electrophysiology Data Scientist Scarcity:Shortage of specialists capable of validating machine-learning models against annotated ECG gold standards slows algorithm deployment.
- HIPAA-Compliant Cloud Architecture:Engineering teams must redesign data transmission pipelines to satisfy protected health information requirements across multi-tenant analytics environments.
- Legacy EMR Integration:Hospital IT departments face protracted interface development cycles when connecting proprietary patch data formats to established electronic medical record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Cardiac Monitoring Devices Market |
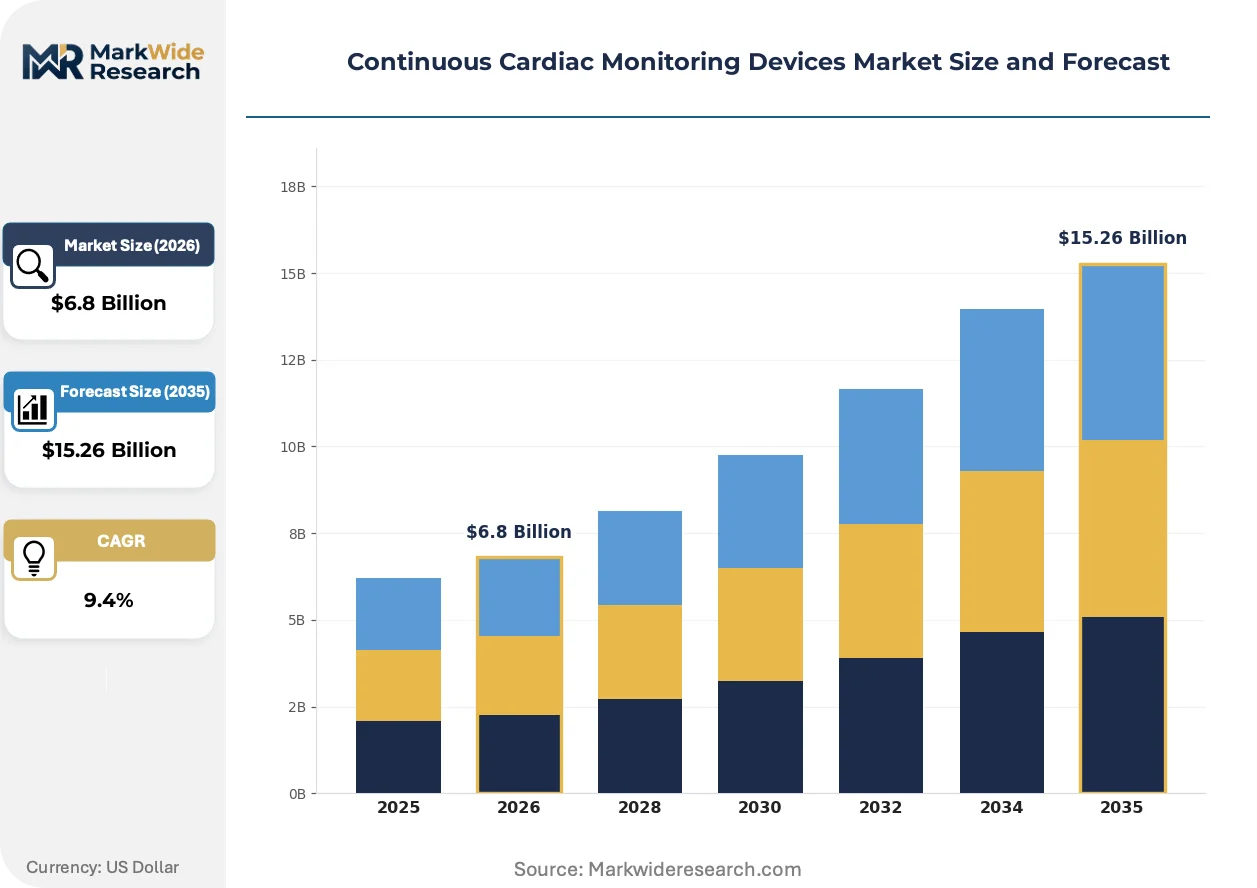
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Implantable Devices, Handheld Devices, Mobile Apps Technology: ECG Monitoring, RFID Technology, Bluetooth Technology, Cloud-Based Solutions End User: Hospitals, Home Care Settings, Emergency Services, Telemedicine Providers Application: Arrhythmia Monitoring, Heart Rate Variability, Post-Operative Care, Sports Medicine |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, Philips, GE Healthcare, Edwards Lifesciences Corporation, BIOTRONIK, iRhythm Technologies, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Cardiac Monitoring Devices Market Emerging Trajectories
Wearable ECG patch technology is actively fragmenting the traditional diagnostic monitoring landscape, creating parallel demand channels for consumer-accessible and prescription-grade telemetry systems.
Extended-wear adhesive electrode arrays capable of 14-day continuous recording are bifurcating the competitive landscape between acute-care telemetry specialists and direct-to-consumer heart health platforms. Outpatient cardiology clinics in the United States are adopting these patches at accelerating rates for cryptogenic stroke workups and intermittent symptom correlation. The technology is compressing margins for conventional event monitor manufacturers while opening subscription revenue models for cloud-integrated analytics providers.
FDA draft guidance on predetermined change control plans for artificial intelligence-enabled devices is reshaping regulatory submission strategies for arrhythmia detection algorithms. Manufacturers must now document anticipated software modifications prior to market authorization, increasing upfront development costs. Cloud-based diagnostic platforms with machine-learning components face the most significant compliance burden as they iterate algorithms against real-world performance data.
Cardiology group purchasing organizations are consolidating vendor contracts around integrated hardware-software-service bundles rather than discrete device procurement. Independent electrophysiology practices find themselves excluded from preferred pricing tiers, driving consolidation into hospital-employed models. This concentration is most visible in United States metropolitan markets where health system market power enables exclusive telemetry partnerships with single manufacturers.
Continuous Cardiac Monitoring Devices Market Segmentation
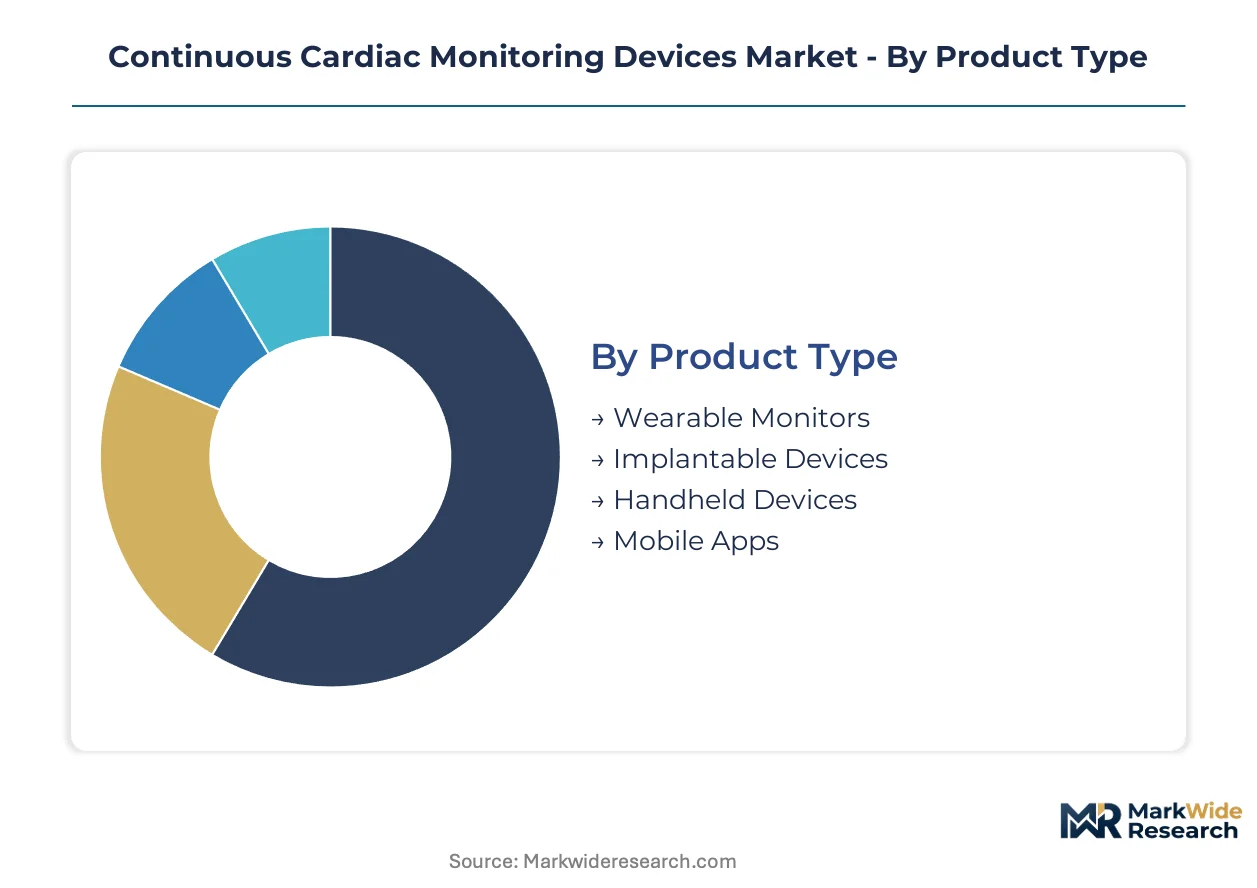
Segmentation in the Continuous Cardiac Monitoring Devices Market reveals divergent margin structures and regulatory pathways across hardware categories. Product architecture determines whether vendors pursue hospital procurement contracts or direct-to-consumer subscription models.
Product Type:
Wearable monitors and implantable devices follow distinct geographic demand patterns, with the former scaling through retail pharmacy channels and the latter concentrating in tertiary cardiac centers.
- Wearable Monitors:Adhesive ECG patches with 7-14 day wear durations transmit data via Bluetooth Low Energy to cloud analytics platforms. Demand concentrates in outpatient cardiology clinics across the United States, where Medicare reimbursement for long-term ambulatory monitoring accelerates replacement of traditional Holter systems.
- Implantable Devices:Subcutaneous loop recorders with 2-3 year battery life capture arrhythmia data through internal electrodes. Surgical placement requirements limit volume to electrophysiology departments in major health systems, with revenue concentrated in high-acuity hospital contracts.
- Handheld Devices:Portable ECG recorders with finger electrodes or chest leads for point-of-care screening.
- Mobile Apps:Smartphone-integrated algorithms for consumer heart rhythm awareness without prescription-grade diagnostic claims.
Implantable devices hold the largest share; momentum sits with wearable monitors.
Technology:
Technology segments stratify by data transmission architecture, with cloud integration becoming the decisive cost tier for enterprise procurement decisions.
- ECG Monitoring:Core electrophysiological signal acquisition at 250+ Hz sampling rates forms the diagnostic foundation across all device categories. Hardware-agnostic ECG front-ends allow manufacturers to source electrodes and amplifiers from diversified component suppliers.
- Cloud-Based Solutions:Centralized data repositories with machine-learning arrhythmia classification enable telemedicine providers to manage distributed patient populations without proprietary hardware investments. FDA scrutiny of predetermined change control plans for AI-enabled diagnostics elevates compliance costs for algorithm developers.
- Bluetooth Technology:Wireless protocol standardization for ambulatory patch-to-smartphone data relay.
- RFID Technology:Passive identification systems for patient-device pairing in hospital inventory management.
ECG monitoring anchors current revenue; cloud-based solutions are climbing the fastest.
End User:
End user concentration reflects reimbursement architecture, with institutional buyers commanding volume discounts unavailable to individual consumers.
- Hospitals:Integrated health systems purchase telemetry hardware through group purchasing organization contracts bundled with software licenses and interpretation services. Readmission penalty pressure under CMS value-based payment models drives investment in post-discharge monitoring infrastructure.
- Telemedicine Providers:Asynchronous cardiology platforms rely on wearable-enabled remote monitoring to serve rural populations without local electrophysiology specialists. Cloud-based analytics subscriptions generate recurring revenue independent of device hardware margins.
- Home Care Settings:Post-acute patients managing chronic heart failure through impedance-derived hemodynamic monitoring.
- Emergency Services:Prehospital ECG acquisition for rapid STEMI identification and cath lab activation.
Hospitals dominate procurement volume; telemedicine providers show the steepest expansion trajectory.
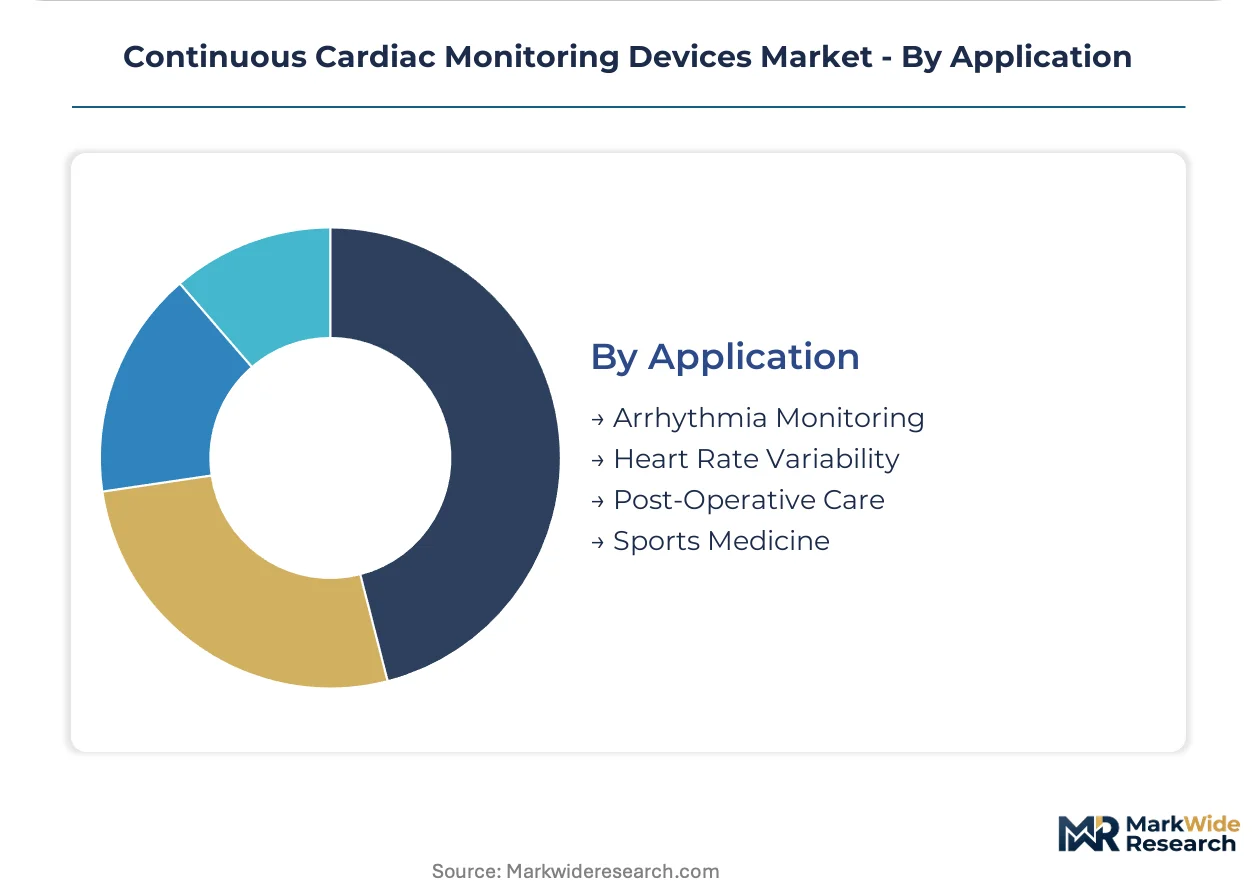
Application:
Application segmentation tracks clinical utility from acute event detection to performance optimization, with regulatory classification determining commercial access pathways.
- Arrhythmia Monitoring:Detection of atrial fibrillation, ventricular tachycardia, and conduction abnormalities represents the primary reimbursed indication for prescription-grade devices. Cryptogenic stroke workups drive 14-day patch utilization in United States neurology and cardiology practices.
- Post-Operative Care:Continuous telemetry following cardiac surgery or catheter ablation enables early detection of recurrent arrhythmia before hemodynamic compromise. Hospital systems deploy disposable patches to reduce nursing labor costs associated with traditional bedside monitoring.
- Heart Rate Variability:Autonomic nervous system assessment for wellness and athletic performance applications.
- Sports Medicine:Pre-participation screening and training load optimization in competitive athletics.
Arrhythmia monitoring captures the deepest revenue pools; post-operative care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers export wearable ECG patch systems to Canadian hospital networks and European telemedicine providers, establishing transatlantic supply corridors for ambulatory cardiac telemetry hardware.
United States
Medicare reimbursement expansion for long-term cardiac monitoring and CMS readmission penalty pressure drive hospital procurement of remote patient monitoring infrastructure. FDA premarket notification pathways under 510(k) govern wearable device commercialization, with evolving guidance on AI-enabled diagnostic algorithms. The Minneapolis-St. Paul corridor anchors electrophysiology device development, while Boston's medical technology cluster concentrates implantable loop recorder engineering talent.
Germany
Hospital system consolidation and value-based care contracts accelerate demand for integrated telemetry hardware-software bundles. EU Medical Device Regulation imposes stricter clinical evidence requirements for software-as-a-medical-device components, extending certification timelines for cloud-based analytics platforms. The Baden-Württemberg region hosts precision electronics manufacturing for extended-wear adhesive electrode arrays supplying outpatient cardiology networks.
Japan
Aging demographics and government telehealth reimbursement expansion create institutional demand for home-based cardiac monitoring solutions. PMDA regulatory frameworks govern software-enabled medical devices, with particular scrutiny of machine-learning arrhythmia classification algorithms. The Tokyo-Osaka corridor concentrates digital health platform development, with Kansai-based manufacturers supplying Bluetooth-enabled patch hardware to domestic hospital chains.
United Kingdom
NHS Long Term Plan targets for cardiovascular disease prevention drive procurement of ambulatory monitoring for cryptogenic stroke workups. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for AI-enabled diagnostics while maintaining alignment with EU MDR standards. The Cambridge-Oxford-London triangle anchors cardiac digital health startups developing cloud-based interpretation services for regional hospital networks.
India
Expanding private hospital chains and medical tourism infrastructure create demand for cost-optimized telemetry solutions in tier-1 and tier-2 cities. CDSCO medical device rules govern import and local manufacturing of cardiac monitoring hardware, with quality management system requirements under ISO 13485. Hyderabad and Bengaluru clusters host software development for remote cardiac analytics platforms serving domestic telemedicine providers.
Continuous Cardiac Monitoring Devices Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory sophistication, with publicly traded device manufacturers holding advantages in hospital GPO contracting while venture-backed platforms capture telemedicine subscription revenue. The competitive structure bifurcates between implantable device incumbents with deep electrophysiology relationships and wearable patch challengers scaling through direct-to-clinic sales. Three archetypes dominate: diversified cardiovascular conglomerates anchoring health system contracts, pure-play telemetry specialists monetizing cloud analytics, and diversified electronics manufacturers supplying commoditized sensor hardware. M&A activity concentrates on AI-enabled diagnostic platforms and extended-wear patch technologies, while strategic partnerships between device makers and telemedicine providers reshape distribution economics.
Among diversified cardiovascular conglomerates, Medtronic and Abbott Laboratories exemplify the acute-care contract archetype, anchoring high-volume hospital system relationships through integrated implantable and wearable portfolios. iRhythm Technologies occupies a distinct position as a pure-play ambulatory monitoring specialist, representing the cloud-native platform model that telemedicine providers favor for distributed patient population management.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| Philips |
| GE Healthcare |
| Edwards Lifesciences Corporation |
| BIOTRONIK |
| iRhythm Technologies |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day electrode array lead times from East Asian contract manufacturers concentrate procurement leverage among hospital systems with multi-year volume commitments, compressing margins for mid-tier wearable patch vendors while insulating integrated device-electrophysiology service bundles from spot-price volatility.
Pricing Analysis
Hospital procurement committees anchor pricing structure around three-tier hardware-software-service bundles spanning premium implantable loop recorder systems, standard extended-wear patch platforms, and economy-grade event monitor replacements. Price differentiation hinges on FDA 510(k) clearance tier and cloud analytics integration depth, with Medicare reimbursement rate pressure intensifying cost compression in the standard tier. Outpatient cardiology clinics exhibit highest price sensitivity due to thin procedure margins, while integrated health systems leverage GPO scale for locked-in multi-year contracts.
Supply Chain Analysis
Just-in-time inventory strategies dominate adhesive electrode and Bluetooth module procurement, though silver-zinc battery cell sourcing from concentrated South Korean and Japanese suppliers drives strategic stockpiling among tier-one patch manufacturers. Component dependencies center on precision analog front-end semiconductors from Taiwan, medical-grade adhesives from Germany, and flexible printed circuit substrates from China. Single-source vulnerability in advanced ECG amplifier chipsets constitutes the primary structural risk. Distribution runs through cardiology-focused medical device distributors and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native telemetry platforms are reshaping competitive economics through interoperability mandates that favor algorithm-as-a-service models over proprietary hardware lock-in, creating winner-take-most dynamics for electrophysiology data aggregators with training-set scale advantages.
For Market Incumbents: Shield high-acuity hospital contracts by deepening electrophysiologist training program investments and securing exclusive GPO telemetry partnerships before AI-enabled diagnostic platforms achieve FDA predetermined change control plan clearance. Vertical integration into extended-wear adhesive manufacturing mitigates silver-zinc battery supply volatility threatening margin stability in the wearable segment.
For New Entrants and Emerging Players: Differentiate on asynchronous interpretation services for rural United States health networks lacking local electrophysiology coverage, where Medicare reimbursement expansion creates immediate addressable demand. Target telemedicine provider white space through white-label cloud analytics partnerships rather than direct hardware competition with entrenched hospital vendors.
For Investors and Strategic Acquirers: Long-term, this sits as a data-network-effects play because arrhythmia classification algorithm accuracy scales non-linearly with annotated ECG volume, concentrating value capture among platforms with earliest hospital system data-sharing agreements. Acquisition candidates with robust HIPAA-compliant cloud architectures and FDA Q-Sub engagement history warrant premium positioning. Watch FDA draft guidance finalization on machine-learning predicate pathways as the definitive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Extended-Wear Patch | Clears Medicare reimbursement pathway for 14-day ambulatory monitoring in outpatient cardiology. |
| Hospital System GPO Partnership | Locks multi-year telemetry hardware-software-service contracts against competing vendor encroachment. |
| Cloud Analytics Platform Integration | Enables telemedicine providers to manage distributed patient populations without proprietary hardware. |
| AI Arrhythmia Algorithm Training Dataset Expansion | Builds regulatory-defensible performance claims for FDA predetermined change control plan submissions. |
| Reimbursement Strategy for Home-Based Heart Failure Monitoring | Creates new CMS billing codes integrating impedance-derived hemodynamic data with ECG streams. |
Methodological Framework
Operator-level perspectives from electrophysiologists, hospital biomedical engineers, GPO contracts managers, and telemedicine platform CTOs anchored the qualitative base, triangulated against CMS Medicare reimbursement databases, FDA 510(k) premarket notification filings, hospital procurement contract records, and electrophysiology society practice guidelines. Bottom-up wearable patch shipment estimates from component suppliers converged with top-down health system telemetry budget allocations.
Sensitivity analysis tested forecast robustness across alternative CMS reimbursement expansion scenarios and EU MDR software-as-a-medical-device compliance timeline assumptions over the projection horizon. Segmentation modeling incorporated product architecture, cloud integration depth, end-user concentration, and application-specific regulatory classification. CAGRs derived from logistic diffusion curves fitted to historical implantable loop recorder and wearable patch adoption patterns, calibrated against electrophysiology procedure volume growth and remote patient monitoring infrastructure investment cycles.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability and Bluetooth Low Energy protocol standardization would require recalibration. Forecasts reflect assumptions regarding FDA AI/ML guidance finalization and silver-zinc battery supply continuity. Revision becomes warranted when EU MDR certification timeline delays or hospital system consolidation acceleration crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Hemoglobin Monitor Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
China Patient Monitoring Market
Patient Monitoring
North America Patient Monitoring Market
Patient Monitoring
Europe Wireless Healthcare Market
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Cardiac Rhythm Remote Monitoring Devices Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Patient Monitoring Devices Market