
 Life Science R&D Infrastructure Outsourcing Market | 2026-2036
Life Science R&D Infrastructure Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Life Science R&D Infrastructure Outsourcing Market Analytics
Contractor-to-sponsor infrastructure allocation is tilting toward integrated platform providers capable of spanning discovery through commercialization. IQVIA leverages its real-world evidence networks to anchor large-scale clinical trial site management across multiple continents. Charles River Laboratories specializes in preclinical laboratory services with extensive vivarium and analytical testing capacity. Lonza dominates cell and gene therapy manufacturing infrastructure, extending bioproduction capabilities into emerging modalities.
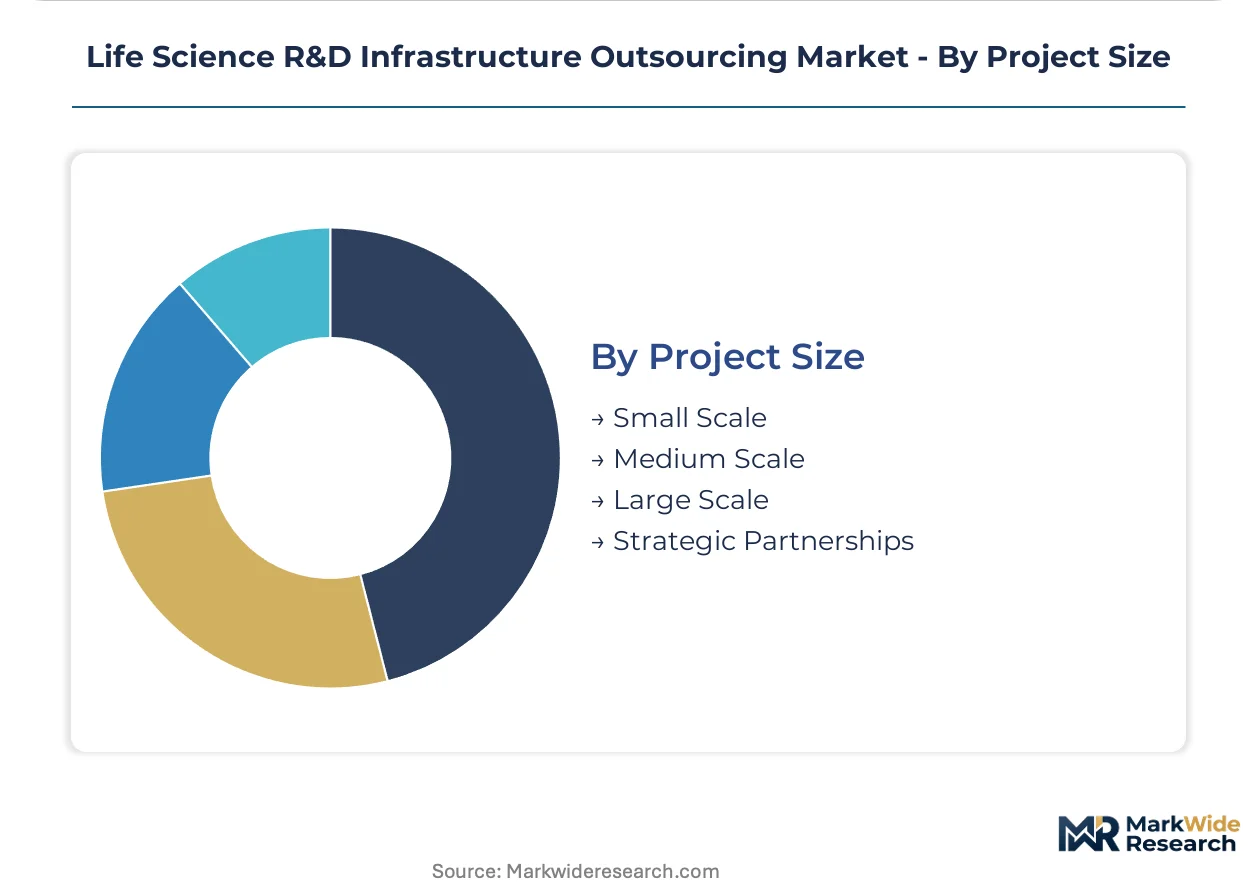
Life Science R&D Infrastructure Outsourcing encompasses the third-party provision of purpose-built laboratory facilities, specialized equipment suites, and technical personnel to support pharmaceutical and biotechnology research operations, typically governed by GLP and GMP quality standards with environmental monitoring and chain-of-custody documentation. Its primary commercial purpose is converting fixed capital expenditures into variable operational costs while accelerating program timelines for asset owners. Laboratory Services commands the largest revenue share among service types due to recurring analytical testing and formulation work, while Genomic Sequencing infrastructure within the technology dimension exhibits the fastest expansion trajectory as CRISPR and single-cell platforms multiply instrument footprints. Small Scale projects retain volume dominance, though Strategic Partnerships capture disproportionate margin pools through multi-year dedicated facility arrangements.
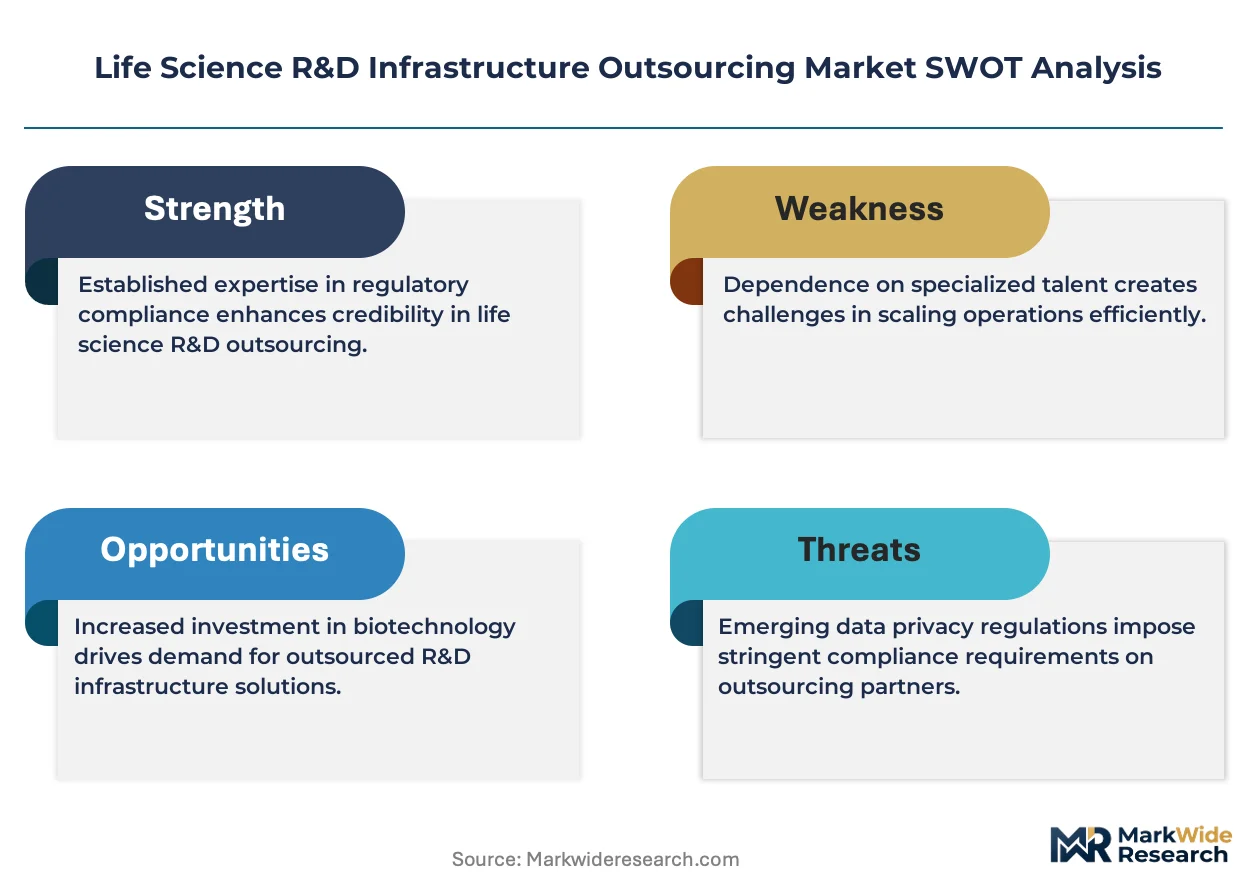
FDA's GLP and GMP enforcement shapes facility design standards and audit frequencies for US-based outsourcing relationships, while EMA's clinical trial regulation harmonizes infrastructure qualification requirements across European member states. ISO 15189 and OECD principles further constrain laboratory accreditation pathways, raising barriers for undercapitalized regional operators. Stakeholders must monitor how AI-validated laboratory automation alters capacity planning assumptions and regulatory inspection protocols.
Market Dynamics
Biopharmaceutical sponsors are compressing fixed-cost exposure by converting proprietary laboratory footprints into variable opex through dedicated facility arrangements with specialized infrastructure providers.
Growth Catalysts
- GLP/GMP Audit Intensification:FDA and EMA inspection frequency increases push asset owners toward qualified third-party facilities with established quality systems and documented environmental monitoring protocols.
- Cell Therapy Manufacturing Scale-Up:Autologous and allogeneic cell therapy pipelines require specialized cleanroom suites and cryogenic logistics that biotech sponsors lack capital to build in-house.
- Single-Cell Platform Proliferation:CRISPR screening and spatial transcriptomics workflows demand instrument clusters and computational infrastructure beyond typical mid-cap biotech balance sheets.
Market Restraints
- Specialized Labor Scarcity:GLP-certified study directors and GMP-qualified manufacturing scientists command premium compensation that inflates facility operating costs.
- Equipment Supplier Concentration:Chromatography skids and single-use bioreactor systems source from limited German and Swiss OEMs, creating input bottlenecks.
- Chain-of-Custody Documentation Burden:OECD principles and ISO 15189 requirements impose sample tracking infrastructure that raises minimum viable facility investment thresholds.
Strategic Opportunities
- India CDMO Infrastructure Gap:CDSCO-aligned facilities for bioanalytical testing and formulation development remain underdeveloped relative to domestic generic API manufacturing scale.
- AI-Validated Laboratory Automation:Convergence of robotics platforms with machine learning-based assay validation compresses analytical turnaround times and inspection readiness.
- Strategic Partnership Contracting:Multi-year dedicated facility arrangements with guaranteed capacity allocations capture margin pools unavailable in transactional project work.
Industry Challenges
- Cross-Functional Talent Integration:Facilities must recruit hybrid scientists capable of operating automated liquid handlers while interpreting regulatory guidance documents.
- Legacy LIMS Migration:Paper-based batch records and disconnected instrument data lakes impede real-time capacity visibility across distributed site networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Science R&D Infrastructure Outsourcing Market |
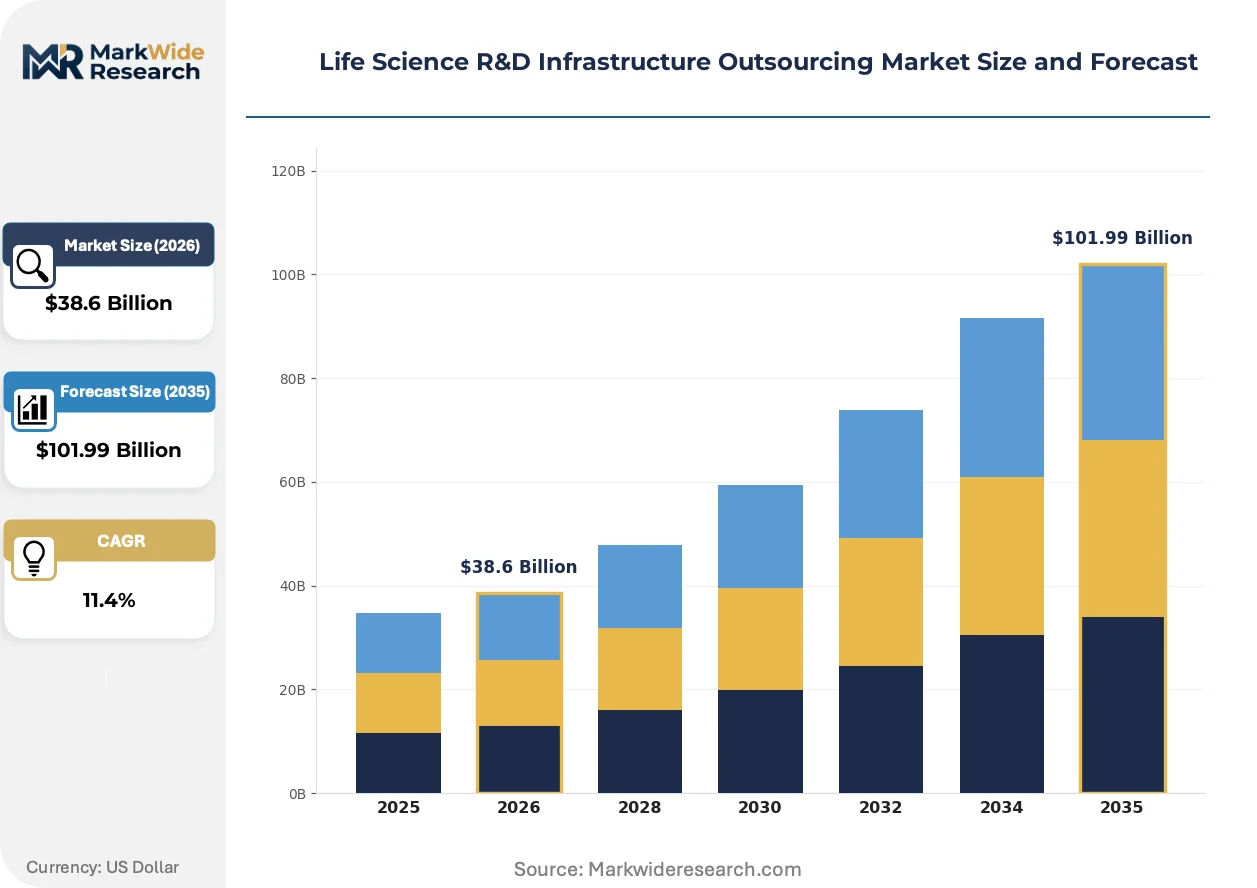
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Services, Data Management, Clinical Trials, Preclinical Research End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Technology: Genomic Sequencing, Bioinformatics Tools, Laboratory Automation, Analytical Instruments Project Size: Small Scale, Medium Scale, Large Scale, Strategic Partnerships |
| Companies Covered | IQVIA, Labcorp, Charles River Laboratories, Parexel International Corporation, ICON plc, Syneos Health, Lonza, Thermo Fisher Scientific, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Science R&D Infrastructure Outsourcing Market Evolving Landscape
Laboratory infrastructure provisioning is pivoting from static facility leasing toward dynamic capacity platforms that synchronize instrument utilization with program-stage demands.
Cloud-native laboratory information management systems are digitizing sample tracking, environmental monitoring, and equipment qualification workflows across multi-site networks. Mid-cap biotech sponsors adopt these platforms fastest, replacing on-premise LIMS within 18-24 month migration windows. Real-time dashboard visibility is digitizing capacity planning, enabling sponsors to right-size infrastructure commitments as programs advance from discovery into GLP toxicology.
EMA's clinical trial regulation harmonizes infrastructure qualification requirements across European member states, eliminating redundant national inspections for multi-country studies. Sponsors now qualify central laboratories once for pan-European deployment rather than duplicating efforts. Cell therapy developers with EU commercialization targets are consolidating manufacturing infrastructure in Belgium and Netherlands to exploit this regulatory convergence.
Biopharmaceutical procurement teams are unbundling analytical testing from integrated discovery contracts, awarding standalone formulation and bioanalytical work to specialized infrastructure providers. This disintermediation fragments purchasing authority that previously resided with full-service CRO relationship managers. United States-based sponsors with compressed IND timelines drive this behavior most aggressively, prioritizing instrument access over bundled service convenience.
Life Science R&D Infrastructure Outsourcing Market Segmentation
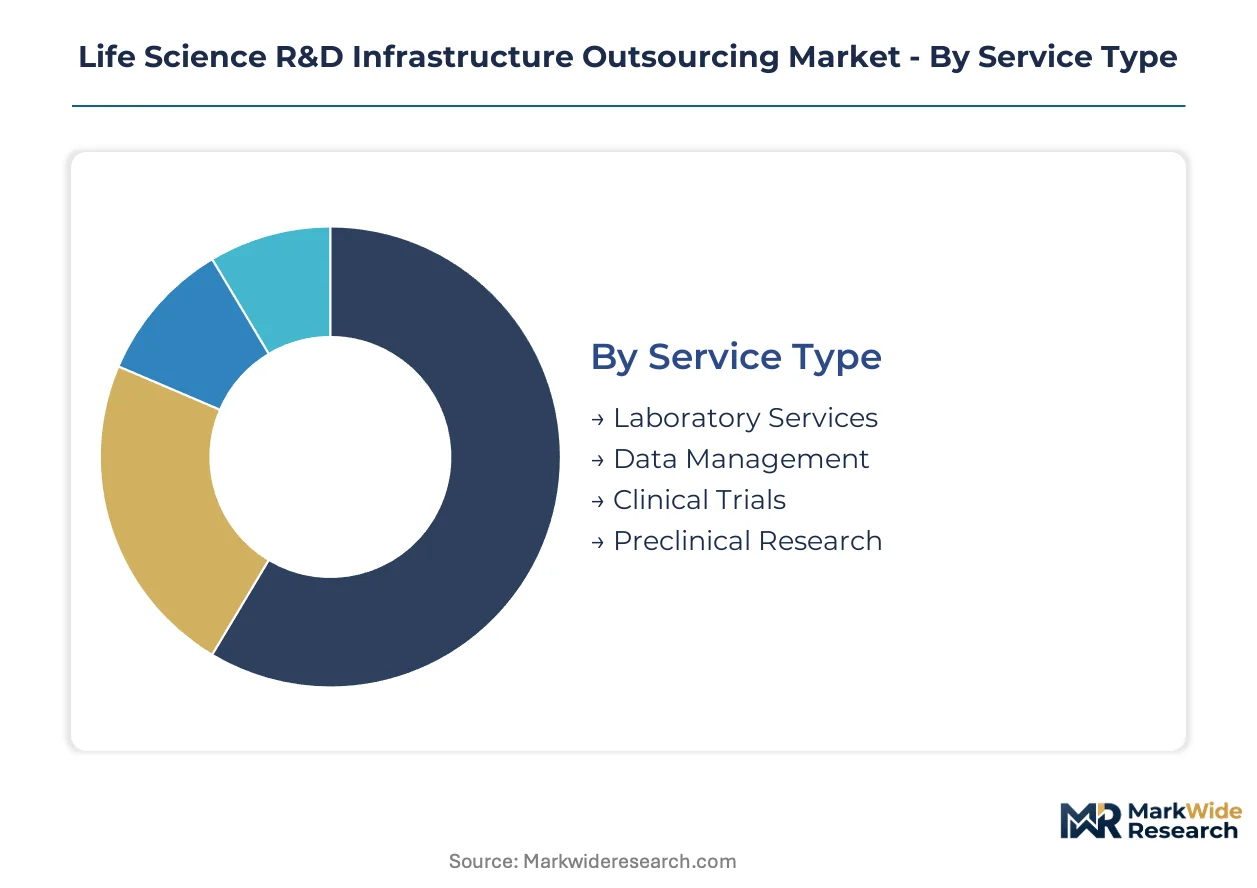
Segmentation in life science R&D infrastructure outsourcing reveals how contract structures and technical capabilities align with sponsor risk tolerance and program maturity. Distinct service tiers, technology platforms, and engagement scales command fundamentally different pricing models and facility investment profiles.
Service Type:
Laboratory Services turn over fastest with recurring analytical cycles measured in days, while Clinical Trials infrastructure locks in multi-year site commitments with qualification timelines spanning quarters.
- Laboratory Services:Encompasses GLP-compliant analytical testing, formulation development, and stability studies executed within controlled environmental conditions. Demand concentrates among mid-cap biotechnology firms in Massachusetts and California seeking to avoid capital deployment in chromatography and mass spectrometry suites. FDA audit intensification drives preference toward providers with documented equipment qualification protocols.
- Data Management:Covers clinical data capture, statistical programming, and regulatory submission infrastructure including validated computing environments. Pharmaceutical sponsors in New Jersey and Pennsylvania outsource these functions to compress database lock timelines for NDA filings. EMA's clinical trial regulation harmonization reduces redundant system validation across European member states.
- Clinical Trials:Site management infrastructure spanning patient recruitment networks, investigator site facilities, and central laboratory coordination. Contract Research Organizations represent the dominant procurement channel for these bundled services.
- Preclinical Research:Vivarium facilities, in vivo imaging suites, and GLP toxicology study execution. Charles River Laboratories and similar providers maintain dedicated capacity for IND-enabling safety assessment programs.
Laboratory Services anchors the volume base while Data Management gains share at the steepest rate as real-world evidence requirements expand computational infrastructure demand.
End User:
Cost tier stratification separates capital-constrained academic budgets from strategic partnership commitments capable of underwriting dedicated facility construction.
- Pharmaceutical Companies:Large-cap sponsors with global commercial portfolios leverage outsourcing to convert fixed laboratory footprints in Connecticut, Illinois, and New Jersey into variable operational expenditures. These organizations prioritize providers with established FDA inspection histories and multi-continent redundancy.
- Biotechnology Firms:Venture-backed and publicly traded development-stage companies lacking balance sheet capacity for specialized cleanroom or vivarium construction. Boston and San Francisco clusters drive disproportionate demand for flexible, short-term infrastructure access.
- Academic Institutions:University medical centers and research foundations accessing outsourced capabilities for grant-funded investigator-initiated studies. Funding cycle discontinuity creates demand volatility relative to commercial sponsors.
- Contract Research Organizations:Full-service and niche CROs subcontracting specialized capacity to extend service portfolios without direct capital investment. These intermediaries concentrate procurement authority for sponsor-facing relationships.
Biotechnology Firms generate the highest transaction velocity while Pharmaceutical Companies capture margin concentration through multi-year strategic partnerships.
Technology:
Application criticality varies across discovery, characterization, and quality control workflows with divergent throughput and regulatory scrutiny requirements.
- Genomic Sequencing:Next-generation sequencing platforms, single-cell transcriptomics infrastructure, and CRISPR screening capabilities requiring substantial instrument clusters and computational storage. Spatial omics expansion in Cambridge and South San Francisco biotechnology corridors drives capacity investment.
- Bioinformatics Tools:Cloud-based pipeline infrastructure for variant calling, pathway analysis, and AI-assisted target identification. FDA guidance on computational model validation shapes qualification requirements for regulatory submission support.
- Laboratory Automation:Robotic liquid handling, automated sample preparation, and integrated workcell configurations. Labor scarcity in GLP-certified study director roles accelerates sponsor preference for automated analytical workflows.
- Analytical Instruments:Chromatography, mass spectrometry, and spectroscopy platforms for small-molecule and biologic characterization. Equipment supplier concentration among German and Swiss OEMs creates procurement bottlenecks.
Analytical Instruments maintains volume dominance while Genomic Sequencing climbs the fastest as cell and gene therapy pipelines multiply instrument footprint requirements.
Project Size:
Customer type and engagement duration separate transactional project work from captive capacity arrangements with divergent margin and capital intensity profiles.
- Small Scale:Discrete analytical testing campaigns, pilot formulation batches, and limited toxicology studies with defined deliverables and 30-90 day execution windows. Mid-cap biotechnology sponsors in Research Triangle Park and San Diego deploy this tier for IND-enabling data packages.
- Medium Scale:Multi-study programs spanning 6-18 months with dedicated project teams and reserved instrument access. These engagements balance flexibility with preferential scheduling.
- Large Scale:Phase II-III clinical trial infrastructure, commercial manufacturing technology transfer, and integrated discovery-to-development platforms. Lonza and IQVIA compete for these capital-intensive commitments.
- Strategic Partnerships:Multi-year dedicated facility arrangements with guaranteed capacity allocations, joint governance structures, and co-investment in specialized equipment. EMA-aligned sponsors consolidate manufacturing in Belgium and Netherlands under this model.
Small Scale projects sustain transaction volume while Strategic Partnerships expand most quickly as sponsors seek supply security for cell therapy commercialization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for biotech R&D infrastructure investment are reshaping national competitive positioning. FDA and EMA regulatory tightening accelerates sponsor migration toward qualified third-party facilities with established quality systems. Capital deployment concentrates in jurisdictions offering accelerated approval pathways and specialized workforce pipelines.
United States
FDA GLP and GMP audit intensification drives demand for qualified laboratory infrastructure among mid-cap biotechnology sponsors. The Inflation Reduction Act provisions reshape capital allocation toward outsourced variable cost models. Boston and San Francisco clusters anchor preclinical capacity expansion with dedicated vivarium and analytical testing facilities.
Germany
EMA clinical trial regulation harmonization positions German facilities as pan-European infrastructure hubs for multi-country studies. REACH compliance requirements for chemical safety testing elevate demand for GLP-certified analytical laboratories. The Rhine-Main and Munich biotech corridors concentrate cell therapy manufacturing investments from international sponsors.
Switzerland
Swissmedic alignment with EMA standards enables seamless regulatory qualification for EU-targeted commercialization programs. Federal tax incentives for R&D infrastructure depreciation attract dedicated facility investments from global pharmaceutical sponsors. Basel and Zurich anchor specialized bioproduction capacity serving cell and gene therapy pipelines.
India
CDSCO regulatory pathway streamlining for bioanalytical testing creates infrastructure investment opportunities relative to domestic generic API scale. Production-Linked Incentive schemes for pharmaceutical manufacturing extend toward specialized laboratory services. Hyderabad and Bangalore clusters develop GLP-compliant toxicology capacity for export-oriented contract research.
China
NMPA clinical trial data acceptance reforms accelerate infrastructure qualification for multinational sponsor programs. Dual carbon goals reshape facility energy specifications and environmental monitoring system investments. Shanghai and Suzhou biotech parks concentrate genomic sequencing instrument clusters for CRISPR and single-cell platform deployment.
Life Science R&D Infrastructure Outsourcing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of spanning discovery through commercialization. Tiered competitive dynamics separate full-service infrastructure conglomerates from specialized modality-focused operators. Three archetypes dominate: integrated clinical-to-commercial platforms, preclinical laboratory specialists, and cell therapy manufacturing pure-plays. Capacity expansion and strategic partnership contracting represent the dominant competitive vectors as sponsors prioritize supply security over transactional flexibility.
Within the integrated platform tier, IQVIA and Labcorp occupy positions exemplifying real-world evidence network leverage for large-scale clinical trial site management. Charles River Laboratories anchors the preclinical specialist archetype with extensive vivarium and analytical testing infrastructure. Lonza represents the cell and gene therapy manufacturing pure-play model, extending bioproduction capabilities into emerging modalities through dedicated cleanroom suites and cryogenic logistics specialization.
| Leading Market Players |
|---|
| IQVIA |
| Labcorp |
| Charles River Laboratories |
| Parexel International Corporation |
| ICON plc |
| Syneos Health |
| Lonza |
| Thermo Fisher Scientific |
| Eurofins Scientific |
| Others |
Value Network & Pricing Analysis
Frankfurt-to-Boston cryogenic logistics corridors carry 40% cost premiums for cell therapy shipments, concentrating supply power among German-Swiss OEM equipment clusters while forcing sponsor price differentiation between GLP-certified and standard analytical tiers.
Pricing Analysis
Certification level creates the primary spread between premium FDA-audited facilities and standard ISO-compliant operations. Three-tier pricing structure across premium, standard, and economy levels reflects audit history depth and equipment qualification documentation density. Cost compression in economy-tier chromatography services is intensifying because mid-cap biotech sponsors prioritize instrument access over bundled convenience. Biotechnology firms exhibit highest price sensitivity due to venture funding cycles, while pharmaceutical companies accept premium positioning for multi-continent redundancy.
Supply Chain Analysis
Lonza, Charles River Laboratories, and IQVIA hold concentrated contract manufacturing capacity across United States, Germany, and Switzerland. Chromatography skids and single-use bioreactor systems draw from limited German and Swiss OEMs, creating input bottlenecks for facility expansion. Single-source vulnerability runs through cryogenic logistics providers serving cell therapy cold chains. Distribution runs through sponsor procurement teams unbundling analytical testing from integrated discovery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Life science R&D infrastructure outsourcing is entering a cyclical recovery phase as FDA and EMA audit intensification forces sponsor conversion from fixed to variable cost models.
For Market Incumbents: Entrench position through multi-year strategic partnerships with guaranteed capacity allocations and co-investment in AI-validated laboratory automation. Backward integration into cloud-native LIMS development counters emerging software-native competitors. Certification investment in CDSCO-aligned Indian facilities defends against price pressure from emerging regional operators. For New Entrants and Emerging Players: CDSCO-aligned bioanalytical testing infrastructure in Hyderabad and Bangalore represents the most penetrable entry point given underdeveloped capacity relative to domestic generic API scale. AI-assisted assay validation platforms offer differentiation against legacy providers with paper-based batch records. Go-to-market through mid-cap biotechnology sponsors with compressed IND timelines prioritizes speed over bundled service relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical parent companies divesting captive laboratory footprints to convert fixed costs. Long-term viability rests on providers integrating discovery-through-commercialization platforms with regulatory inspection readiness. Watch FDA warning letter frequency as inflection indicator for quality-system differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership Contracting | Multi-year dedicated facility arrangements with Lonza and IQVIA capture margin pools unavailable in transactional work. |
| AI-Validated Laboratory Automation | Machine learning-based assay validation compresses analytical turnaround times for FDA inspection readiness. |
| CDSCO-Aligned Facility Investment | Production-Linked Incentive schemes in India extend toward GLP-compliant toxicology capacity for export markets. |
| Cloud-Native LIMS Migration | Real-time dashboard visibility digitizes capacity planning across distributed site networks for sponsor right-sizing. |
| EMA Clinical Trial Regulation Harmonization | Single qualification for pan-European deployment eliminates redundant national inspections for central laboratories. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA warning letters, EMA inspection databases, ClinicalTrials.gov infrastructure disclosures, and SEC 10-K facility capital expenditure filings. Interviews with drug development executives, regulatory affairs leads, GLP study directors, and CRO procurement managers informed demand-side assumptions. Bottom-up triangulation across service type, technology platform, and project size segmentation validates top-down market sizing from sponsor R&D expenditure flows.
Forecast inputs span laboratory services, data management, clinical trials, and preclinical research infrastructure with technology dimensions including genomic sequencing, bioinformatics tools, laboratory automation, and analytical instruments. Modeled variables encompass project scale from discrete analytical campaigns through strategic partnerships, end-user segmentation across pharmaceutical, biotechnology, academic, and CRO channels, and regional regulatory cluster alignment. CAGRs derive from sponsor pipeline stage advancement rates and facility capacity utilization trends across the projection horizon.
Practitioners should monitor FDA and EMA inspection frequency shifts, cell therapy pipeline advancement rates, and AI validation guidance evolution for early signals requiring forecast revision. Equipment supplier concentration among German and Swiss OEMs, specialized labor scarcity in GLP-certified roles, and chain-of-custody documentation burden escalation constitute primary risk factors. Quarterly review of CDSCO regulatory pathway streamlining progress and sponsor unbundling behavior is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Health Economics and Outcomes Research (HEOR) Services Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Asia-Pacific Computer-Aided Drug Discovery Market
Medical Research
Europe AMH Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Global Human Liver Models Market
Medical Research
Cancer Mouse Models Market
Medical Research
Placenta Market
Medical Research
Preventive Medicine Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market
Medical Research
Human Osteoblasts Market
Medical Research
Medical Device Contract Research Organization Market
Medical Research
Epigenetics Market
Medical Research
Chromatin Immunoprecipitation Sequencing Market
Medical Research
US Academic Medical Centers Market