
 Healthcare BI Market | 2026-2036
Healthcare BI Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare BI Market Outlook
Cloud-native architecture is pivoting Healthcare BI economics away from legacy on-premise installations toward subscription-based delivery models. Microsoft Corporation leverages its Azure cloud footprint to anchor enterprise health system contracts. Oracle Corporation sustains database-layer dominance through backward integration into clinical data repositories. SAP SE competes on financial analytics specialization, embedding cost-accounting modules that align with hospital ERP workflows.
Healthcare business intelligence encompasses software platforms that aggregate, analyze, and visualize clinical, operational, and financial data from disparate health information systems, typically processing structured and unstructured data through ETL pipelines, data warehouses, and machine learning inference layers to support decision-making. Its primary commercial purpose is enabling health organizations to reduce cost variability, improve clinical outcomes, and meet regulatory reporting obligations. Analytics software and visualization platforms lead product-type revenue generation, while cloud-based and SaaS deployment modes capture the fastest expansion as health systems shed capital-intensive infrastructure. Operational efficiency and patient analytics applications concentrate margin pools where outcomes-based contracting creates recurring analytics dependencies.
FDA interoperability mandates, HIPAA security requirements, and ONC certification standards collectively shape product roadmaps, forcing vendors to embed consent management, audit logging, and standardized APIs as core features rather than aftermarket modules. The EU AI Act and GDPR add compliance layers for vendors serving European health systems, constraining automated clinical decision support deployments. Stakeholders must monitor whether emerging federal data-blocking enforcement in the United States accelerates platform consolidation or fragments analytics across point solutions.
Market Dynamics
Cloud-native architecture is compressing capital expenditure cycles for hospital systems while FDA interoperability mandates force vendors toward open API frameworks that erode proprietary data lock-in.
Growth Catalysts
- Interoperability Mandates:The FDA's 21st Century Cures Act requires standardized data exchange, compelling health systems to replace siloed legacy systems with integrated analytics platforms.
- Cloud Migration:Hospital IT departments are accelerating SaaS adoption to shed on-premise infrastructure maintenance burdens and redirect capital toward clinical programs.
- Outcomes-Based Contracting:Payers are tying reimbursement to measurable quality metrics, creating recurring demand for real-time performance analytics across acute and ambulatory networks.
Market Restraints
- Data Fragmentation:Disparate EHR systems across acquired hospital networks resist standardization, inflating integration costs and delaying analytics deployment timelines.
- Cybersecurity Exposure:HIPAA breach penalties and ransomware targeting of health data create liability thresholds that slow cloud migration for risk-averse institutions.
- Talent Scarcity:Health informatics specialists with dual clinical and data engineering expertise command premium compensation, constraining vendor delivery capacity.
Strategic Opportunities
- Rural Health Networks:Federally qualified health centers in underserved regions lack analytics infrastructure, creating whitespace for cloud-native platforms with simplified deployment models.
- Genomic Data Integration:Converging clinical BI with bioinformatics pipelines enables precision medicine analytics that pharmaceutical sponsors will subsidize.
- EU AI Act Compliance:Automated clinical decision support vendors can capture European market share by embedding explainability and human oversight features ahead of enforcement deadlines.
Industry Challenges
- Legacy System Entrenchment:Decades-old data warehouses and proprietary reporting tools resist retirement, forcing expensive middleware layers that degrade query performance.
- Change Management Resistance:Clinical workflows hardened through years of EHR optimization create user adoption friction that analytics vendors must address through embedded training.
- Real-Time Data Latency:Streaming analytics from bedside devices and wearables strains ingestion architectures, requiring infrastructure investments that compress vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare BI Market |
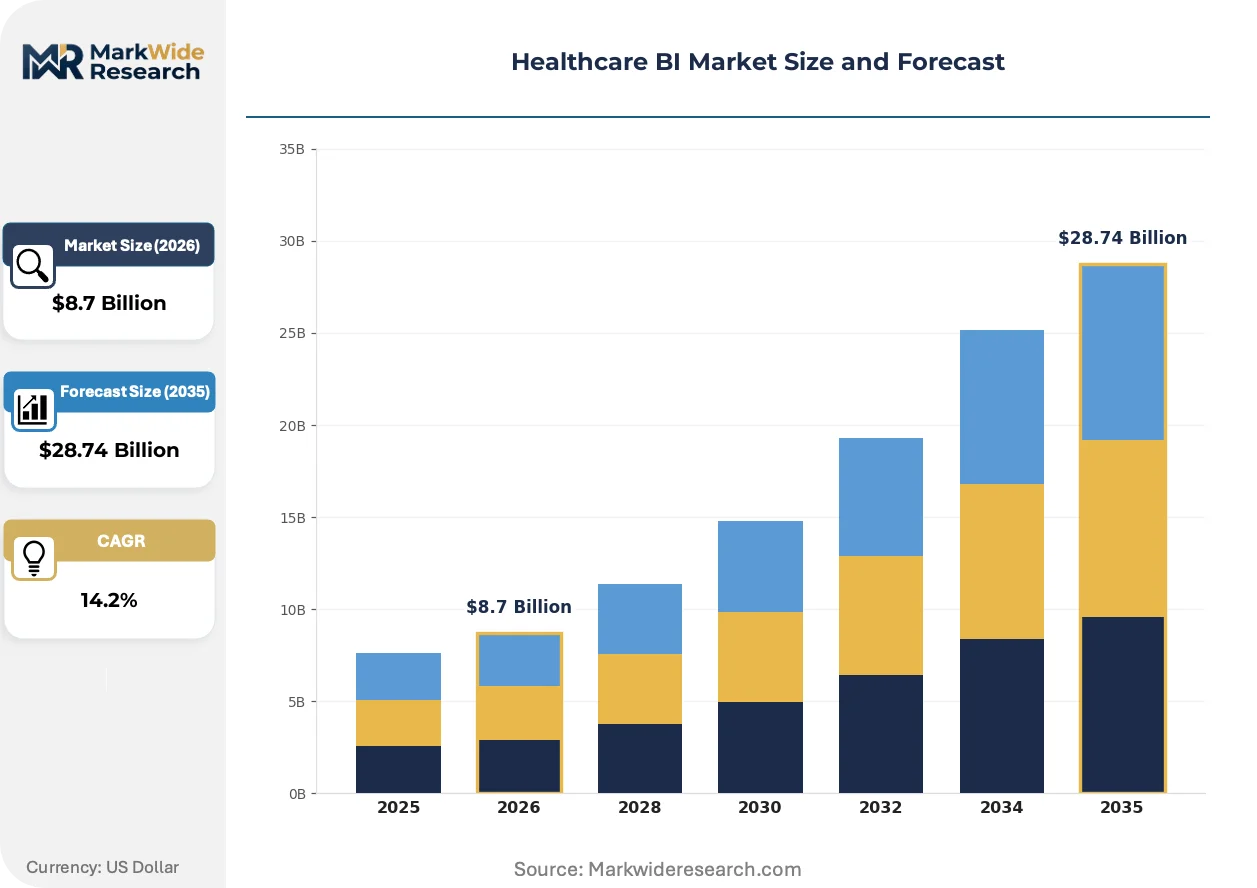
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reporting Tools, Analytics Software, Visualization Platforms, Dashboard Solutions End User: Hospitals, Physician Practices, Research Organizations, Payers Deployment: On-premise, Cloud-based, Hybrid, SaaS Application: Operational Efficiency, Patient Analytics, Financial Management, Quality Improvement |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, SAS Institute Inc., Tableau Software, Qlik Technologies, Inc, Infor, Inc, MicroStrategy Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare BI Market Strategic Shifts
Natural language processing and federated learning architectures are redrawing competitive boundaries in healthcare analytics, while regulatory pressure on algorithmic transparency accelerates vendor differentiation around explainability.
Generative AI for clinical documentation is overtaking traditional NLP pipelines in health system procurement cycles. Epic Systems and Cerner clients are piloting ambient listening tools that auto-populate EHR fields. This capability is compressing documentation burdens and enabling analytics vendors to capture workflow automation budgets previously held by scribe services.
The EU AI Act's risk classification framework for medical software is forcing vendors to reengineer automated diagnostic suggestions as decision-support rather than autonomous outputs. High-risk algorithmic tools now require conformity assessments that add months to European market entry. German and French hospital procurement committees are prioritizing vendors with established notified body relationships.
Subscription pricing for analytics modules is displacing perpetual license structures in US integrated delivery network RFPs. Chief financial officers prefer operational expenditure treatment that aligns software costs with utilization. This shift is most visible in California and Texas health systems where capital allocation committees have frozen infrastructure investments through 2026.
Healthcare BI Market Segmentation
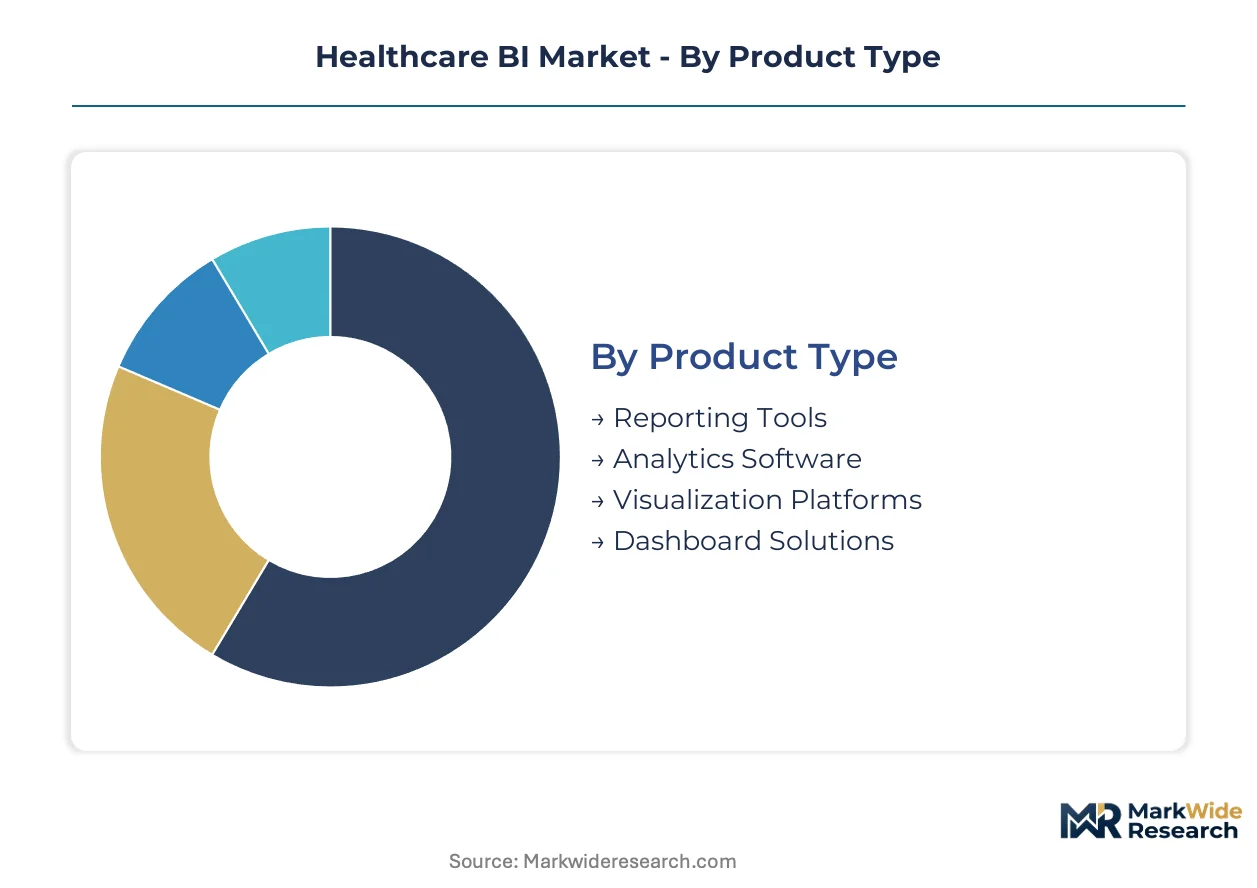
Healthcare BI segmentation reveals how regulatory compliance burdens, infrastructure maturity, and clinical workflow integration shape procurement decisions across health system archetypes. Vendors must align certification requirements with segment-specific deployment constraints to capture recurring revenue pools.
Product Type:
FDA 21st Century Cures Act interoperability mandates and ONC certification standards impose distinct compliance loads across product categories, with visualization platforms facing lighter conformance burdens than clinical decision support modules.
- Analytics Software:Core platforms processing structured and unstructured data through ETL pipelines and machine learning inference layers. Demand concentrates in US integrated delivery networks seeking unified patient views across acute and ambulatory settings, driven by outcomes-based contracting requirements. FDA interoperability mandates force embedded API frameworks that erode proprietary data lock-in.
- Visualization Platforms:Dashboard and reporting interfaces rendering clinical, operational, and financial metrics for executive consumption. Hospital CFOs in California and Texas health systems prefer subscription pricing that aligns software costs with utilization, freezing capital allocation for infrastructure through 2026.
- Reporting Tools:Standardized output generators for regulatory submissions and quality measure documentation.
- Dashboard Solutions:Real-time monitoring interfaces aggregating bedside device streams and wearable data.
Leading the category by volume: Analytics Software. Growing fastest: Visualization Platforms.
End User:
Customer scale determines pricing architecture, with enterprise health systems commanding volume discounts while rural networks absorb premium per-seat rates for simplified deployment models.
- Hospitals:Acute care facilities and integrated delivery networks with complex multi-EHR environments. Epic Systems and Cerner clients dominate US procurement cycles, piloting ambient documentation tools that compress analytics vendor margins through workflow automation bundling.
- Payers:Insurance organizations tying reimbursement to measurable quality metrics. United States commercial payers and Medicare Advantage plans create recurring demand for real-time performance analytics across provider networks.
- Physician Practices:Ambulatory settings with lighter IT infrastructure and tighter budget constraints.
- Research Organizations:Academic medical centers and pharmaceutical sponsors requiring genomic data integration and precision medicine analytics.
Hospitals anchor procurement volume. Payers are expanding most quickly as risk-bearing entities multiply.
Deployment:
Architecture choice dictates capital expenditure treatment and cybersecurity exposure profiles, with cloud-native options compressing implementation timelines but triggering HIPAA breach liability thresholds.
- Cloud-based:Vendor-managed infrastructure eliminating on-premise maintenance burdens. US hospital IT departments accelerate adoption to redirect capital toward clinical programs, though ransomware targeting of health data creates adoption friction for risk-averse institutions.
- SaaS:Subscription-delivered analytics modules displacing perpetual license structures in RFPs. Chief financial officers prefer operational expenditure treatment that aligns costs with utilization.
- On-premise:Legacy installations persisting in security-sensitive environments with dedicated compliance teams.
- Hybrid:Mixed architectures preserving sensitive data locally while leveraging cloud compute for non-clinical workloads.
Cloud-based deployments dominate new implementations. SaaS is gaining share fastest as CFOs freeze infrastructure investments.
Application:
Use case prioritization reflects margin pressure intensity, with financial management modules embedding cost-accounting logic that aligns with hospital ERP workflows.
- Operational Efficiency:Analytics reducing cost variability across supply chain, staffing, and capacity utilization. Oracle Corporation sustains database-layer dominance through backward integration into clinical data repositories serving this use case.
- Patient Analytics:Clinical outcome prediction and population health stratification. Microsoft Corporation leverages Azure cloud footprint to anchor enterprise contracts for longitudinal patient views.
- Financial Management:Revenue cycle optimization and cost-accounting alignment with ERP systems.
- Quality Improvement:Regulatory reporting and measure attainment for value-based programs.
Operational Efficiency leads by deployment volume. Patient Analytics shows the steepest expansion trajectory as outcomes-based contracting deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States integrated delivery networks concentrate demand for unified patient analytics across acute and ambulatory settings, while European health systems prioritize GDPR-compliant platforms and Asian markets accelerate cloud migration for cost efficiency.
United States
Hospital systems in California and Texas freeze capital allocation for infrastructure through 2026, redirecting budgets toward clinical programs and SaaS analytics modules. FDA 21st Century Cures Act interoperability mandates compel replacement of siloed legacy systems with open API frameworks. The Greater Boston cluster anchors precision medicine analytics development, with academic medical centers piloting genomic data integration for pharmaceutical-sponsored research.
Germany
Hospital procurement committees in Baden-Württemberg and Bavaria prioritize vendors with established notified body relationships under the EU AI Act's risk classification framework. German health informatics specialists command premium compensation, constraining vendor delivery capacity for automated clinical decision support deployments. The Rhine-Ruhr metropolitan region concentrates operational efficiency analytics demand from large hospital networks seeking ERP-aligned cost-accounting modules.
United Kingdom
NHS integrated care systems generate recurring demand for real-time performance analytics as outcomes-based contracting deepens across provider networks. NHS Digital interoperability standards push vendors toward standardized APIs that erode proprietary data lock-in. London's health tech cluster attracts cloud-native platform deployments targeting operational efficiency in acute care trusts.
India
Corporate hospital chains in Maharashtra and Karnataka accelerate adoption of subscription-based analytics to avoid capital-intensive infrastructure investments. CDSCO medical device regulations and the Digital Personal Data Protection Act shape product roadmaps for clinical decision support vendors. The Hyderabad-Bengaluru corridor concentrates health informatics talent pools that global vendors tap for delivery capacity expansion.
Australia
State health departments in New South Wales and Victoria prioritize cybersecurity-hardened cloud architectures following high-profile ransomware incidents targeting health data. TGA software as a medical device guidance constrains automated diagnostic suggestions to decision-support rather than autonomous outputs. The Melbourne-Sydney corridor anchors Asia-Pacific regional headquarters for multinational analytics vendors serving public hospital networks.
Healthcare BI Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors commanding premium pricing in integrated delivery networks while niche analytics providers capture rural health whitespace. The vendor base organizes around three strategic archetypes: cloud hyperscalers leveraging infrastructure dominance, database incumbents defending data-layer positions, and visualization specialists embedding workflow automation. Competitive intensity concentrates on M&A activity targeting clinical data repository assets and strategic partnerships with EHR vendors for workflow integration.
Within the cloud-hyperscaler tier, Microsoft Corporation and Oracle Corporation exemplify divergent defensive strategies—Microsoft leverages Azure footprint to anchor enterprise health system contracts, while Oracle sustains database-layer dominance through backward integration into clinical repositories. SAP SE occupies a position within the ERP-anchored analytics segment, embedding cost-accounting modules that align with hospital financial workflows. These three entities collectively represent the competitive frontier where infrastructure scale meets clinical workflow integration.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| SAS Institute Inc. |
| Tableau Software |
| Qlik Technologies, Inc |
| Infor, Inc |
| MicroStrategy Incorporated |
| Others |
Value Chain & Pricing Dynamics
Backward integration into clinical data repository assets anchors both supply security and pricing power for enterprise healthcare BI vendors, as FDA 21st Century Cures Act interoperability mandates force health systems toward platforms with captive ETL pipeline control rather than modular point solutions.
Pricing Analysis
Volume concentration in integrated delivery networks splits sharply from margin capture in specialized modules. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ONC certification tier and embedded API framework complexity. Pricing pressure stems from CFO-mandated operational expenditure treatment that compresses upfront licensing revenue. Rural health networks exhibit highest price sensitivity, while academic medical centers absorb premium rates for genomic data integration capabilities.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in United States, Ireland, and Singapore data center regions. Software development draws from health informatics talent pools in India, Poland, and the United States, while specialized GPU compute for machine learning inference rests on Taiwan and South Korea semiconductor supply. Tariff exposure on cross-border data transfers creates regulatory friction for European deployments. Distribution runs through direct enterprise sales teams and strategic partnerships with Epic Systems and Cerner implementation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare BI functions as a cost-of-compliance market where FDA 21st Century Cures Act certification requirements erect barrier-to-entry moats that favor incumbents with established interoperability frameworks and audit-ready infrastructure.
For Market Incumbents: Acquire clinical data repository assets to deepen ETL pipeline control and defend against cloud-hyperscaler encroachment. Embed consent management and audit logging as native architecture rather than aftermarket modules to preempt ONC enforcement actions. Prioritize backward integration into genomic data pipelines serving pharmaceutical-sponsored research networks. For New Entrants and Emerging Players: Capture federally qualified health center whitespace through simplified cloud-native deployment models that bypass capital allocation committee approvals. Target rural health networks in Texas and California with subscription pricing aligned to utilization. Lead with ambient documentation automation that bundles analytics workflow capture previously held by scribe services. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by EHR vendors seeking analytics layer integration and by cloud hyperscalers anchoring healthcare vertical specialization. Long-term viability favors platforms with established FDA interoperability certification and recurring SaaS revenue above project-based implementation fees. Monitor federal data-blocking enforcement intensity as inflection signal for platform consolidation versus point-solution fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interoperability Certification | ONC-compliant API frameworks unlock health system procurement eligibility under 21st Century Cures Act mandates. |
| Hospital System Partnership | Epic Systems and Cerner workflow integration secures embedded analytics placement in clinical documentation streams. |
| Cloud Infrastructure Partnership | Azure or AWS co-sell agreements redirect hospital IT capital budgets toward vendor-managed subscription models. |
| Genomic Data Pipeline Acquisition | Precision medicine analytics capabilities attract pharmaceutical sponsor subsidies and research organization contracts. |
| EU AI Act Conformity Assessment | Established notified body relationships accelerate German and French hospital procurement committee approvals. |
Study Parameters
Multi-period observation of hospital procurement database trends and GPO contract structures anchored the trend analysis, supplemented by interviews with hospital CIOs, health informatics directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare cost report data, ONC certification records, and hyperscaler healthcare vertical revenue disclosures. Bottom-up health system deployment tracking triangulated against top-down vendor revenue segmentation.
Segment-weighting across deployment model, organization size, application use case, and regional regulatory cluster shaped the analytical framework. CAGRs derived from fitted trend extrapolation with cross-validation against historical technology adoption curves. Forecast inputs incorporated EHR vendor implementation timelines and federal interoperability enforcement intensity across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal data-blocking enforcement, ransomware targeting frequency, and EU AI Act implementation rigor. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Laboratory Information System Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
Allergy Care Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Healthcare Natural Language Processing Market