
 Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market | 2026-2036
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market Foresight
Platform modularization is rebalancing buyer choice in NLP healthcare suites as vendors unbundle clinical documentation, genomic analysis, and drug discovery modules into separately licensable components. Microsoft leverages its cloud infrastructure to anchor enterprise deployments across hospital networks. Google competes through specialized large language models trained on biomedical corpora. Nuance Communications dominates clinical speech recognition with deep workflow integration into electronic health records.
Natural Language Processing in Healthcare and Life Sciences encompasses computational techniques that interpret, classify, and generate human language from unstructured clinical text, genomic literature, and patient-generated data using transformer architectures, named entity recognition, and semantic parsing. Its primary purpose is extracting actionable insights from medical records, trial protocols, and scientific publications to accelerate diagnosis, research, and regulatory submissions. Clinical documentation applications lead deployment volumes due to immediate labor cost reduction, while drug discovery represents the fastest-expanding segment as pharmaceutical companies apply text mining to identify novel therapeutic targets. Deep learning technology occupies the highest-margin tier within the technology stack, though machine learning maintains broader installed base penetration.
FDA guidance on AI-based software as a medical device, EMA's evolving framework for algorithmic clinical decision support, and HIPAA privacy requirements collectively shape product validation pathways and data handling standards for NLP vendors seeking market access. The EU AI Act introduces additional conformity obligations for high-risk healthcare AI applications, creating divergence in go-to-market strategies between jurisdictions. Stakeholders must monitor how regulatory fragmentation between FDA, EMA, and national health technology assessment bodies affects cross-border deployment economics and model retraining requirements.
Market Dynamics
Transformer architectures are compressing development cycles for clinical NLP applications while FDA and EMA guidance on AI-enabled software as a medical device forces vendors to rebuild validation pipelines around explainability requirements.
Growth Catalysts
- EMA algorithmic clinical decision support framework:The evolving European guidance creates compliance clarity that accelerates vendor market entry across EU member states.
- Pharmaceutical text mining:Drug discovery teams deploy named entity recognition systems to extract therapeutic targets from genomic literature at machine scale.
- United States health system digitization:Hospital networks allocate capital budgets toward clinical documentation automation to offset labor cost pressure.
Market Restraints
- GPU compute cost volatility:Training large language models on biomedical corpora requires sustained access to specialized semiconductor hardware subject to supply fluctuation.
- Training data concentration:Curated clinical text repositories cluster within academic medical centers in Boston, Stanford, and Heidelberg, creating access asymmetry.
- HIPAA de-identification technical limits:Current anonymization methods retain re-identification risk that constrains cross-institutional dataset pooling.
Strategic Opportunities
- Japan's pharmaceutical regulatory pathway:PMDA's structured dialogue mechanism for AI-based submissions offers first-mover positioning for compliant NLP platforms.
- Patient-generated health data integration:Wearable-derived unstructured text streams create new training corpora outside traditional electronic health record silos.
- Federated learning architectures:Distributed model training across hospital networks without centralizing sensitive records addresses data residency constraints.
Industry Challenges
- Clinical informaticist talent scarcity:The intersection of medicine, linguistics, and machine learning engineering produces candidate pools too shallow for vendor hiring targets.
- EHR workflow integration complexity:Legacy electronic health record systems require custom API development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market |
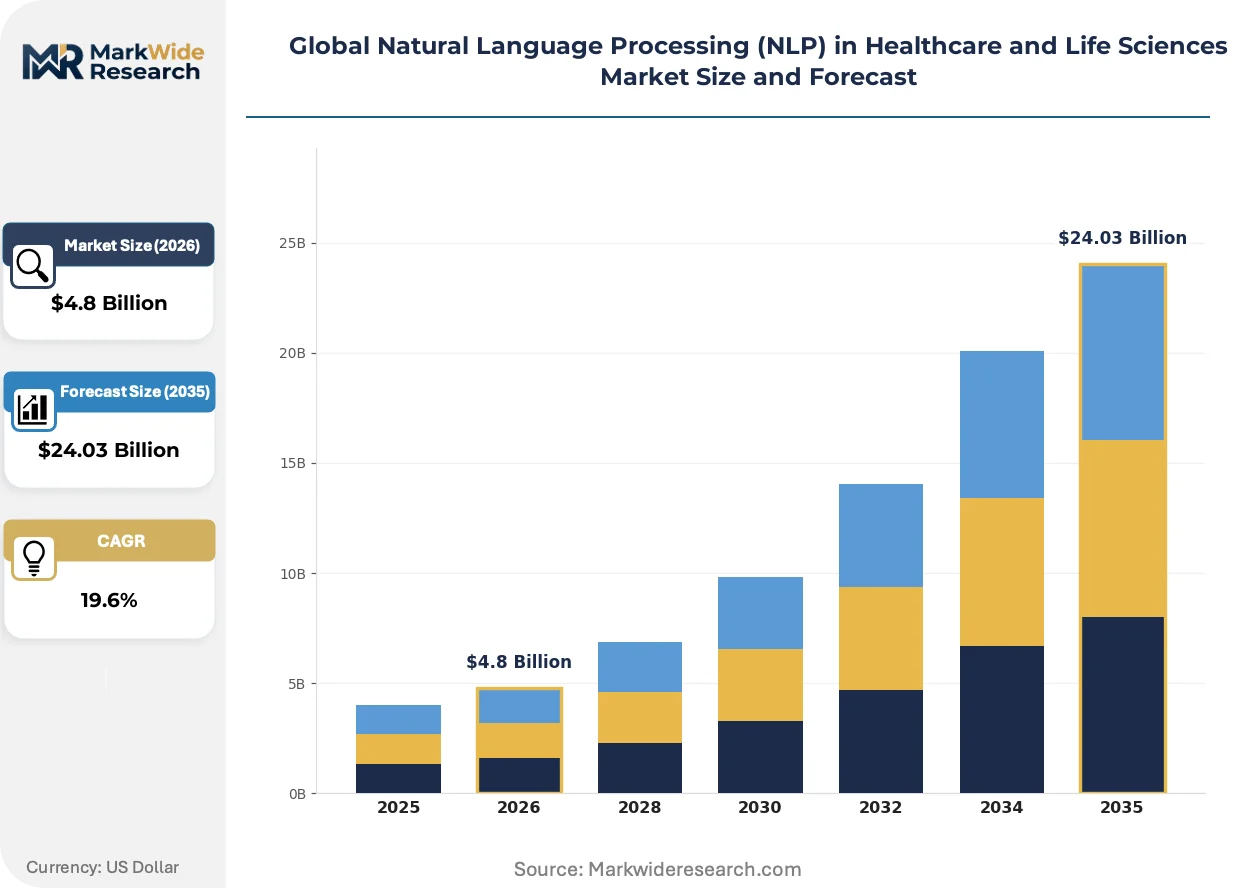
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $24.03 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Clinical Documentation, Patient Data Analysis, Drug Discovery, Medical Imaging Interpretation, Genomic Data Processing Technology: Machine Learning, Deep Learning, Speech Recognition, Text Mining, Sentiment Analysis End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms, Diagnostic Centers Deployment: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | IBM, Microsoft, Google, IQVIA, Amazon Web Services, Oracle, Cerner, Nuance Communications, Tempus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market Shifts & Advancements
Biomedical large language models are rewriting competitive boundaries between cloud infrastructure providers and specialized healthcare AI vendors. Three developments merit particular attention.
Transformer-based architectures trained on PubMed abstracts and clinical trial protocols are electrifying the speed at which pharmaceutical safety teams extract adverse event signals from unstructured case reports. Roche and Novartis have established dedicated computational linguistics units. The technology is compressing pharmacovigilance cycle times from quarterly to near-real-time monitoring.
EU AI Act conformity obligations for high-risk healthcare applications are forcing vendors to reengineer model documentation and risk management systems. The regulation's tiered classification scheme places clinical decision support tools in the highest scrutiny category. German hospital procurement offices now require CE marking plus algorithmic impact assessments before contract execution.
Hospital pharmacy departments are consolidating vendor relationships around platforms that bundle medication reconciliation with clinical documentation. The unbundling of point solutions into integrated suites is displacing standalone speech recognition contracts. This concentration is most visible in United States integrated delivery networks with centralized IT governance.
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market Segmentation
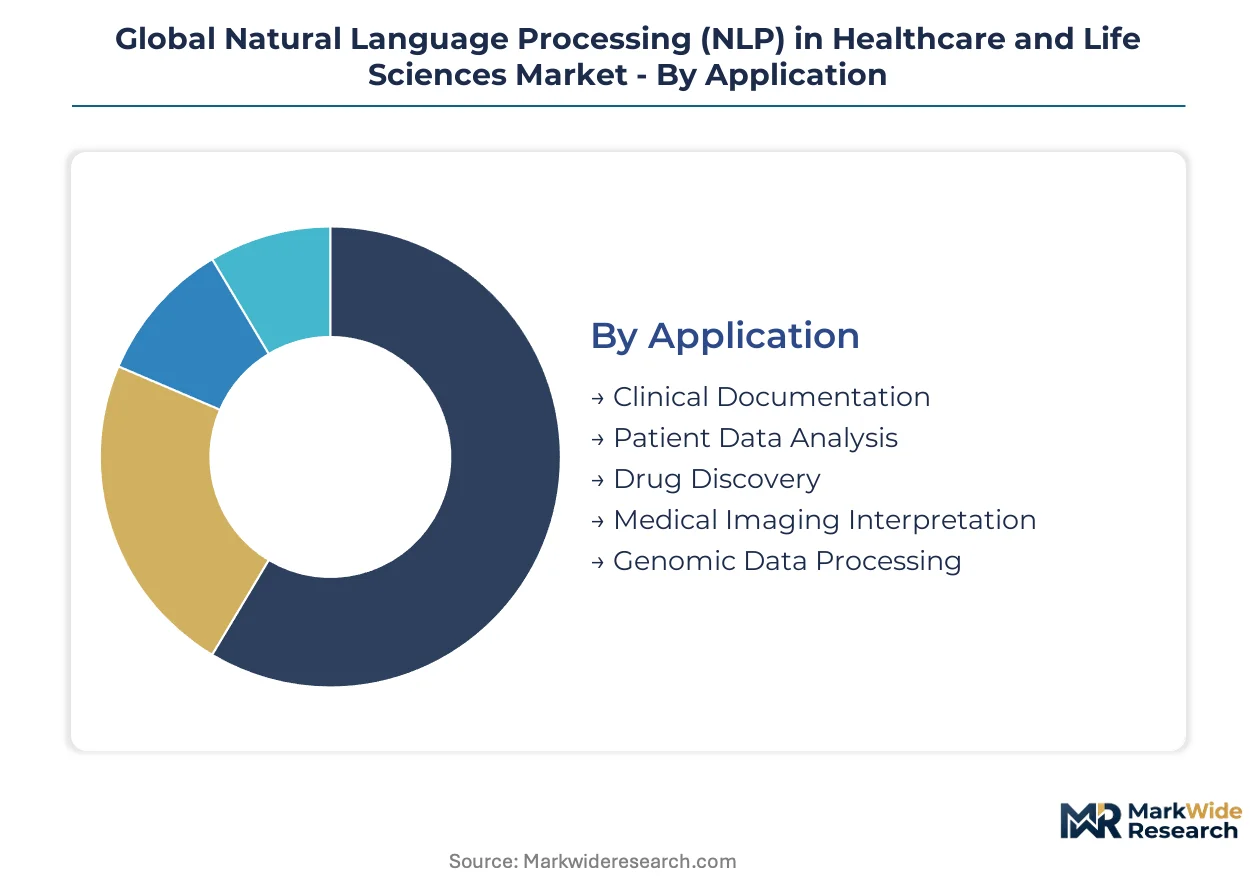
NLP healthcare vendors configure pricing and feature tiers around deployment complexity and clinical risk exposure. Segment boundaries shift as pharmaceutical companies absorb capabilities once reserved for hospital IT budgets.
Application:
Clinical documentation commands the largest installed base while drug discovery captures the highest per-seat licensing fees.
- Clinical Documentation:Speech-to-text engines transcribe physician-patient encounters into structured EHR fields, reducing administrative burden. United States hospital networks deploy these systems across emergency departments and ambulatory clinics where documentation backlogs accumulate fastest.
- Drug Discovery:Named entity recognition pipelines extract protein interactions and adverse event signals from biomedical literature and trial protocols. Roche and Novartis maintain dedicated computational linguistics units that compress pharmacovigilance cycles from quarterly to near-real-time monitoring.
- Patient Data Analysis:Unstructured nursing notes and discharge summaries feed predictive readmission models.
- Medical Imaging Interpretation:Radiology reports undergo semantic parsing to flag incidental findings requiring follow-up.
- Genomic Data Processing:Variant classification systems mine PubMed abstracts for pathogenicity evidence.
Today's leader: Clinical Documentation. Tomorrow's challenger: Drug Discovery.
Technology:
Deep learning architectures occupy premium pricing tiers while machine learning maintains broader penetration across legacy hospital infrastructure.
- Deep Learning:Transformer models trained on biomedical corpora achieve state-of-the-art performance in clinical entity extraction and relation classification. Google's Med-PaLM and specialized biomedical LLMs from academic medical centers in Boston and Heidelberg set performance benchmarks that justify per-query inference pricing.
- Machine Learning:Random forest and SVM classifiers power rule-based clinical decision support with deterministic, auditable outputs. German hospital procurement offices favor these systems for their explainability under EU AI Act documentation requirements.
- Speech Recognition:Acoustic models optimized for medical terminology enable real-time clinical dictation.
- Text Mining:Pattern-based extraction surfaces therapeutic targets from patent filings and trial registries.
- Sentiment Analysis:Patient forum scraping gauges treatment satisfaction and adverse event prevalence.
Deep learning is expanding most quickly. Machine learning retains the deepest footprint.
End User:
Pharmaceutical companies drive R&D-oriented contract values while hospitals anchor recurring subscription revenue.
- Pharmaceutical Companies:Safety and regulatory affairs teams deploy NLP for periodic benefit-risk assessment report generation and label expansion research. FDA submission timelines pressure these organizations toward validated, audit-ready text mining platforms.
- Hospitals:Chief medical information officers prioritize clinical documentation automation to offset nursing and physician labor cost inflation. United States integrated delivery networks with centralized IT governance consolidate vendor relationships around bundled platform contracts.
- Research Laboratories:Academic medical centers curate training corpora and benchmark novel architectures.
- Biotechnology Firms:Emerging drug developers license target identification pipelines without in-house computational linguistics capacity.
- Diagnostic Centers:Pathology and radiology practices apply report generation tools to standardize output formats.
Hospitals dominate current procurement. Pharmaceutical companies are climbing the fastest.
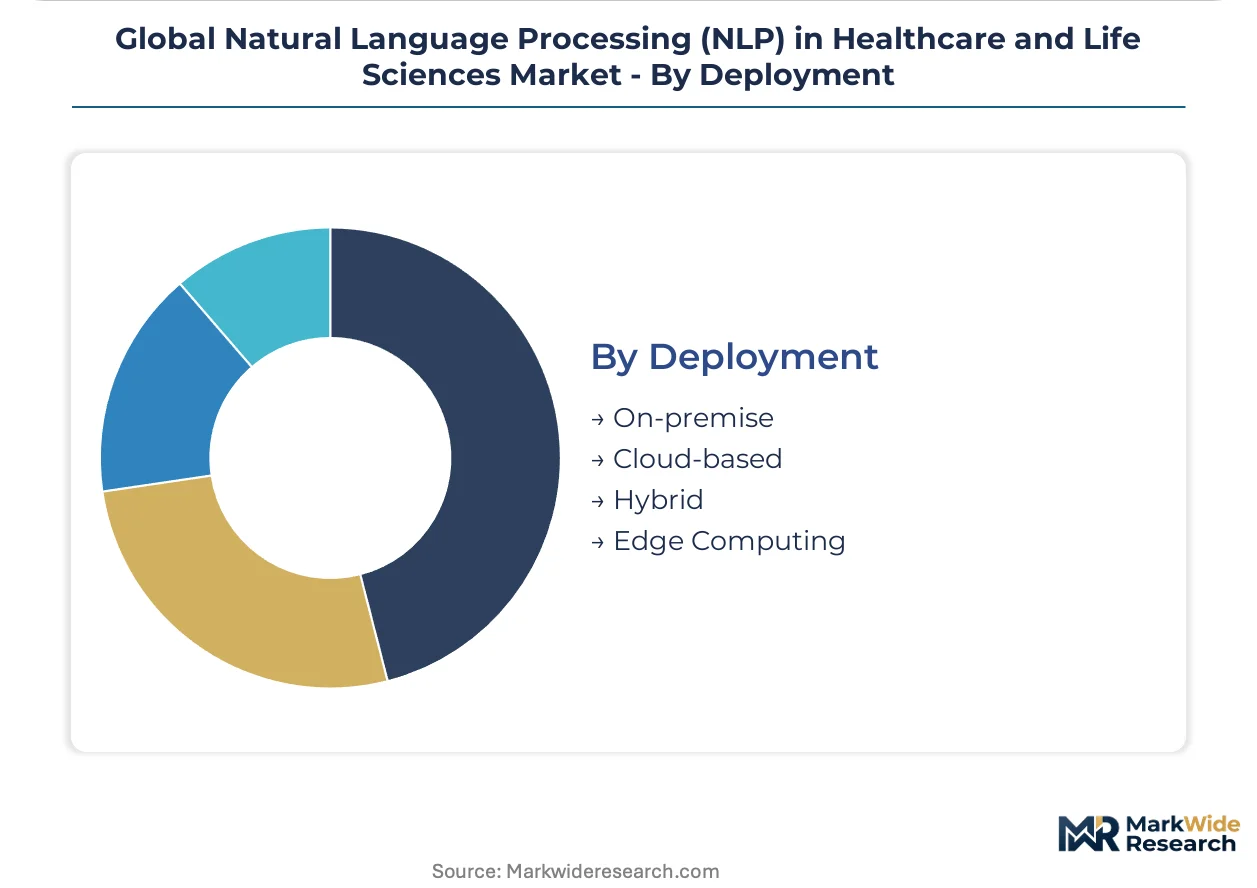
Deployment:
Cloud-based delivery captures new contract growth while on-premise installations persist where data residency requirements are strictest.
- Cloud-based:Microsoft Azure and Google Cloud host enterprise NLP workloads with auto-scaling inference capacity and pre-integrated security certifications. HIPAA Business Associate Agreements and EU GDPR compliance modules accelerate procurement timelines for multi-site hospital networks.
- Hybrid:Sensitive clinical data remains on-premise while model training and updates flow through cloud pipelines. German university hospitals favor this architecture to satisfy state-level data protection officers while accessing GPU clusters for periodic retraining.
- On-premise:Air-gapped installations serve military and national health service environments with classified or restricted patient populations.
- Edge Computing:Lightweight models deploy to point-of-care devices for offline clinical decision support.
Cloud-based deployment leads new bookings. Hybrid architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NLP healthcare applications first achieved commercial scale in the United States during the 2010s as hospital digitization mandates created structured data requirements. European and Japanese health systems subsequently adopted clinical documentation automation to address comparable physician workforce constraints.
United States
Hospital networks in the United States deploy clinical speech recognition at scale to offset nursing and physician administrative burden. FDA guidance on AI-based software as a medical device shapes vendor validation requirements for clinical decision support tools. The Boston-Stanford corridor concentrates academic medical centers that curate training corpora and benchmark novel transformer architectures.
Germany
German university hospitals favor hybrid cloud architectures to satisfy state-level data protection officers while accessing GPU clusters for periodic model retraining. EU AI Act conformity obligations force vendors to reengineer documentation and risk management systems for high-risk healthcare applications. The Heidelberg medical informatics cluster anchors computational linguistics research partnerships between academic hospitals and pharmaceutical safety teams.
Japan
Japanese pharmaceutical companies accelerate text mining adoption for drug discovery pipelines as PMDA's structured dialogue mechanism offers compliant pathways for AI-based submissions. METI funding programs support health system digitization budgets concentrated in Tokyo and Osaka metropolitan areas. The Kanto region hosts hospital networks consolidating vendor relationships around bundled platform contracts.
United Kingdom
United Kingdom hospital procurement offices prioritize clinical documentation automation to address National Health Service workforce pressures. NHS Digital interoperability standards influence vendor API development requirements for EHR workflow integration. The London-Oxford-Cambridge triangle concentrates biotechnology firms licensing target identification pipelines without in-house computational linguistics capacity.
Switzerland
Swiss pharmaceutical headquarters in Basel deploy named entity recognition systems for pharmacovigilance signal detection from multilingual case reports. Swissmedic guidance on algorithmic clinical decision support creates compliance clarity for vendor market entry. The Basel-Zurich corridor concentrates vendor relationships around platforms that bundle medication reconciliation with clinical documentation.
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market Competitive Landscape
The competitive structure tilts toward cloud infrastructure providers anchoring enterprise deployments across hospital networks. Microsoft leverages Azure's pre-integrated security certifications and HIPAA Business Associate Agreements to accelerate procurement timelines. Google competes through specialized large language models trained on biomedical corpora. Two strategic archetypes dominate: horizontal cloud platforms with healthcare verticalization, and specialized clinical workflow integrators. Dominant competitive moves include strategic partnerships with electronic health record vendors and technology licensing agreements for biomedical transformer architectures.
Within the cloud-platform tier, Microsoft and Google exemplify infrastructure-led positioning, while Nuance Communications occupies a position as the clinical speech recognition specialist with deep EHR workflow integration. IBM and Oracle sit within the enterprise software archetype, leveraging existing hospital IT relationships to bundle NLP capabilities into broader platform contracts. Amazon Web Services represents the scale-driven hyperscaler approach, offering auto-scaling inference capacity for pharmaceutical text mining workloads.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| IQVIA |
| Amazon Web Services |
| Oracle |
| Cerner |
| Nuance Communications |
| Tempus |
| Others |
Supply & Pricing Matrix
Horizontal cloud platform partnerships anchor supply positioning and pricing power for NLP healthcare vendors, as Microsoft and Google leverage pre-integrated security certifications to compress procurement timelines while commanding premium SaaS margins. This integration choice locks hospital networks into multi-year contracts that bundle inference capacity with compliance modules, insulating established providers from price erosion even as GPU compute costs fluctuate.
Pricing Analysis
Three-tier pricing structure across enterprise, professional, and developer levels dominates NLP healthcare licensing, with FDA validation tier and deployment scale serving as primary differentiation drivers. Cost compression in the developer tier intensifies because open-source biomedical transformers erode entry-level margins. Pharmaceutical safety teams exhibit lowest price sensitivity due to regulatory submission pressures, while independent diagnostic centers face acute budget constraints.
Supply Chain Analysis
Regional GPU cluster distribution through hyperscaler availability zones in the United States, Germany, and Japan shapes model training economics for biomedical transformer development. NVIDIA semiconductor supply draws from Taiwan and South Korea fabs, with single-source vulnerability concentrated in advanced node lithography. Distribution runs through cloud marketplace procurement channels that bundle HIPAA Business Associate Agreements with auto-scaling inference capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage positioning favors vendors establishing EU AI Act compliance infrastructure in Germany to capture premium pricing from hospital procurement offices, while maintaining training operations in the United States where academic medical center partnerships lower data access costs.
For Market Incumbents: Anchor enterprise relationships through deep EHR workflow integration that raises switching costs for hospital networks facing clinical informaticist talent scarcity. Defend against specialized biomedical LLM entrants by accelerating FDA software-as-medical-device validation pipelines. Prioritize backward integration into curated clinical text repositories at Boston and Stanford academic medical centers. For New Entrants and Emerging Players: Enter via federated learning architectures that address HIPAA de-identification limits constraining incumbents. Target biotechnology firms in the United Kingdom's London-Oxford-Cambridge triangle lacking in-house computational linguistics capacity. Lead with pharmacovigilance signal detection modules that compress quarterly monitoring cycles. For Investors and Strategic Acquirers: Roll-up economics work for clinical workflow integrators because EHR vendor fragmentation creates acquisition targets with sticky hospital relationships. Five-to-ten year viability hinges on FDA and EMA regulatory pathway expertise as compliance moats widen. Watch PMDA structured dialogue submission volumes as inflection signal for Japanese market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Validation | Accelerates hospital procurement timelines by satisfying AI-based clinical decision support requirements. |
| Biomedical Transformer Architecture Licensing | Enables pharmaceutical safety teams to extract adverse event signals from unstructured case reports. |
| Hospital Network Platform Integration | Consolidates vendor relationships around bundled medication reconciliation and clinical documentation modules. |
| Federated Learning Infrastructure Deployment | Addresses HIPAA data residency constraints while enabling cross-institutional model training. |
| EU AI Act Conformity Investment | Unlocks German hospital procurement requiring CE marking plus algorithmic impact assessments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chief medical information officers, pharmaceutical regulatory affairs leads, NLP platform engineers, and hospital GPO contracts managers with secondary validation against FDA 510(k) filings, EMA qualification opinions, ClinicalTrials.gov protocol registries, and hyperscaler healthcare cloud revenue disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation anchored value estimates.
Segment-weighting across application, technology, end user, and deployment dimensions structured the analytical framework over the projection horizon. CAGRs derived from modeled adoption curves weighted by health system digitization budget trajectories and pharmaceutical R&D pipeline text mining penetration. Industry-specific inputs included GPU cluster availability indices and regulatory guidance publication timelines.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around deployment velocity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Clinical Intelligence Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Global Ambulatory EHR Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Cat Allergy in Humans Market