
 North America Laboratory Information System Market | 2026-2036
North America Laboratory Information System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laboratory Information System Market Insights
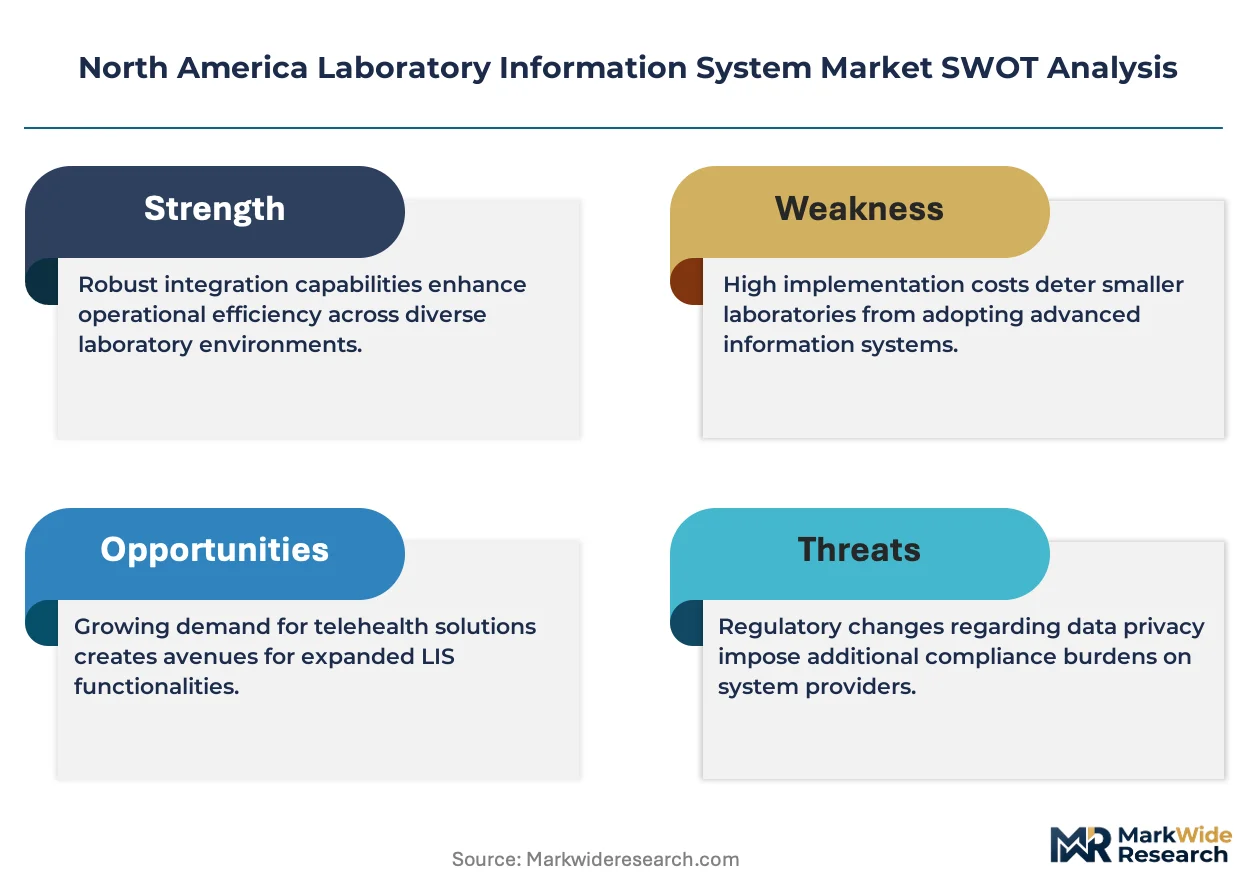
Federal interoperability mandates are collapsing the gap between basic LIS functionality and enterprise-grade clinical data exchange. Oracle leverages its Cerner acquisition to sustain dominance in hospital-anchored deployments across the United States. Thermo Fisher Scientific anchors its position through deep specialization in research laboratory workflows and scientific instrumentation integration. Epic Systems Corporation competes by extending its EHR-native LIS module into academic medical centers with captive pathology operations.
A Laboratory Information System constitutes software infrastructure that manages specimen tracking, test ordering, result reporting, and regulatory compliance documentation across clinical and research environments, typically interfacing with analytical instruments through HL7 or FHIR protocols. Cloud-based solutions represent the fastest-expanding deployment architecture as health systems prioritize remote accessibility and reduced capital expenditure, while on-premise installations retain preference in blood bank operations where data sovereignty requirements remain stringent. Research laboratories and microbiology labs constitute adjacent demand poles, with the former driving customization intensity and the latter generating recurring revenue through infectious disease surveillance mandates.
The Office of the National Coordinator for Health Information Technology enforces certification criteria that determine vendor eligibility for federal reimbursement programs, effectively gatekeeping market access for non-compliant platforms. FDA oversight of laboratory-developed tests intersects with LIS functionality in molecular diagnostics and precision medicine workflows, particularly under evolving framework guidance. State-level health information exchange authorities in California, Texas, and New York impose supplementary data-sharing protocols that fragment standardization efforts. Stakeholders must monitor pending CMS rulemaking on prior authorization automation and assess whether their platforms can absorb real-time eligibility verification without architectural overhaul.
Market Dynamics
Health system consolidation across the United States is compressing vendor margins while elevating enterprise-scale procurement requirements, forcing LIS providers to absorb integration costs that previously fell on hospital IT departments.
Growth Catalysts
- ONC Cures Act Final Rule:Information blocking provisions mandate interoperable data exchange, compelling diagnostic centers to upgrade from siloed legacy platforms.
- Cloud infrastructure maturation:Health systems in California, Texas, and New York are migrating core laboratory workflows to SaaS architectures to reduce capital expenditure cycles.
- Precision medicine expansion:Molecular diagnostics laboratories require LIS modules capable of managing complex biomarker tracking and companion diagnostic workflows.
Market Restraints
- FDA LDT oversight uncertainty:Evolving framework guidance for laboratory-developed tests creates compliance timeline risk for molecular diagnostics vendors.
- Legacy system entrenchment:Blood bank operations retain on-premise installations due to stringent data sovereignty requirements, slowing cloud migration in this segment.
- Specialized talent scarcity:Health informaticists with dual expertise in clinical laboratory operations and FHIR protocol implementation command premium compensation.
Strategic Opportunities
- Microbiology surveillance mandates:State health departments are expanding infectious disease reporting requirements, generating recurring revenue for LIS platforms with real-time epidemiological dashboards.
- Academic medical center pathology:Research-intensive institutions seek customizable modules integrating scientific instrumentation with clinical reporting workflows.
- Prior authorization automation:Pending CMS rulemaking on real-time eligibility verification creates white space for platforms architected to absorb payer integration without overhaul.
Industry Challenges
- HL7-to-FHIR migration complexity:Health systems with decades of HL7 interface investments face expensive recertification of existing instrument connections.
- Multi-site standardization friction:Consolidated hospital networks struggle to harmonize specimen tracking protocols across acquired facilities with divergent legacy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laboratory Information System Market |
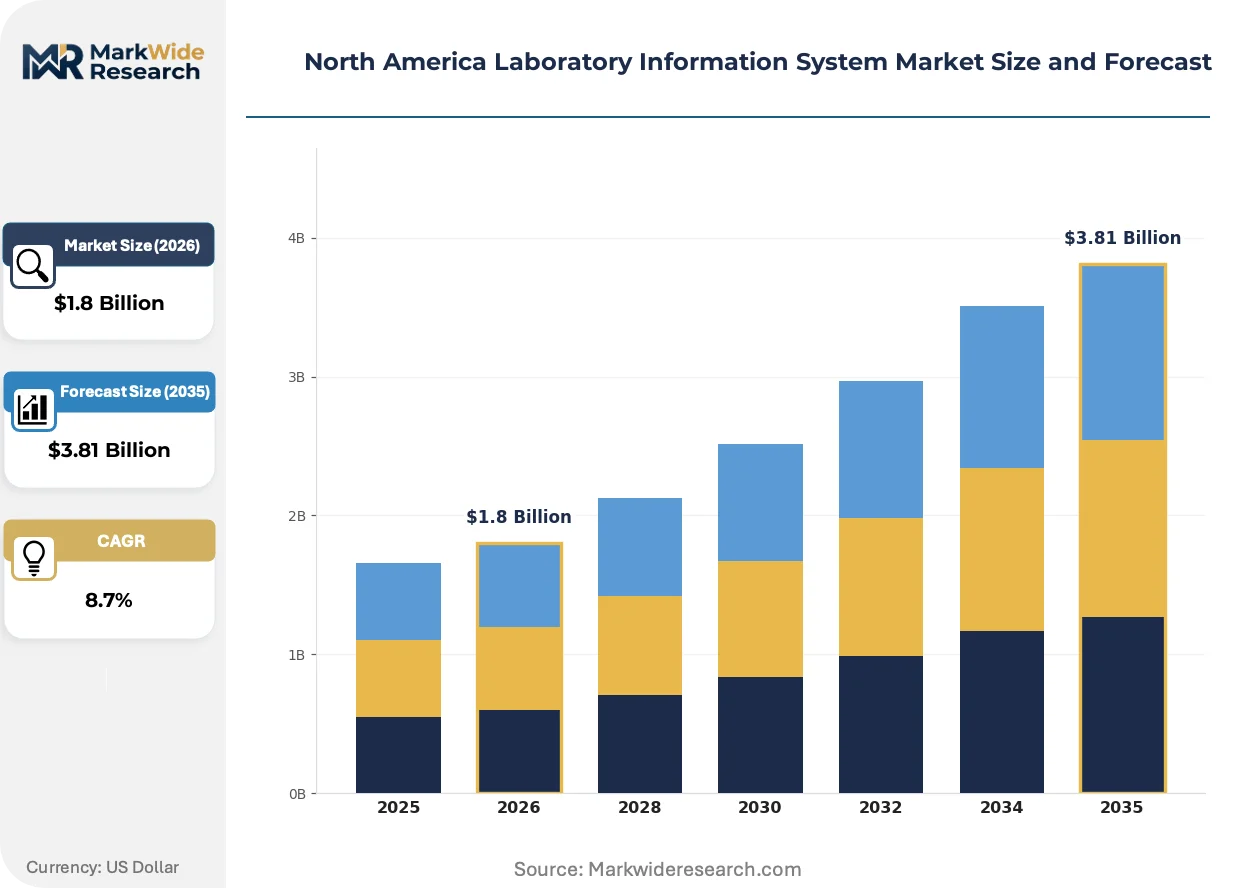
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
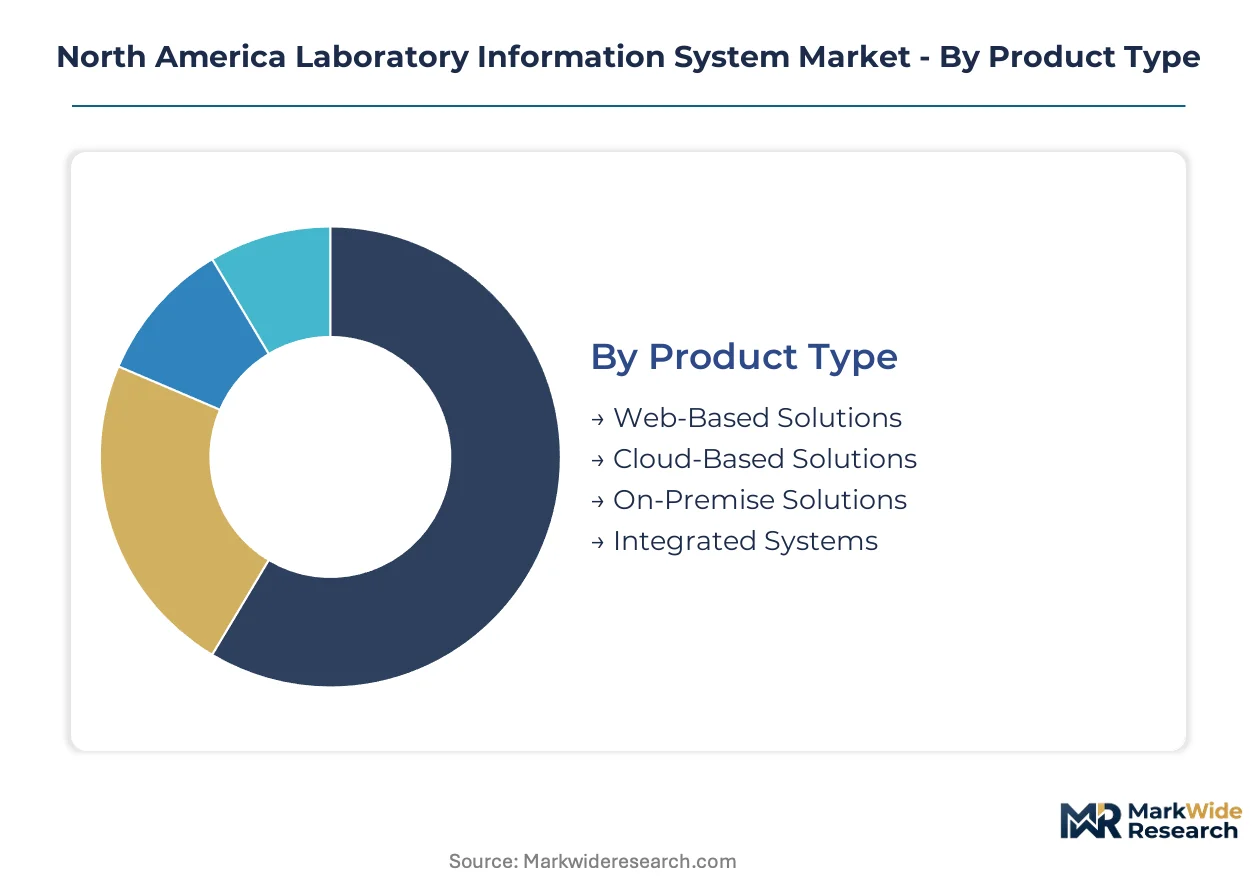
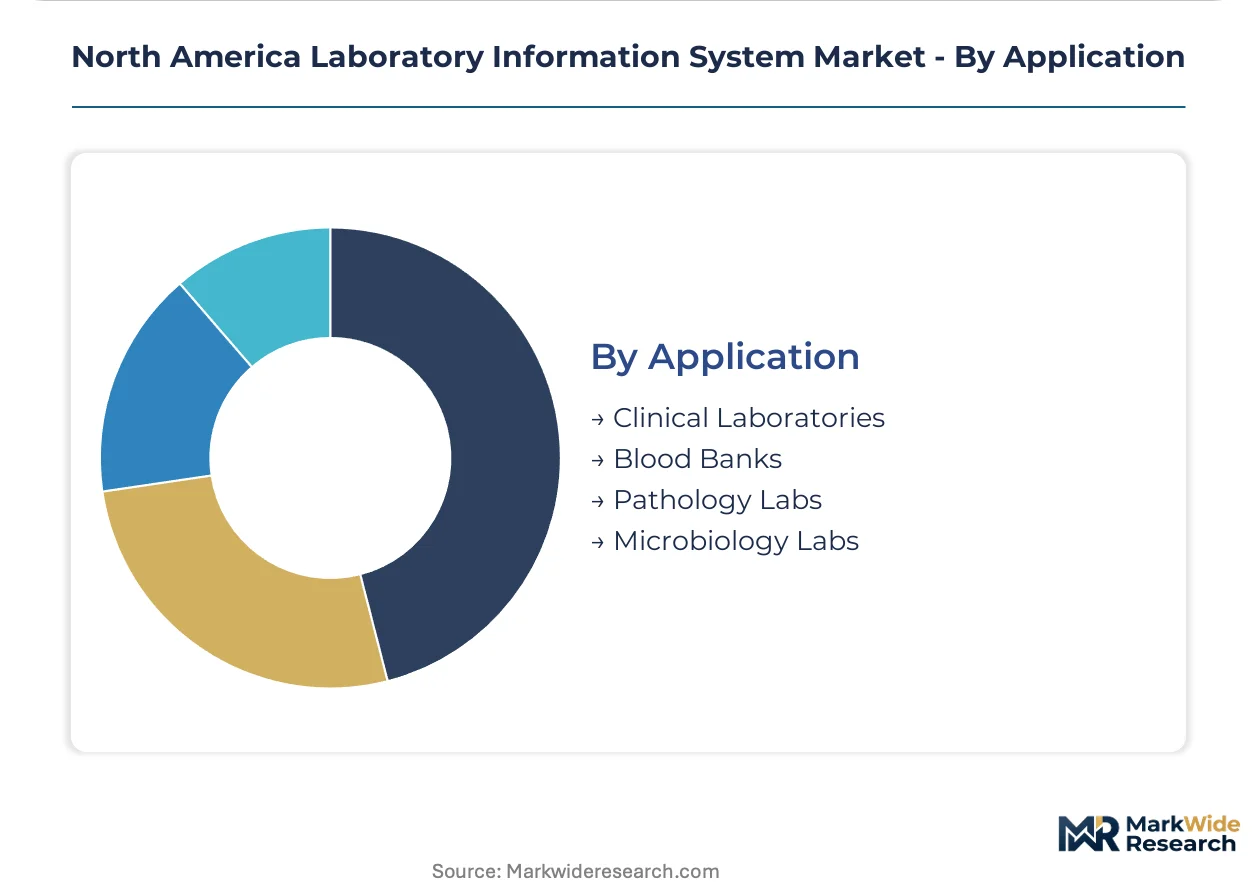
| Segmentation | Product Type: Web-Based Solutions, Cloud-Based Solutions, On-Premise Solutions, Integrated Systems End User: Hospitals, Diagnostic Centers, Research Laboratories, Academic Institutions Deployment: Hosted, SaaS, Client-Server, Hybrid Application: Clinical Laboratories, Blood Banks, Pathology Labs, Microbiology Labs |
| Companies Covered | Oracle (Cerner Corporation), Thermo Fisher Scientific Inc., XiFin, Inc., Orchard Software Corporation, Comp Pro Med Inc, Epic Systems Corporation, Sunquest Information Systems, Meditech, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laboratory Information System Market Trends and Innovations
FHIR-native architectures are collapsing the traditional boundary between laboratory operations and enterprise clinical data exchange, while regulatory pressure accelerates vendor consolidation around interoperable platforms.
Cloud-native LIS deployments are supplanting client-server installations in mid-sized health systems. Regional hospital networks with limited IT infrastructure are adopting subscription models to access enterprise-grade functionality without capital commitment. This shift is compressing the addressable market for on-premise license vendors and elevating recurring revenue multiples for SaaS-native competitors.
The Office of the National Coordinator for Health Information Technology certification criteria now gate federal reimbursement eligibility, reshaping vendor competitive positioning. Non-compliant platforms face exclusion from Medicare and Medicaid participation, forcing smaller vendors toward acquisition or partnership. Diagnostic centers in the United States are prioritizing ONC-certified solutions to protect revenue cycle integrity.
Subscription pricing models are displacing perpetual license structures in health system procurement. Hospital CFOs prefer operational expenditure classification for software investments, particularly in capital-constrained environments. This preference is most visible among independent diagnostic laboratories and specialty physician groups seeking predictable cost structures.
North America Laboratory Information System Market Segmentation
Laboratory Information System procurement in North America diverges sharply by operational scale and regulatory exposure, with enterprise health systems prioritizing integration depth while independent labs emphasize subscription flexibility. Understanding segment boundaries reveals where vendor margin compression intersects with buyer power concentration.
Product Type:
Cloud-based architectures flow predominantly through vendor-direct SaaS channels, while on-premise and integrated systems move through systems integrators and regional IT distributors serving consolidated hospital networks.
- Web-Based Solutions:Browser-accessible platforms with minimal local infrastructure requirements, typically deployed in small-to-mid-sized diagnostic centers. Demand concentrates in Texas and Florida independent laboratory networks seeking rapid deployment without capital commitment, constrained by limited offline functionality during connectivity disruptions.
- Cloud-Based Solutions:Fully managed SaaS architectures with automated updates and elastic compute scaling. California and New York health systems are migrating core workflows here fastest, driven by CFO preference for operational expenditure classification and reduced data center overhead.
- On-Premise Solutions:Locally installed software with dedicated server infrastructure, retaining preference in blood bank operations where data sovereignty requirements override cloud migration incentives.
- Integrated Systems:Unified platforms embedding LIS functionality within broader EHR or instrumentation ecosystems, typically procured through enterprise software vendors with existing hospital relationships.
On-premise solutions dominate installed base. Cloud-based solutions are where expansion concentrates.
End User:
Cost tier stratification separates enterprise health systems with dedicated procurement teams from mid-market buyers sensitive to per-seat pricing thresholds.
- Hospitals:Large-scale integrated delivery networks requiring multi-site standardization and enterprise-grade uptime guarantees. Consolidated systems in the United States Midwest are driving the steepest expansion trajectory for modular, interoperable platforms.
- Diagnostic Centers:High-volume commercial laboratories with specialized workflow needs including high-throughput specimen tracking and automated result distribution. Independent chains in California and Texas face ONC certification pressure accelerating replacement cycles.
- Research Laboratories:Scientific environments prioritizing customization depth and instrumentation integration over regulatory compliance speed.
- Academic Institutions:Hybrid clinical-research environments with dual reporting requirements and complex governance structures.
Hospitals command the largest contract values. Diagnostic centers generate the highest volume of new deployments.
Deployment:
Maturity gradients separate established client-server installations from emerging hybrid architectures bridging legacy and cloud-native environments.
- Hosted:Vendor-managed infrastructure with dedicated single-tenant environments, appealing to mid-sized labs seeking cloud benefits without multi-tenancy security concerns. Demand clusters in state hospital associations with centralized IT governance.
- SaaS:Multi-tenant cloud delivery with subscription pricing and automatic feature updates. Regional networks in the United States Southeast are adopting this fastest to eliminate version fragmentation across acquired facilities.
- Client-Server:Traditional on-site installation with perpetual licensing, concentrated in blood banks and facilities with decades-old HL7 interface investments.
- Hybrid:Split architectures preserving sensitive workloads on-premise while migrating analytics and reporting to cloud tiers, gaining traction among academic medical centers with dual compliance obligations.
Client-server retains the deepest installed base. SaaS is climbing the fastest among new procurements.
Application:
Regulatory intensity varies dramatically across laboratory types, with blood banks facing FDA oversight and microbiology labs subject to state surveillance mandates that shape platform requirements.
- Clinical Laboratories:High-throughput diagnostic environments processing routine chemistry, hematology, and immunoassay workflows. United States hospital-anchored labs are consolidating onto enterprise platforms fastest, pressured by ONC interoperability deadlines.
- Blood Banks:Highly regulated operations requiring chain-of-custody documentation and donor management with stringent data residency requirements. On-premise retention here is strongest due to AABB accreditation protocols and state-level hemovigilance reporting.
- Pathology Labs:Anatomic and molecular diagnostics operations with complex case tracking and image management needs, concentrated in academic medical centers with research affiliations.
- Microbiology Labs:Infectious disease testing environments with real-time surveillance reporting obligations to state health departments, generating recurring revenue for platforms with epidemiological dashboard capabilities.
Clinical laboratories represent the largest addressable revenue pool. Microbiology labs are where specialized functionality commands premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based LIS vendors export cloud-native platforms to Canadian health authorities and Mexican diagnostic chains, with cross-border data flows governed by USMCA digital trade provisions and HIPAA-equivalent privacy frameworks.
United States
Health system consolidation across the Midwest and Southeast drives enterprise-scale LIS procurement at integrated delivery networks. ONC Cures Act Final Rule enforcement compels diagnostic centers to abandon siloed legacy systems for FHIR-native architectures. The Texas Medical Center in Houston anchors the nation's largest concentration of precision medicine laboratories requiring biomarker-tracking modules.
Canada
Provincial health authorities in Ontario and British Columbia accelerate cloud migration to reduce capital expenditure cycles. Health Canada and Infoway interoperability standards mandate alignment with US ONC certification criteria for cross-border data exchange. Toronto's hospital network cluster leads adoption of SaaS-based laboratory workflows among Canadian academic medical centers.
Mexico
Private diagnostic chains in Mexico City and Monterrey import US-certified LIS platforms to serve medical tourism and domestic middle-class demand. COFEPRIS regulatory convergence with FDA quality system requirements facilitates technology transfer from US vendors. The Bajío Region's growing pharmaceutical manufacturing base generates ancillary demand for research-grade laboratory information systems.
North America Laboratory Information System Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and vertical integration intensity. The vendor base stratifies into three tiers: enterprise EHR-integrated platforms, standalone diagnostic specialists, and research-scientific instrumentation hybrids. Oracle and Epic Systems occupy the hospital-anchored tier through EHR-native modules. Thermo Fisher Scientific anchors the research-scientific segment. Consolidation pressure elevates M&A activity and API-first partnership strategies as dominant competitive moves.
Among US-based platform vendors, Oracle (Cerner Corporation), Thermo Fisher Scientific Inc., and Epic Systems Corporation exemplify the three strategic archetypes reshaping procurement patterns. Oracle represents the enterprise consolidation play, absorbing integration costs that previously burdened hospital IT departments. Thermo Fisher Scientific occupies the research-scientific instrumentation nexus, where customization depth commands premium positioning. Epic Systems exemplifies the EHR-native approach, extending captive laboratory modules into academic medical centers with captive pathology operations.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Thermo Fisher Scientific Inc. |
| XiFin, Inc. |
| Orchard Software Corporation |
| Comp Pro Med Inc |
| Epic Systems Corporation |
| Sunquest Information Systems |
| Meditech |
| McKesson Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at multi-tenant cloud infrastructure providers shapes price floors for SaaS-native LIS vendors, compressing margins for on-premise license incumbents while elevating recurring revenue multiples for subscription-first platforms. Health system CFOs in California and Texas exploit this scale asymmetry to extract operational expenditure concessions from legacy vendors facing stranded server investments.
Pricing Analysis
Next-generation FHIR-native architectures command 40-60% subscription premiums over HL7-based legacy installations, while prior-generation client-server platforms face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by ONC certification tier and integration complexity. Pricing pressure stems from health system consolidation forcing vendors to absorb multi-site standardization costs previously borne by hospital IT departments. Independent diagnostic laboratories in Florida exhibit highest price sensitivity due to capital constraints, while integrated delivery networks in the Midwest prioritize uptime guarantees over per-seat economics.
Supply Chain Analysis
Inventory cycles for laboratory instrumentation interfaces stretch 12-18 months, constraining LIS vendors' ability to synchronize software releases with analytical equipment refresh schedules. Software development concentrates in the United States, with specialized HL7-FHIR middleware sourcing from Canada and cloud infrastructure provisioning from domestic hyperscaler regions. Supply chain risk centers on single-source dependency for FHIR certification testing tools. Distribution runs through vendor-direct enterprise sales teams for hospital networks, while regional IT distributors serve mid-sized diagnostic centers with bundled implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ONC Cures Act Final Rule constitutes a regulatory inflection collapsing the viable vendor set, transforming compliance certification from competitive differentiator into market access gate. This disruption favors platforms with pre-built FHIR-native architectures over retrofit-dependent incumbents.
For Market Incumbents: Shield installed base revenue by accelerating HL7-to-FHIR migration subsidies for blood bank and pathology customers facing 2025 certification deadlines. Prioritize backward integration into cloud infrastructure provisioning to capture operational expenditure flows that hospital CFOs now demand, neutralizing SaaS-native challengers' cost structure advantage.
For New Entrants and Emerging Players: Anchor in microbiology surveillance verticals where state health departments mandate real-time epidemiological reporting, creating sticky revenue streams with limited incumbent specialization. Target independent diagnostic chains in Texas and Florida with rapid-deployment SaaS modules priced below Cerner and Epic entry thresholds, exploiting procurement friction at consolidated health systems.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors research-scientific instrumentation hybrids with captive laboratory workflow expertise over pure-play software vendors facing margin compression. Long-term viability rests on platforms embedding precision medicine biomarker tracking capabilities. Monitor FDA LDT oversight rulemaking as the critical inflection signal determining molecular diagnostics LIS addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Architecture Migration | ONC certification deadlines force replacement of HL7-dependent legacy platforms at hospital networks. |
| Cloud Infrastructure Partnership | Multi-tenant SaaS delivery reduces capital expenditure burden for California and Texas health systems. |
| Microbiology Surveillance Module Development | State health department reporting mandates generate recurring revenue with limited incumbent competition. |
| Precision Medicine Workflow Integration | Biomarker tracking capabilities capture molecular diagnostics expansion at academic medical centers. |
| Prior Authorization Automation Investment | Pending CMS rulemaking creates white space for real-time payer eligibility verification functionality. |
Research Methodology
A standing panel of laboratory information system product managers, health system CIOs, diagnostic center operations directors, and FHIR integration specialists provided ongoing calibration across the research process. Primary interview data triangulated against secondary sources including ONC certification databases, CMS Medicare reimbursement filings, state health information exchange authority protocols, and hospital procurement records. Bottom-up deployment estimates across product type, end user, and application segments reconciled with top-down health IT spending benchmarks.
Consistency checks against external health IT expenditure surveys validated volume and value outputs across the projection horizon. Segmentation modeling incorporated deployment architecture, operational scale, regulatory exposure tier, and geographic adoption pattern dimensions. CAGRs derived from segment-level unit economics and pricing trajectory assumptions, with precision medicine workflow intensity and cloud migration velocity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained ONC enforcement and stable health system consolidation velocity; material deviation in FDA LDT oversight timing or federal reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare Middleware Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
EHR EMR Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Healthcare API Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Healthcare Laboratory Informatics Market