
 High Acuity Information Systems Market | 2026-2036
High Acuity Information Systems Market Size, Share, and Industry Trends Forecast 2026-2036
High Acuity Information Systems Market Outlook
Aftermarket service revenue is reconfiguring margin pools across the High Acuity Information Systems landscape. GE HealthCare leverages its installed base of monitoring hardware to sustain recurring software maintenance contracts. Koninklijke Philips N.V. anchors its competitive stance through deep integration of patient monitoring with enterprise data architectures. Epic Systems Corporation dominates the clinical workflow layer, controlling access to the electronic health record systems that high-acuity platforms must interoperate with.
High acuity information systems encompass software and hardware platforms designed to capture, integrate, and analyze real-time physiological data for critically ill patients, typically supporting sampling rates exceeding 240 Hz for hemodynamic waveforms and sub-second alarm latency thresholds. These systems serve primarily to reduce cognitive load in intensive care environments while enabling predictive deterioration alerts. Clinical Decision Support and Patient Monitoring Systems command the largest current revenue pools, though AI-Driven Analytics within the technology dimension is expanding fastest as health systems seek automated early warning scores. Cloud-Based Solutions are maturing in delivery mode adoption, while on-premise hybrid architectures retain preference among institutions with legacy infrastructure investments.
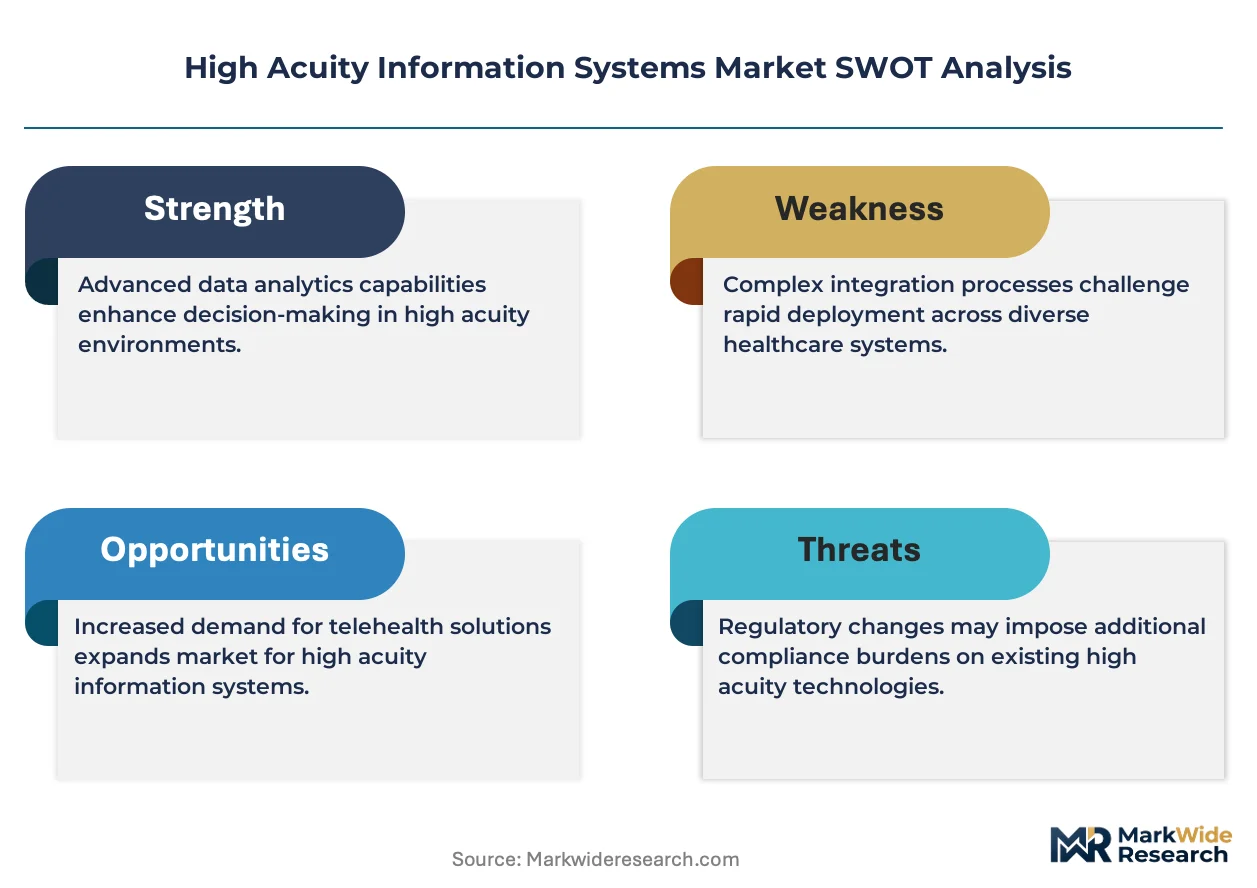
FDA enforces software-as-medical-device classifications under 21 CFR Part 820, compelling vendors to maintain design control documentation and risk management files for algorithm-based diagnostic outputs. HIPAA security rule provisions mandate encryption standards and access logging that shape product architecture decisions for any system handling protected health information. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled devices, as predicate device pathways for machine-learning algorithms remain unresolved and will determine speed-to-market for next-generation platforms.
Market Dynamics
Enterprise health system consolidation is compressing vendor selection cycles and mandating unified platform architectures across ICU, ED, and perioperative environments. This structural force privileges vendors capable of spanning hardware, software, and analytics layers under single contracting relationships.
Growth Catalysts
- FDA 21 CFR Part 820:Tightened quality system requirements for software-as-medical-device classifications are accelerating replacement of legacy monitoring systems that lack design control documentation.
- Cloud-native architectures:Health systems with aging on-premise infrastructure are migrating toward hybrid cloud deployments that reduce capital intensity while preserving sub-second alarm latency.
- ICU digitization programs:Hospital capital allocation in the United States is concentrating on enterprise-wide platform deployments that integrate patient monitoring with electronic health record workflows.
Market Restraints
- Input cost volatility:Specialized medical-grade sensors and FPGA chipsets face supply concentration risk from Taiwan-based foundries, compressing hardware margins.
- Technical limitation:Waveform sampling rates exceeding 240 Hz generate data volumes that strain legacy hospital network infrastructure, requiring parallel connectivity investments.
- Regulatory friction:Unresolved FDA predicate device pathways for machine-learning algorithms delay speed-to-market for next-generation diagnostic outputs.
Strategic Opportunities
- AI-Driven Analytics convergence:Integration of real-time physiological data streams with automated early warning scores represents underexploited white space in clinical decision support.
- Underpenetrated acute care settings:Step-down units and emergency departments in the United States lack high-acuity system penetration relative to ICUs, offering expansion vectors.
- Interoperability mandates:HIPAA security rule provisions for encryption standards and access logging create compliance-driven demand for modernized platform architectures.
Industry Challenges
- Biomedical informatics talent scarcity:Health systems struggle to recruit engineers capable of bridging clinical workflow design with real-time data pipeline architecture.
- Legacy system integration complexity:Decades-old patient monitoring hardware requires middleware layers that introduce latency and failure points into alarm chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Acuity Information Systems Market |
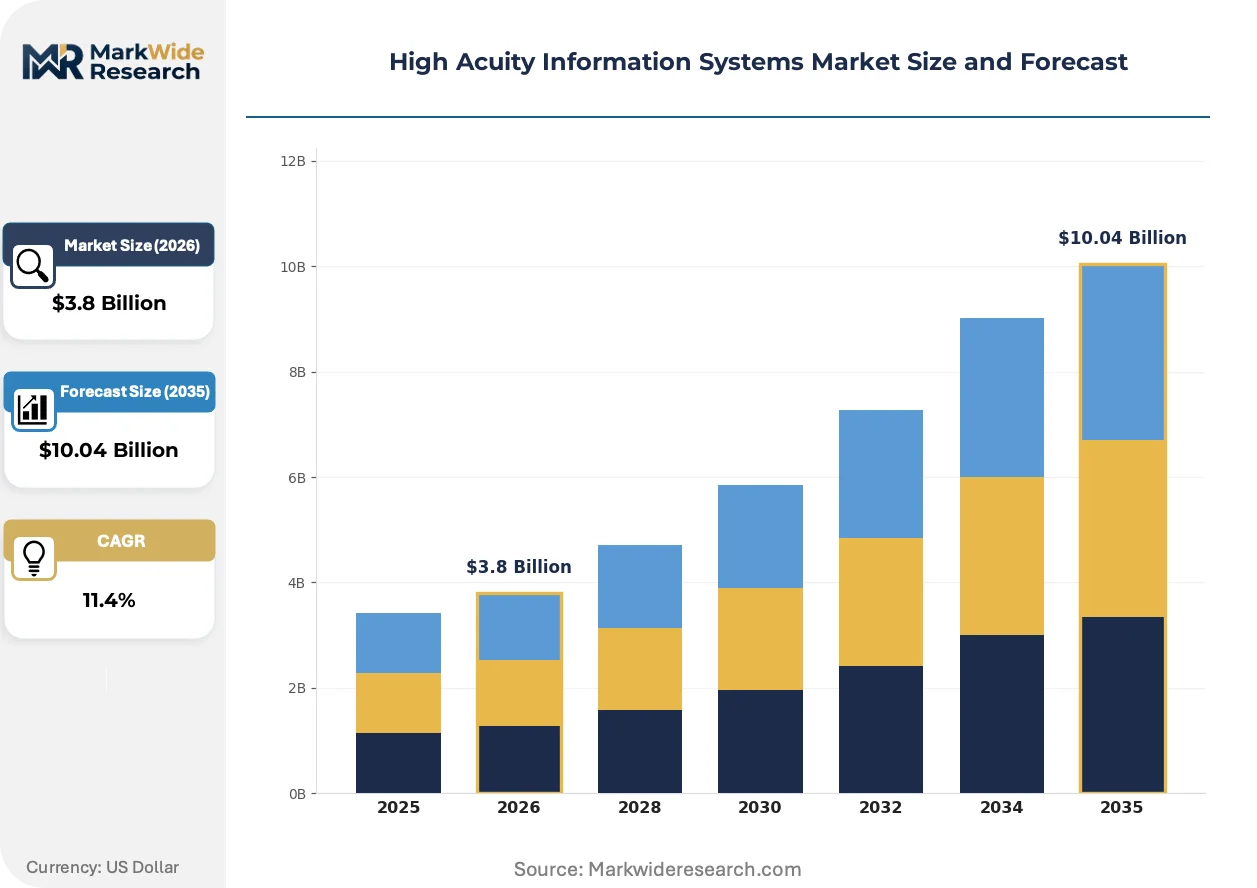
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Patient Monitoring Systems, Data Management Solutions, Telemedicine Platforms Technology: Cloud-Based Solutions, Mobile Applications, AI-Driven Analytics, Interoperability Standards End User: Intensive Care Units, Emergency Departments, Surgical Centers, Specialty Clinics Delivery Mode: On-Premise, Software as a Service, Hybrid Solutions, Remote Hosting |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Cerner Corporation, Epic Systems Corporation, Dragerwerk AG & Co. KGaA, Allscripts Healthcare Solutions, Nihon Kohden Corporation, McKesson Corporation, Picis Clinical Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Acuity Information Systems Market Strategic Shifts
Algorithmic processing of continuous physiological streams is displacing threshold-based alarm systems. This shift compresses cognitive load on bedside clinicians while creating new competitive terrain around predictive accuracy and false-positive rates.
Edge computing architectures for waveform analysis are rendering obsolete centralized server-based processing models that introduced unacceptable latency for hemodynamic instability detection. Academic medical centers in the United States are piloting FPGA-based edge nodes that process 240 Hz sampling rates locally. This topology eliminates network dependency for critical alarm pathways while reducing data center capital requirements.
EU Medical Device Regulation (MDR) post-market surveillance requirements are mandating systematic clinical follow-up for software updates that modify diagnostic algorithms. Vendors must now maintain performance documentation across deployed versions, increasing regulatory affairs headcount. Class III high-acuity systems face the steepest compliance burden, with notified bodies extending review timelines for AI-enabled features.
Subscription-based platform licensing is displacing perpetual software purchases in health system procurement. Chief information officers now prioritize operational expenditure models that align vendor compensation with uptime and outcome metrics. This preference shift is most pronounced among consolidated US health systems with centralized vendor management functions.
High Acuity Information Systems Market Segmentation
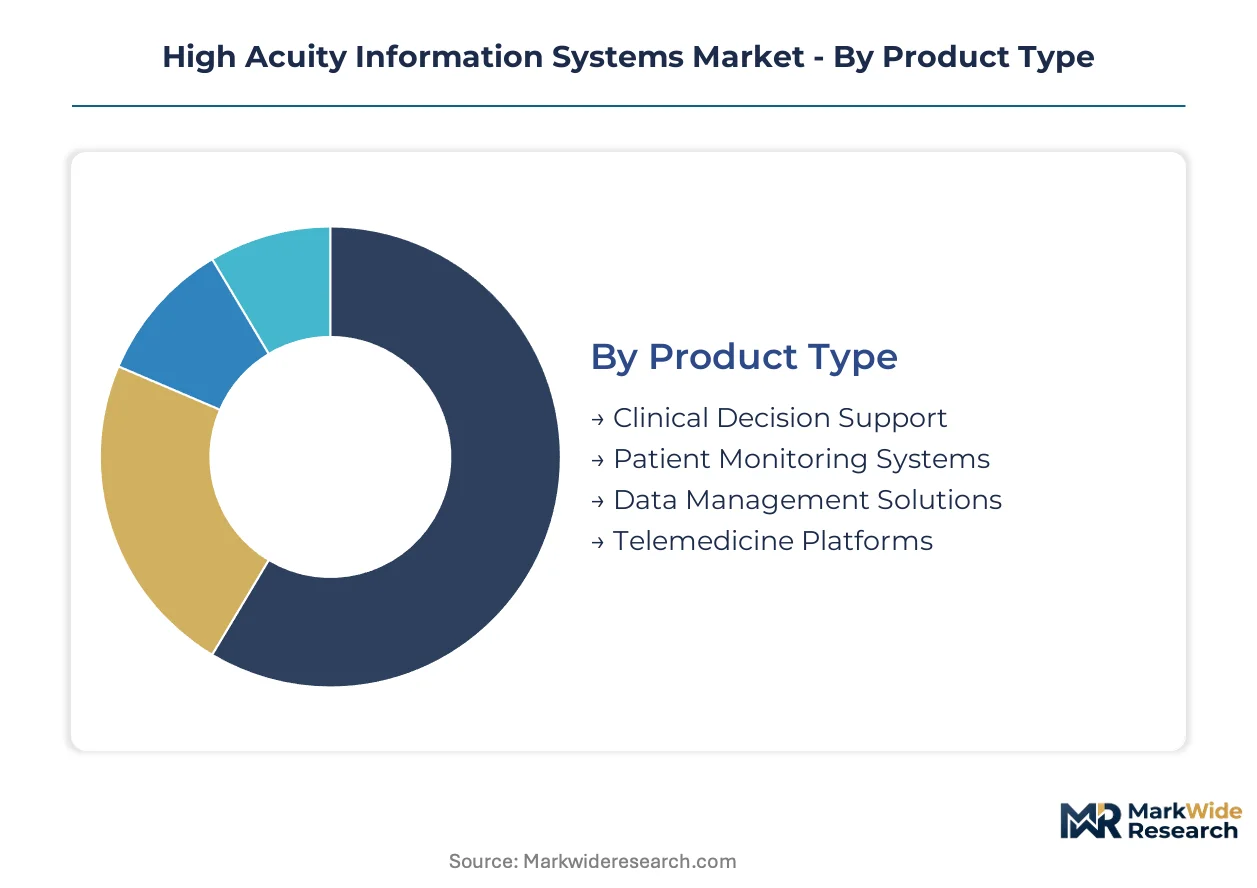
Segmentation in high acuity information systems reveals distinct procurement rhythms and technical requirements across product architectures, deployment models, and care settings. Understanding these divisions exposes where capital cycles concentrate versus where operational expenditure models are displacing traditional purchasing patterns.
Product Type:
Replacement cycles vary sharply across this category, with hardware-intensive platforms turning over every 5-7 years while software modules refresh on 18-36 month horizons.
- Clinical Decision Support:Algorithmic platforms that synthesize multi-parameter physiological data into predictive alerts and protocol recommendations. Demand concentrates in United States academic medical centers seeking automated early warning scores that reduce cognitive load on bedside nurses. FDA 21 CFR Part 820 documentation requirements compress vendor margins but create switching costs that protect incumbent positions.
- Patient Monitoring Systems:Hardware-software integrated platforms capturing real-time hemodynamic waveforms at sampling rates exceeding 240 Hz. United States health system consolidation drives enterprise-wide standardization contracts spanning ICU, ED, and perioperative environments. Alarm latency thresholds below one second mandate specialized FPGA chipsets with supply concentration risk from Taiwan-based foundries.
- Data Management Solutions:Middleware architectures normalizing continuous physiological streams into structured formats for EHR ingestion and retrospective analytics.
- Telemedicine Platforms:Remote monitoring interfaces enabling intensivist coverage across distributed hospital networks and rural critical access facilities.
Patient Monitoring Systems anchors the volume base while Clinical Decision Support gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive edge computing deployments from lightweight mobile implementations with minimal infrastructure requirements.
- Cloud-Based Solutions:Scalable architectures reducing data center capital intensity while preserving sub-second alarm latency through hybrid edge-cloud topologies. United States health systems with aging on-premise infrastructure are migrating toward these models to align vendor compensation with uptime metrics. HIPAA security rule encryption standards shape product architecture decisions for any system handling protected health information.
- AI-Driven Analytics:Machine-learning algorithms processing continuous physiological streams to predict deterioration before threshold-based alarms trigger. United States academic medical centers pilot these capabilities, though unresolved FDA predicate device pathways for self-modifying algorithms delay commercial deployment. EU MDR post-market surveillance requirements mandate systematic clinical follow-up for diagnostic algorithm updates.
- Mobile Applications:Lightweight interfaces extending alarm notification and waveform visualization to clinician smartphones and tablets.
- Interoperability Standards:FHIR-based APIs and HL7 messaging protocols enabling data exchange between proprietary monitoring platforms and enterprise EHR systems.
Cloud-Based Solutions anchors the volume base while AI-Driven Analytics climbs the fastest as regulatory clarity emerges.
End User:
Application severity determines technical specifications, with highest-acuity settings demanding redundant alarm pathways that step-down environments can relax.
- Intensive Care Units:Primary deployment setting requiring 240 Hz waveform sampling, sub-second alarm latency, and predictive analytics integration. United States hospital capital allocation concentrates here, with enterprise-wide platform deployments integrating patient monitoring with Epic Systems EHR workflows. FDA software-as-medical-device classifications under 21 CFR Part 820 compel rigorous design control documentation.
- Emergency Departments:High-acuity episodic care environments where rapid patient turnover demands streamlined monitoring setup and automated data capture. United States EDs lack high-acuity system penetration relative to ICUs, offering expansion vectors for vendors with portable, rapidly deployable platforms. Triage protocols and boarding patient management create distinct workflow requirements.
- Surgical Centers:Perioperative environments requiring seamless anesthesia information system integration and post-anesthesia care unit handoff workflows.
- Specialty Clinics:Cardiac catheterization labs, neuro-ICU step-down units, and other focused acute care settings with specialized monitoring needs.
Intensive Care Units anchors the volume base while Emergency Departments expand most quickly as health systems seek to extend high-acuity capabilities beyond traditional ICU boundaries.
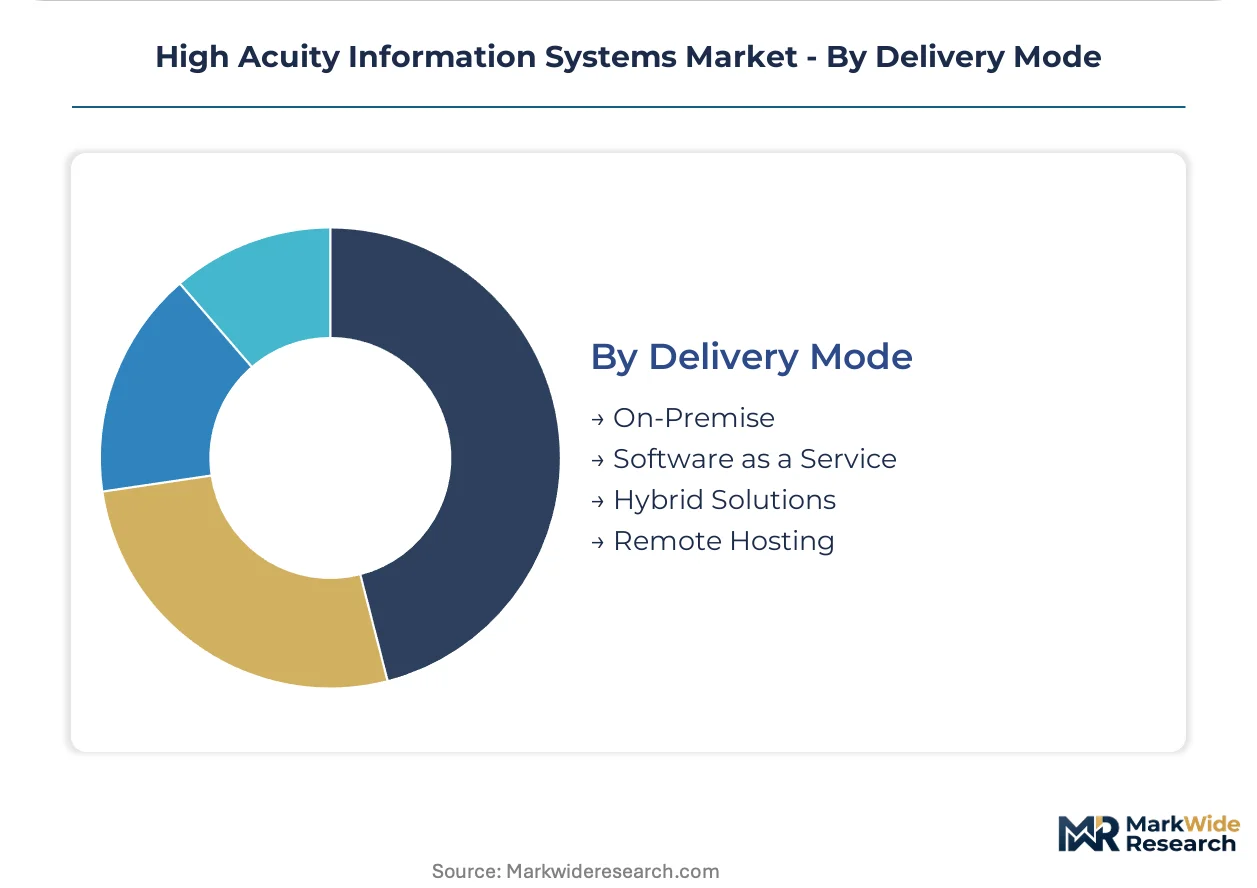
Delivery Mode:
Customer type stratification separates consolidated United States health systems with centralized vendor management functions from independent hospitals with constrained IT resources.
- Software as a Service:Subscription licensing models aligning vendor compensation with uptime and outcome metrics. United States consolidated health systems with centralized procurement functions prioritize these operational expenditure structures. Chief information officers favor models that transfer infrastructure risk to vendors while preserving clinical functionality.
- Hybrid Solutions:Architectures combining on-premise edge computing for critical alarm pathways with cloud-based analytics and long-term data storage. United States institutions with legacy infrastructure investments retain preference for these models to preserve capital sunk in existing data centers while accessing scalable analytics capabilities. Network segmentation requirements for HIPAA compliance favor this topology.
- On-Premise:Traditional perpetual licensing with customer-managed infrastructure and software maintenance contracts.
- Remote Hosting:Vendor-managed data center deployments with dedicated connectivity to customer sites.
Hybrid Solutions anchors the volume base while Software as a Service shows the steepest expansion trajectory as procurement shifts toward outcome-aligned expenditure models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States health systems absorb premium pricing for enterprise-wide ICU digitization, while emerging markets prioritize cost-optimized modular deployments. European procurement cycles stretch longer under stricter post-market surveillance mandates.
United States
Hospital consolidation drives enterprise-wide platform standardization across ICU, ED, and perioperative environments. FDA 21 CFR Part 820 quality system requirements accelerate replacement of legacy monitoring systems lacking design control documentation. Academic medical centers in Boston and the Research Triangle pilot FPGA-based edge computing nodes for 240 Hz waveform processing.
Germany
Industrial hospital networks demand seamless integration between patient monitoring and enterprise data architectures. EU MDR post-market surveillance requirements extend review timelines for AI-enabled diagnostic features, compressing vendor margins. Medical technology clusters in Baden-Württemberg concentrate R&D investment for interoperability standards and FHIR-based API development.
Japan
Aging demographics intensify demand for remote intensivist coverage across rural critical access facilities. PMDA software-as-medical-device classifications align with international harmonization efforts, streamlining predicate device pathways. Tokyo-Osaka hospital chains deploy hybrid cloud architectures to reduce data center capital intensity while preserving sub-second alarm latency.
United Kingdom
NHS procurement frameworks favor subscription-based platform licensing aligned with uptime and outcome metrics. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines, complicating vendor compliance strategies. London teaching hospitals anchor pilot programs for AI-driven early warning scores integrated with Epic Systems EHR workflows.
China
Tier-3 hospital expansion programs concentrate demand for cost-optimized patient monitoring hardware with modular software upgrades. NMPA software-as-medical-device classifications tighten documentation requirements for algorithm-based diagnostic outputs. Yangtze River Delta medical device manufacturing clusters scale production of medical-grade sensors for domestic ICU digitization initiatives.
High Acuity Information Systems Market Competitive Environment
Capability concentration sits with integrated hardware-software vendors; scale advantage sits with enterprise software platforms. The market structures around three tiers: diversified medical technology conglomerates with installed base leverage, specialized patient monitoring hardware vendors with FPGA chipset supply relationships, and clinical workflow software providers controlling EHR interoperability gateways. Dominant competitive moves include strategic partnerships bridging hardware and analytics layers, and vertical integration into edge computing chip design to secure supply chain resilience.
Within the diversified medical technology tier, GE HealthCare and Koninklijke Philips N.V. occupy positions anchored by decades of monitoring hardware deployment. Epic Systems Corporation exemplifies the clinical workflow software archetype, its market presence shaped by EHR system penetration that high-acuity platforms must interoperate with. These three entities collectively represent the competitive fault lines between hardware-installed-base leverage and software-controlled data flow architecture.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Cerner Corporation |
| Epic Systems Corporation |
| Dragerwerk AG & Co. KGaA |
| Allscripts Healthcare Solutions |
| Nihon Kohden Corporation |
| McKesson Corporation |
| Picis Clinical Solutions |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Taiwan-based FPGA foundries is compressing hardware margins while forcing United States health systems toward subscription-based procurement models that transfer infrastructure risk to vendors.
Pricing Analysis
Long-term enterprise service contracts dominate procurement, with United States consolidated health systems favoring SaaS-tiered structures that align vendor compensation with uptime metrics. Price differentiation rests on FDA 21 CFR Part 820 certification tier and after-sales service bundling. Cost compression in hardware-intensive platforms is intensifying because Taiwan foundry undercapacity elevates medical-grade sensor input costs. Academic medical centers show least price sensitivity; rural critical access facilities exhibit highest.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk planning for FPGA chipset procurement. Manufacturing concentrates in Taiwan, China, and Germany. Raw material dependencies include medical-grade sensors, FPGA semiconductors, and specialized cabling. Single-source vulnerability in Taiwan-based foundries threatens alarm latency compliance. Distribution runs through regional medical device distributors with GPO contract integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment protects incumbent positions through FDA design control documentation requirements that create prohibitive switching costs.
For Market Incumbents: Build data-architecture moats by deepening Epic Systems EHR interoperability integration and acquiring edge computing chip design capabilities. Threat from cloud-native entrants demands defensive certification investment in EU MDR post-market surveillance compliance. Capacity addition in United States-based FPGA packaging reduces Taiwan supply exposure. For New Entrants and Emerging Players: United States emergency departments offer the most penetrable geographic underpenetration relative to ICU saturation. White-space targets include step-down unit predictive analytics and portable perioperative platforms. Go-to-market angle: hybrid cloud deployments preserving sub-second latency for institutions with legacy infrastructure investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-as-a-service delivery modes while hardware-integrated platforms retain elevated fixed-cost structures. Long-term viability favors vendors with recurring revenue composition exceeding transactional hardware sales. Acquisition target archetype: clinical decision support specialists with FDA-cleared algorithms. Signal to watch: FDA predicate device pathway resolution for self-modifying machine-learning algorithms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 21 CFR Part 820 Compliance Investment | Design control documentation creates switching costs that protect incumbent market positions. |
| Epic Systems EHR Integration Partnership | Workflow interoperability secures access to electronic health record data architectures. |
| Edge Computing Hardware Acquisition | FPGA chipset supply control reduces Taiwan foundry dependency for alarm latency compliance. |
| EU MDR Post-Market Surveillance Buildout | Systematic clinical follow-up capabilities satisfy notified body requirements for AI-enabled features. |
| Hybrid Cloud Architecture Development | Network segmentation preserves HIPAA compliance while reducing data center capital intensity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, hospital procurement databases, GPO contract disclosures, and SEC 10-K regulatory filings. Primary interviews engaged biomedical engineers, hospital purchasing committee members, ICU clinicians, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, hospital capital expenditure surveys, and medical device trade flow records. Bottom-up unit economics triangulate against top-down health system IT budget allocations.
Forecast inputs span product type segmentation across clinical decision support and patient monitoring systems, technology dimensions including cloud-based solutions and AI-driven analytics, and end-user settings from intensive care units through emergency departments. Deployment mode distinctions between software-as-a-service and hybrid solutions anchor the modeling framework. CAGRs derive from installed base turnover rates, replacement cycle compression, and enterprise consolidation trajectories. Regulatory approval timelines and predicate device pathway uncertainty shape variance bands across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or cross-border hardware integrators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
Healthcare Information Exchange Market