
 IT Spending on Clinical Analytics Market | 2026-2036
IT Spending on Clinical Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
IT Spending on Clinical Analytics Market Outlook
Enterprise-grade interoperability certification is collapsing the gap between legacy EHR silos and modern analytics stacks. Epic Systems Corporation leverages its dominant hospital install base to extend analytics modules directly into clinical workflows. IBM Corporation competes through Watson Health's specialized focus on oncology and population health algorithms. SAS Institute anchors its position with deep statistical computing heritage that sustains loyalty among research institutions.
IT spending on clinical analytics encompasses the procurement, deployment, and maintenance of software systems, hardware infrastructure, and professional services that transform structured and unstructured clinical data into actionable intelligence using statistical models, machine learning pipelines, and real-time processing architectures operating at sub-second latency thresholds. The primary commercial purpose is to reduce clinical variation, optimize resource allocation, and enable value-based reimbursement by predicting patient deterioration, identifying care gaps, and automating quality reporting. Software solutions dominate current expenditure as hospitals replace point tools with integrated platforms spanning predictive analytics, data management, and clinical decision support. Cloud-based delivery models are capturing the fastest growth trajectory as health systems seek to shift capital expenditure to operational models while addressing cybersecurity and scalability requirements.
FDA's 21st Century Cures Act and ONC information blocking rules are reshaping data liquidity requirements, compelling vendors to support standardized APIs that enable third-party analytics ingestion. HIPAA security provisions and state-level privacy statutes create compliance complexity that favors vendors with mature governance frameworks and dedicated regulatory affairs functions. Stakeholders must monitor whether emerging state artificial intelligence oversight laws will impose algorithmic audit obligations that reshape vendor liability and procurement criteria.
Market Dynamics
FDA's 21st Century Cures Act interoperability mandates are forcing EHR vendors to dismantle data silos, creating immediate procurement pressure for analytics platforms that can ingest standardized APIs and operate across heterogeneous clinical environments.
Growth Catalysts
- Medicare reimbursement rules:United States payment structures increasingly tie hospital revenue to quality metrics derived from predictive analytics, compelling health systems to invest in readmission reduction platforms.
- Cloud migration architectures:Health systems are shifting capital expenditure models toward operational spending, accelerating adoption of scalable SaaS analytics delivery.
- Real-time processing requirements:Sub-second latency thresholds for patient deterioration alerts are driving replacement of batch-processing legacy systems with streaming analytics infrastructure.
Market Restraints
- Cybersecurity compliance costs:HIPAA security provisions and state-level privacy statutes create multi-layered governance complexity that extends procurement timelines and inflates total cost of ownership.
- Legacy system technical debt:Decades of fragmented EHR deployments create data standardization barriers that resist rapid analytics integration without expensive middleware layers.
- Specialized talent scarcity:Health systems compete for data scientists with clinical domain expertise, constraining deployment velocity for advanced machine learning pipelines.
Strategic Opportunities
- Emerging AI oversight legislation:Proposed state-level algorithmic audit obligations will favor vendors with mature governance frameworks and dedicated regulatory affairs functions.
- Rural health network penetration:Critical access hospitals remain undersupplied with enterprise analytics, presenting white space for cloud-native platforms with lower infrastructure requirements.
- FHIR standard convergence:Fast Healthcare Interoperability Resources specification maturation enables third-party analytics ingestion that bypasses traditional EHR vendor control points.
Industry Challenges
- Workflow integration complexity:Clinician resistance to alert fatigue requires analytics vendors to embed insights directly into existing EHR interfaces without disrupting established care patterns.
- Data quality remediation:Unstructured clinical notes and incomplete coding create training data deficiencies that degrade predictive model performance in production environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Spending on Clinical Analytics Market |
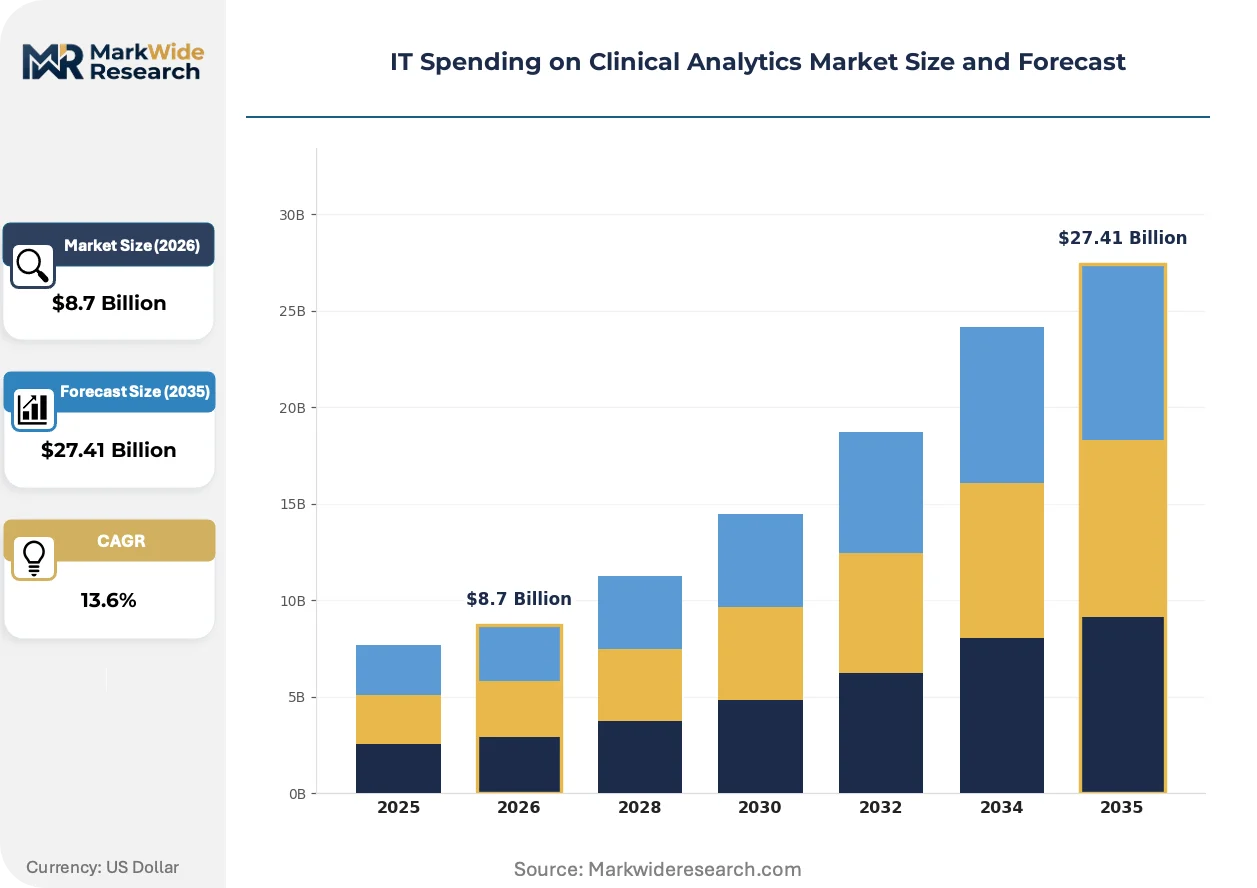
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Application: Predictive Analytics, Data Management, Reporting, Clinical Decision Support End User: Hospitals, Diagnostic Labs, Research Institutions, Healthcare Providers Delivery Model: On-Premise, Cloud-Based, Hybrid, Subscription |
| Companies Covered | Epic Systems Corporation, Innovaccer, Optum, Philips, IBM Corporation, IQVIA, Health Catalyst, SAS Institute, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Spending on Clinical Analytics Market Strategic Shifts
Clinical analytics infrastructure is undergoing fundamental architecture transformation as regulatory mandates collide with computational advances, reshaping how health systems procure, deploy, and monetize data intelligence capabilities.
Natural language processing engines are supplanting manual abstraction workflows for unstructured clinical documentation. Hospital informatics departments are deploying these systems to extract diagnostic and procedural codes from physician notes with minimal human review. This automation is compressing revenue cycle timelines while reducing dependency on specialized clinical documentation improvement staff.
ONC information blocking enforcement is reshaping vendor competitive dynamics by mandating standardized API availability. EHR incumbents must now expose patient data endpoints that third-party analytics developers can access without proprietary negotiation. Specialty analytics vendors in oncology and population health are exploiting this opening to bypass traditional distribution channels and contract directly with health system innovation offices.
Subscription-based platform procurement is displacing perpetual license arrangements across integrated delivery networks. Finance departments prefer operational expenditure treatment for analytics investments that require continuous algorithm retraining and regulatory compliance updates. This preference is most pronounced among mid-size health systems in the United States that lack dedicated health IT capital reserves but maintain robust annual technology budgets.
IT Spending on Clinical Analytics Market Segmentation
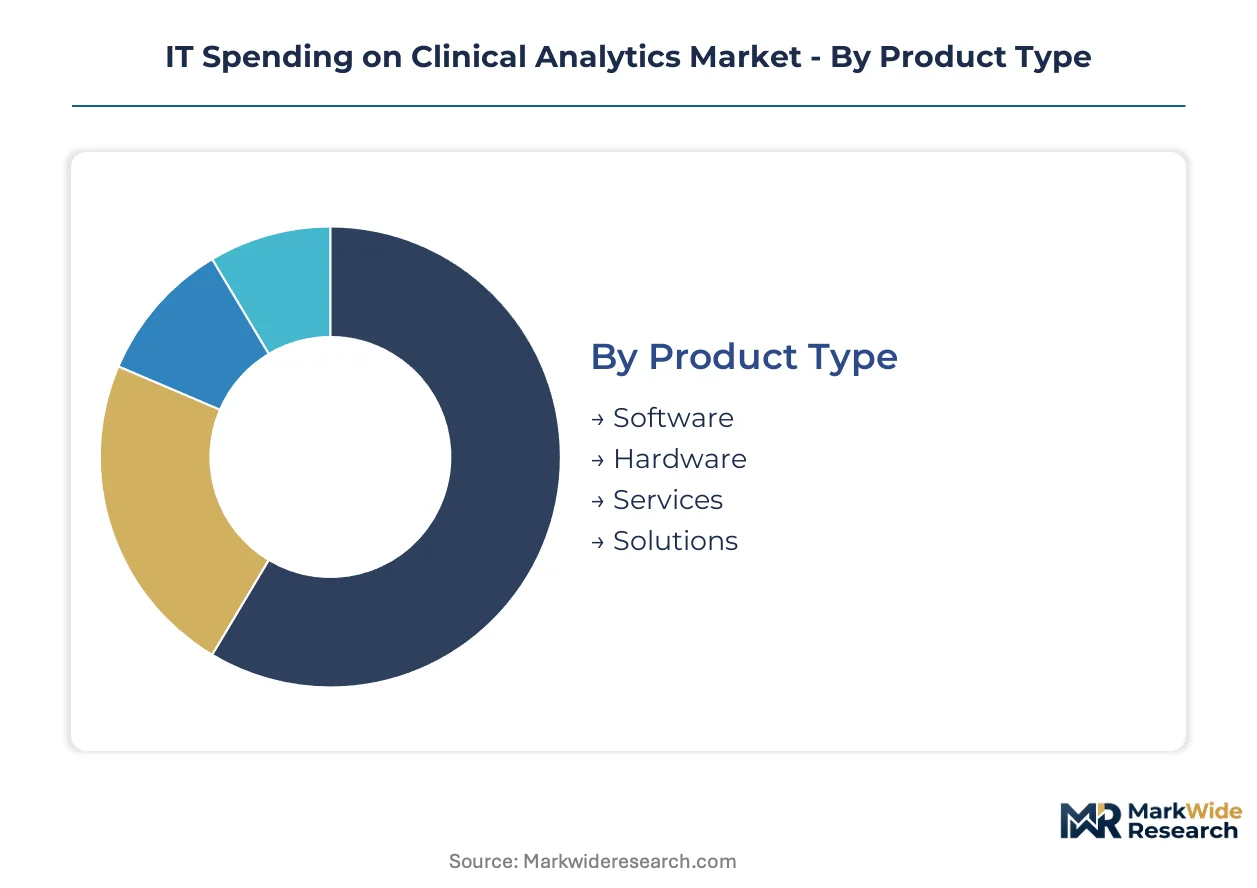
IT spending on clinical analytics fragments across four dimensions that determine procurement patterns and vendor positioning. Product type and delivery model decisions drive capital allocation, while application focus and end-user scale dictate implementation complexity and return timelines.
Product Type:
Software solutions command the dominant margin pool, capturing recurring licensing revenue and upgrade cycles. Hardware infrastructure yields thinner margins but locks in long-term maintenance contracts.
- Software:Predictive analytics platforms, NLP engines, and visualization tools constitute the core expenditure category. United States hospital systems prioritize integrated suites that span risk stratification, quality reporting, and operational dashboards under single-vendor contracts.
- Services:Implementation consulting, data migration, and managed analytics operations represent high-margin attach revenue. Health systems in the United States increasingly outsource algorithm development and model retraining to compensate for internal data science shortages.
- Hardware:GPU clusters, edge computing appliances, and high-throughput storage arrays support latency-sensitive applications. Procurement concentrates among academic medical centers building dedicated research infrastructure.
- Solutions:Pre-configured vertical packages combining software, hardware, and services for specific clinical domains. Oncology and population health variants show strongest traction among integrated delivery networks.
Software holds installed capacity. Services is rotating up the share rankings.
Application:
Volume concentrates in retrospective reporting tools, but growth vectors align with predictive and real-time capabilities. Regulatory pressure on readmission penalties and quality metrics reshapes priority hierarchies.
- Predictive Analytics:Machine learning models forecasting patient deterioration, sepsis onset, and readmission risk operate at sub-second latency thresholds. United States Medicare reimbursement rules tie hospital revenue to outcomes derived from these platforms, compelling procurement across health system tiers.
- Clinical Decision Support:Real-time alerts and evidence-based order sets embedded within EHR workflows reduce clinical variation. FDA 21st Century Cures Act interoperability mandates enable third-party algorithms to surface directly in clinician interfaces.
- Data Management:Master data management, data lakes, and FHIR-compliant integration layers standardize heterogeneous clinical sources. Cloud-native architectures are displacing on-premise data warehouses among mid-size health systems.
- Reporting:Automated quality measure extraction and regulatory submission tools compress manual abstraction timelines. ONC information blocking enforcement accelerates API-based reporting platform adoption.
Predictive analytics is climbing the fastest. Clinical decision support holds installed capacity.
End User:
Procurement scale and decision velocity vary sharply across user categories. Hospital systems drive enterprise platform contracts, while research institutions favor specialized statistical computing environments.
- Hospitals:Integrated delivery networks and standalone acute care facilities represent the dominant procurement volume. United States health systems prioritize readmission reduction platforms and sepsis prediction algorithms to avoid Medicare penalties.
- Research Institutions:Academic medical centers and contract research organizations demand high-compute environments for clinical trial analytics and real-world evidence generation. SAS Institute and specialized biostatistical tools retain strong loyalty in this segment.
- Diagnostic Labs:Anatomic pathology and molecular diagnostics operations require analytics for workflow optimization and predictive maintenance of instrumentation. Cloud-based platforms with lower infrastructure requirements penetrate this historically undersupplied category.
- Healthcare Providers:Physician practices and ambulatory networks seek lightweight analytics for population health management and care gap identification. Subscription delivery models align with their operational expenditure preferences.
Hospitals hold installed capacity. Research institutions maintain pricing power through specialized requirements.
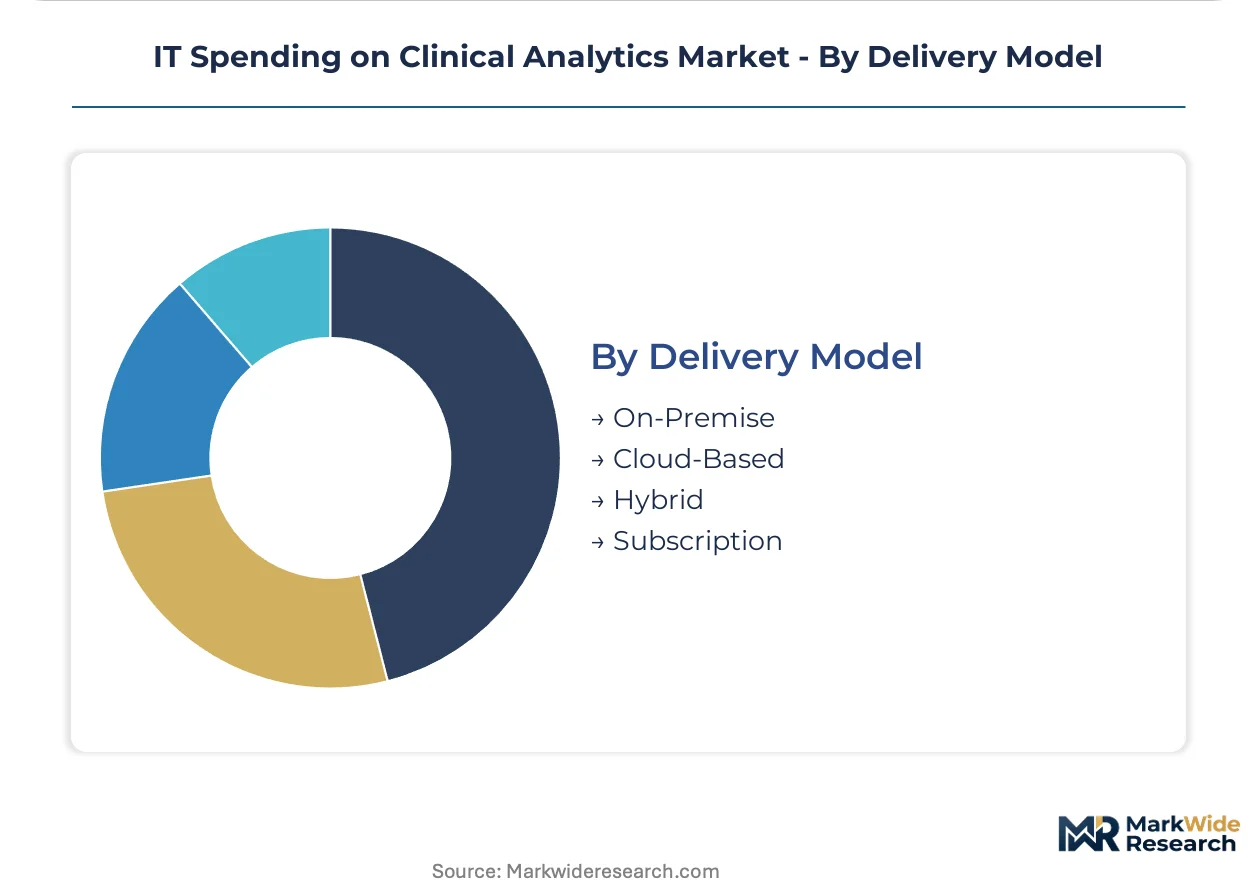
Delivery Model:
Finance department preferences are restructuring procurement patterns. Capital expenditure constraints favor operational models, though cybersecurity and data residency concerns sustain hybrid architectures.
- Cloud-Based:SaaS analytics platforms with automatic updates and elastic scaling address cybersecurity and disaster recovery requirements. United States mid-size health systems lacking dedicated IT capital reserves drive fastest expansion in this category.
- Hybrid:Sensitive patient data remains on-premise while compute-intensive model training leverages cloud resources. HIPAA security provisions and state-level privacy statutes favor this architecture among risk-averse institutions.
- On-Premise:Legacy perpetual license deployments persist among health systems with substantial sunk infrastructure investments. Replacement cycles lengthen as vendors shift R&D priority toward cloud-native architectures.
- Subscription:Annual or multi-year contracts covering software, maintenance, and compliance updates align with value-based reimbursement timelines. Finance departments prefer operational expenditure treatment for analytics investments requiring continuous algorithm retraining.
Cloud-based is gaining share fastest. On-premise retains legacy lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems export clinical analytics expertise and platform architectures to hospital networks in Canada, United Kingdom, and Australia, establishing a transnational procurement corridor for predictive analytics and interoperability solutions.
United States
Medicare reimbursement rules tie hospital revenue to quality metrics derived from predictive analytics, compelling integrated delivery networks to procure readmission reduction platforms. FDA's 21st Century Cures Act interoperability mandates force EHR vendors to open standardized APIs for third-party analytics ingestion. The Boston-Cambridge corridor concentrates academic medical centers deploying real-time sepsis prediction algorithms at sub-second latency thresholds.
Germany
University hospitals in Baden-Württemberg and Bavaria demand high-compute environments for clinical trial analytics and real-world evidence generation. EMA's evolving guidance on AI-enabled medical devices creates compliance complexity that favors vendors with mature governance frameworks. The Rhine-Main cluster around Frankfurt anchors pharmaceutical-sponsored analytics deployments for post-market surveillance.
United Kingdom
NHS England's integrated care systems accelerate procurement of population health analytics to manage capitated budgets across regional footprints. MHRA's post-Brexit regulatory autonomy shapes algorithmic audit requirements for clinical decision support tools. London's digital health cluster concentrates health tech procurement offices negotiating SaaS analytics contracts with operational expenditure treatment.
Japan
Super-aging demographics drive demand for predictive analytics forecasting patient deterioration in acute care settings. PMDA's streamlined review pathways for SaMD accelerate deployment of AI-enabled diagnostic algorithms. The Kanto region around Tokyo concentrates university hospital networks building dedicated clinical data warehouses for research-commercial hybrid applications.
Australia
State health departments procure cloud-native analytics platforms to unify fragmented hospital information systems across rural and metropolitan networks. TGA's software as a medical device framework imposes cybersecurity and clinical validation requirements on imported platforms. The Melbourne-Sydney corridor concentrates digital health agencies piloting FHIR-based interoperability for cross-jurisdictional patient data exchange.
IT Spending on Clinical Analytics Market Competitive Environment
Listed leaders compete with private specialists across delivery model preferences, with publicly traded health IT conglomerates anchoring enterprise platform contracts while venture-backed analytics specialists capture mid-market cloud migrations. The vendor base arranges into three strategic archetypes: EHR incumbents extending analytics modules into existing install bases, specialized AI developers targeting oncology and population health verticals, and statistical computing heritage vendors retaining research institution loyalty. Dominant competitive moves include M&A to acquire FHIR-native interoperability capabilities and strategic partnerships with cloud hyperscalers to address cybersecurity and elastic scaling requirements.
Among EHR-anchored platforms, Epic Systems Corporation exemplifies the incumbent archetype leveraging dominant hospital install bases to embed analytics directly into clinical workflows. IBM Corporation occupies a position representing specialized AI heritage through Watson Health's oncology and population health algorithm focus. SAS Institute anchors the statistical computing tier with deep research institution loyalty sustained by biostatistical tool ecosystems. These three patterns—workflow-embedded, vertically specialized, and research-compute—capture the competitive structure governing procurement decisions across health system tiers.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Innovaccer |
| Optum |
| Philips |
| IBM Corporation |
| IQVIA |
| Health Catalyst |
| SAS Institute |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS platforms displacing on-premise perpetual licenses simultaneously redistribute supply geography toward hyperscaler regions and compress pricing economics through operational expenditure models. This substitution collapses legacy vendor maintenance revenue pools while shifting procurement leverage toward health systems with annual technology budgets rather than capital reserves.
Pricing Analysis
Next-generation cloud-native platforms command 40-60% subscription premiums over prior-generation on-premise licenses, while current-generation hybrid architectures occupy a contracting middle tier. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade FHIR-native suites from mid-market SaaS bundles and basic reporting tools. Cost compression in the economy tier is intensifying because rural health networks and critical access hospitals negotiate volume discounts for stripped-down predictive analytics modules. Academic medical centers with dedicated IT capital reserves exhibit lowest price sensitivity, while standalone physician practices demonstrate acute sensitivity to per-seat licensing costs.
Supply Chain Analysis
Inbound logistics costs for GPU clusters and edge computing appliances have stabilized following pandemic-era port congestion, though specialized healthcare-grade hardware still faces extended lead times through the Shanghai-Los Angeles trade lane. Supply concentrates in the United States for EHR-embedded analytics modules, Taiwan and South Korea for GPU semiconductor components, and Ireland and Singapore for cloud infrastructure serving European and Asia-Pacific health systems. Raw material dependencies span NVIDIA H100 tensor cores, high-bandwidth memory modules, and HIPAA-compliant data center certifications. Single-source vulnerability around NVIDIA's AI training hardware creates procurement risk for academic medical centers building dedicated research infrastructure. Distribution runs through direct vendor-to-health-system contracts for enterprise platforms, with channel partners penetrating mid-market ambulatory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IT spending on clinical analytics market sits in a cyclical recovery phase driven by Medicare reimbursement rule tightening that compels hospital systems to accelerate predictive analytics procurement. Health systems facing readmission penalties create sustained demand visibility for vendors with compliant quality reporting platforms.
For Market Incumbents: Secure FHIR-native interoperability certification to defend against third-party analytics vendors exploiting FDA 21st Century Cures Act mandates. Lock in long-term subscription contracts with integrated delivery networks before mid-market cloud-native entrants achieve enterprise-grade security accreditation. Vertical integration into natural language processing engines for unstructured clinical documentation insulates against specialized AI developers encroaching on revenue cycle automation.
For New Entrants and Emerging Players: Rural health network penetration gaps where critical access hospitals lack enterprise analytics infrastructure present the most penetrable white space. Cloud-native platforms with lower infrastructure requirements bypass incumbent lock-in among mid-size health systems lacking dedicated IT capital reserves. Direct contracting with health system innovation offices—bypassing traditional EHR vendor distribution channels—exploits ONC information blocking enforcement.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized AI developers with oncology and population health algorithm focus. Long-term viability hinges on regulatory compliance moats rather than raw predictive accuracy, positioning vendors with mature governance frameworks for sustained margin protection. Watch FDA guidance on AI-enabled medical device classification as the inflection signal determining whether analytics platforms face heightened clinical validation requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Interoperability Certification | FDA 21st Century Cures Act mandates force EHR vendors to open standardized APIs for third-party ingestion. |
| Cloud Infrastructure Partnership | Hyperscaler alliances address HIPAA security provisions and elastic scaling for mid-market health systems. |
| Natural Language Processing Acquisition | Automated clinical documentation extraction compresses revenue cycle timelines and reduces specialized staffing dependency. |
| Rural Health Network Expansion | Critical access hospitals remain undersupplied with enterprise analytics, presenting white space for lower-infrastructure platforms. |
| Algorithmic Governance Framework Investment | Proposed state-level AI oversight laws favor vendors with dedicated regulatory affairs functions and audit capabilities. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs, health system procurement committee members, EHR implementation specialists, and clinical informatics directors. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement rule filings, ONC interoperability certification records, and hospital capital expenditure disclosures. Bottom-up health system spending estimates triangulated against top-down vendor revenue segmentation across software, services, hardware, and solutions categories.
Across the analysis window, the forecasting framework modeled expenditure trajectories by product type, application focus, end-user scale, and delivery model preference. CAGRs were derived from weighted regression against Medicare reimbursement rule evolution, cloud migration velocity indices, and real-time processing latency requirement diffusion. Industry-specific inputs included sepsis prediction algorithm deployment rates, FHIR standard adoption curves, and health system cybersecurity incident frequency.
Material uncertainties—regulatory delays in FDA AI-enabled medical device guidance, state-level algorithmic audit obligation enactment timelines, and hyperscaler data center capacity constraints—sit outside the modeled envelope. Forecasts reflect assumptions about continued Medicare quality metric expansion and sustained cloud infrastructure investment by mid-size health systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
EHR EMR Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
United States Healthcare Information Exchange Market
Health Informatics
Allergy Care Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Healthcare BI Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
AI-Powered Formulary Management Market