
 Asia Pacific Healthcare Analytics Market | 2026-2036
Asia Pacific Healthcare Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Healthcare Analytics Market Outlook
Multi-source vendor engagement for healthcare analytics platforms is hardening across Asia Pacific hospital procurement departments. IBM Corporation leverages its Watson Health architecture to sustain enterprise contracts with large hospital networks in Japan and Australia. Oracle Corporation anchors cloud-based analytics deployments through its Cerner acquisition, competing directly with Optum Inc., which dominates UnitedHealth Group's regional data services footprint.
Asia Pacific healthcare analytics encompasses the computational processing of clinical, financial, and operational health data using statistical algorithms, machine learning models, and distributed computing architectures to generate actionable intelligence for care delivery optimization. These systems integrate electronic health records, claims databases, and real-time patient monitoring streams to support clinical decision-making, resource allocation, and population-level disease surveillance. Cloud-based delivery modes are capturing the fastest expansion as hospitals migrate from legacy on-premises infrastructure, while artificial intelligence and machine learning technologies concentrate the highest R&D investment and margin potential. Patient care applications lead current deployment volumes, though population health analytics is gaining traction as governments fund preventive care programs.
Japan's PMDA and Australia's TGA enforce data integrity standards that shape analytics platform validation requirements, while India's CDSCO and BIS frameworks govern medical device software classifications affecting market access pathways. The EU AI Act's extraterritorial influence on Asia Pacific exporters is tightening algorithmic transparency obligations for analytics vendors serving multinational hospital chains. Stakeholders must monitor regulatory divergence between national data localization mandates and cross-border cloud processing needs.
Market Dynamics
Cloud migration is compressing hospital procurement timelines across Asia Pacific as legacy on-premises infrastructure reaches end-of-life cycles and IT budgets reallocate toward operational expenditure models.
Growth Catalysts
- Japan's PMDA data integrity standards:These frameworks mandate validated analytics pipelines, compelling hospital networks to upgrade from spreadsheet-based reporting to certified enterprise platforms.
- Real-time patient monitoring integration:IoT-enabled bedside devices stream continuous vitals data, requiring predictive analytics infrastructure that hospitals now prioritize in capital planning.
- Australia's aged care procurement:Government-funded residential care facilities are consolidating vendor relationships for population health dashboards, creating concentrated demand pockets in Sydney and Melbourne hospital networks.
Market Restraints
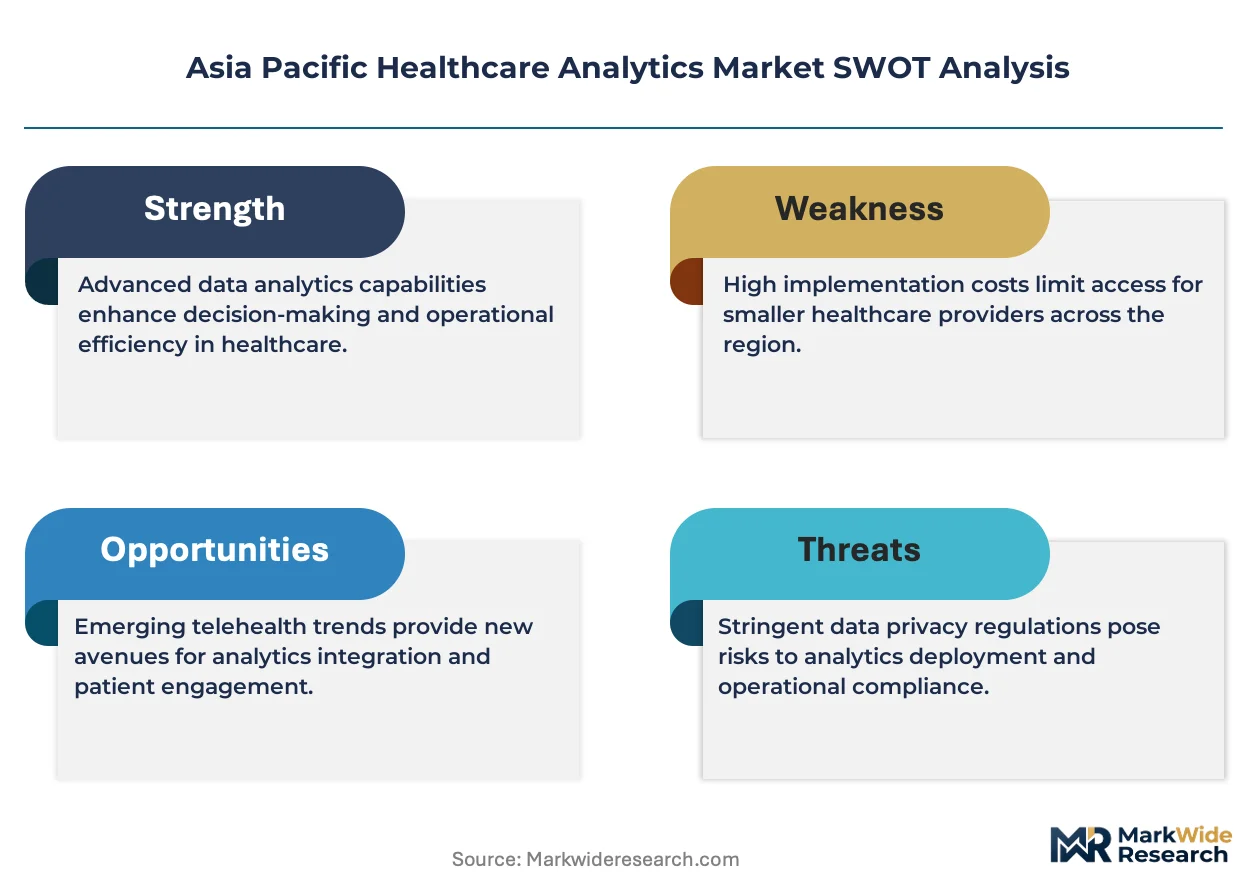
- Data localization mandates:India's proposed data protection framework and China's cybersecurity law require domestic server infrastructure, fragmenting cloud economics for multinational analytics vendors.
- Specialized clinical informaticist scarcity:Southeast Asian markets face acute shortages of professionals who bridge medical workflow knowledge with statistical programming capabilities.
- Legacy EHR interoperability gaps:Proprietary data formats from dominant hospital information system vendors in South Korea and Thailand resist standardized API integration.
Strategic Opportunities
- Vietnam's hospital digitization wave:Public-private partnership models for tertiary care construction include bundled analytics procurement, opening greenfield deployment opportunities.
- AI Act algorithmic transparency requirements:EU extraterritorial rules create competitive differentiation for vendors who pre-certify explainable machine learning models for export-oriented hospital chains.
- Telehealth-triage convergence:Integration of remote consultation platforms with automated severity scoring algorithms enables new subscription revenue streams for platform providers.
Industry Challenges
- Multi-year validation timelines:Australia's TGA software-as-medical-device classification process extends commercialization cycles for predictive diagnostic algorithms.
- Interoperability standard fragmentation:Competing health data exchange protocols across Japan, South Korea, and Australia force vendors to maintain parallel integration teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Healthcare Analytics Market |
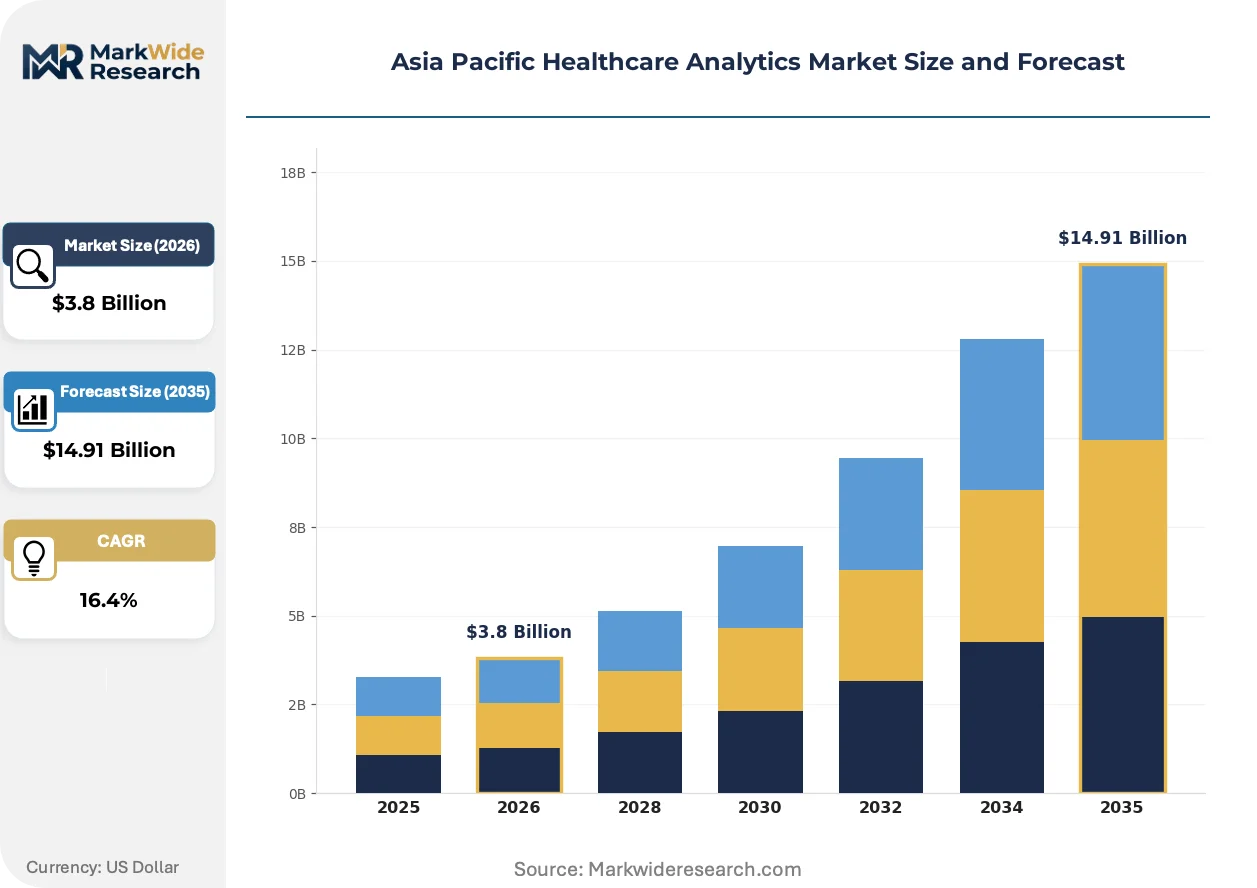
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Patient Care, Financial Analytics, Operations Management, Population Health Technology: Artificial Intelligence, Big Data, Cloud Computing, Machine Learning End User: Hospitals, Clinics, Pharmacies, Research Institutions Delivery Mode: On-Premises, Cloud-Based, Hybrid, Mobile Applications |
| Companies Covered | Optum Inc., SAS Institute Inc., IBM Corporation, Oracle Corporation, Cerner Corporation, Merative, McKesson Corp, IQVIA Holdings Inc, CitiusTech Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Healthcare Analytics Market Strategic Shifts
Artificial intelligence architectures are restructuring competitive positioning in Asia Pacific healthcare analytics as vendors race to embed generative capabilities into clinical decision support workflows.
Federated learning infrastructure is consolidating distributed model training across hospital networks without centralizing sensitive patient records. Australian cancer centers and Japanese university hospitals are piloting these privacy-preserving architectures for multi-site oncology research. This approach is consolidating vendor differentiation around data governance capabilities rather than raw algorithmic performance.
Japan's PMDA and Australia's TGA are tightening software validation requirements for machine learning-based diagnostic tools, forcing analytics vendors to maintain quality management systems comparable to medical device manufacturers. Hospital procurement departments in both markets now require ISO 13485 certification for predictive analytics modules, elevating compliance costs for smaller platform providers.
Subscription-based platform access is displacing perpetual license sales in Southeast Asian hospital procurement. Malaysian and Indonesian health systems favor operational expenditure models that bundle implementation, training, and continuous algorithm updates. Singapore's integrated care networks have pioneered this shift, with procurement teams now evaluating total cost of ownership over five-year horizons rather than upfront capital outlays.
Asia Pacific Healthcare Analytics Market Segmentation
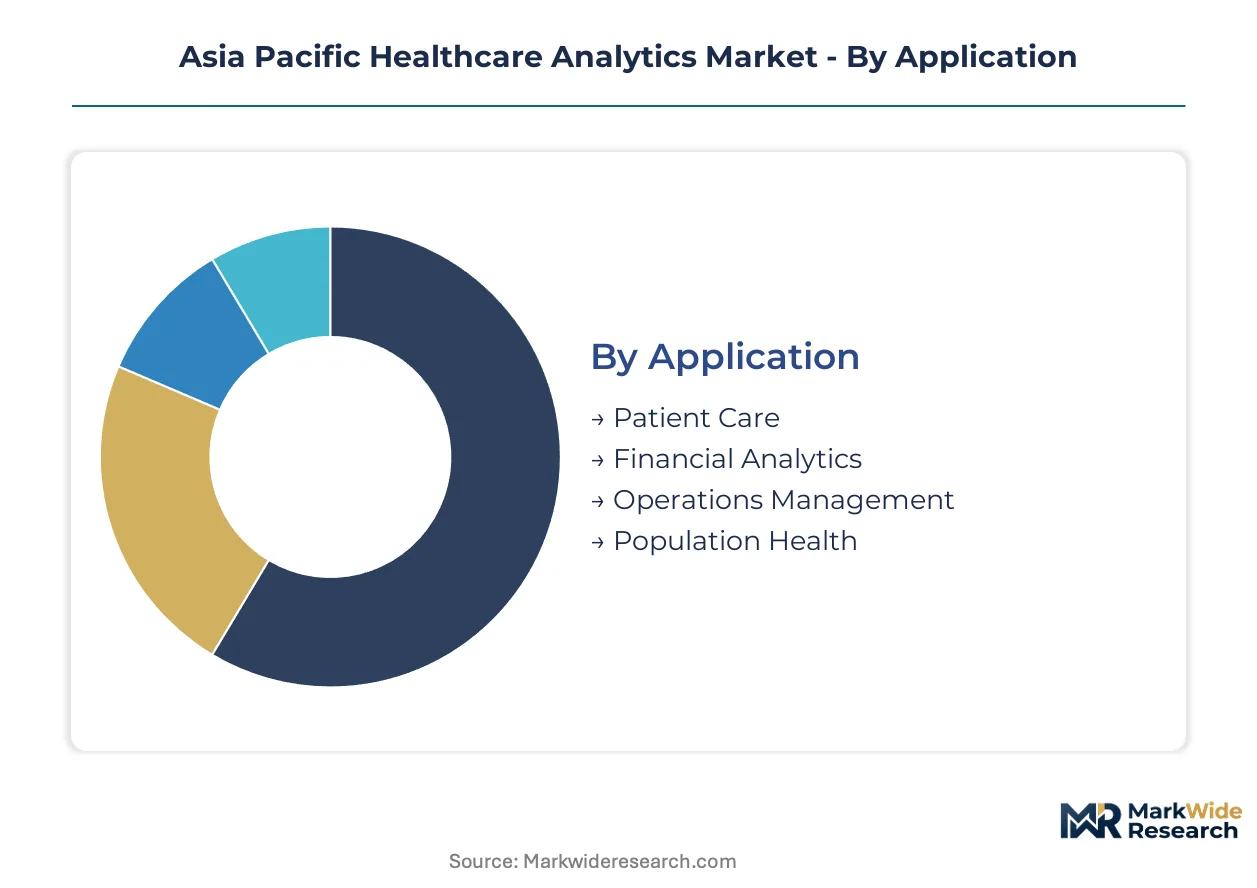
Healthcare analytics procurement in Asia Pacific fragments across four distinct dimensions. Application use cases determine workflow integration requirements. Technology stacks differentiate vendor capabilities. End-user scale shapes deployment economics. Delivery modes govern compliance architecture.
Application:
Supply concentration in patient care analytics has consolidated around Japanese and Australian hospital networks with validated enterprise platforms.
- Patient Care:Clinical decision support systems integrate real-time EHR data with predictive risk scoring. Australian tertiary hospitals and Japan's university medical centers dominate procurement volumes, driven by PMDA and TGA validation mandates for diagnostic algorithms.
- Financial Analytics:Revenue cycle management tools process claims data and optimize reimbursement workflows. India's expanding hospital networks under PLI scheme incentives represent concentrated demand growth as facilities upgrade from spreadsheet-based reporting.
- Operations Management:Resource allocation dashboards optimize bed utilization and staffing schedules across Southeast Asian health systems.
- Population Health:Disease surveillance platforms aggregate regional health data for government preventive care programs.
Today's leader: Patient Care. Tomorrow's challenger: Population Health.
Technology:
Cost tier stratification separates AI-enabled premium platforms from standardized big data infrastructure.
- Artificial Intelligence:Generative clinical documentation and diagnostic imaging analysis command highest R&D investment. Australia's TGA software-as-medical-device classifications and Japan's PMDA algorithm validation requirements concentrate vendor compliance spending in these markets.
- Machine Learning:Predictive models for readmission risk and sepsis detection deploy across cloud and edge architectures. Singapore's integrated care networks and South Korean hospital systems drive adoption through bundled procurement of continuous learning platforms.
- Big Data:Distributed processing frameworks handle batch analytics for historical population studies.
- Cloud Computing:Scalable infrastructure underpins subscription-based delivery models displacing perpetual licenses.
AI and machine learning platforms absorb disproportionate capital allocation, though cloud infrastructure enables margin expansion through operational expenditure conversion.
End User:
Volume concentration in hospital procurement creates tiered vendor engagement strategies.
- Hospitals:Enterprise-scale deployments require ISO 13485-certified analytics modules for predictive diagnostics. Australia's aged care procurement programs and Japan's PMDA-mandated upgrades sustain concentrated demand for validated platforms.
- Clinics:Ambulatory settings prioritize lightweight cloud solutions with rapid implementation timelines.
- Pharmacies:Inventory optimization and patient adherence analytics gain traction under India's PLI pharmaceutical incentives.
- Research Institutions:Federated learning pilots across Australian cancer centers and Japanese university hospitals drive privacy-preserving architecture development.
Hospital procurement governs current revenue concentration. Research institutional pilots signal next-generation platform requirements.
Delivery Mode:
Maturity gradients separate legacy on-premises installations from cloud-native deployments.
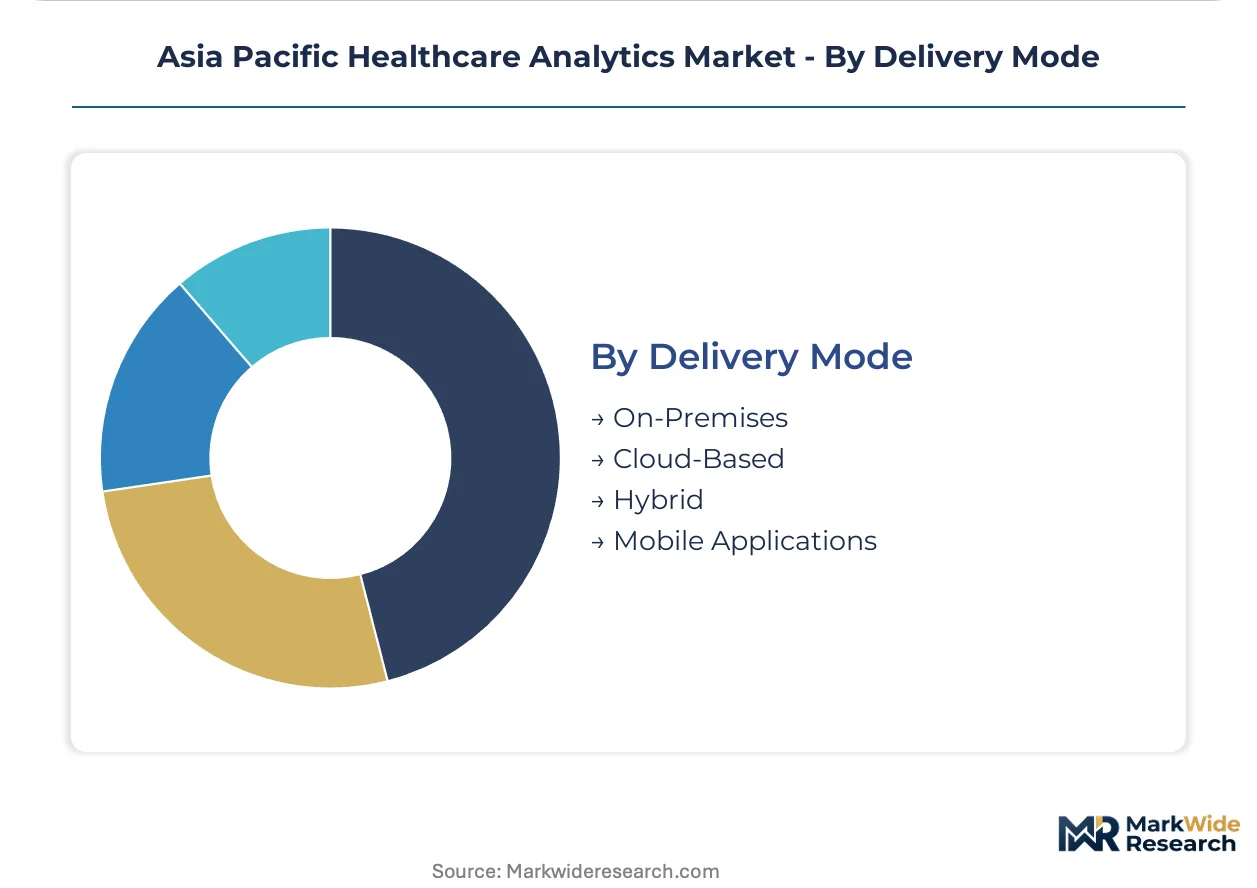
- Cloud-Based:Operational expenditure models bundle implementation, training, and algorithm updates. Malaysia and Indonesia favor subscription structures, while Singapore's integrated networks evaluate five-year total cost of ownership.
- Hybrid:Split architectures accommodate India's proposed data localization mandates and China's cybersecurity law requirements, fragmenting economics for multinational vendors.
- On-Premises:Legacy infrastructure persists in South Korean and Thai hospitals with proprietary EHR formats resisting API standardization.
- Mobile Applications:Point-of-care decision support extends analytics to bedside workflows and remote consultation platforms.
Cloud-based delivery is climbing the fastest. Hybrid architectures address regulatory fragmentation constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's hospital networks and aged care procurement programs anchor demand concentration in Asia Pacific healthcare analytics, with government-funded residential care facilities in Sydney and Melbourne driving validated platform adoption.
Japan
University medical centers and large hospital networks dominate procurement volumes for predictive diagnostic platforms. PMDA data integrity standards mandate validated analytics pipelines, compelling facilities to upgrade from spreadsheet-based reporting to certified enterprise systems. Tokyo and Osaka medical clusters concentrate deployment of clinical decision support infrastructure.
Australia
Tertiary hospitals and aged care facilities drive concentrated demand for population health dashboards and patient care analytics. TGA software-as-medical-device classifications extend commercialization timelines for predictive algorithms, favoring established vendors with quality management systems. Sydney and Melbourne hospital networks consolidate vendor relationships under government-funded procurement programs.
India
Expanding hospital networks under PLI scheme incentives represent accelerating demand for financial analytics and revenue cycle management tools. CDSCO and BIS frameworks govern medical device software classifications affecting market access pathways. Bangalore and Hyderabad health systems upgrade from legacy reporting to cloud-based operational expenditure models.
Singapore
Integrated care networks pioneer subscription-based platform procurement with five-year total cost of ownership evaluations. Government preventive care programs fund population health analytics deployment across public health clusters. The city-state's procurement teams bundle implementation, training, and continuous algorithm updates in vendor contracts.
South Korea
Hospital systems drive adoption of machine learning platforms for predictive diagnostics and sepsis detection. MFDS regulatory frameworks and proprietary EHR formats from dominant hospital information system vendors resist standardized API integration. Seoul medical centers concentrate cloud migration initiatives as legacy infrastructure reaches end-of-life cycles.
Asia Pacific Healthcare Analytics Market Competitive Environment
Global majors compete with regional champions across cloud delivery modes and regulatory compliance capabilities, creating a tiered structure where enterprise-scale vendors with ISO 13485 certification command premium positioning in Japan and Australia. Three archetypes dominate: multinational cloud platforms with healthcare-specific modules, regional specialists with localized regulatory expertise, and research-institution spinoffs commercializing federated learning architectures. M&A activity concentrates around Cerner-type acquisitions for cloud infrastructure, while strategic partnerships address data localization mandates in fragmented Southeast Asian markets.
Within the multinational platform tier, IBM Corporation and Oracle Corporation exemplify enterprise-scale positioning, with the former leveraging Watson Health architecture and the latter anchoring deployments through cloud-based Cerner integration. Optum Inc. occupies a distinct position tied to UnitedHealth Group's regional data services footprint. These three companies represent contrasting approaches to regulatory compliance: IBM's PMDA-validated pipelines, Oracle's hybrid cloud architectures for data localization, and Optum's integrated payer-provider data networks.
| Leading Market Players |
|---|
| Optum Inc. |
| SAS Institute Inc. |
| IBM Corporation |
| Oracle Corporation |
| Cerner Corporation |
| Merative |
| McKesson Corp |
| IQVIA Holdings Inc |
| CitiusTech Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification ladders bifurcate vendor economics across Asia Pacific healthcare analytics, with certified enterprise platforms commanding premium subscription rates while uncertified competitors absorb margin compression from Japan's PMDA and Australia's TGA validation mandates. This tier divergence manifests in procurement timelines: validated vendors secure multi-year hospital contracts while non-certified suppliers compete on price for clinic-tier deployments, with cloud infrastructure costs further stratifying supply chain configurations between hybrid and pure-play delivery models.
Pricing Analysis
Input-cost pass-through from ISO 13485 quality management system investments flows into subscription pricing for predictive diagnostic modules, particularly in Japan and Australia where TGA and PMDA software-as-medical-device classifications mandate certified pipelines. Three-tier pricing structure across certified enterprise, standard cloud, and economy clinic levels separates vendors by validation depth and implementation bundling. Pricing pressure stems from Southeast Asian procurement teams favoring operational expenditure models that compress vendor margins through continuous algorithm update obligations. Hospital networks in Sydney and Tokyo demonstrate lowest price sensitivity due to government-funded procurement programs, while Indonesian and Malaysian clinics prioritize rapid deployment over certification depth.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise-scale demand from Australia's aged care procurement programs and Japan's university medical centers, while distributor partnerships serve clinic-tier volumes across Southeast Asia. Cloud infrastructure supply concentrates in Singapore, Australia, and Japan, with hybrid architectures fragmenting economics for vendors serving India's data localization mandates and China's cybersecurity requirements. Raw material dependencies span GPU compute clusters, federated learning middleware, and FHIR-compliant API frameworks. Single-source vulnerability runs through proprietary EHR formats from dominant hospital information system vendors in South Korea and Thailand, which resist standardized integration. Distribution runs through GPO contracts in Australian hospital networks and direct vendor relationships in Singapore's integrated care systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific healthcare analytics functions as a stable compounder, with government-funded hospital digitization programs across Australia, Japan, and Singapore providing predictable procurement pipelines that sustain vendor revenue visibility.
For Market Incumbents: Acquire federated learning architecture capabilities to defend against research-institution spinoffs commercializing privacy-preserving analytics. PMDA and TGA validation requirements create moats that smaller competitors cannot bridge without multi-year quality management investments. Backward integration into cloud infrastructure operations secures margin control as subscription models displace perpetual licenses.
For New Entrants and Emerging Players: Launch via public-private partnership bundled procurement in Vietnam's tertiary care construction wave, where greenfield hospital deployments include analytics infrastructure in initial capital planning. White-space concentration appears in telehealth-triage convergence platforms for Indonesian and Malaysian clinic networks, with lightweight cloud solutions penetrating faster than enterprise-grade alternatives. Target operational expenditure procurement teams evaluating five-year total cost of ownership rather than upfront capital outlays.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification requirements exceed capital access for mid-tier platform providers, particularly in predictive diagnostic segments facing Japan's PMDA algorithm validation mandates. Long-term viability favors vendors with hybrid cloud architectures addressing data localization fragmentation across India and China. Acquisition target archetype: regional specialists with localized regulatory expertise and existing hospital network relationships. Signal to watch: TGA software-as-medical-device classification timeline extensions that accelerate vendor attrition.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | PMDA and TGA mandates elevate compliance barriers for predictive diagnostic modules in Japan and Australia. |
| Hybrid Cloud Architecture Deployment | India's proposed data localization framework and China's cybersecurity law fragment pure-play cloud economics. |
| Federated Learning Platform Development | Australian cancer centers and Japanese university hospitals pilot privacy-preserving multi-site research infrastructure. |
| Subscription Model Transition | Singapore's integrated care networks evaluate five-year total cost of ownership, displacing perpetual licenses. |
| Telehealth-Triage Integration | Remote consultation platforms with automated severity scoring enable new recurring revenue streams in Southeast Asia. |
Study Parameters
Direct dialogue with hospital procurement managers, clinical informaticists, cloud platform engineers, and regulatory affairs specialists across Tokyo, Sydney, Singapore, and Bangalore grounded qualitative insights. Secondary validation drew from TGA software classification databases, PMDA algorithm validation guidelines, hospital GPO contract disclosures, and ASEAN health digitization policy frameworks. Bottom-up deployment modeling triangulated against top-down healthcare IT expenditure forecasts from national statistical agencies.
Bottom-up analysis aggregated hospital-level procurement patterns across application segments, technology tiers, and delivery modes, while top-down approaches validated aggregate market sizing against government health IT budget allocations. Segmentation dimensions spanned patient care versus population health applications, AI-enabled versus big data infrastructure, cloud versus hybrid deployment, and hospital versus clinic end-user scale. CAGRs derived from weighted regression of historical procurement velocity against policy-funded digitization timelines, with cloud migration curves and regulatory compliance cost trajectories as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA validation timeline extensions or India's data protection framework implementation delays. Projections assume sustained government funding for Australia's aged care analytics programs and Japan's hospital system upgrades. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Cardiology Information System Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare API Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Healthcare BI Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
USA Electronic Health Records (EHR) Market