
 Pharmaceutical Regulatory Affairs Market | 2026-2036
Pharmaceutical Regulatory Affairs Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Regulatory Affairs Market Analytics
Specialized regulatory talent is rotating toward digital submission platforms and eCTD expertise, tightening labor pools for traditional paper-based compliance roles. IQVIA leverages its integrated data and regulatory infrastructure to anchor large-scale pharmaceutical submissions across multiple jurisdictions. Parexel International sustains competitive positioning through deep therapeutic specialization in oncology and rare disease pathways. ICON plc differentiates by embedding regulatory strategy into clinical trial design from protocol inception.
Pharmaceutical regulatory affairs encompasses the scientific, legal, and administrative processes required to demonstrate product quality, safety, and efficacy to health authorities prior to market authorization, with eCTD formatting and e-submission validation serving as core technical parameters. The discipline ensures compliance with evolving pharmacovigilance obligations and lifecycle management requirements across geographically fragmented approval frameworks. Clinical Trials applications command premium service margins due to protocol complexity and real-time regulatory interaction demands, while Post-Market Surveillance represents the fastest-expanding segment as pharmacovigilance outsourcing accelerates. Regulatory Compliance Software within the technology dimension is displacing legacy document management approaches as FDA mandates for structured data intensify.
FDA's eCTD 4.0 mandate and EMA's SPOR data management framework are reshaping submission infrastructure requirements, forcing service providers to retool technology stacks or risk disqualification from sponsor shortlists. The EU AI Act and FDA's emerging guidance on machine-learning-enabled drug discovery are introducing novel compliance categories that demand cross-functional legal-technical expertise. Stakeholders must monitor how health authority convergence on real-world evidence standards alters the boundary between clinical development and post-approval regulatory obligations.
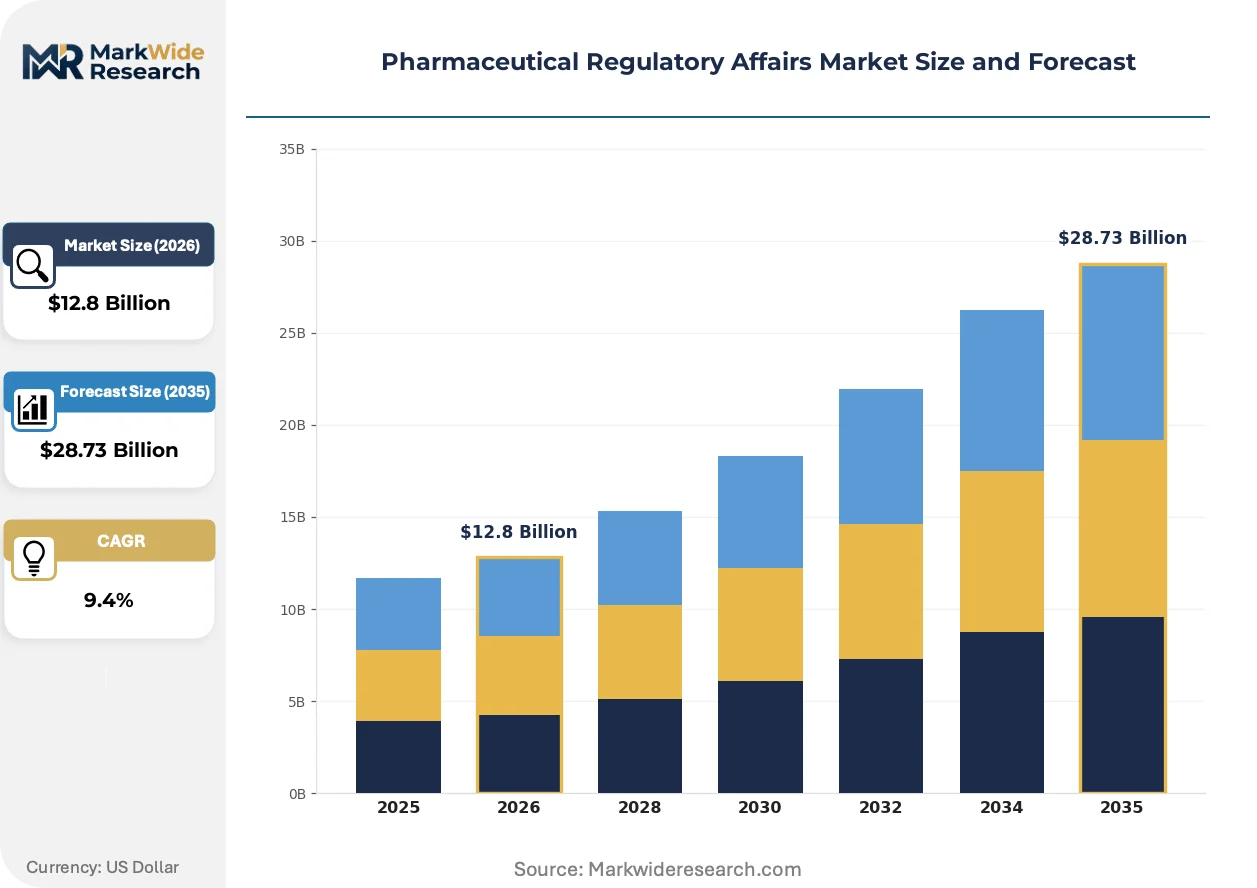
Market Dynamics
eCTD 4.0 mandates from FDA and EMA's SPOR framework are forcing service providers to rebuild submission infrastructure, concentrating contract awards among technology-capable vendors while squeezing traditional document-heavy consultancies.
Growth Catalysts
- EMA SPOR Data Standards:The Substance, Product, Organization and Referential framework compels sponsors to standardize master data, creating sustained demand for data governance and IDMP compliance services across European submissions.
- Oncology Pipeline Expansion:Breakthrough therapy designations and accelerated approval pathways for immuno-oncology agents require specialized regulatory strategists who navigate complex biomarker qualification and adaptive trial protocols.
- Real-World Evidence Integration:FDA's expanding acceptance of RWE for supplemental indications drives investment in observational study design and external control arm methodologies for post-market commitments.
Market Restraints
- Specialized Talent Scarcity:eCTD technical specialists and pharmacovigilance physicians command compensation premiums that compress service margins, particularly in mid-tier consultancies without scale advantages.
- Technology Retooling Costs:Validation engine upgrades and cloud-based submission platform migrations require seven-figure capital commitments that disadvantage smaller regulatory service providers.
- Health Authority Divergence:Misaligned eCTD implementation timelines between FDA, EMA, and PMDA force sponsors to maintain parallel submission formats, inflating operational complexity.
Strategic Opportunities
- Cell and Gene Therapy Submissions:CBER's emerging guidance framework for lentiviral vectors and CRISPR-based therapeutics creates first-mover advantage for regulatory shops building viral vector CMC expertise.
- Combination Product Pathways:Device-drug convergence under FDA's OCP jurisdiction demands cross-functional teams spanning 510(k), PMA, and NDA regulations, a capability gap in pure-play CROs.
- Pharmacovigilance Outsourcing:Biotech sponsors without in-house safety databases are contracting aggregate reporting and signal detection to specialized vendors, expanding addressable market beyond traditional registration services.
Industry Challenges
- Legacy System Integration:Sponsor IT environments with decades of paper-based regulatory archives resist full digitization, complicating eCTD 4.0 backfile conversion and lifecycle management.
- Cross-Functional Talent Synthesis:Regulatory strategists must now command data science literacy, legal expertise on EU AI Act implications, and therapeutic area depth simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Regulatory Affairs Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Drug Development, Market Authorization, Post-Market Surveillance, Clinical Trials End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Consulting Firms Service Type: Consultation Services, Submission Services, Audit Services, Training Services Technology: Data Management Systems, Regulatory Compliance Software, Document Management Systems, Workflow Automation Tools |
| Companies Covered | ProPharma Group, Parexel International, PharmaLex, Freyr, IQVIA, ICON plc, Criterium, Labcorp Drug Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Regulatory Affairs Market Evolving Landscape
Submission technology and health authority data requirements are converging to reshape competitive positioning in regulatory services, with automation and structured data mandates compressing timelines for traditional consulting models.
Artificial intelligence-enabled document authoring platforms are fragmenting the regulatory writing market by automating routine CMC and clinical summary generation, allowing sponsors to redeploy medical writers toward strategic health authority negotiations and complex response-to-questions preparation.
FDA's emerging guidance on machine-learning-enabled drug discovery introduces novel validation requirements for algorithm training datasets and model interpretability, compelling regulatory consultants to develop cross-functional expertise spanning biostatistics, software quality assurance, and traditional clinical development.
Biotech procurement teams are unbundling regulatory services from full-service CRO contracts, establishing direct relationships with specialized regulatory consultancies for IND-enabling activities while retaining clinical operations with larger vendors, a pattern most visible among Boston and San Francisco venture-backed sponsors.
Pharmaceutical Regulatory Affairs Market Segmentation
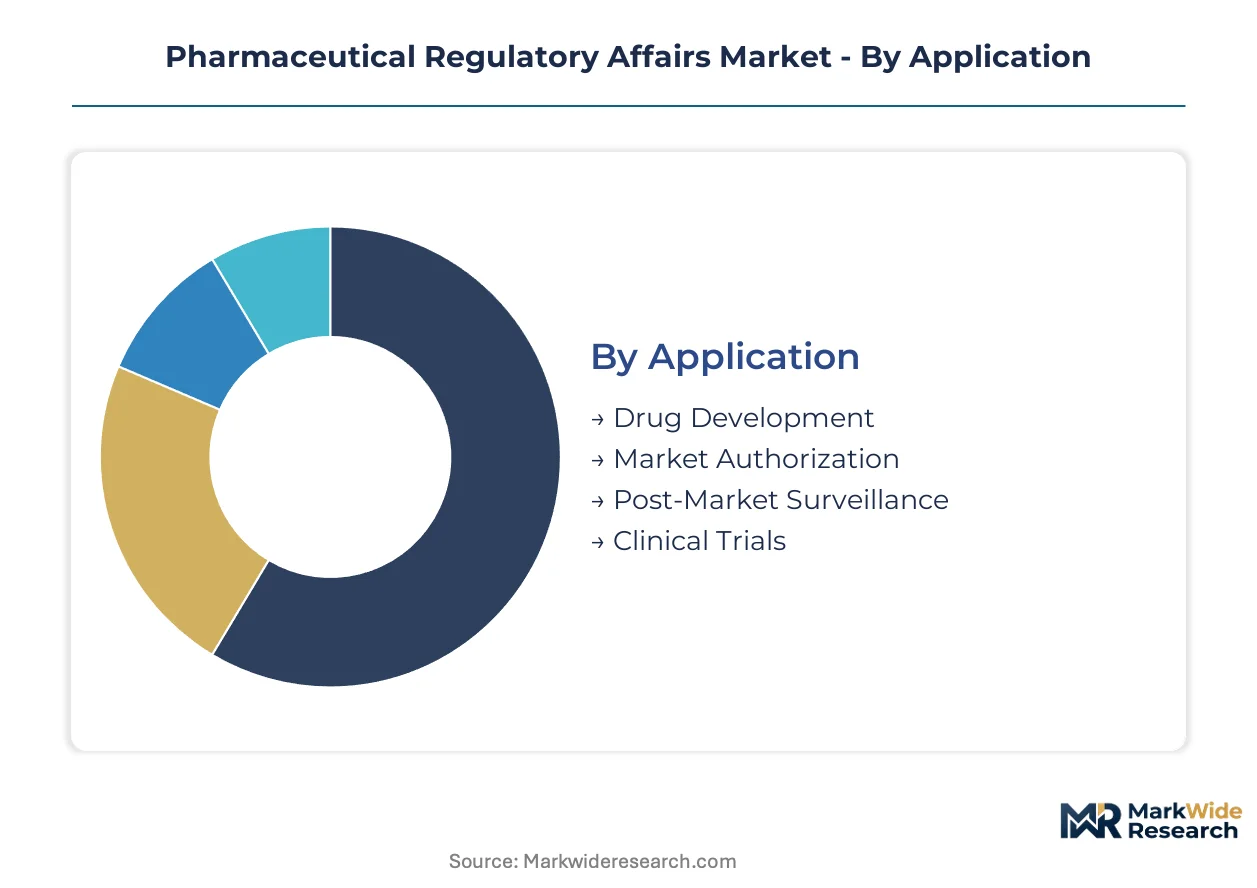
Regulatory service procurement follows distinct channel patterns shaped by sponsor size and therapeutic complexity. Understanding segment boundaries reveals where contract awards concentrate and which capabilities command premium positioning.
Application:
Service flows diverge sharply across application types, with large pharma routing complex submissions through integrated vendors while biotech sponsors unbundle discrete regulatory milestones.
- Drug Development:Pre-IND and IND-enabling activities span CMC strategy, toxicology consultation, and early-phase protocol design. Demand concentrates among Boston and San Francisco venture-backed sponsors seeking specialized regulatory shops for first-in-human filings.
- Clinical Trials:Protocol-level regulatory interaction demands real-time health authority negotiation and adaptive design expertise. Sponsors with breakthrough therapy designations invest heavily here to maintain accelerated approval timelines.
- Market Authorization:NDA and BLA compilation requires cross-functional CMC, clinical, and labeling integration.
- Post-Market Surveillance:Pharmacovigilance outsourcing and periodic safety reporting dominate biotech procurement.
By volume, Clinical Trials leads application spending. By growth pace, Post-Market Surveillance is climbing the fastest as lifecycle management obligations expand.
End User:
Customer archetypes stratify by internal capability depth, determining whether regulatory functions stay captive or flow to external specialists.
- Pharmaceutical Companies:Large sponsors maintain in-house regulatory affairs departments for core submissions while outsourcing specialized geographies or novel modalities. Internal teams at Pfizer and Roche-scale organizations handle FDA interactions directly.
- Biotech Firms:Development-stage companies without regulatory infrastructure depend entirely on contracted expertise for IND preparation and health authority meetings. Cell and gene therapy developers show particular reliance on viral vector CMC consultants.
- Contract Research Organizations:Full-service CROs embed regulatory strategy within clinical operations.
- Consulting Firms:Pure-play regulatory boutiques capture unbundled procurement from biotech sponsors.
Pharmaceutical Companies anchor absolute spending. Biotech Firms are gaining share fastest as venture funding concentrates in development-stage therapeutics.
Service Type:
Margin profiles vary dramatically across service archetypes, with transactional submission work compressing while strategic consultation holds pricing power.
- Consultation Services:Strategic regulatory planning, health authority meeting preparation, and response-to-questions strategy command premium rates due to specialized therapeutic expertise requirements. Oncology and rare disease specialists extract the highest fees.
- Submission Services:eCTD compilation, publishing, and validation represent high-volume, price-competitive work where technology-enabled vendors displace traditional document shops. FDA eCTD 4.0 mandates favor providers with validated cloud infrastructure.
- Audit Services:Mock inspections and compliance gap assessments support sponsor readiness programs.
- Training Services:eCTD technical certification and pharmacovigilance curriculum address talent pipeline gaps.
Submission Services dominates transaction volume. Consultation Services shows the steepest expansion trajectory as strategic advisory unbundles from full-service contracts.
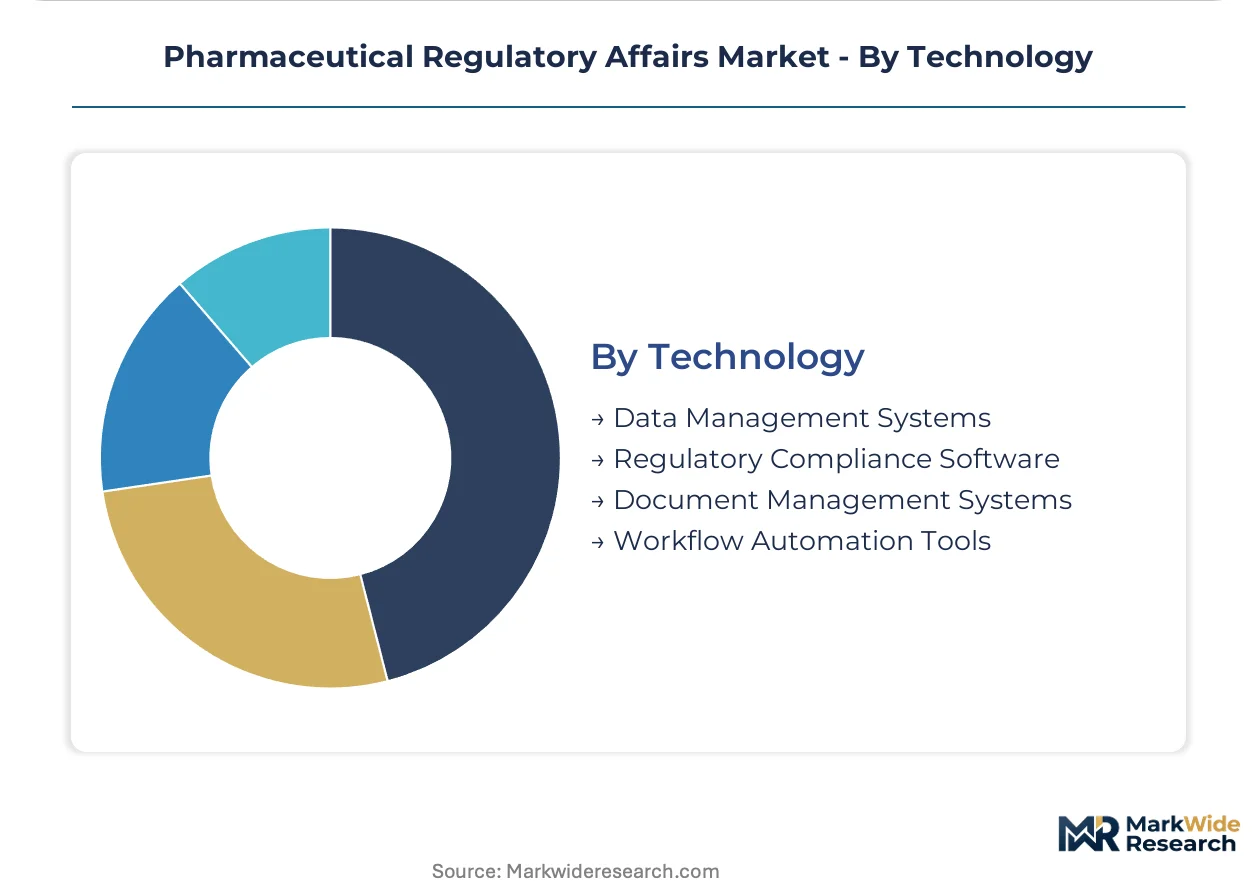
Technology:
Technology procurement patterns reveal sponsor maturity, with sophisticated buyers investing in integrated platforms while smaller players adopt point solutions.
- Regulatory Compliance Software:Structured data platforms for IDMP compliance and eCTD lifecycle management displace legacy document repositories. EMA SPOR framework mandates drive replacement cycles among European-focused sponsors.
- Data Management Systems:Clinical and safety data integration supports RWE generation and pharmacovigilance signal detection. FDA's expanding RWE acceptance elevates demand for observational study infrastructure.
- Document Management Systems:Version-controlled regulatory archives enable eCTD backfile conversion.
- Workflow Automation Tools:AI-enabled document authoring fragments the regulatory writing market.
Data Management Systems leads current installed base. Regulatory Compliance Software is expanding most quickly as health authority mandates force infrastructure replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA submission volumes anchor North American demand as combination product pathways and accelerated approval mechanisms concentrate service investment. Regulatory complexity across eCTD 4.0 mandates and pharmacovigilance obligations fragments operational requirements by jurisdiction.
United States
Cell and gene therapy developers in Greater Boston and San Francisco drive specialized regulatory procurement for CBER submissions. FDA's eCTD 4.0 mandate forces sponsors to rebuild validation infrastructure. The Research Triangle Park cluster anchors pharmacovigilance outsourcing operations for mid-tier biotech sponsors.
Germany
EMA SPOR framework implementation compels German sponsors to standardize master data for IDMP compliance. The country's national pharmaceutical regulator aligns with centralized European procedures while maintaining national variation pathways. Frankfurt and Munich host regulatory service hubs serving DACH-region biopharma operations.
Switzerland
Swissmedic's streamlined approval procedures attract global headquarters seeking concurrent EU-Swiss submissions. Basel's pharmaceutical cluster generates concentrated demand for regulatory strategy and health authority meeting preparation. Roche and Novartis-scale organizations maintain captive regulatory affairs departments handling FDA interactions directly.
United Kingdom
MHRA independent procedures post-Brexit create parallel submission requirements for UK market access. London's regulatory consultancies specialize in bridging EU-UK divergence for orphan drug designations. The Golden Triangle biotech corridor drives unbundled procurement of IND-enabling regulatory services.
India
CDSCO's expanding bioequivalence standards and biosimilar guidelines create export-oriented regulatory documentation demand. Hyderabad and Bengaluru clusters host contract regulatory shops serving US and EU submission requirements. Domestic pharma sponsors invest in eCTD capabilities to access accelerated approval pathways.
Pharmaceutical Regulatory Affairs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the regulatory services value chain. Integrated data and clinical infrastructure providers capture large-scale pharmaceutical submissions spanning multiple jurisdictions. Pure-play regulatory boutiques and full-service CROs represent distinct strategic archetypes. Competitive moves concentrate on technology platform acquisitions and therapeutic specialization depth.
Among integrated infrastructure providers, IQVIA anchors large-scale submissions through combined data and regulatory capabilities. Parexel International exemplifies therapeutic specialization positioning in oncology and rare disease pathways. ICON plc occupies a position embedding regulatory strategy into clinical trial design from protocol inception. These three represent contrasting approaches to unbundling pressure from biotech procurement teams.
| Leading Market Players |
|---|
| ProPharma Group |
| Parexel International |
| PharmaLex |
| Freyr |
| IQVIA |
| ICON plc |
| Criterium |
| Labcorp Drug Development |
| Others |
Value Network & Pricing Analysis
FDA's eCTD 4.0 mandate gates vendor qualification and price differentiation simultaneously, concentrating contract awards among technology-capable providers while squeezing traditional document-heavy consultancies from sponsor shortlists. Sponsors now pay premiums for validated cloud infrastructure and cross-functional expertise spanning data science and therapeutic depth.
Pricing Analysis
Geographic price spreads widen between US-based regulatory strategists and India-based submission operations, with Boston and San Francisco biotech sponsors absorbing 40-60% cost premiums for FDA-facing health authority negotiation expertise. Three-tier pricing structure across premium, standard, and economy levels stratifies by therapeutic specialization depth, eCTD technical certification, and real-time regulatory interaction availability. Cost compression in transactional submission services intensifies because AI-enabled document authoring fragments the regulatory writing market. Small biotech firms without internal regulatory infrastructure exhibit highest price sensitivity, while large pharma sponsors with breakthrough therapy designations prioritize strategic advisory over unit cost.
Supply Chain Analysis
India and the United States anchor global regulatory service delivery, with Hyderabad and Bengaluru clusters handling eCTD compilation and publishing while Greater Boston and San Francisco concentrate strategic health authority meeting preparation. Raw material dependencies center on specialized pharmacovigilance physicians, eCTD technical specialists, and cross-functional talent synthesizing data science literacy with legal expertise. Single-source vulnerability concentrates in cloud-based submission platform providers, where seven-figure validation engine upgrades create switching costs. Distribution runs through direct procurement relationships between biotech sponsors and specialized regulatory boutiques, bypassing full-service CRO intermediaries for IND-enabling milestones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical regulatory affairs sits in early-cycle expansion as pharmacovigilance outsourcing accelerates beyond traditional registration services, with biotech procurement teams unbundling regulatory milestones from full-service contracts.
For Market Incumbents: Compound technology leadership through acquisition of AI-enabled document authoring platforms and validated cloud infrastructure, defending against pure-play regulatory boutiques capturing unbundled biotech procurement. Vertical integration into pharmacovigilance signal detection capabilities anchors lifecycle management relationships beyond one-time submissions. For New Entrants and Emerging Players: Anchor in cell and gene therapy regulatory consulting, where CBER's emerging guidance framework for lentiviral vectors and CRISPR-based therapeutics creates first-mover advantage for viral vector CMC expertise. Target Boston and San Francisco venture-backed sponsors seeking specialized shops for first-in-human IND filings, with go-to-market positioning around accelerated approval pathway navigation. For Investors and Strategic Acquirers: FDA's eCTD 4.0 mandate reshapes the acquisition landscape toward technology-enabled vendors with validated infrastructure, compressing valuations for traditional document-heavy consultancies. Long-term viability favors targets combining therapeutic specialization depth with data governance capabilities. Monitor health authority convergence on real-world evidence standards as the inflection indicator for observational study infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Platform Acquisition | FDA eCTD 4.0 validation requirements disqualify legacy document shops from sponsor shortlists. |
| Therapeutic Specialization Depth Buildout | Oncology and rare disease expertise commands premium rates in breakthrough therapy designations. |
| Pharmacovigilance Outsourcing Expansion | Biotech sponsors without safety databases contract aggregate reporting to specialized vendors. |
| Cross-Functional Talent Synthesis | EU AI Act compliance demands simultaneous legal-technical-biostatistical expertise in regulatory teams. |
| Real-World Evidence Infrastructure Investment | FDA's expanding RWE acceptance elevates observational study design capabilities in competitive positioning. |
Research Methodology
A spread of perspectives from regulatory affairs directors, drug development executives, pharmacovigilance physicians, and biotech procurement leads converged on the working assumptions underlying this analysis. Primary interviews with health authority meeting specialists and eCTD technical consultants combined with secondary validation against FDA filings, EMA SPOR framework documentation, ClinicalTrials.gov records, and sponsor 10-K disclosures. Bottom-up service provider revenue estimates and top-down market sizing triangulated across the analysis window.
Segmentation dimensions modeled include service type, application, end user, technology procurement pattern, and regional regulatory cluster complexity. CAGRs derived from historical trajectory analysis and forward-looking penetration assumptions for pharmacovigilance outsourcing and AI-enabled document authoring. Industry-specific forecast inputs incorporate pipeline data for cell and gene therapy submissions and health authority mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued FDA-EMA regulatory convergence and sustained biotech venture funding concentration; material deviation in health authority data standard alignment or sponsor unbundling velocity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Italy Operations Service Consulting Market