
 Global Medical Device Regulatory Affairs Outsourcing Market | 2026-2036
Global Medical Device Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Regulatory Affairs Outsourcing Market Foresight
Multi-sourced regulatory partnerships is realigning how device makers manage global market access. IQVIA leverages its integrated clinical-regulatory data infrastructure to anchor large-scale outsourcing engagements across multiple jurisdictions. Emergo by UL competes through deep notified body relationships and technical file compilation expertise in European markets. Freyr differentiates via fixed-fee regulatory intelligence platforms that reduce submission cycle variability for mid-tier manufacturers.
Medical device regulatory affairs outsourcing encompasses the delegation of compliance planning, dossier preparation, quality system maintenance, and authority negotiation to external specialists rather than internal staff. The practice centers on navigating technical documentation requirements, risk management file alignment to ISO 14971, and post-market surveillance obligations across divergent national frameworks. Regulatory strategy and submission management services command premium engagement terms due to their direct impact on time-to-market and approval probability. Project-based contracts dominate early-stage device companies seeking milestone-gated regulatory support, while retainer structures prevail among established manufacturers with recurring global portfolio maintenance needs.
FDA's Quality System Regulation, the EU Medical Device Regulation, and Japan's PMDA consultation pathways collectively determine outsourcing intensity by jurisdiction. ISO 13485 certification requirements and MDR technical documentation standards raise barriers that specialized providers alone can navigate efficiently for smaller manufacturers. Stakeholders must monitor notified body capacity expansion rates and FDA's anticipated harmonization with international medical device regulators to calibrate their internal-versus-external regulatory resource mix.
Market Dynamics
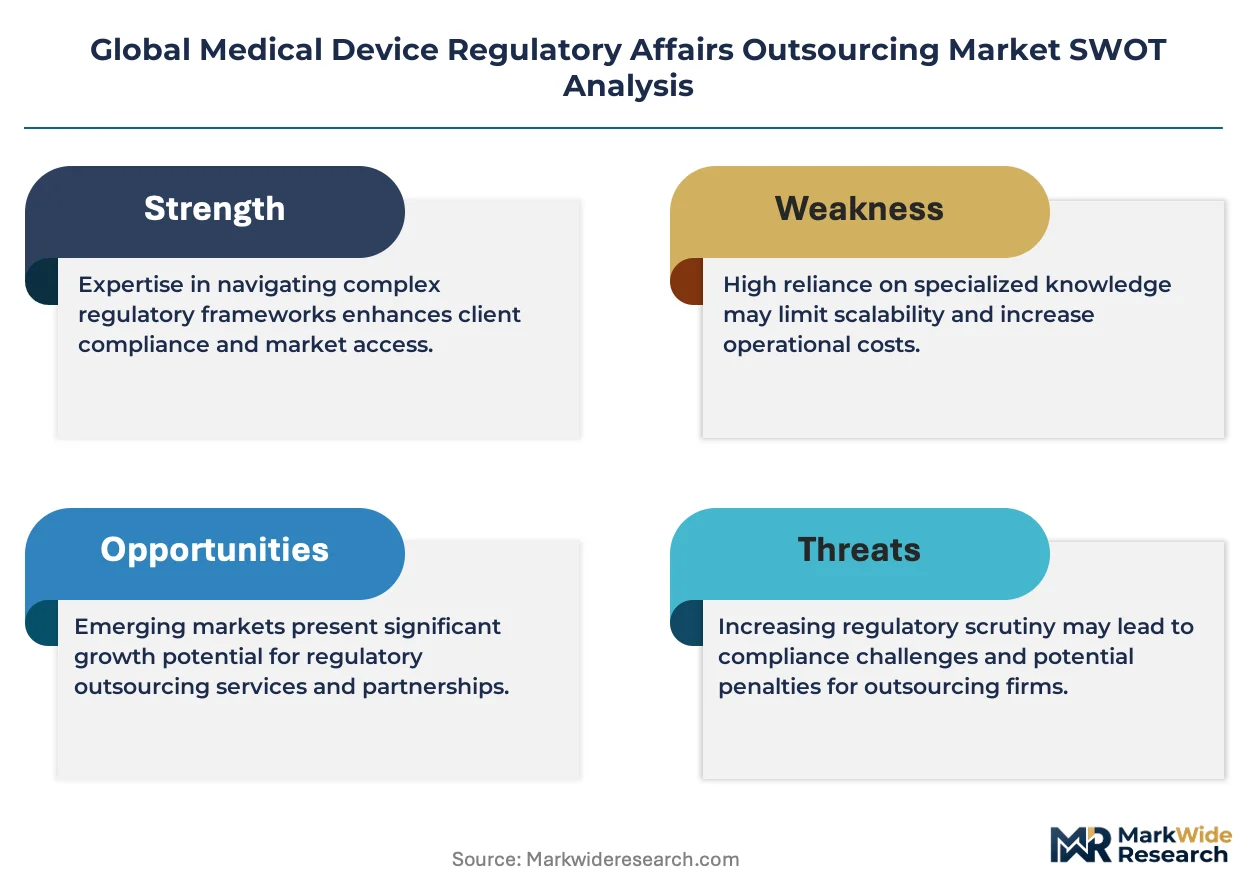
Notified body capacity constraints across the European Union are forcing Class II and III device manufacturers to externalize regulatory functions rather than build internal capabilities that cannot scale across jurisdictions.
Growth Catalysts
- EU MDR Technical Documentation Complexity:The expanded clinical evidence requirements under the Medical Device Regulation push manufacturers toward specialized partners capable of navigating notified body variability.
- Software as Medical Device (SaMD) Proliferation:FDA's evolving digital health guidance creates compliance gaps that internal teams cannot bridge without external machine-learning validation expertise.
- China Localization Mandates:NMPA's in-country testing and Mandarin documentation requirements compel foreign manufacturers to engage local regulatory representation.
Market Restraints
- Notified Body Bottleneck:The finite pool of EU-MDR designated bodies creates submission queues that delay outsourcing contract initiation regardless of provider capacity.
- Intellectual Property Exposure:Technical file handoffs to external partners risk core device design disclosure in competitive therapeutic categories.
- Specialized Talent Scarcity:The shallow labor pool for dual-qualified regulatory-technical professionals inflates outsourcing contract rates beyond mid-tier manufacturer budgets.
Strategic Opportunities
- Japan PMDA Pre-Submission Pathways:The structured consultation system creates demand for regulatory partners who can navigate Science Table meetings and accelerate novel device approvals.
- Combination Product Convergence:Drug-device integration under FDA's Office of Combination Products jurisdiction requires hybrid regulatory expertise that pure-play CROs cannot deliver.
- Post-Market Surveillance Automation:AI-enabled vigilance reporting platforms offer outsourcing providers a recurring revenue model beyond one-time submission support.
Industry Challenges
- Legacy Quality System Integration:Manufacturers running pre-ISO 13485:2016 quality management systems face friction when outsourcing partners demand harmonized documentation formats.
- Multi-Jurisdiction Timeline Coordination:Synchronizing FDA 510(k) clearance with EU MDR certification and NMPA registration creates resource allocation conflicts across parallel workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Regulatory Affairs Outsourcing Market |
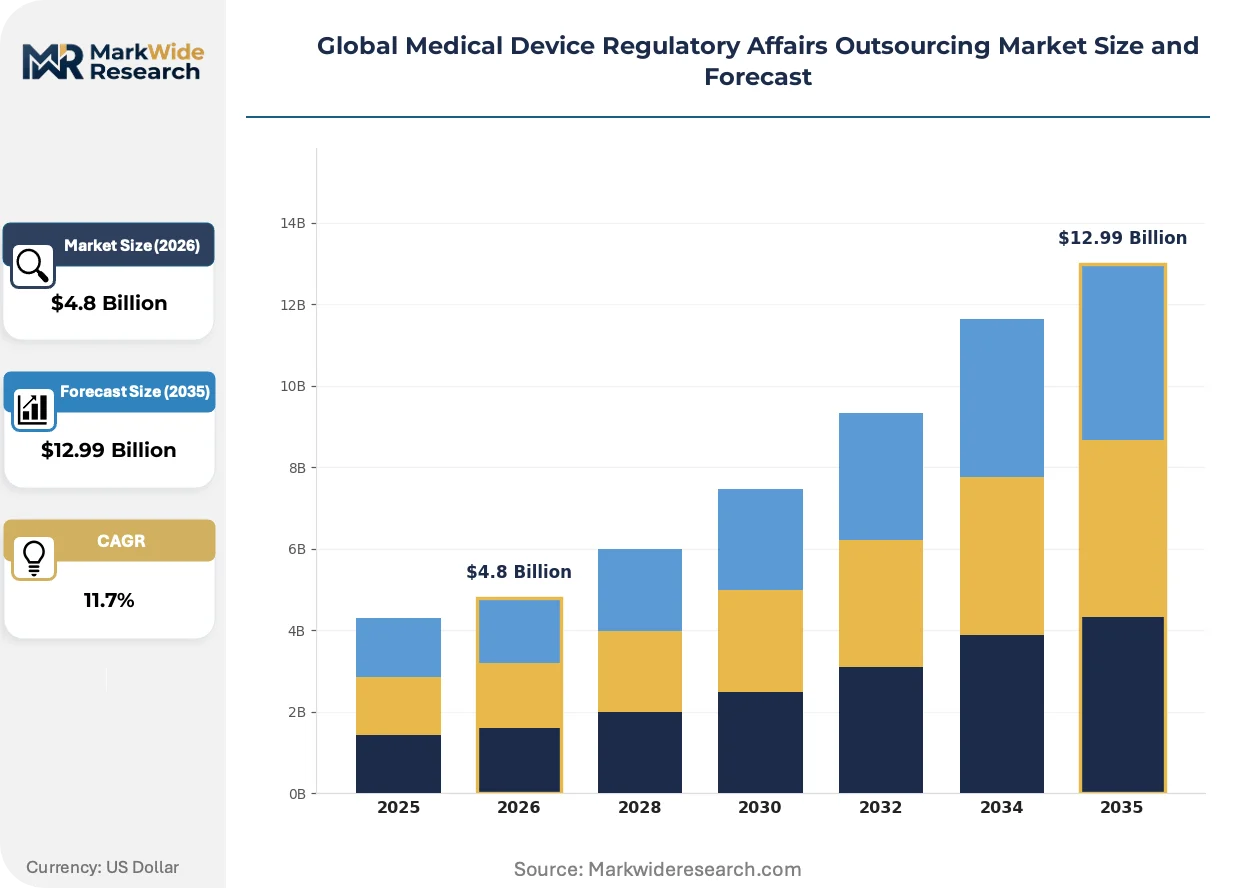
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Submission Management, Compliance Support, Regulatory Strategy End User: Medical Device Manufacturers, Healthcare Organizations, Biotech Companies, Academic Institutions Geographical Focus: North America, Europe, Asia Pacific, Latin America Engagement Model: Project-Based, Retainer, Contingency, Hybrid |
| Companies Covered | IQVIA, ICON plc, Emergo by UL, Freyr, MCRA, ProPharma Group, SGS, Intertek Group plc, Elexes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Regulatory Affairs Outsourcing Market Shifts & Advancements
Regulatory technology platforms are compressing submission preparation timelines while authority-specific expertise becomes the primary differentiator among outsourcing providers.
Artificial intelligence document generation is consolidating technical file compilation workflows by automating cross-referencing between risk management files and clinical evaluation reports. Mid-tier device manufacturers lacking internal regulatory information management systems are adopting these platforms fastest. The technology is consolidating market share among providers who integrate AI tooling with retained human authority negotiation capability.
The EU AI Act's risk classification framework for medical device software is reshaping conformity assessment pathways for diagnostic algorithms. Manufacturers must now demonstrate algorithmic transparency and bias mitigation alongside traditional safety and efficacy evidence. European notified bodies are developing AI-specific audit competencies that only specialized outsourcing partners currently possess.
Subscription-based regulatory intelligence services are displacing project-based consulting engagements among established manufacturers with recurring global portfolio maintenance needs. Device companies with 15-plus active registrations now favor fixed-fee retainers providing real-time regulatory change monitoring across FDA, EMA, and NMPA jurisdictions. This model is most advanced in Germany and Switzerland where manufacturer consolidation has concentrated outsourcing procurement decisions.
Global Medical Device Regulatory Affairs Outsourcing Market Segmentation
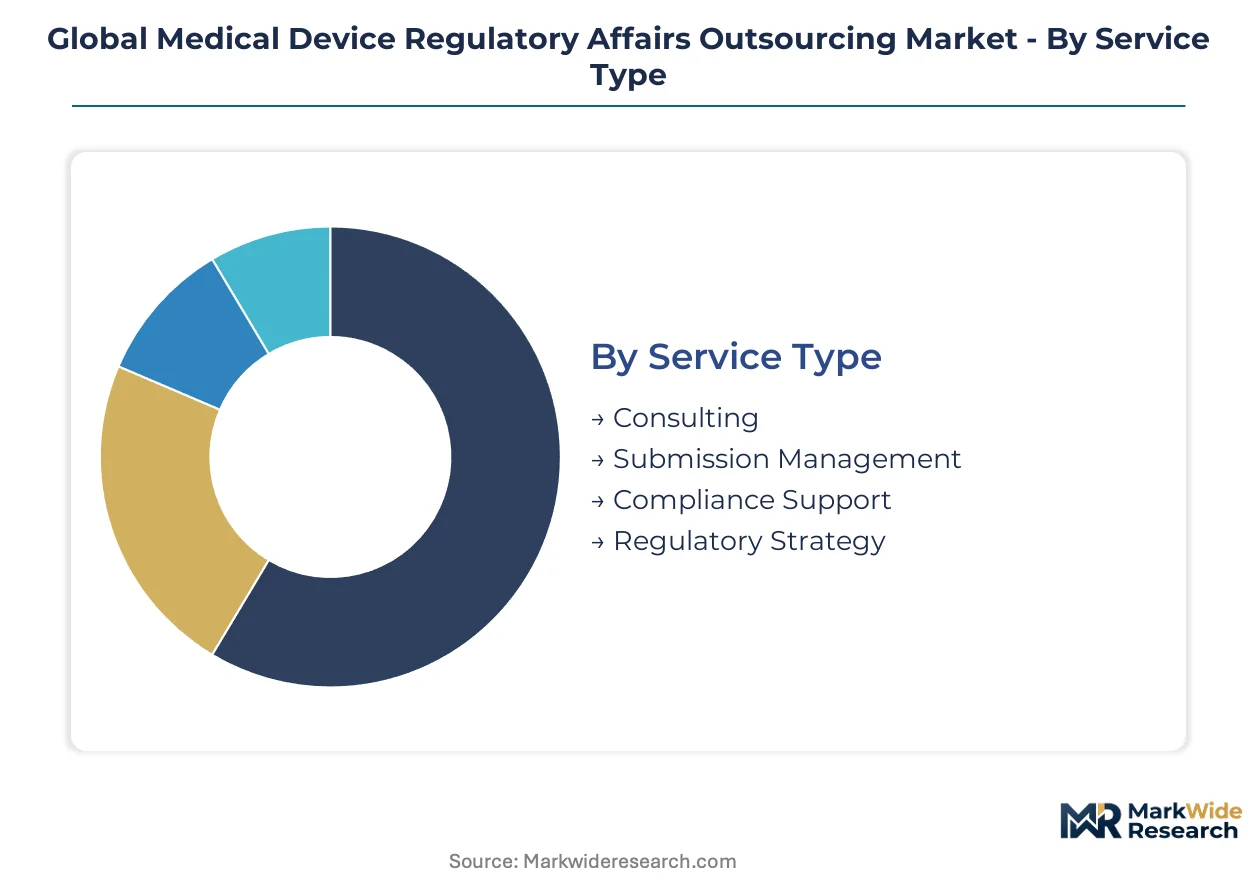
Regulatory outsourcing contracts fragment across service intensity levels and engagement structures. Manufacturers calibrate external partnerships against internal capability gaps, portfolio complexity, and jurisdiction-specific compliance burdens.
Service Type:
Standalone advisory engagements differ materially from embedded submission execution partnerships across the four service tiers.
- Consulting:Strategic advisory covering regulatory pathway selection, predicate device analysis, and authority pre-submission planning. Demand clusters among early-stage manufacturers in the United States navigating FDA's evolving digital health guidance for novel device categories.
- Submission Management:End-to-end dossier preparation, technical file compilation, and authority negotiation through clearance or approval. German and Swiss manufacturers expanding EU MDR certification portfolios drive contract volume for this highest-engagement tier.
- Compliance Support:Quality system maintenance, post-market surveillance execution, and ISO 13485 audit preparation. Mid-tier device makers in China leverage these services to satisfy NMPA localization mandates without building full internal regulatory departments.
- Regulatory Strategy:Portfolio-level planning spanning multi-jurisdiction registration sequencing and renewal optimization. Academic spinouts and biotech entrants in Japan utilize these engagements to structure PMDA pre-submission pathways for combination products.
Volume placements concentrate in Submission Management; the faster expansion belongs to Regulatory Strategy.
End User:
Customer sophistication and regulatory asset scale determine outsourcing contract structure and duration across four distinct organizational profiles.
- Medical Device Manufacturers:Established producers of Class II and III devices with recurring global portfolio maintenance requirements. These entities in Germany and the United States favor retainer-based engagements covering FDA, EMA, and notified body interactions.
- Healthcare Organizations:Hospital systems and integrated delivery networks developing in-house medical devices for institutional use. These customers in China engage project-based support for NMPA registration of proprietary diagnostic equipment.
- Biotech Companies:Drug developers expanding into combination products requiring hybrid pharmaceutical-device regulatory expertise. Japanese biotech firms leverage these services for PMDA Science Table consultations on novel therapeutic platforms.
- Academic Institutions:University technology transfer offices commercializing research-derived medical devices. These entities across Latin America rely on external partners to bridge gaps between laboratory validation and regulatory submission standards.
Contract value concentrates among Medical Device Manufacturers; Academic Institutions are expanding their outsourcing footprint most rapidly.
Geographical Focus:
Jurisdiction-specific regulatory complexity and authority capacity constraints shape regional outsourcing intensity.
- North America:FDA's Quality System Regulation and evolving software as medical device guidance drive demand. United States-based manufacturers face particular pressure from digital health validation requirements and 510(k) pathway modifications.
- Europe:EU MDR technical documentation standards and notified body capacity bottlenecks compel externalization. German manufacturers encounter extended certification queues that disrupt internal regulatory timeline planning.
- Asia Pacific:NMPA localization mandates and PMDA structured consultation systems create specialized service needs. China and Japan represent distinct regulatory ecosystems requiring country-specific expertise rather than regional generalists.
- Latin America:Emerging regulatory harmonization across Mercosur and national health authority capacity limitations. Brazilian and Mexican manufacturers navigate ANVISA and COFEPRIS requirements with limited internal regulatory infrastructure.
Revenue concentration sits in North America; Asia Pacific demonstrates the steepest expansion trajectory.
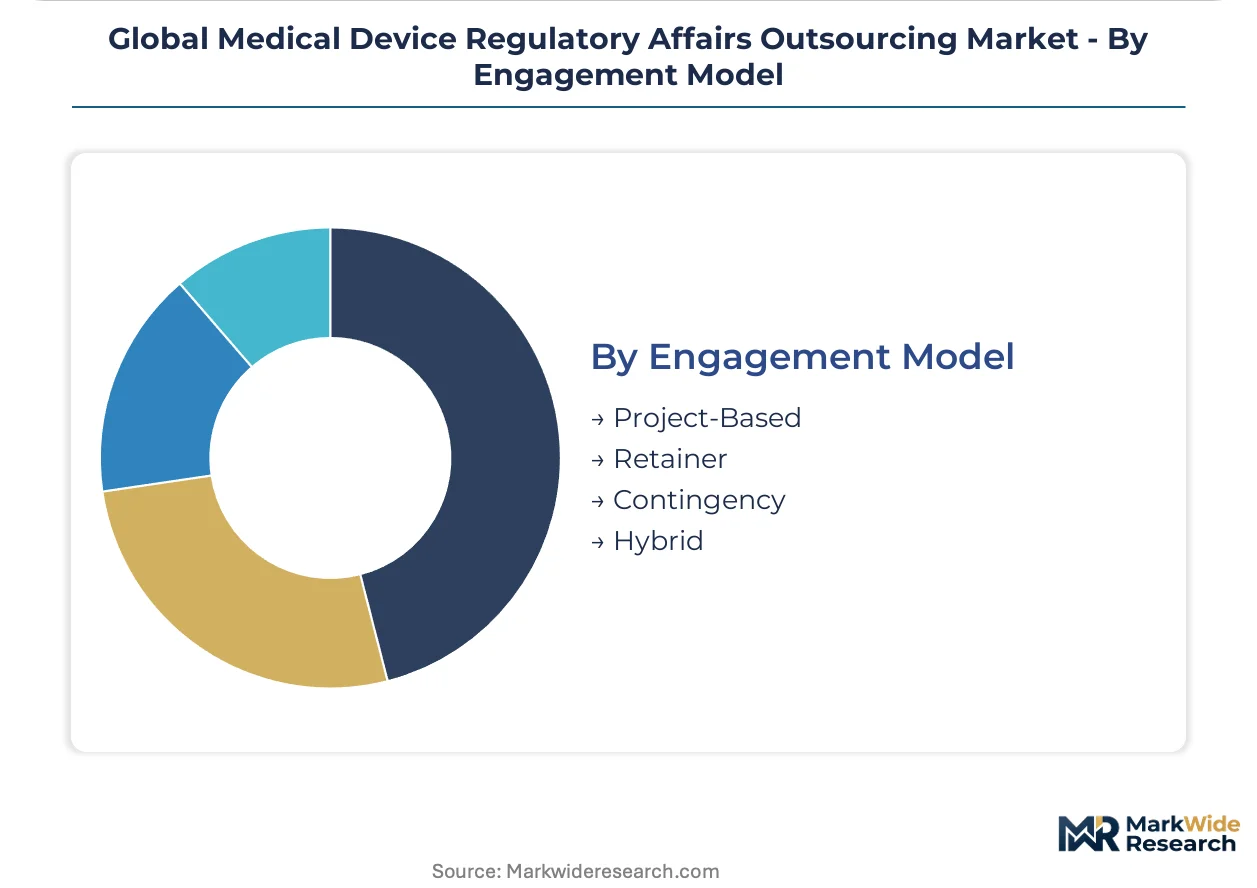
Engagement Model:
Payment structure aligns risk allocation between outsourcing provider and manufacturer based on outcome predictability.
- Project-Based:Milestone-gated contracts for discrete submissions or regulatory events. Early-stage device companies in the United States prefer this model for initial FDA 510(k) clearances where internal regulatory experience is absent.
- Retainer:Fixed-fee arrangements covering ongoing regulatory intelligence, change monitoring, and routine authority correspondence. Established manufacturers in Switzerland and Germany with 15-plus active registrations favor this predictable cost structure.
- Contingency:Success-fee components tied to approval outcomes or accelerated timeline achievement. These structures appear selectively for high-risk novel device categories in Japan where PMDA consultation outcomes remain uncertain.
- Hybrid:Blended base-plus-incentive structures combining guaranteed service access with performance-linked components. Large multinational manufacturers across multiple jurisdictions deploy this model to balance cost control with outcome motivation.
Retainer structures dominate current contract volume; Hybrid models are gaining adoption fastest among portfolio-scale manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized regulatory talent pools in Massachusetts, Bavaria, and Basel anchor the geographic distribution of medical device regulatory affairs outsourcing demand. These clusters concentrate notified body relationships, FDA interaction experience, and pharmaceutical-device hybrid expertise.
United States
FDA's evolving digital health guidance and 510(k) pathway modifications drive outsourcing intensity among software-enabled device developers. The Quality System Regulation and recent cybersecurity guidance documents raise compliance barriers that internal teams cannot scale. Greater Boston hosts the densest concentration of regulatory consultancies serving early-stage manufacturers navigating pre-submission pathways.
Germany
EU MDR technical documentation requirements and notified body capacity constraints compel externalization among Mittelstand device manufacturers. Extended certification queues disrupt internal timeline planning for Class II implantable devices. The Munich-Stuttgart corridor concentrates regulatory service providers with deep TÜV and DEKRA relationship networks.
China
NMPA localization mandates for in-country testing and Mandarin documentation requirements push foreign manufacturers toward domestic regulatory representation. The 2021 Medical Device Registration and Administration Regulations intensify compliance complexity for imported products. Shanghai and Suzhou host the primary clusters of bilingual regulatory specialists serving multinational device entrants.
Japan
PMDA's structured consultation system and Science Table meetings create specialized demand for regulatory partners who can accelerate novel device approvals. The Pharmaceuticals and Medical Devices Act amendments expand QMS requirements for foreign manufacturers. Tokyo and Osaka concentrate the hybrid pharmaceutical-device regulatory expertise needed for combination product submissions.
Switzerland
Swissmedic's alignment with EU MDR standards while maintaining independent market authorization requirements drives dual-track regulatory planning. The country's medical technology cluster generates retainer-based outsourcing contracts for global portfolio maintenance. Basel and Zürich anchor regulatory intelligence services serving manufacturers with 15-plus active registrations.
Global Medical Device Regulatory Affairs Outsourcing Market Competitive Landscape
Global majors compete with regional champions across authority-specific expertise and jurisdiction coverage. The market structure tiers between integrated clinical-regulatory platforms, specialized European notified body navigators, and fixed-fee technology-enabled providers. Three archetypes dominate: data-anchored conglomerates, relationship-driven European specialists, and automation-focused mid-tier enablers. M&A activity concentrates on acquiring notified body relationships and regulatory technology platforms.
Within the integrated platform tier, IQVIA and ICON plc exemplify data-anchored global reach across multiple jurisdictions. Emergo by UL occupies a position among European relationship specialists with deep notified body networks. Freyr represents the technology-enabled archetype with fixed-fee regulatory intelligence platforms. These three anchors illustrate the strategic segmentation between scale, regional depth, and automation in competitive positioning.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Emergo by UL |
| Freyr |
| MCRA |
| ProPharma Group |
| SGS |
| Intertek Group plc |
| Elexes |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists have consolidated fragmented regulatory consultancies across Massachusetts, Bavaria, and Basel, concentrating supply-side pricing power while compressing margins for independent mid-tier providers competing on project-based submissions. This ownership pattern enforces disciplined retainer pricing among portfolio companies while squeezing cost-plus structures for standalone firms serving early-stage device manufacturers.
Pricing Analysis
Service bundling separates retainer-based regulatory intelligence from unbundled project submissions, with premium tiers incorporating real-time FDA pre-submission support and notified body relationship access. Three-tier pricing structure across premium, standard, and economy levels aligns with engagement depth: premium captures 15-plus active registration portfolios with dedicated account teams, standard covers milestone-gated submission management, and economy serves single-market 510(k) filings. Cost compression in the economy tier is intensifying because AI-enabled document generation platforms reduce technical file compilation hours. Academic institutions and early-stage spinouts exhibit highest price sensitivity; established multinational manufacturers with recurring EU MDR renewal obligations demonstrate lowest sensitivity due to switching costs.
Supply Chain Analysis
ISO 13485 certification and FDA establishment registration requirements gate entry for regulatory talent providers, limiting qualified supply to the United States, Germany, and Switzerland where training infrastructure and notified body proximity concentrate expertise. The supply chain draws from bilingual regulatory specialists, clinical evaluation report writers, and quality system auditors as core inputs. Single-source vulnerability persists in EU MDR technical documentation expertise where notified body-trained professionals remain scarce. Distribution runs through direct enterprise sales teams for retainer contracts and platform-mediated marketplaces for project-based engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory affairs outsourcing functions as a consolidation play where notified body capacity constraints and AI-enabled platform economics force sub-scale providers toward acquisition or exit. EU MDR technical documentation complexity and talent scarcity accelerate this pressure.
For Market Incumbents: Deepen vertical integration into clinical evaluation report writing and post-market surveillance automation to defend against pure-play AI document platforms eroding submission management margins. Acquire boutique notified body relationship specialists in Germany and Switzerland to lock in scarce TÜV and DEKRA access. Expand retainer-based regulatory intelligence services to capture recurring revenue from manufacturers with 15-plus active registrations.
For New Entrants and Emerging Players: Capture the Japan PMDA pre-submission pathway segment where hybrid pharmaceutical-device regulatory expertise remains underdeveloped and Science Table navigation commands premium pricing. Target academic technology transfer offices in Latin America with project-based support bridging laboratory validation to ANVISA and COFEPRIS submission standards. Deploy platform-based fixed-fee models to undercut incumbent hourly billing for mid-tier manufacturers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-enabled regulatory intelligence platforms with recurring revenue bases in Germany and Switzerland where manufacturer consolidation concentrates procurement decisions. Five-to-ten year viability hinges on AI document generation capabilities that compress technical file preparation timelines. Watch FDA harmonization initiatives with international regulators as the inflection signal for platform scalability across jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Acquisition | Secures scarce TÜV and DEKRA access for EU MDR certification queues. |
| AI Document Generation Platform Deployment | Compresses technical file compilation timelines for mid-tier manufacturers. |
| PMDA Pre-Submission Pathway Specialization | Captures hybrid expertise demand for Japan combination product approvals. |
| Retainer-Based Intelligence Service Expansion | Locks in recurring revenue from 15-plus registration portfolio clients. |
| Post-Market Surveillance Automation Buildout | Extends revenue model beyond one-time submission support. |
Research Methodology
Independent corroboration across regulatory affairs directors at Class II and III device manufacturers, notified body audit managers, and GPO contracts managers underwrites the qualitative findings in this study. Primary fieldwork with FDA submission specialists, EU MDR technical file consultants, and NMPA localization advisors combined with secondary validation from FDA 510(k) databases, EUDAMED registration records, and NMPA Medical Device Registration and Administration Regulations. Bottom-up triangulation across service type engagement volumes and top-down validation against manufacturer regulatory spending disclosures anchored the market sizing.
Rate-of-change decomposition across the analysis window separated volume effects from price-mix shifts in retainer versus project-based contract evolution. Segmentation modeling incorporated service type intensity, end user organizational profile, engagement model structure, and jurisdiction-specific regulatory complexity. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against notified body capacity expansion rates and FDA digital health guidance issuance frequency.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, FDA software as medical device guidance revisions, and NMPA localization mandate enforcement. Forecasts reflect assumptions regarding stable regulatory fragmentation across FDA, EMA, and NMPA jurisdictions. A model refresh is warranted upon material change in notified body designation rates or FDA harmonization treaty progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Global Healthcare IT Consulting Market