
 Consulting Service Market | 2026-2036
Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Consulting Service Market Outlook
Capability gaps between asset-heavy technology integrators and strategy-first boutiques is collapsing as cloud delivery and AI tooling democratize execution scale. Accenture leverages its global delivery network to embed consulting inside managed services contracts. McKinsey & Company sustains pricing power through proprietary research assets and partner-led client relationships. Deloitte Consulting anchors its position by combining audit-adjacent trust with multidisciplinary implementation teams.
Consulting services encompass advisory, implementation, and change-management engagements delivered by professional services firms to improve organizational performance, technology deployment, or financial outcomes; engagements typically involve diagnostic assessment, solution design, and knowledge transfer phases executed through partner-staffed project teams. Management consulting leads revenue contribution as boards seek cost restructuring and M&A advisory, while IT consulting captures the fastest expansion as enterprises migrate legacy systems to cloud-native architectures. Project-based engagements dominate large transformation deals, though retainer relationships with technology sector clients concentrate recurring margin pools.
SEC disclosure rules and the EU AI Act reshape demand for risk and compliance advisory, forcing firms to build specialized regulatory practices. HIPAA, GDPR, and ISO 27001 certifications function as market-access credentials that filter procurement shortlists for healthcare and cross-border engagements. Stakeholders must monitor how generative AI tools alter the labor-value equation between junior staff leverage and partner expertise monetization.
Market Dynamics
Generative AI tooling is collapsing the traditional leverage model of consulting, compressing project timelines and forcing firms to reprice junior analyst hours against automated output quality.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across the 27 member states must document algorithmic risk assessments, creating sustained demand for regulatory advisory practices that bridge legal interpretation and technical implementation.
- Healthcare digital transformation:Hospital systems in the United States are outsourcing electronic health record modernization and HIPAA-compliant cloud migration to specialized implementation partners.
- Cloud-native architecture migration:Legacy mainframe estates in financial services require phased replatforming, sustaining multi-year advisory engagements for mainframe-to-microservices transformation.
Market Restraints
- Talent wage inflation:Compensation for AI/ML specialists and cybersecurity architects has escalated 40-60% above pre-2022 baselines, compressing project margins.
- Client insourcing:Technology sector buyers are building internal strategy functions, reducing reliance on external advisors for recurring operational decisions.
- Scope creep liability:Fixed-fee transformation contracts expose firms to uncapped labor investment when client data readiness or change-management timelines slip.
Strategic Opportunities
- India mid-market penetration:Domestic conglomerates and PLI-scheme beneficiaries in manufacturing require operational excellence advisory previously concentrated among multinationals.
- SEC climate disclosure rules:Scope 3 emissions accounting and CSRD-aligned reporting create recurring advisory retainer relationships with cross-border compliance complexity.
- Generative AI + process mining convergence:Firms that combine automated workflow discovery with synthetic scenario modeling can compress diagnostic phases from months to weeks.
Industry Challenges
- Partner-level succession gaps:Rainmaking senior partners in their late 50s-60s hold irreplaceable client relationships, yet knowledge transfer systems fail to replicate trust-based access.
- ISO 27001 certification bottlenecks:Healthcare and financial services procurement gates require current certification, yet audit backlogs delay market entry for boutique entrants.
- Multi-vendor integration friction:Clients engaging separate strategy, implementation, and change-management advisors face coordination failures that erode transformation outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consulting Service Market |
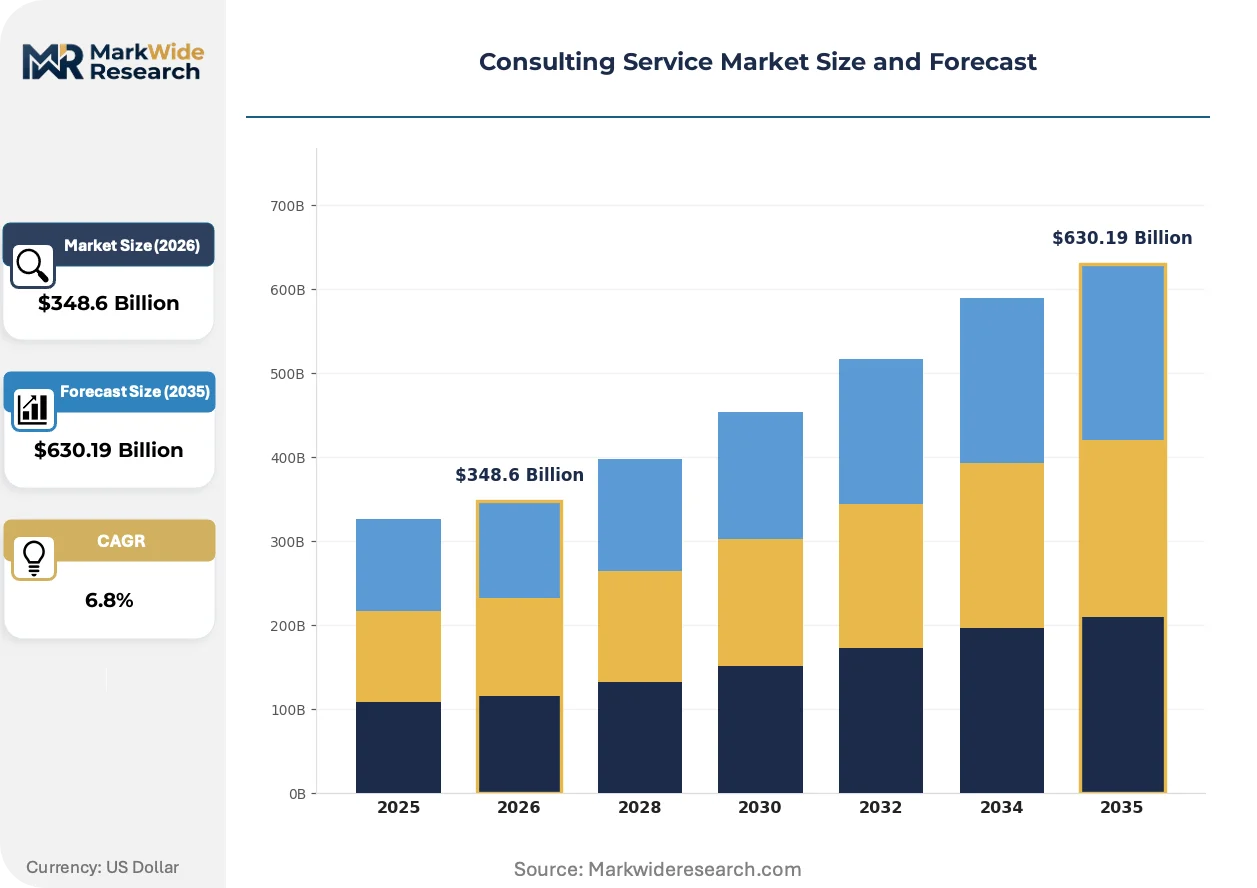
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $630.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
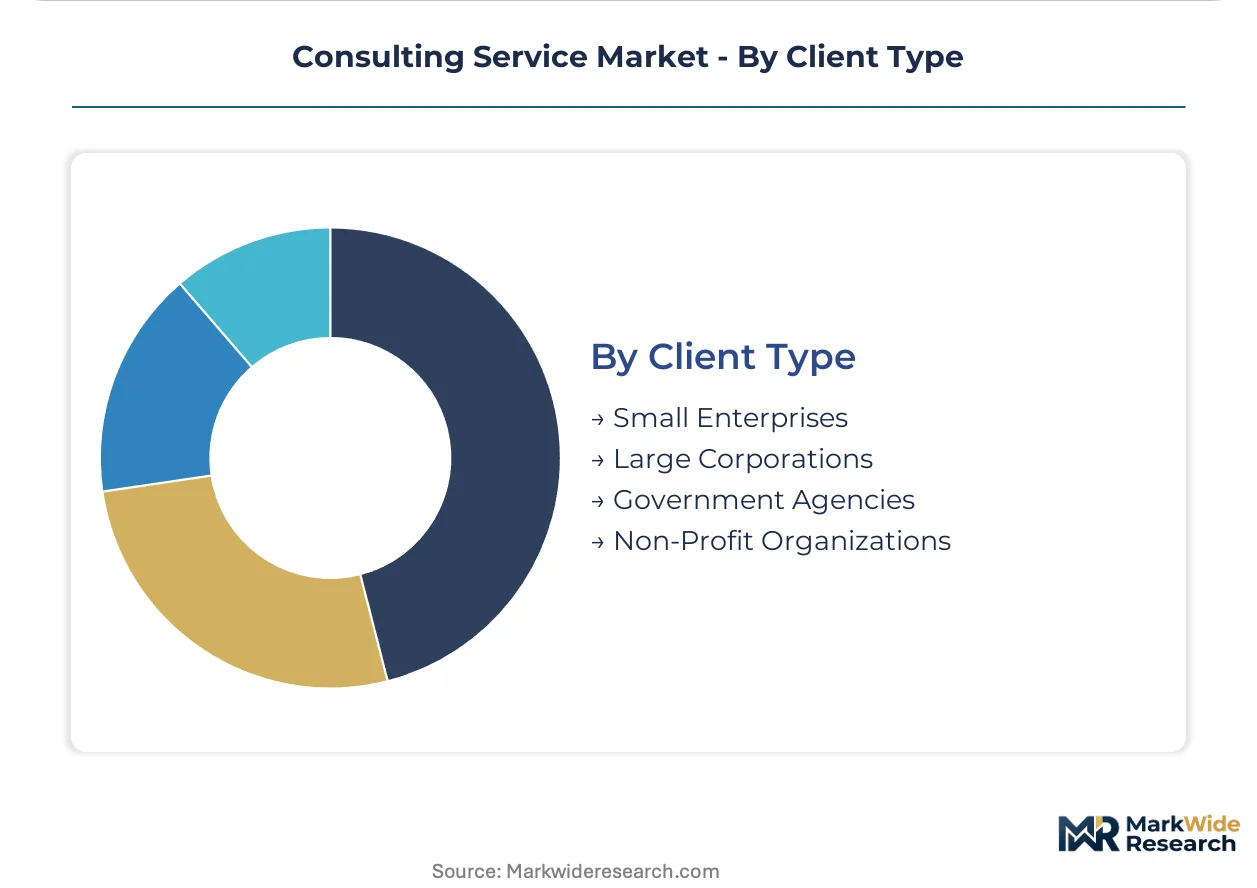
| Segmentation | Service Type: Management Consulting, IT Consulting, Financial Advisory, Human Resource Consulting Industry Vertical: Healthcare, Retail, Manufacturing, Technology Engagement Model: Project-Based, Hourly Rate, Retainer, On-Demand Client Type: Small Enterprises, Large Corporations, Government Agencies, Non-Profit Organizations |
| Companies Covered | Accenture, PricewaterhouseCoopers, McKinsey & Company, Oliver Wyman, Ernst & Young, Boston Consulting Group, Deloitte Consulting, KPMG, Bain & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consulting Service Market Strategic Shifts
Advisory delivery models are fragmenting as AI copilots compress diagnostic work and clients demand embedded, outcome-contingent engagement structures over traditional time-and-materials billing.
Large language model copilots are supplanting first-draft research synthesis, financial modeling, and presentation production previously executed by analyst classes. Private equity and corporate strategy teams now expect 48-hour turnaround on market scans that required two-week staffing rotations. This compression is forcing firms to retrain junior staff toward client facilitation and quality assurance rather than content generation.
The EU AI Act's risk-tiering framework is mandating conformity assessments for high-risk algorithmic systems used in credit scoring, recruitment, and medical diagnostics. Consulting practices are building specialized legal-engineering hybrid teams to document technical robustness and human oversight protocols. Financial services institutions in Frankfurt and Paris are the earliest adopters, engaging advisors to map AI inventories against prohibited and high-risk categories before enforcement deadlines.
Enterprise buyers are unbundling strategy advisory from implementation, selecting boutique firms for diagnostic phases and systems integrators for execution. This disintermediation fragments revenue pools and requires strategy firms to defend margin through proprietary data assets or partner-staffed delivery. Technology sector clients in Silicon Valley and Seattle pioneered this split-procurement model, which is now migrating to healthcare and industrial conglomerates.
Consulting Service Market Segmentation
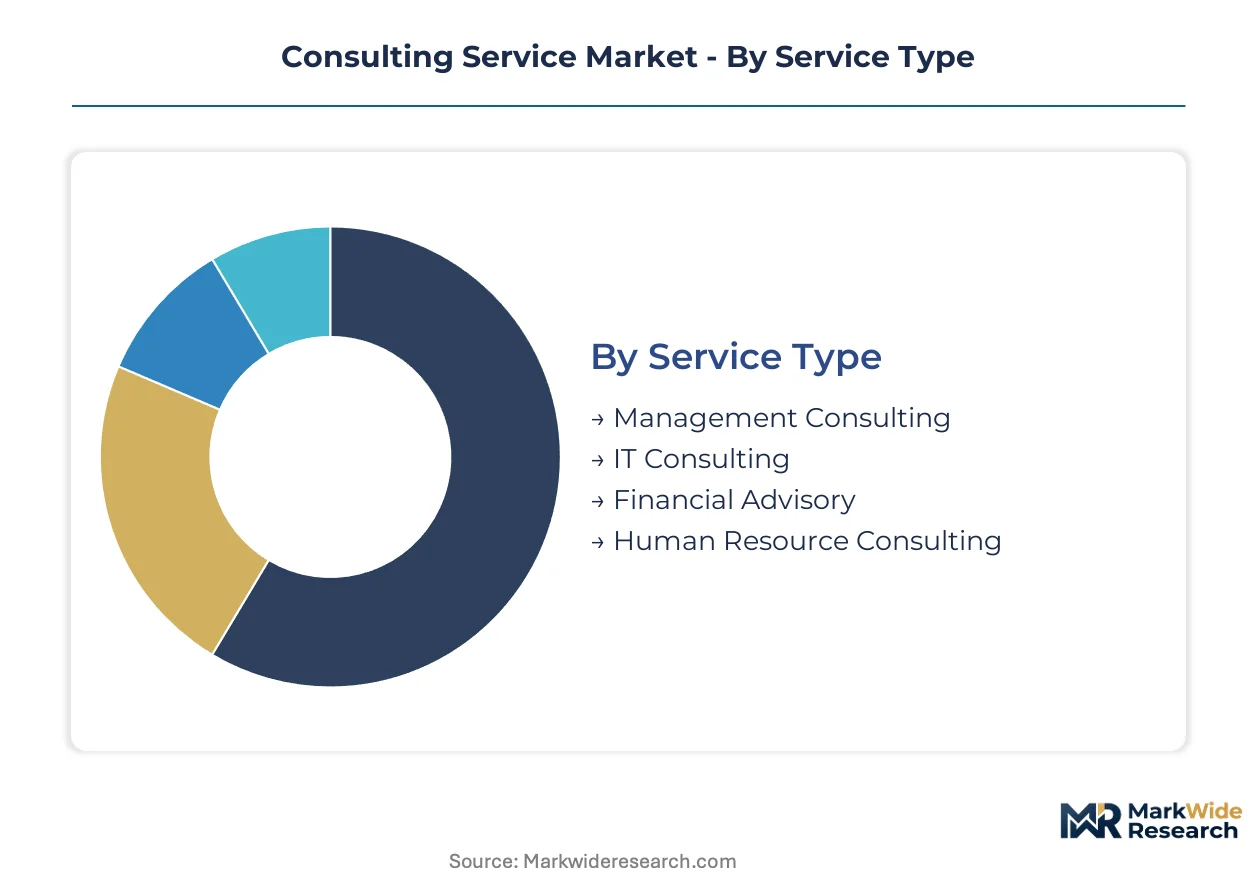
Segmentation in consulting services reveals how procurement criteria diverge across regulatory exposure, technology intensity, and relationship duration. Buyers select engagement structures based on compliance complexity and the need for sustained advisory versus discrete intervention.
Service Type:
Regulatory differentiation separates advisory practices by the certification burden each carries — HIPAA for healthcare implementations, SOX for financial advisory, ISO 27001 for technology delivery.
- Management Consulting:Board-level advisory spanning cost restructuring, M&A due diligence, and operating model redesign. Demand concentrates among Fortune 500 industrials in the United States where SEC disclosure rules mandate external validation of material transactions. Partner-led delivery sustains premium pricing against AI-automated alternatives.
- IT Consulting:Cloud migration, cybersecurity architecture, and legacy system modernization delivered through blended onshore-offshore teams. Healthcare providers in the United States outsource electronic health record replatforming to specialists holding current HIPAA attestations. The EU AI Act's technical documentation requirements are creating specialized legal-engineering hybrid practices.
- Financial Advisory:Transaction structuring, valuation, and restructuring advisory governed by SEC and FINRA oversight.
- Human Resource Consulting:Compensation benchmarking, talent analytics, and organizational design delivered through proprietary survey databases.
Established volume favors Management Consulting; emerging adoption favors IT Consulting.
Industry Vertical:
Cost tier differentiation separates buyers by procurement sophistication — technology sector clients demand outcome-contingent structures while healthcare accepts time-and-materials for compliance-bound work.
- Healthcare:Hospital systems and payers require HIPAA-compliant cloud migration and clinical workflow optimization. United States health networks concentrate spending on electronic health record modernization and revenue cycle management. CMS reimbursement rule changes drive recurring advisory demand.
- Technology:Software vendors and cloud providers engage strategy firms for market entry and pricing architecture. Silicon Valley buyers pioneered the unbundling of diagnostic and implementation phases, compressing margins for full-service delivery.
- Retail:Omnichannel transformation and supply chain resilience advisory for consumer-facing brands.
- Manufacturing:Operational excellence and Industry 4.0 implementation for industrial conglomerates.
Technology verticals drive margin expansion; healthcare anchors recurring revenue pools.
Engagement Model:
Customer type and deal size dictate structure — enterprise transformation demands project-based scoping while ongoing regulatory exposure favors retainers.
- Project-Based:Fixed-scope transformation engagements with defined deliverables and milestone payments. Financial services institutions in Frankfurt and Paris commission mainframe-to-microservices replatforming through multi-year statements of work. Scope creep liability concentrates in data readiness phases.
- Retainer:Recurring advisory relationships with predefined partner access and quarterly strategic reviews. Technology sector clients in Seattle and Silicon Valley concentrate premium recurring margin pools through continuous innovation advisory.
- Hourly Rate:Time-and-materials billing for discrete diagnostic or litigation support engagements.
- On-Demand:Subscription platforms for rapid access to specialist expertise without long-term commitment.
Project-based structures dominate large transformation value; retainer relationships concentrate recurring margin.
Client Type:
Maturity and procurement sophistication separate segments — government agencies mandate certification gates while enterprises prioritize speed-to-insight.
- Large Corporations:Multinational enterprises with centralized procurement functions and multi-year master service agreements. United States-based technology and healthcare conglomerates drive premium engagement volumes through partner-level relationship requirements.
- Government Agencies:Federal and state entities with mandated competitive bidding and socio-economic contracting preferences. CMS and VA health IT modernization programs require CMMI Level 3+ and FedRAMP certifications as procurement gates.
- Small Enterprises:Mid-market companies with limited procurement staff and preference for fixed-fee certainty.
- Non-Profit Organizations:Mission-driven entities with board-governed consulting budgets and donor transparency requirements.
Large Corporations anchor revenue concentration; Government Agencies sustain certification-barrier protected demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in consulting services favor net-importing jurisdictions with complex regulatory environments. The United States runs a structural surplus in advisory exports while importing specialized implementation capacity from India and Eastern Europe. Germany and the United Kingdom compete for cross-border regulatory advisory mandates serving EU-wide compliance programs.
United States
Technology sector clients in Silicon Valley and Seattle drive premium engagement volumes for digital transformation advisory. SEC disclosure rules and HIPAA mandates create sustained demand for compliance-integrated consulting. Hospital systems in Texas and Florida outsource electronic health record modernization to specialized implementation partners holding current attestations.
Germany
Frankfurt-based financial institutions commission mainframe-to-microservices replatforming through multi-year statements of work. The EU AI Act's risk-tiering framework compels enterprises to document algorithmic assessments, creating specialized legal-engineering hybrid practices. Industrial conglomerates in Bavaria and Baden-Württemberg anchor operational excellence advisory demand.
United Kingdom
London concentrates M&A advisory and restructuring mandates serving cross-border transaction flows. GDPR compliance and CSRD-aligned reporting sustain recurring retainer relationships with multinational headquarters. Fintech clusters in Manchester and Edinburgh generate specialized regulatory advisory demand for open banking and payments architecture.
India
Domestic conglomerates and PLI-scheme beneficiaries in manufacturing require operational excellence advisory previously concentrated among multinationals. Mumbai and Bangalore serve as delivery hubs for global advisory firms embedding offshore capacity into managed services contracts. RBI and SEBI regulatory changes drive financial services consulting demand among private banks and asset managers.
France
Paris-based institutions lead early adoption of EU AI Act conformity assessments for high-risk algorithmic systems. The CNIL enforces GDPR interpretation that shapes cross-border data governance advisory. Pharmaceutical and luxury goods clusters in Île-de-France sustain pricing architecture and market entry strategy demand.
Consulting Service Market Competitive Environment
Concentration sits with full-service networks combining audit-adjacent trust with multidisciplinary implementation teams. The market structure spans three tiers: global networks with integrated delivery, strategy-first boutiques with proprietary research assets, and specialized implementation firms with certification-gated access. Strategic moves center on embedding consulting inside managed services contracts and building legal-engineering hybrid practices for regulatory advisory.
Within the global network tier, Accenture leverages its delivery footprint to integrate advisory with execution, while McKinsey & Company and Boston Consulting Group occupy positions sustained by partner-level client relationships and proprietary knowledge assets. Deloitte Consulting anchors trust-based positioning through audit-adjacent credentials combined with implementation scale.
| Leading Market Players |
|---|
| Accenture |
| PricewaterhouseCoopers |
| McKinsey & Company |
| Oliver Wyman |
| Ernst & Young |
| Boston Consulting Group |
| Deloitte Consulting |
| KPMG |
| Bain & Company |
| Others |
Value Chain & Pricing Dynamics
Ninety-day partner onboarding cycles for regulatory certification programs anchor pricing power with established networks while compressing margins for boutiques lacking audit-adjacent credentials. This lead-time differential concentrates premium engagements with firms holding current HIPAA and ISO 27001 attestations, forcing price stratification between compliance-gated and generalist advisory tiers.
Pricing Analysis
Configured-to-order project pricing commands 40-60% premiums over standardized advisory packages due to partner-level staffing requirements and proprietary research asset deployment. The dominant structure runs through project-based statements of work with milestone payments, though technology sector buyers in Seattle and Silicon Valley increasingly demand outcome-contingent arrangements. Price differentiation rests on certification grade—EU AI Act readiness assessments and HIPAA-compliant implementations filter procurement shortlists—and vertical integration depth, with audit-adjacent networks capturing trust premiums. Pricing pressure stems from generative AI tooling compressing diagnostic timelines and client expectations of 48-hour deliverables previously requiring two-week rotations. Small enterprises exhibit highest price sensitivity, seeking fixed-fee certainty, while Fortune 500 technology conglomerates prioritize speed-to-insight over rate negotiation.
Supply Chain Analysis
Partner-level talent pipelines in the United States, United Kingdom, and India constitute the primary chokepoint constraining advisory capacity expansion. The supply chain draws from specialized labor pools—legal-engineering hybrids for EU AI Act compliance, cloud architects for healthcare migration, and regulatory specialists for SEC disclosure mandates—anchored in credential-constrained markets. Single-source vulnerability concentrates in rainmaking senior partners holding irreplaceable client relationships, with knowledge transfer systems failing to replicate trust-based access. Distribution runs through centralized procurement functions at multinational enterprises, supplemented by managed services contracts embedding advisory inside technology delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The consulting services market is recovering from cyclical compression as enterprise technology refresh budgets rebound and regulatory compliance mandates create non-discretionary advisory demand. This recovery is anchored in the EU AI Act enforcement timeline and SEC climate disclosure implementation, which sustain multi-year advisory engagements regardless of macroeconomic headwinds.
For Market Incumbents: Fortify certification moats by accelerating ISO 27001 and HIPAA attestation coverage for offshore delivery centers, while embedding advisory capabilities inside managed services contracts to capture recurring revenue pools. The threat of boutique strategy firms unbundling diagnostic phases from implementation requires defensive proprietary data asset investments. Vertical integration into legal-engineering hybrid practices for EU AI Act compliance represents the priority capability addition. For New Entrants and Emerging Players: Differentiate on regulatory specialization depth rather than geographic coverage breadth, targeting India mid-market manufacturing conglomerates previously underserved by multinational advisory networks. The most penetrable segment sits with PLI-scheme beneficiaries requiring operational excellence advisory without enterprise-grade procurement sophistication. A go-to-market angle anchored in rapid diagnostic sprints—compressing assessment phases from months to weeks through generative AI tooling—bypasses incumbent scale advantages. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and partner relationship economics favor scaled networks over fragmented boutiques. Acquisition targets should display audit-adjacent credentials combined with specialized implementation depth in healthcare or financial services verticals. The signal to watch is enforcement acceleration for EU AI Act high-risk system categories, which will trigger compliance advisory demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Legal-Engineering Hybrid Practice Buildout | EU AI Act conformity assessments require teams bridging technical documentation and regulatory interpretation for Frankfurt and Paris financial institutions. |
| Managed Services Contract Embedding | Accenture-style integration of advisory inside technology delivery captures recurring margin pools from healthcare cloud migration mandates. |
| Proprietary Research Asset Investment | McKinsey-style knowledge monetization defends pricing power against AI-automated diagnostic alternatives. |
| India Mid-Market Geographic Expansion | Domestic conglomerates and PLI beneficiaries in manufacturing require operational excellence advisory previously concentrated among multinationals. |
| Partner Succession System Overhaul | Rainmaking senior partner knowledge transfer failures threaten client relationship continuity at strategy-first boutiques. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory submissions, healthcare procurement databases, and technology sector capex disclosures. Interviews with consulting firm partners, healthcare CIOs, financial services regulatory leads, and enterprise procurement officers provided demand-side validation. Secondary sources included CMS reimbursement rule documentation, GPO contract databases, and hyperscaler partnership announcements. Bottom-up engagement volume estimates triangulated against top-down market sizing from audit-adjacent network revenue disclosures.
Segmentation dimensions modeled span service type, industry vertical, engagement model, and client type across the analysis window. The quantitative framework projects revenue trajectories using partner-staffing ratios, certification-gated market access filters, and regulatory mandate enforcement calendars. CAGRs derive from historical engagement growth patterns adjusted for AI tooling adoption curves and compliance deadline clustering. Industry-specific inputs include EU AI Act implementation timelines, SEC climate disclosure phase-in schedules, and healthcare EHR modernization funding cycles.
Material uncertainties—regulatory enforcement delays, generative AI capability leaps, and talent wage inflation acceleration—sit outside the modeled envelope. Forecasts reflect assumptions about partner productivity retention and certification audit backlog resolution. Practitioners should keep alternative scenarios live as EU AI Act guidance interpretation and SEC staff accounting bulletins evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Italy Operations Service Consulting Market