
 Global Healthcare IT Consulting Market | 2026-2036
Global Healthcare IT Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare IT Consulting Market Foresight
Cloud-native architecture is fragmenting traditional enterprise software delivery into modular microservices that demand specialized integration expertise. Deloitte Touche Tohmatsu Limited anchors its healthcare practice around regulatory-compliant cloud migrations for large hospital networks. IBM Corporation leverages its Watson Health analytics heritage to differentiate in clinical data interoperability engagements. Accenture competes through end-to-end digital transformation programs that span EHR modernization through cybersecurity hardening.
Healthcare IT consulting encompasses advisory and implementation services that configure, integrate, and optimize clinical information systems, patient data platforms, and care delivery infrastructure across provider organizations. These engagements typically involve HL7 FHIR interface mapping, zero-trust security architecture deployment, and workflow redesign to achieve measurable clinical efficiency gains. Implementation services dominate current revenue pools as hospitals replace legacy on-premise EHR installations with hybrid cloud architectures that require phased migration planning. Cybersecurity segments command premium pricing due to escalating ransomware threats against patient data repositories and the specialized compliance knowledge required under HIPAA and state breach-notification laws.
FDA guidance on software-as-a-medical-device and HIPAA Security Rule enforcement by the Office for Civil Rights shape product validation requirements and liability frameworks for IT consultants. The EU AI Act and GDPR impose algorithmic transparency mandates and cross-border data localization rules that constrain how European health data flows into cloud analytics pipelines. Stakeholders must monitor evolving FDA pre-certification pathways for AI-enabled diagnostic tools, as these frameworks will determine which consulting firms can credibly guide clients through regulatory submission and post-market surveillance obligations.
Market Dynamics
Cloud-native EHR migrations are fragmenting enterprise software delivery into modular microservices, forcing consulting firms to rebuild implementation methodologies around containerized architectures and API-first integration patterns rather than monolithic system replacements.
Growth Catalysts
- HIPAA interoperability mandates:The Office for Civil Rights enforcement of information blocking rules compels hospital systems to accelerate FHIR interface deployments, driving specialized consulting demand for legacy-to-cloud data mapping.
- EU AI Act algorithmic transparency requirements:German hospital networks now require dual-compliance architecture for AI-enabled diagnostic tools, creating premium advisory segments around explainability frameworks and post-market surveillance protocols.
- Ransomware escalation against patient data repositories:Zero-trust security architecture deployments concentrate procurement in cybersecurity-hardening engagements that command specialized HIPAA breach-notification expertise.
Market Restraints
- Specialized talent scarcity:The shallow pool of consultants holding simultaneous HL7 FHIR certification and cloud architecture credentials inflates project staffing costs and extends implementation timelines.
- Regulatory friction from overlapping jurisdictions:Cross-border health data flows into cloud analytics pipelines face GDPR localization rules that constrain multi-tenant platform architectures for European deployments.
- Legacy technical debt:Decades-old on-premise EHR installations impose brittle interface constraints that resist phased cloud migration without expensive middleware layers.
Strategic Opportunities
- Underpenetrated Saudi Arabian hospital digitization:SFDA regulatory frameworks for software-as-a-medical-device create first-mover advisory windows for firms establishing localized compliance practices.
- AI-enabled clinical decision support convergence:FDA pre-certification pathway evolution for diagnostic algorithms opens implementation services spanning algorithm validation through post-market surveillance obligation design.
- Value-based care workflow redesign:US Medicare reimbursement shifts toward bundled payments drive demand for consulting that reconfigures EHR analytics to track episode-cost accountability across integrated delivery networks.
Industry Challenges
- Multi-cloud integration complexity:Hospital procurement of best-of-breed SaaS modules from competing hyperscalers fragments data governance and demands expensive custom API orchestration.
- Certification timeline compression:FDA software-as-a-medical-device guidance updates accelerate validation cycles, forcing consultants to rebuild quality management system documentation under compressed deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare IT Consulting Market |
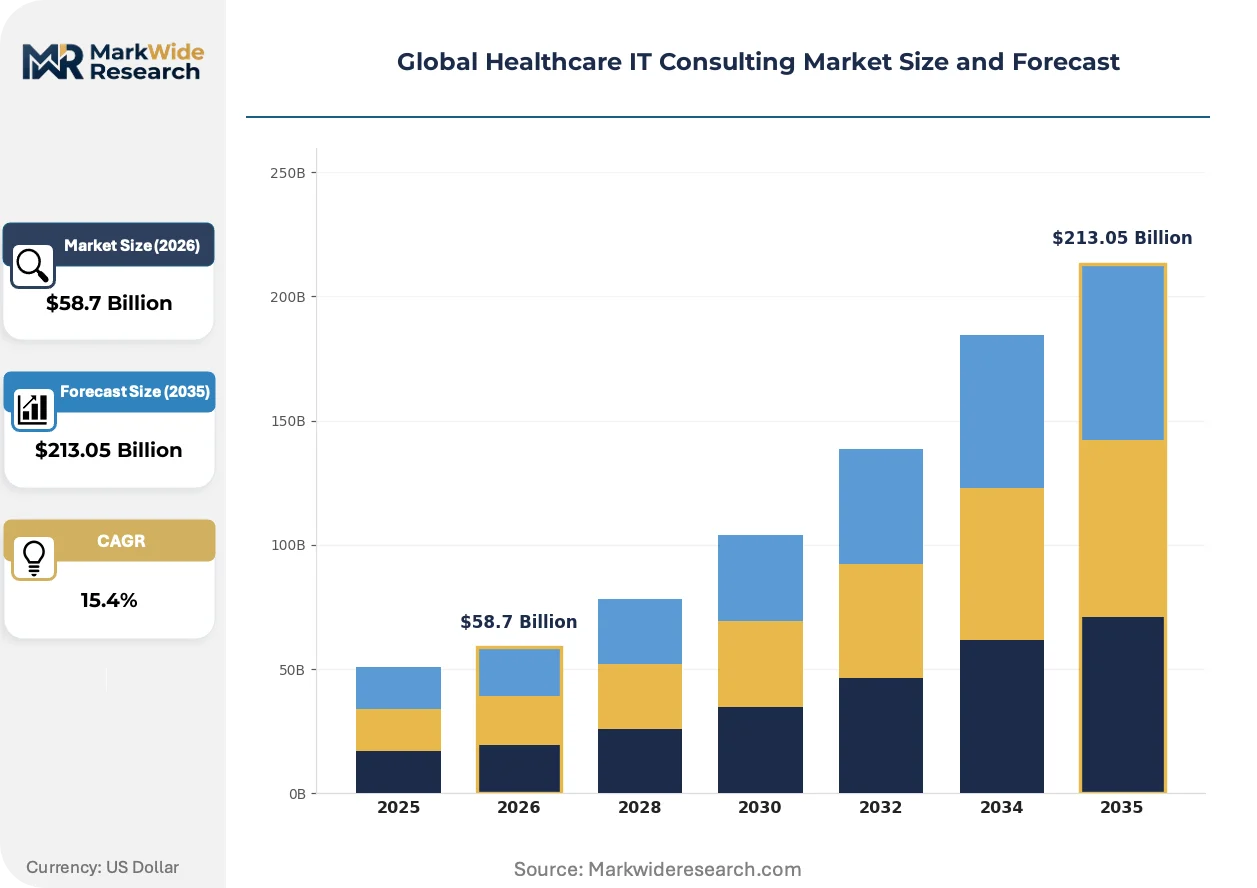
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $213.05 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Implementation, Strategy Advisory, Managed Services, System Integration, Training & Support Technology Focus: Electronic Health Records, Telemedicine, Cloud Computing, Data Analytics, Cybersecurity Client Type: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutions, Long-Term Care Facilities Deployment Model: On-Premise, Hybrid Cloud, Public Cloud, Private Cloud, Virtual Desktop Infrastructure |
| Companies Covered | Accenture, Deloitte Touche Tohmatsu Limited, IBM Corporation, Cognizant, HCL Technologies Limited, Ernst & Young Global Limited, McKesson Corporation, Optum, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare IT Consulting Market Shifts & Advancements
Healthcare IT consulting is pivoting from system installation toward continuous optimization models as cloud-native architectures enable iterative deployment cycles rather than decade-long EHR replacement programs.
Containerized microservices architecture is virtualizing traditional monolithic EHR deployments into modular, API-interchangeable components. Large hospital networks in the United States are adopting Kubernetes-orchestrated clinical workloads at accelerating pace. This virtualization is compressing vendor lock-in and enabling best-of-breed substitution without full-platform replacement.
The EU AI Act risk-classification framework for health algorithms imposes conformity assessment obligations that reshape consulting scope. Implementation services must now incorporate algorithmic impact documentation and human-oversight protocol design. German hospital systems face the steepest compliance burden as they process high-risk diagnostic AI under dual GDPR and AI Act jurisdiction.
Hospital procurement committees are unbundling implementation from ongoing managed services, creating discrete vendor relationships for migration, optimization, and security monitoring. Traditional end-to-end consulting contracts fragment into specialized engagements with distinct KPI structures. This unbundling is most advanced in California and Texas health systems with mature vendor management offices.
Global Healthcare IT Consulting Market Segmentation
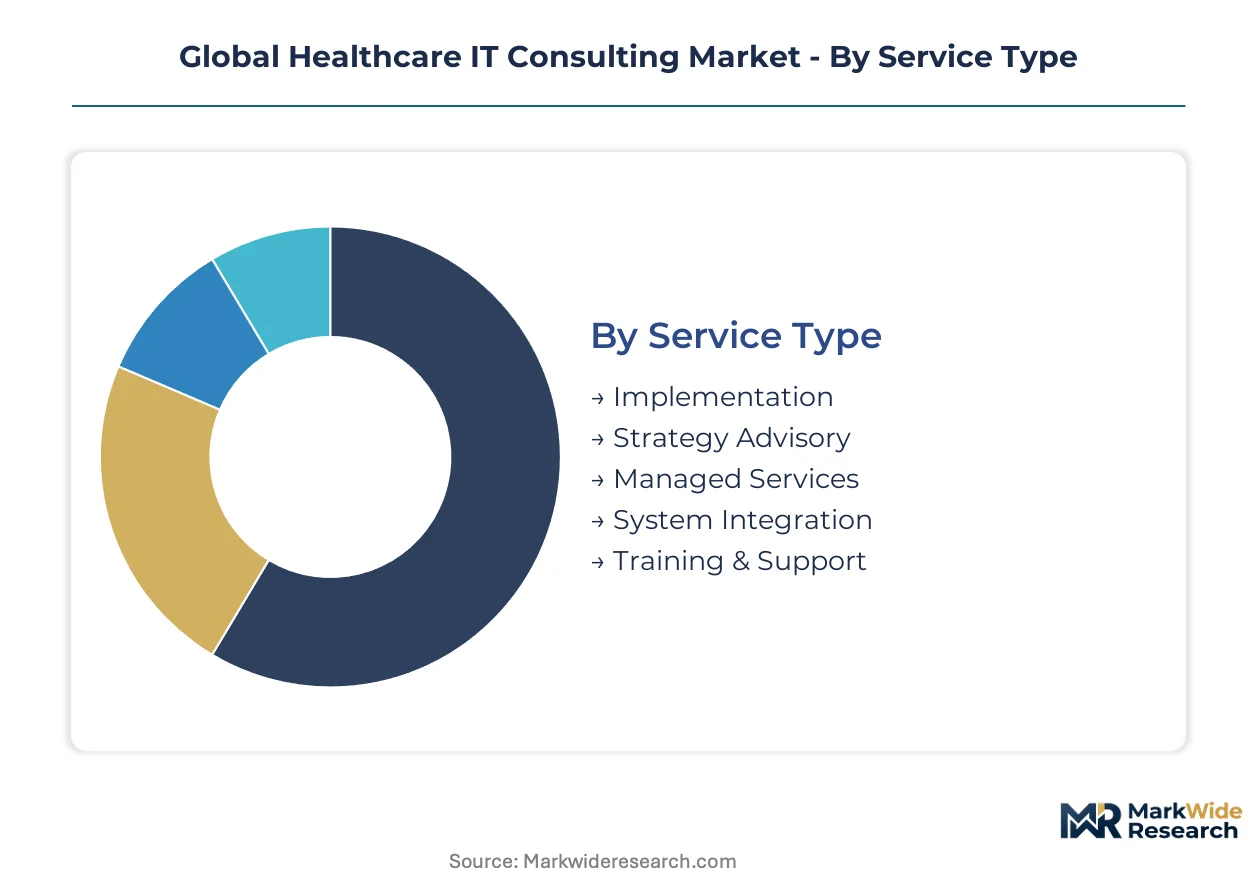
Healthcare IT consulting engagements fragment across service modalities, technology domains, and client infrastructure maturity. Understanding these fault lines reveals where specialized expertise commands premium pricing and where commoditization pressures concentrate.
Service Type:
Use-case complexity spans from discrete implementation sprints to continuous operational partnerships.
- Implementation:Phased migration of legacy EHR systems to cloud-native architectures dominates procurement volume. Hospital networks in Germany and the United States drive concentrated demand as HIPAA and GDPR interoperability deadlines compress project timelines.
- Strategy Advisory:C-suite engagements around digital transformation roadmapping and regulatory compliance architecture. Saudi Arabian hospital systems seeking SFDA software-as-a-medical-device guidance represent the steepest expansion trajectory for specialized advisory practices.
- Managed Services:Ongoing operational support for cloud infrastructure and security monitoring.
- System Integration:HL7 FHIR interface mapping and API orchestration across fragmented SaaS modules.
- Training & Support:Change management and clinical workflow optimization for new technology deployments.
The dominant share belongs to Implementation, while Strategy Advisory is closing the gap fastest.
Technology Focus:
Technology concentration reflects where regulatory pressure and clinical risk intersect most acutely.
- Cybersecurity:Zero-trust architecture deployment and ransomware response protocols command premium pricing. United States hospital systems facing OCR enforcement actions drive procurement concentration for HIPAA-compliant breach notification and forensic services.
- Electronic Health Records:Modernization of monolithic EHR installations through containerized microservices architecture. Large integrated delivery networks in Texas and California lead unbundling of legacy vendor contracts.
- Cloud Computing:Hybrid and multi-cloud orchestration for clinical workloads.
- Data Analytics:Population health management and value-based care reporting infrastructure.
- Telemedicine:Virtual care platform integration with existing clinical workflows.
Cybersecurity maintains the revenue lead, though Electronic Health Records modernization is gaining share most rapidly as replacement cycles accelerate.
Client Type:
Organizational scale determines consulting engagement structure and procurement authority.
- Hospitals:Enterprise-wide digital transformation programs spanning EHR replacement through cybersecurity hardening. Academic medical centers in the United States and university hospital networks in Germany anchor demand for end-to-end consulting relationships.
- Specialty Clinics:Focused implementations of practice-specific clinical systems and revenue cycle optimization. Ambulatory surgical centers and cardiology groups in California represent concentrated growth for modular, rapid-deployment services.
- Diagnostic Laboratories:LIS integration with hospital EHRs and regulatory compliance for test reporting.
- Research Institutions:Clinical trial data management and FDA submission support systems.
- Long-Term Care Facilities:Electronic medication administration records and care coordination platforms.
Hospitals capture the largest engagement value, with Specialty Clinics expanding most quickly as consolidation creates multi-site ambulatory networks requiring standardization.
Deployment Model:
Infrastructure choices reflect data sovereignty requirements and legacy technical debt positions.
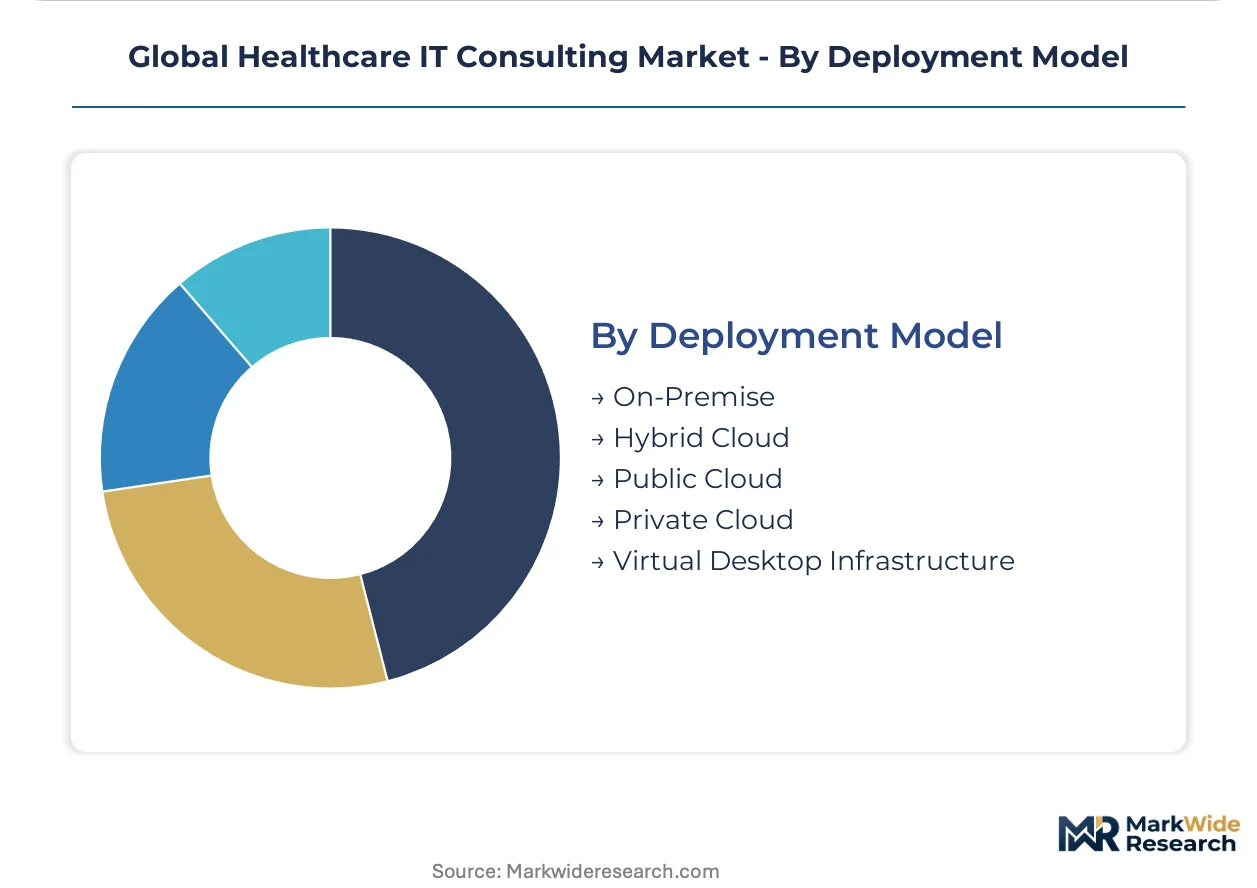
- Hybrid Cloud:Workload distribution between on-premise clinical systems and cloud-based analytics pipelines. German hospital networks under dual GDPR and EU AI Act jurisdiction drive specialized demand for data localization architecture.
- Private Cloud:Dedicated infrastructure for high-risk diagnostic AI and regulated clinical workloads. Saudi Arabian health systems pursuing SFDA software-as-a-medical-device certification favor this model for algorithmic transparency documentation.
- On-Premise:Legacy retention for systems resisting cloud migration due to interface constraints.
- Public Cloud:Scalable infrastructure for non-clinical administrative and development environments.
- Virtual Desktop Infrastructure:Secure endpoint access for distributed clinical staff.
Hybrid Cloud holds the prevailing position, while Private Cloud is climbing fastest as algorithmic transparency mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and large integrated delivery networks concentrate procurement authority for multi-year digital transformation programs. Hospital systems in Germany and the United States currently drive the steepest spending trajectories for cloud migration and cybersecurity hardening services.
United States
Academic medical centers in Boston and Houston anchor demand for end-to-end EHR modernization and zero-trust security architecture. The Office for Civil Rights enforces HIPAA information blocking rules that compel FHIR interface deployments by 2026 deadlines. Texas Health Systems in Dallas-Fort Worth unbundles legacy vendor contracts for containerized microservices migration.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia require dual-compliance architecture for AI-enabled diagnostic tools. The EU AI Act and GDPR impose algorithmic transparency mandates and cross-border data localization constraints. Berlin-Brandenburg health clusters concentrate procurement for explainability framework implementation and post-market surveillance protocol design.
Saudi Arabia
Ministry of Health digitization initiatives drive concentrated demand for software-as-a-medical-device compliance advisory. The Saudi Food and Drug Authority (SFDA) regulatory frameworks create first-mover windows for localized compliance practices. Riyadh-based hospital systems favor private cloud deployments for algorithmic transparency documentation in diagnostic AI certification.
United Kingdom
NHS Trusts in London and Greater Manchester accelerate procurement for cybersecurity-hardening engagements following ransomware incidents. NHS Digital mandates for interoperability standards reshape consulting scope around HL7 FHIR mapping. The Southeast England cluster leads unbundling of implementation from managed services contracts with distinct KPI structures.
India
Corporate hospital chains in Maharashtra and Karnataka expand demand for cloud-native EHR implementations and revenue cycle optimization. The Ministry of Health and Family Welfare's digital health mission accelerates procurement for telemedicine platform integration. Hyderabad and Bengaluru technology corridors concentrate specialized talent pools for HL7 FHIR certification and cloud architecture credentials.
Global Healthcare IT Consulting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered engagement structures. Large professional services networks anchor enterprise-wide digital transformation programs spanning EHR modernization through cybersecurity hardening. Boutique regulatory compliance specialists command premium pricing for HIPAA breach-notification expertise and FDA software-as-a-medical-device guidance. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into AI-enabled clinical decision support validation services.
Within the full-service consulting tier, Deloitte Touche Tohmatsu Limited and Accenture exemplify archetypes competing for multi-year hospital network transformations. IBM Corporation occupies a distinct position leveraging analytics heritage for clinical data interoperability engagements. These three anchors represent divergent strategic postures: regulatory-compliant cloud migration specialization, end-to-end program delivery, and clinical intelligence platform integration respectively.
| Leading Market Players |
|---|
| Accenture |
| Deloitte Touche Tohmatsu Limited |
| IBM Corporation |
| Cognizant |
| HCL Technologies Limited |
| Ernst & Young Global Limited |
| McKesson Corporation |
| Optum |
| Cerner Corporation |
| Others |
Supply & Pricing Matrix
Ransomware liability exposure concentrates pricing power among boutique HIPAA breach-response specialists while compressing margins for commoditized implementation services. This risk asymmetry stratifies consulting tiers around cyber incident response retainers versus fixed-fee cloud migration contracts, reshaping how talent pipelines and subcontractor networks configure across delivery models.
Pricing Analysis
Cost-plus contracts indexed to certified consultant day rates dominate enterprise engagements, with premium multiples attaching to simultaneous HL7 FHIR and zero-trust architecture credentials. Price differentiation hinges on regulatory certification depth and geographic delivery cost, with United States-based cybersecurity hardening commanding substantial premiums over offshore system integration. Pricing pressure stems from hyperscaler-managed service encroachment on baseline cloud migration work. Academic medical centers exhibit lowest price sensitivity due to bundled digital transformation budgets, while ambulatory surgical centers negotiate aggressively on modular implementation sprints.
Supply Chain Analysis
Export-control restrictions on advanced encryption and AI training hardware constrain technology flows into certain consulting toolchains, particularly affecting firms serving diagnostic AI validation practices. Talent supply concentrates in India, Germany, and the United States, with Hyderabad and Bengaluru corridors feeding cloud architecture certification pipelines. Raw material dependencies include proprietary FHIR interface libraries, cybersecurity threat intelligence feeds, and cloud hyperscaler partnership tiers. Single-source vulnerability runs through elite regulatory compliance specialists holding simultaneous FDA and EU AI Act credentials. Distribution runs through direct enterprise sales teams and channel partnerships with GPOs and hospital purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
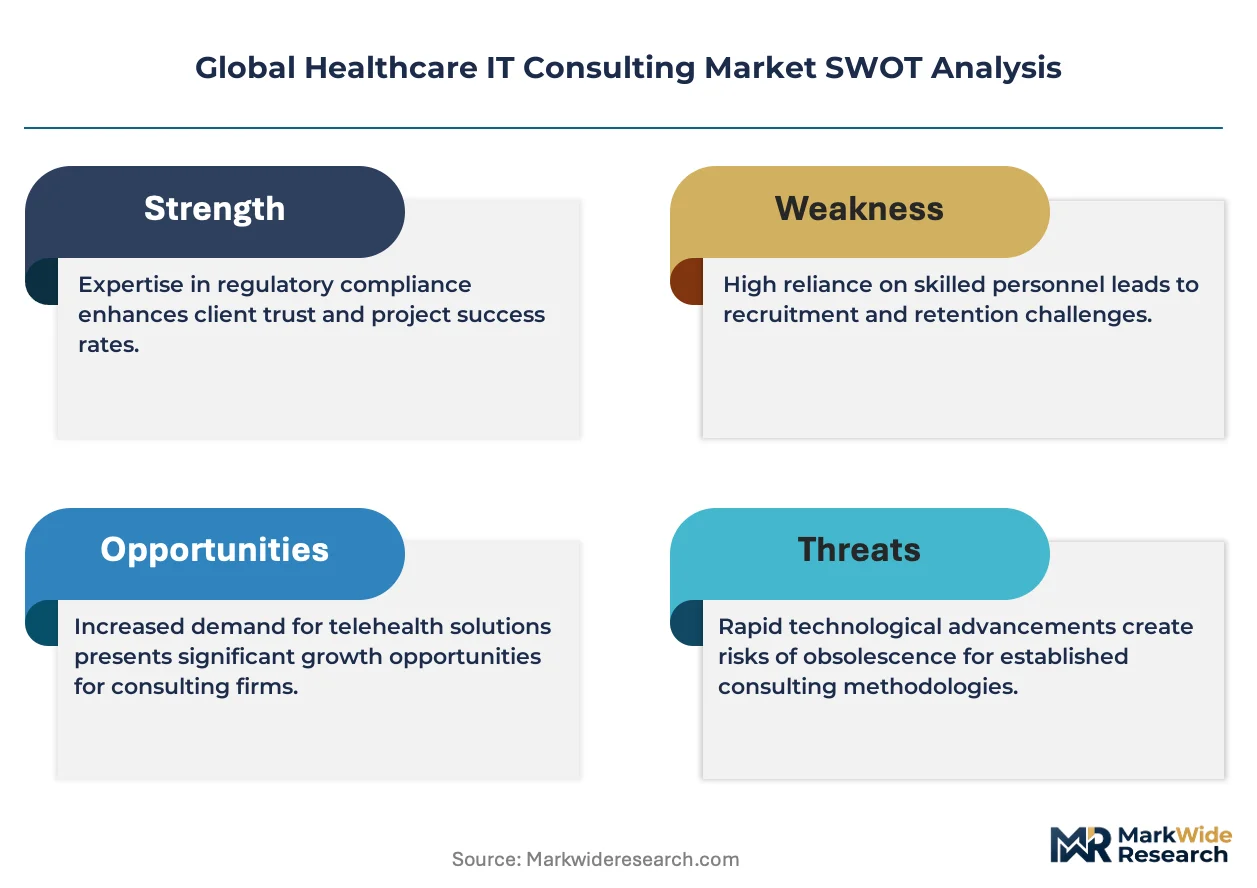
Regulatory entrenchment creates durable defensive moats as HIPAA interoperability mandates and EU AI Act compliance requirements raise switching costs for hospital systems. This structural advantage favors incumbents with established quality management system documentation and regulator relationships.
For Market Incumbents: Build certification moats through simultaneous investment in FDA pre-certification pathway expertise and EU AI Act conformity assessment capabilities. Deepen vertical integration into proprietary FHIR interface libraries to reduce dependency on open-source middleware. Defend against boutique regulatory specialists by acquiring algorithm validation practices in Riyadh and Berlin, where SFDA and dual GDPR-AI Act jurisdictions concentrate premium advisory demand. For New Entrants and Emerging Players: Pursue white-space penetration in Saudi Arabian hospital digitization, where SFDA software-as-a-medical-device frameworks create first-mover advisory windows before incumbent localization. Target value-based care workflow redesign for Medicare Advantage-focused integrated delivery networks in Texas and Florida, segments where bundled payment reimbursement shifts drive urgent demand but incumbent presence remains thin. Lead with rapid-deployment modular services priced below end-to-end transformation contracts to establish referenceability. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized regulatory compliance boutiques with defendable certification expertise over generalist implementation firms. Long-term viability hinges on exposure to algorithmic transparency mandates and post-market surveillance obligations rather than commoditized cloud migration. Target acquisition archetypes include HIPAA breach-response specialists with OCR enforcement relationships and AI validation practices holding FDA Q-Sub experience. Watch FDA software-as-a-medical-device guidance updates as inflection indicators for which consulting capabilities will command scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | Simultaneous FDA pre-certification and EU AI Act expertise captures premium pricing in German hospital networks. |
| Hospital System Partnership | Multi-year EHR modernization contracts with Texas Health Systems anchor recurring revenue and referenceability. |
| Acquisition of Specialist Firm | Boutique HIPAA breach-response practices add OCR enforcement relationships and ransomware forensic capabilities. |
| Geographic Expansion | Riyadh and Jeddah offices establish SFDA software-as-a-medical-device advisory presence before incumbent saturation. |
| Platform Integration | Kubernetes-orchestrated clinical workload partnerships with hyperscalers differentiate containerized microservices offerings. |
Research Methodology
Desk research of FDA guidance documents, EU AI Act implementing acts, and hospital procurement databases preceded structured interviews with chief information officers, biomedical informatics directors, GPO contracts managers, and cybersecurity officers at academic medical centers. Primary fieldwork with cloud architecture specialists and regulatory compliance consultants in Germany, Saudi Arabia, and the United States validated secondary findings on implementation timelines and certification bottlenecks. Bottom-up engagement sizing across service modalities triangulated against top-down spending estimates from health system capital budgets.
Analytical frameworks held regulatory enforcement intensity and cloud hyperscaler partnership structures fixed while varying hospital digital maturity and AI adoption trajectories across the projection horizon. Segmentation dimensions modeled include service type, technology focus, client infrastructure maturity, and regional regulatory cluster. CAGRs derived from weighted average of historical implementation cycle compression and forward-looking interoperability mandate deadlines, with inputs from HL7 FHIR deployment rates and ransomware incident frequency trends.
Sensitivities concentrate around FDA software-as-a-medical-device guidance acceleration, EU AI Act risk-classification revisions, and hyperscaler vertical integration into managed healthcare services. Forecasts reflect assumptions on consultant certification pipeline expansion and cross-border data localization enforcement. Material shifts in OCR information blocking rule timelines or SFDA regulatory framework evolution would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
UK Healthcare Consulting Market