
 Italy Operations Service Consulting Market | 2026-2036
Italy Operations Service Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Operations Service Consulting Market Foresight
Cloud-native analytics platforms is pivoting traditional on-premise ERP consulting toward subscription-based operational intelligence. Deloitte Touche Tohmatsu Limited leverages its Milan-based manufacturing practice to anchor large-scale Industry 4.0 transformations across Northern Italy. Accenture PLC competes through dedicated digital operations studios in Rome and Turin. McKinsey & Company Inc specializes in private-equity-backed operational turnaround engagements for mid-market Italian industrials.
Italy Operations Service Consulting encompasses advisory and implementation services that optimize production workflows, reduce operational waste, and align enterprise processes with regulatory and financial performance targets. Technical specifications typically include ISO 9001-aligned quality management system redesigns, lean Six Sigma process mapping, and ERP integration protocols that synchronize shop-floor data with enterprise resource planning layers. Process Improvement engagements generate the deepest margin pools due to recurring diagnostic retainers and measurable KPI-linked fees. Supply Chain Optimization shows the fastest expansion as Italian exporters rebuild buffer inventory strategies and nearshore supplier networks post-disruption. Compliance Services remains mature, with fee pressure from standardized GDPR and CSRD reporting templates.
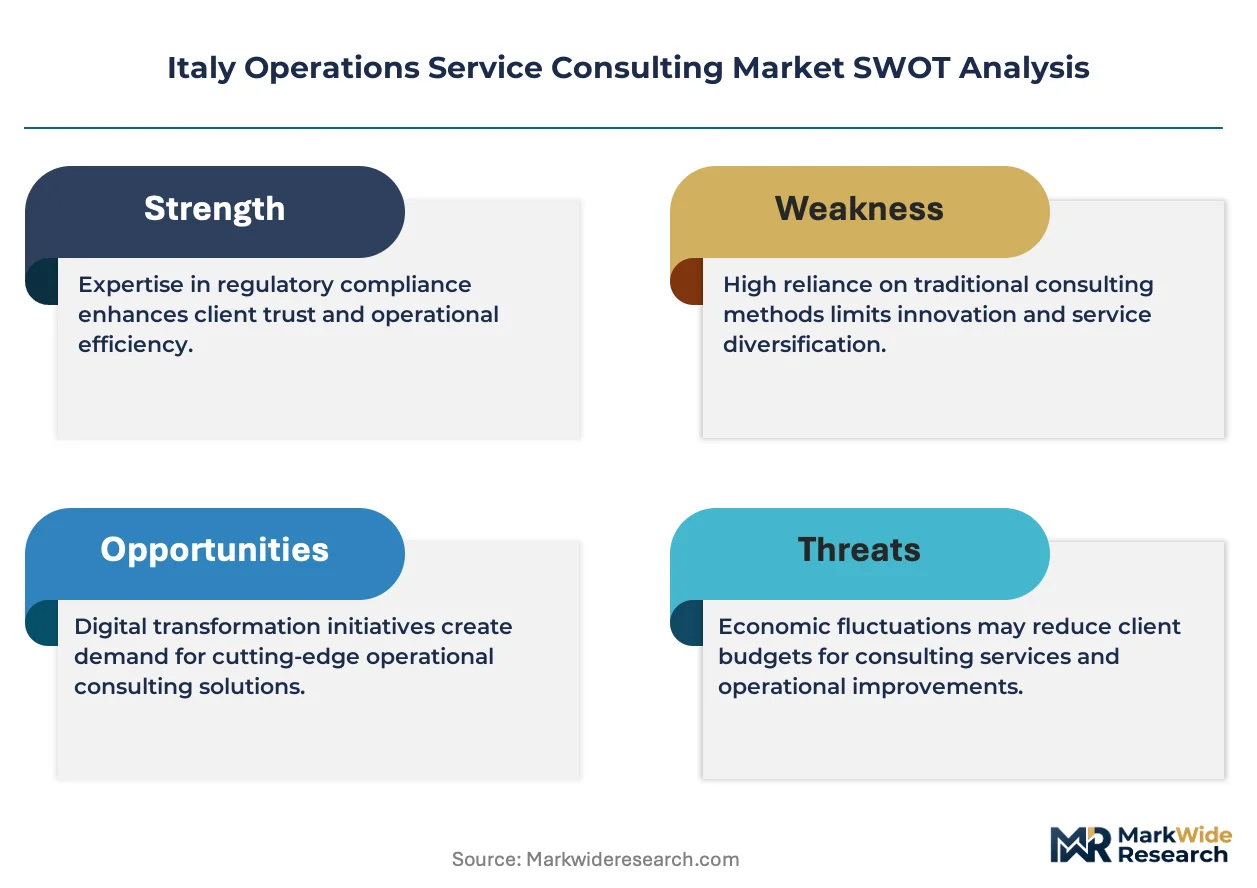
Italy's PNRR implementation rules require operational certification from accredited consultants for infrastructure and energy-transition disbursements. CE marking alignment and EU CSRD sustainability reporting obligations compel manufacturers to retain external operational auditors. The country's national pharmaceutical regulator, AIFA, enforces Good Manufacturing Practice (GMP) consulting mandates that sustain healthcare vertical demand. Stakeholders must monitor whether Rome extends PNRR compliance requirements beyond current sunset clauses or folds them into permanent industrial policy.
Market Dynamics
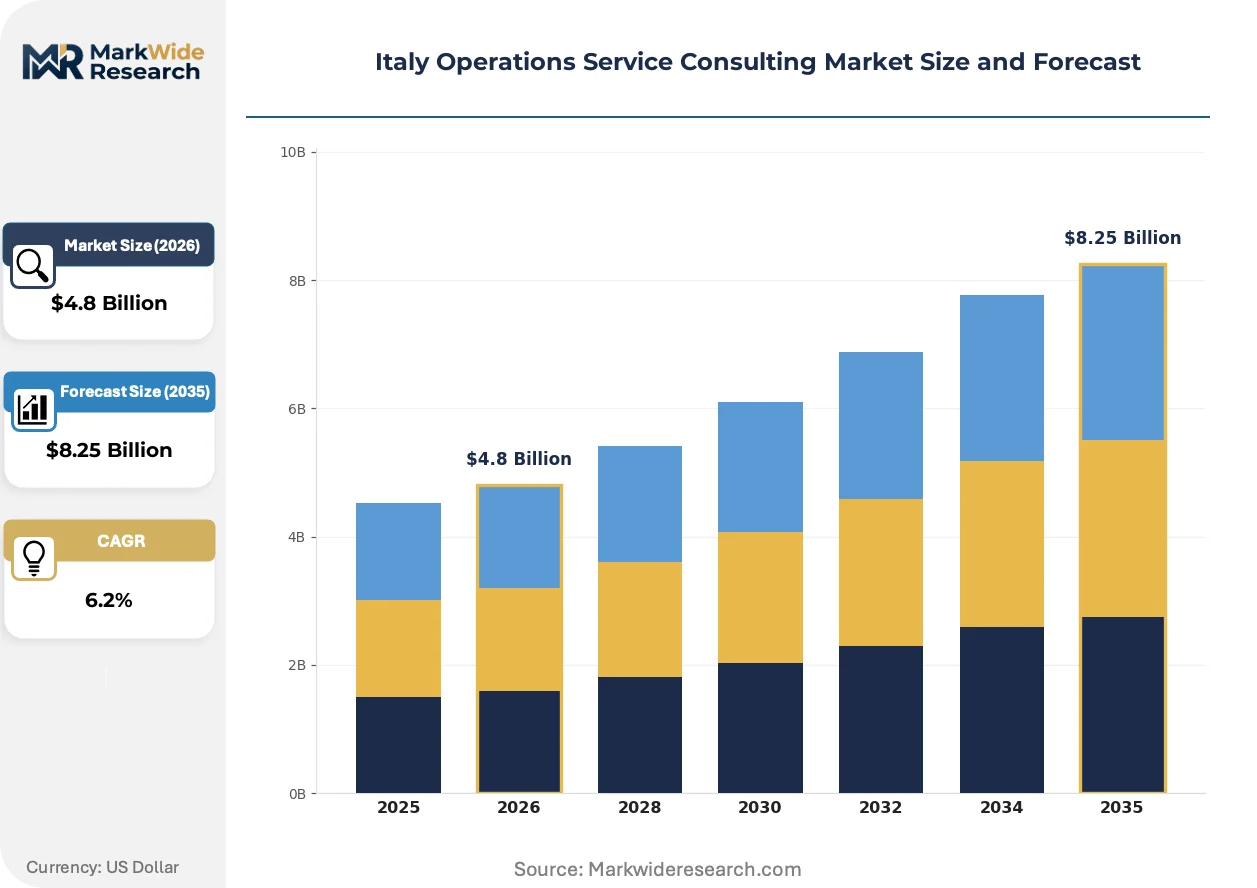
Italy's National Recovery and Resilience Plan (PNRR) is compressing procurement timelines for operational certification services while mandating digital twin integration across EU-funded infrastructure disbursements. This regulatory-engineered demand surge is restructuring consultant-client relationships toward continuous diagnostic retainers rather than discrete project fees.
Growth Catalysts
- PNRR Operational Audits:Infrastructure and energy-transition projects require accredited consultant certification for fund release, creating a captive revenue stream tied to public disbursement schedules.
- Digital Twin Adoption:Automotive manufacturers in Turin's industrial cluster are deploying factory optimization simulations that demand ongoing operational advisory support for model calibration and scenario testing.
- CSRD Sustainability Reporting:EU Corporate Sustainability Reporting Directive obligations compel mid-market industrials to retain external auditors for supply-chain emissions verification and operational data alignment.
Market Restraints
- Fee Compression in Compliance:Standardized GDPR and CSRD reporting templates are commoditizing traditional audit services, squeezing margins on recurring certification work.
- Skill Concentration in Northern Italy:Lean Six Sigma and Industry 4.0 expertise clusters disproportionately in Milan and Turin, limiting service scalability to Central and Southern regions.
- ERP Integration Complexity:Legacy on-premise systems at family-owned manufacturing SMEs resist cloud-native analytics migration, extending implementation timelines and deferring revenue recognition.
Strategic Opportunities
- Central Italy Industrial Corridors:Tuscany and Emilia-Romagna manufacturing bases remain underpenetrated by dedicated operational consulting practices, offering first-mover expansion potential.
- Pharmaceutical GMP Mandates:AIFA enforcement of Good Manufacturing Practice consulting requirements sustains healthcare vertical demand with long-term retainer structures.
- Nearshoring Supply Chain Redesign:Exporters rebuilding buffer inventory strategies and domestic supplier networks post-disruption require operational workflow reconfiguration services.
Industry Challenges
- Certified Talent Scarcity:ISO 9001 lead auditor and Six Sigma Black Belt credentials are concentrated among senior practitioners approaching retirement, constraining practice headcount growth.
- Multi-stakeholder Coordination:PNRR-funded projects require simultaneous alignment with Rome's Ministry of Economy, regional procurement offices, and EU disbursement authorities, multiplying administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Operations Service Consulting Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Improvement, Change Management, Supply Chain Optimization, Compliance Services Client Type: Manufacturers, Retailers, Financial Institutions, Technology Firms Engagement Model: Consulting Projects, Advisory Services, Workshops, Implementation Support Industry Vertical: Consumer Goods, Automotive, Healthcare, Telecommunications |
| Companies Covered | Ernst & Young Italy Limited, Capgemini SE, Deloitte Touche Tohmatsu Limited, McKinsey & Company Inc, Boston Consulting Group Inc, Accenture PLC, KPMG International, Bain & Company Inc, PricewaterhouseCoopers LLP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Operations Service Consulting Market Shifts & Advancements
Cloud-native operational intelligence platforms are absorbing the analytical functions once performed by on-premise ERP modules, redefining how Italian manufacturers purchase consulting expertise. This technological inflection is compressing traditional implementation cycles while expanding recurring diagnostic service contracts.
Digital twin technology is absorbing capital allocation from physical prototyping and pilot production lines. Automotive and aerospace suppliers in Piedmont are deploying virtual factory simulations to test workflow modifications before shop-floor deployment. This adoption pattern is absorbing consulting hours into continuous model maintenance rather than discrete process redesign engagements.
EU CSRD disclosure requirements are mandating granular operational data collection across Scope 1, 2, and 3 emissions categories. Manufacturing exporters must now synchronize shop-floor energy monitoring with enterprise sustainability reporting systems. Food processing and textile verticals in Northern Italy face the steepest compliance curves, driving demand for integrated operational and environmental audit services.
Subscription-based operational intelligence contracts are displacing traditional time-and-materials consulting arrangements. Milan-headquartered financial services firms and Turin-based industrial automation clusters are piloting KPI-linked fee structures that tie consultant compensation to measurable efficiency gains. This procurement evolution is most advanced among private-equity-backed portfolio companies seeking rapid operational turnaround documentation.
Italy Operations Service Consulting Market Segmentation
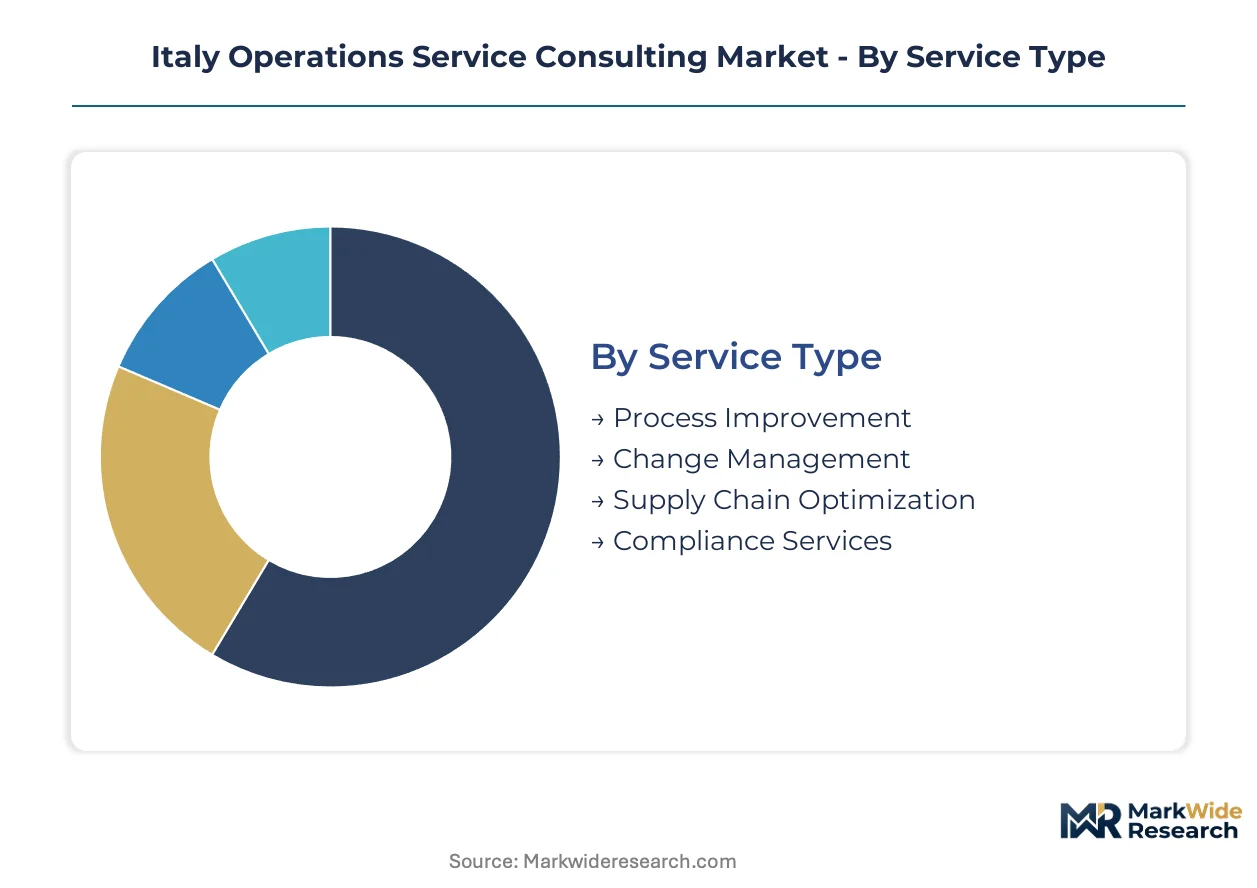
Segmentation in Italy's operations consulting market reveals distinct procurement patterns across service types, client profiles, and engagement structures. These divisions expose where standardization pressures collide with bespoke advisory requirements.
Service Type:
Standardization potential varies sharply across this category, with diagnostic methodologies commoditizing faster than implementation frameworks.
- Process Improvement:Lean Six Sigma process mapping and ISO 9001-aligned quality management system redesigns anchor this segment. Milan's financial services corridor and Turin's industrial automation cluster generate concentrated demand for recurring diagnostic retainers with measurable KPI-linked fee structures.
- Supply Chain Optimization:Buffer inventory strategy redesign and nearshore supplier network reconfiguration define technical scope. Italian exporters rebuilding post-disruption logistics generate the steepest expansion trajectory as procurement teams prioritize operational resilience over cost minimization.
- Change Management:Organizational transformation and workforce transition advisory services. Family-owned manufacturing SMEs in Central Italy resist cloud-native analytics migration, extending implementation timelines.
- Compliance Services:GDPR and CSRD reporting template standardization. Fee compression intensifies as regulatory templates commoditize traditional audit functions.
Most installed capacity flows through Process Improvement. Expansion is steepest in Supply Chain Optimization.
Client Type:
Procurement sophistication creates a cost-to-complexity gradient, with large institutions demanding outcome-linked contracts while mid-market players retain time-and-materials structures.
- Manufacturers:Automotive and aerospace suppliers in Piedmont deploy digital twin simulations for factory optimization. PNRR operational audit mandates create captive revenue tied to public disbursement schedules.
- Financial Institutions:Milan-headquartered banks and insurers pilot subscription-based operational intelligence with KPI-linked fee structures. Cloud-native analytics platforms displace traditional on-premise ERP consulting arrangements.
- Retailers:Omnichannel inventory management and last-mile logistics optimization. Standardized demand forecasting tools limit customization premiums.
- Technology Firms:Agile operational frameworks and DevOps workflow integration. Smaller addressable base constrains dedicated practice investment.
Manufacturers command the deepest advisory relationships. Financial Institutions are gaining share fastest through procurement innovation.
Engagement Model:
Revenue recognition timing separates this category, with discrete project fees yielding immediate cash conversion against deferred diagnostic retainers.
- Consulting Projects:Discrete process redesign with defined deliverables and fixed pricing. Legacy on-premise ERP integration complexity extends timelines for family-owned manufacturing SMEs.
- Advisory Services:Continuous diagnostic retainers replacing time-and-materials arrangements. Private-equity-backed portfolio companies in Northern Italy drive adoption of efficiency-gain-linked compensation.
- Workshops:Training-intensive knowledge transfer for ISO 9001 lead auditor and Six Sigma Black Belt certification. Certified talent scarcity among senior practitioners approaching retirement constrains scalability.
- Implementation Support:Hands-on deployment assistance for ERP integration protocols. Shop-floor data synchronization with enterprise resource planning layers demands specialized technical expertise.
Advisory Services capture expanding share through recurring revenue structures. Implementation Support faces margin pressure from talent constraints.
Industry Vertical:
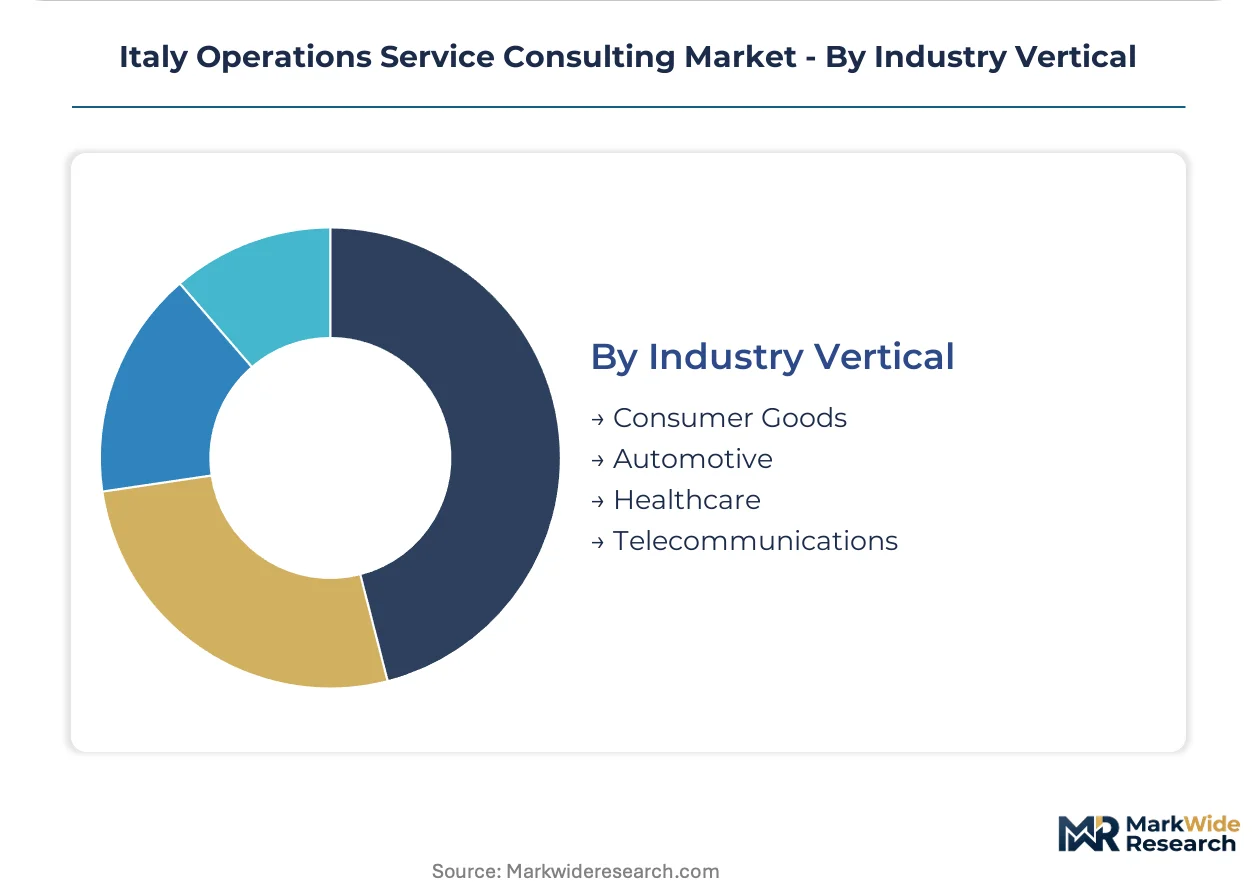
Regulatory exposure and operational complexity stratify this category, with healthcare and automotive commanding premium pricing against commoditized consumer goods.
- Healthcare:AIFA-mandated Good Manufacturing Practice consulting sustains long-term retainer demand. Pharmaceutical manufacturers face steep compliance curves for operational data alignment with sustainability reporting.
- Automotive:Digital twin technology deployment for virtual factory simulation and workflow modification testing. Turin's industrial cluster absorbs consulting hours into continuous model maintenance.
- Consumer Goods:Food processing and textile verticals in Northern Italy face EU CSRD disclosure requirements for Scope 1, 2, and 3 emissions verification. Integrated operational and environmental audit services gain traction.
- Telecommunications:Network operations center optimization and infrastructure deployment project management. Standardized methodologies limit differentiation potential.
Healthcare retains the most durable revenue base. Consumer Goods is climbing the fastest as CSRD obligations expand the addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Italy's industrial triangle anchors national consulting demand, with Milan's financial corridor and Turin's automation cluster generating disproportionate advisory revenue relative to population share.
Lombardy
Milan-headquartered financial institutions pilot subscription-based operational intelligence with KPI-linked fee structures. CE marking alignment and EU CSRD sustainability reporting obligations compel manufacturers to retain external operational auditors. The metropolitan region absorbs the deepest share of Industry 4.0 transformation advisory hours.
Piedmont
Automotive manufacturers deploy digital twin simulations for factory optimization and workflow modification testing. Italy's National Recovery and Resilience Plan mandates operational certification for EU-funded infrastructure disbursements. Turin's industrial cluster absorbs consulting hours into continuous model maintenance rather than discrete project engagements.
Veneto
Export-oriented manufacturing bases rebuild buffer inventory strategies and nearshore supplier networks post-disruption. AIFA enforcement of Good Manufacturing Practice consulting requirements sustains healthcare vertical demand. The region's pharmaceutical corridor generates long-term retainer structures for operational compliance services.
Emilia-Romagna
Food processing verticals face steep EU CSRD compliance curves for Scope 1, 2, and 3 emissions verification. The country's national pharmaceutical regulator enforces operational data alignment mandates. Bologna-Modena manufacturing bases remain underpenetrated by dedicated operational consulting practices.
Lazio
Public sector procurement offices coordinate multi-stakeholder PNRR project alignment with Rome's Ministry of Economy. Infrastructure and energy-transition projects require accredited consultant certification for fund release. The capital region concentrates administrative overhead for EU disbursement authority coordination.
Italy Operations Service Consulting Market Competitive Landscape
Strategic partnerships dominate the current landscape as consulting firms anchor Industry 4.0 transformation engagements through continuous diagnostic retainers. The vendor base concentrates among multinational professional services networks with established Italian manufacturing practices. Three archetypes define competitive positioning: premium-tier strategy houses, scale-driven technology integrators, and specialized operational compliance boutiques. M&A activity and cloud-native platform partnerships represent the dominant competitive moves reshaping service delivery models.
Among scale-driven technology integrators, Accenture PLC and Capgemini SE exemplify the digital operations studio model with dedicated facilities in Rome and Turin. Deloitte Touche Tohmatsu Limited occupies a position representing premium-tier advisory anchored through Milan-based manufacturing practice strength. These three firms illustrate how multinational networks leverage geographic practice concentration to capture PNRR-mandated certification demand and private-equity-backed operational turnaround engagements.
| Leading Market Players |
|---|
| Ernst & Young Italy Limited |
| Capgemini SE |
| Deloitte Touche Tohmatsu Limited |
| McKinsey & Company Inc |
| Boston Consulting Group Inc |
| Accenture PLC |
| KPMG International |
| Bain & Company Inc |
| PricewaterhouseCoopers LLP |
| Others |
Supply & Pricing Matrix
Cloud-native operational intelligence platforms are compressing traditional ERP implementation timelines while simultaneously redistributing supply-side expertise toward Milan and Turin. This technological transition concentrates certified Six Sigma Black Belt and ISO 9001 lead auditor talent in Northern Italy's industrial triangle, amplifying regional pricing power for high-complexity engagements.
Pricing Analysis
Input-cost pass-through from certified practitioner scarcity flows directly into advisory fee structures, with senior auditor compensation inflation transmitting to client rates. Three-tier pricing structure across premium strategy houses, scale-driven integrators, and specialized compliance boutiques stratifies the market. Pricing pressure stems from standardized GDPR and CSRD template commoditization squeezing compliance margins. Mid-market manufacturing SMEs exhibit highest price sensitivity, while private-equity-backed industrials accept KPI-linked premium structures.
Supply Chain Analysis
Direct-to-manufacturer channels handle Tier 1 automotive and pharmaceutical advisory demand, with Milan-based practices anchoring multinational client relationships. Supply concentrates in Italy, Germany, and France for ISO-certified operational audit expertise. Raw material dependencies include cloud infrastructure subscriptions, specialized diagnostic software licenses, and cross-border talent mobility arrangements. Single-source vulnerability resides in senior practitioner retirement waves. Distribution runs through continuous diagnostic retainers displacing discrete project engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy Operations Service Consulting functions as a stable compounder anchored by PNRR-mandated certification requirements that institutionalize recurring revenue streams across public infrastructure disbursement cycles.
For Market Incumbents: Extend digital twin implementation capabilities into Emilia-Romagna's underpenetrated manufacturing corridor before regional competitors establish practice density. Consolidate ISO 9001 lead auditor certification pipelines through structured apprenticeship programs to offset senior practitioner retirement risk. Vertical integration into proprietary cloud-native analytics platforms deepens client switching costs.
For New Entrants and Emerging Players: Enter via Tuscany's food processing vertical where EU CSRD Scope 3 emissions verification demand outpaces established consulting capacity. Target pharmaceutical GMP advisory services in Veneto's healthcare corridor where AIFA mandates sustain long-term retainer structures. Deploy outcome-based pricing models to differentiate from incumbent time-and-materials conventions.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market operational compliance boutiques with concentrated PNRR certification revenue and defensible regional client relationships. Five-to-ten-year viability hinges on Rome's extension of operational audit mandates beyond current sunset clauses. Monitor PNRR disbursement acceleration rates as inflection indicator for advisory demand cyclicality.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Partnership | Automotive suppliers in Turin deploy virtual factory simulations requiring continuous model calibration support. |
| CSRD Compliance Service Launch | Food processors in Emilia-Romagna face steep emissions verification curves driving integrated audit demand. |
| PNRR Certification Practice Acquisition | Accredited consultant scarcity in Central Italy creates first-mover consolidation opportunity. |
| Cloud-Native Analytics Integration | Financial institutions in Milan pilot subscription-based operational intelligence displacing legacy ERP. |
| Six Sigma Certification Pipeline Investment | Retirement waves among Black Belt practitioners constrain scalable practice headcount growth. |
Research Methodology
Bottom-up manufacturing and financial services modeling reconciled against top-down professional services capacity tracking forms the analytical core. Primary interviews with operations directors at automotive OEMs, compliance officers at pharmaceutical manufacturers, procurement leads at Milan-headquartered banks, and PNRR program administrators in Rome's Ministry of Economy combined with secondary validation from EU disbursement authority filings, AIFA regulatory notices, and ISO certification registry data. Triangulation across these sources ensures segment-level accuracy.
Historical trendline analysis of advisory fee structures and practitioner supply dynamics informed projection frameworks across service type, client profile, engagement model, and industry vertical dimensions. CAGRs derive from regression-weighted growth rates applied to PNRR disbursement schedules and digital twin adoption curves. Forecast inputs incorporate CSRD implementation timelines and nearshoring supply chain redesign velocity among Italian exporters.
The model holds under stable PNRR mandate continuity and gradual cloud-native platform migration; deviation in regulatory sunset extensions or accelerated legacy ERP replacement would shift growth trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Regulatory Affairs Market