
 Australia Dental Devices Market | 2026-2036
Australia Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Dental Devices Market Outlook
TGA certification under the Essential Principles for active implantable medical devices is redrawing competitive boundaries for foreign manufacturers seeking Australian market access. Dentsply Sirona leverages its integrated CAD/CAM workflow portfolio to dominate digital restoration workflows in metropolitan practices. Straumann Group anchors its position through captive implant-abutment-prosthesis ecosystems that lock in recurring consumable revenue. Envista Holdings differentiates via specialized orthodontic and imaging equipment targeting mid-tier clinic chains.
Dental devices encompass instruments, apparatus, and systems designed for diagnosis, treatment, or prevention of oral conditions, typically manufactured from biocompatible titanium alloys, cobalt-chrome, or zirconia ceramics through precision milling or selective laser sintering processes. Their primary commercial purpose is to restore masticatory function and aesthetic outcomes in patients with missing, damaged, or misaligned dentition. Dental implants command premium positioning due to surgical complexity and long-term follow-up requirements that create sticky clinician relationships. CAD/CAM software and 3D printing represent the fastest-expanding technology layer as chairside production compresses laboratory turnaround from weeks to hours. Orthodontic devices sustain volume leadership through adolescent clear-aligner demand and adult retreatment cycles.
The Therapeutic Goods Administration enforces medical device regulations aligned with the Australian Regulatory Guidelines for Medical Devices, while the Dental Board of Australia governs practitioner scope and continuing professional development requirements that shape equipment purchasing authority. Compliance with ISO 13485 quality management systems and IEC 60601 electrical safety standards remains mandatory for market authorization, effectively filtering out smaller offshore suppliers lacking dedicated regulatory affairs capacity. Stakeholders must monitor TGA consultation papers on software as a medical device, as pending reclassifications could force substantial re-registration investments for AI-powered diagnostic tools.
Market Dynamics
Digital dentistry workflows are compressing traditional laboratory turnaround times from weeks to hours, forcing capital equipment upgrades across Australian private practices while TGA reclassification of active implantable devices tightens compliance for imported systems.
Growth Catalysts
- Chairside CAD/CAM Adoption:Metropolitan prosthodontic practices in Sydney and Melbourne are deploying intraoral scanners and milling units to capture same-day restoration revenue previously lost to external laboratories.
- TGA Essential Principles Alignment:The Therapeutic Goods Administration's streamlined conformity assessment pathways for Class IIb devices are accelerating market authorization timelines for ISO 13485-certified manufacturers.
- Clear-Aligner Retreatment Cycles:Adult orthodontic demand for aesthetic correction is generating recurring consumable orders through specialist practices clustered near teaching hospitals.
Market Restraints
- Titanium Alloy Supply Concentration:Australian device manufacturers remain dependent on imported feedstock from limited Asian smelters, exposing margins to commodity volatility and freight cost spikes.
- IEC 60601 Electrical Safety Compliance:Mandatory third-party testing for powered dental equipment creates fixed cost barriers that disproportionately burden smaller clinic chains seeking multi-unit purchases.
- Zirconia Ceramic Substitution Threat:Advances in high-strength glass-ceramics are eroding premium positioning for traditional metal-ceramic restorations in anterior aesthetic cases.
Strategic Opportunities
- Regional Queensland Expansion:Specialist prosthodontic coverage remains sparse outside Brisbane, creating first-mover potential for mobile CAD/CAM service models targeting regional health networks.
- AI-Powered Diagnostic Tools:Pending TGA consultation on software as a medical device classification presents early-entrant advantage for radiographic analysis platforms seeking pre-market positioning.
- Orthodontic-Periodontic Convergence:Integration of clear-aligner planning with guided implant placement is opening bundled procedure revenue streams in multi-disciplinary Sydney practices.
Industry Challenges
- Digital Workflow Integration Complexity:Legacy practice management systems in established Melbourne clinics resist seamless data exchange with new chairside production hardware, forcing costly middleware investments.
- Prosthodontic Technician Skill Compression:Rapid adoption of automated milling and 3D printing is shrinking demand for conventional waxing and casting expertise, creating workforce transition friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Dental Devices Market |
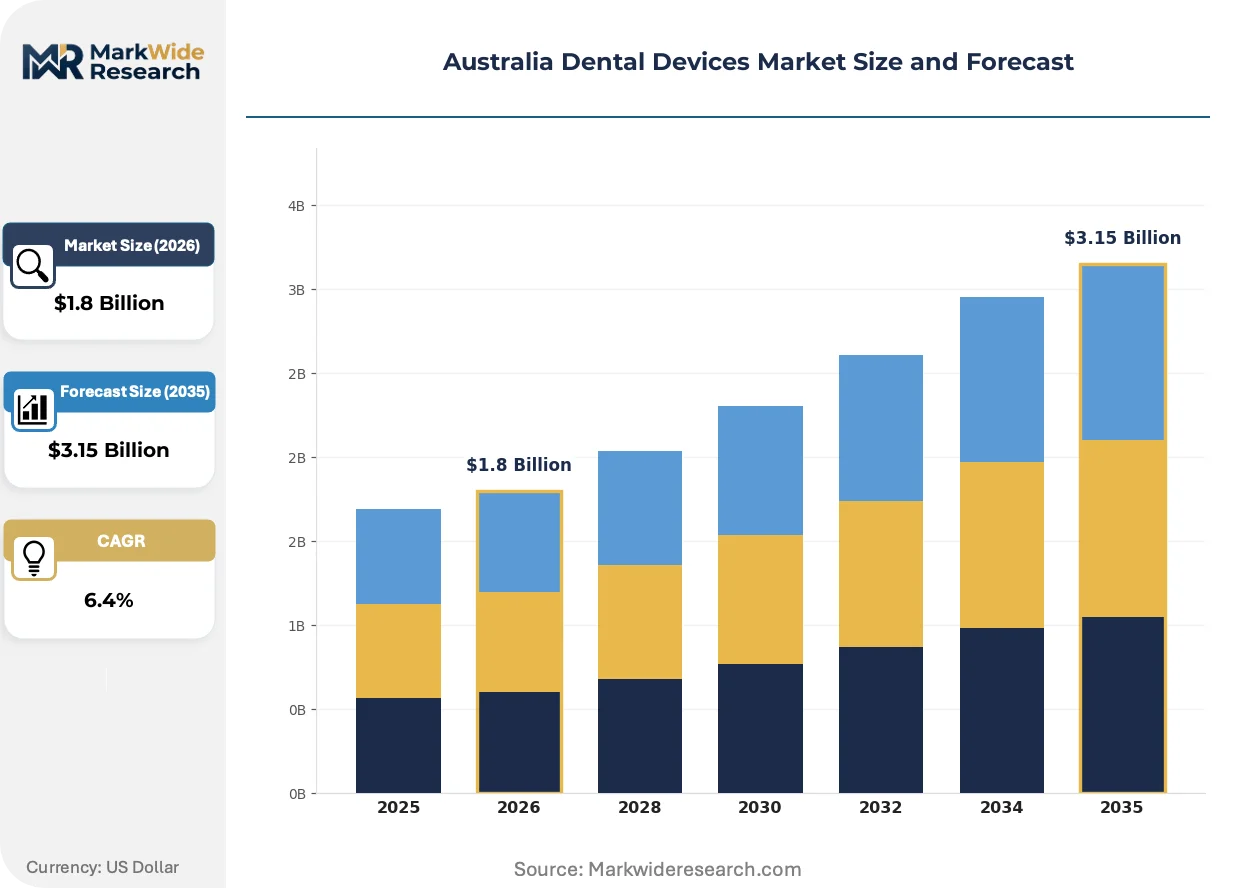
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Implants, Orthodontic Devices, Endodontic Equipment, Dental Crowns Application: Restorative Dentistry, Cosmetic Dentistry, Periodontics, Orthodontics Technology: Laser Systems, 3D Printing, Digital Imaging, CAD/CAM Software End User: Dental Clinics, Hospitals, Research Institutes, Laboratories |
| Companies Covered | Dentsply Sirona, Envista Holdings, 3M, Henry Schein, Carestream Health, GC Corporation, Straumann Group, Ivoclar Vivadent, Planmeca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Dental Devices Market Strategic Shifts
Selective laser sintering of cobalt-chrome frameworks is displacing conventional casting workflows, while TGA scrutiny of AI diagnostics and shifting procurement authority within dental service organizations are restructuring competitive access.
Intraoral scanning combined with chairside milling is displacing traditional impression-taking and laboratory outsourcing in Australian metropolitan practices. Specialist prosthodontists in Sydney teaching hospital precincts are adopting these systems fastest, capturing premium fees for same-day crown delivery. This compression of the restoration production cycle is locking clinicians into proprietary consumable ecosystems.
The Therapeutic Goods Administration's pending software as a medical device reclassification is forcing diagnostic imaging vendors to prepare substantial technical documentation for AI-powered radiographic analysis tools. Manufacturers must demonstrate clinical validation against Australian patient populations to maintain market access. Small developers lacking dedicated regulatory affairs capacity are exiting rather than absorbing compliance costs.
Buying authority within mid-tier dental service organizations is consolidating equipment procurement decisions to centralized supply committees rather than individual practice owners. These committees now demand outcome guarantees and extended service bundling from device vendors. This shift is most visible in Victorian clinic chains seeking volume discounts on digital impression systems.
Australia Dental Devices Market Segmentation
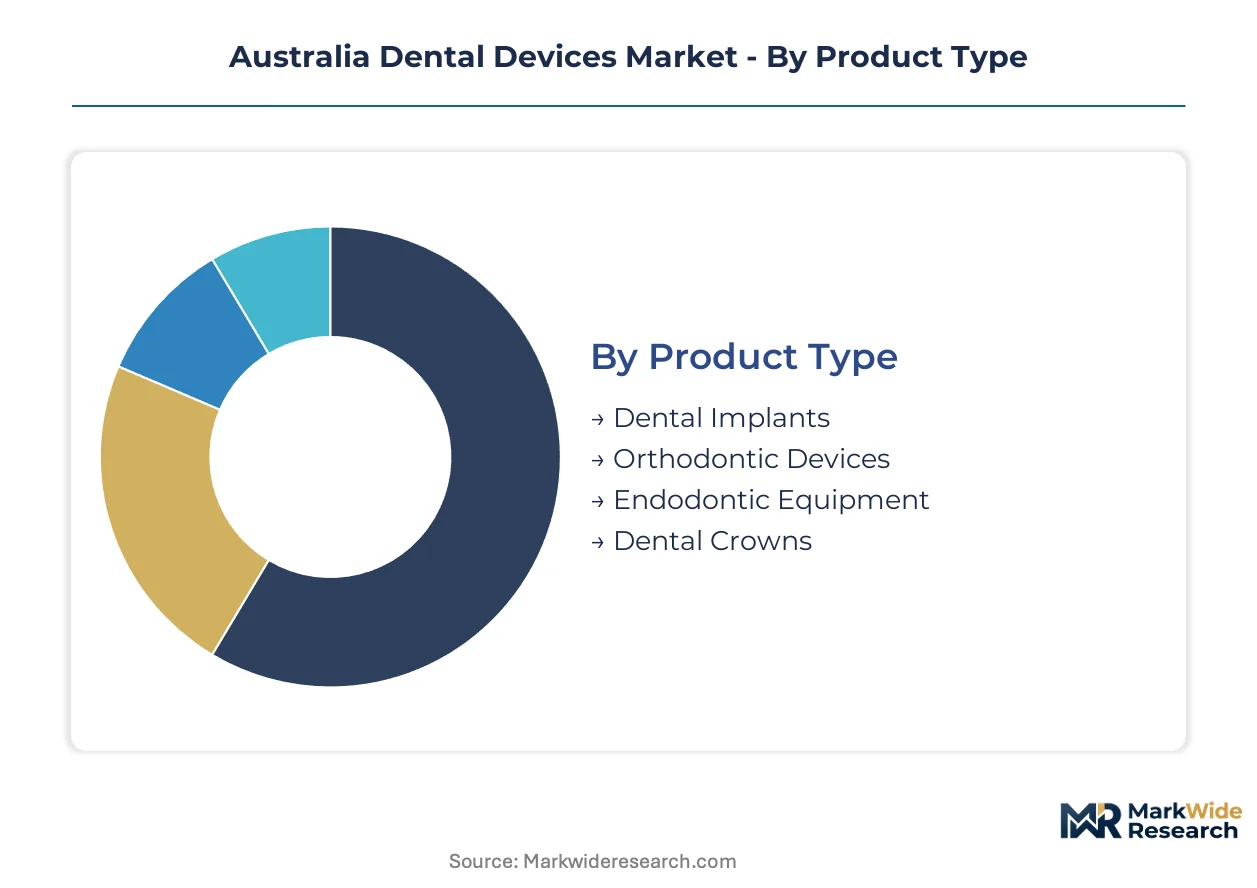
Segmentation in the Australia dental devices market reveals how TGA regulatory pathways, digital workflow adoption, and practitioner purchasing authority reshape competitive access across distinct product and customer categories.
Product Type:
TGA Essential Principles compliance requirements vary sharply across implantable versus non-implantable classifications, filtering manufacturer participation by regulatory capacity.
- Dental Implants:Titanium alloy fixtures and abutments manufactured through precision milling or selective laser sintering. Sydney and Melbourne specialist prosthodontic practices near teaching hospitals concentrate demand for premium implant-abutment-prosthesis ecosystems that lock in recurring consumable revenue.
- Orthodontic Devices:Clear-aligner systems and fixed appliances targeting adolescent and adult aesthetic correction. Victorian and New South Wales mid-tier clinic chains generate volume through retreatment cycles and subscription-based consumable ordering.
- Endodontic Equipment:Nickel-titanium rotary instruments and apex locators for root canal therapy.
- Dental Crowns:Zirconia ceramic and metal-ceramic restorations produced via chairside milling or laboratory outsourcing.
Established volume favors orthodontic devices; emerging adoption favors dental implants.
Application:
Procedure reimbursement patterns and specialist practitioner density determine equipment investment priority across Australian states.
- Restorative Dentistry:Crown, bridge, and implant-supported prosthesis placement. Metropolitan Sydney practices deploy intraoral scanners and chairside mills to capture same-day restoration revenue previously lost to external laboratories.
- Cosmetic Dentistry:Veneer, whitening, and aesthetic contouring procedures. Melbourne's affluent eastern suburbs concentrate demand for premium anterior restorations using high-translucency zirconia and glass-ceramic materials.
- Periodontics:Surgical and non-surgical management of periodontal disease.
- Orthodontics:Malocclusion correction through fixed appliances and removable aligners.
Revenue concentration tilts toward restorative dentistry; technology refresh cycles favor cosmetic applications.
Technology:
Capital intensity and software validation requirements create divergent adoption curves between large metropolitan practices and regional operators.
- Laser Systems:Hard and soft tissue surgical lasers requiring IEC 60601 electrical safety certification. TGA third-party testing mandates disproportionately burden smaller Queensland regional clinics seeking multi-unit purchases.
- 3D Printing:Photopolymer and metal powder bed fusion for surgical guides and provisional restorations. New South Wales teaching hospital precincts pilot biocompatible resin workflows for implant planning.
- Digital Imaging:CBCT and intraoral radiography systems.
- CAD/CAM Software:Design platforms for restorative and orthodontic applications.
Hardware saturation characterizes laser systems; software licensing models favor CAD/CAM expansion.
End User:
Procurement authority consolidation within dental service organizations is restructuring vendor access patterns across customer types.
- Dental Clinics:Private practices and clinic chains representing the dominant equipment purchaser category. Victorian DSO supply committees now centralize digital impression system procurement, demanding outcome guarantees and extended service bundling from vendors.
- Hospitals:Public and private inpatient facilities with specialist oral surgery units. Brisbane and Perth tertiary hospitals concentrate demand for advanced implantology equipment tied to maxillofacial reconstruction services.
- Research Institutes:University dental schools and biomaterials laboratories.
- Laboratories:Commercial dental prosthesis manufacturing facilities.
Transaction volume concentrates in dental clinics; specification influence persists with hospital purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne's container throughput underwrites Victoria's dominance in imported dental equipment distribution, while Sydney's Port Botany anchors New South Wales supply chains for precision-manufactured titanium alloy feedstock.
New South Wales
Sydney's specialist prosthodontic practices near Royal Prince Alfred Hospital and Westmead Hospital concentrate demand for premium implant-abutment-prosthesis ecosystems. TGA's Essential Principles compliance pathways filter market access for ISO 13485-certified manufacturers seeking faster authorization. Chairside CAD/CAM adoption clusters in North Shore and Eastern Suburbs practices capturing same-day restoration revenue.
Victoria
Melbourne's affluent eastern suburbs drive demand for high-translucency zirconia and glass-ceramic anterior restorations. Mid-tier dental service organizations in Greater Melbourne centralize procurement through supply committees demanding outcome guarantees from vendors. The state's teaching hospital precincts pilot biocompatible resin 3D printing workflows for implant surgical guides.
Queensland
Brisbane's tertiary hospitals anchor advanced implantology equipment demand tied to maxillofacial reconstruction services. Specialist prosthodontic coverage remains sparse beyond the capital, creating first-mover potential for mobile CAD/CAM service models targeting regional health networks. IEC 60601 electrical safety testing mandates disproportionately burden smaller regional clinic chains.
Western Australia
Perth's Fiona Stanley Hospital and Royal Perth Hospital concentrate public sector demand for complex oral surgery equipment. Private practice investment in digital imaging lags eastern states due to freight cost premiums on precision hardware. The state's mining-derived affluent demographic sustains cosmetic dentistry demand in western suburban corridors.
South Australia
Adelaide's dental school and biomaterials research programs influence equipment specification in associated teaching practices. Smaller market scale limits dedicated distributor presence, forcing practices to rely on Melbourne-based supply chains with extended lead times. The state's regulatory affairs capacity remains concentrated in TGA-registered consultants serving national authorization pathways.
Australia Dental Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory capacity and digital workflow integration. The vendor base stratifies between multinational conglomerates with captive consumable ecosystems and mid-tier equipment specialists targeting price-sensitive clinic chains. Three archetypes dominate: integrated CAD/CAM workflow providers, implant-abutment ecosystem lock-in players, and orthodontic-imaging equipment specialists. Consolidation proceeds through strategic partnerships with dental service organizations and technology licensing arrangements for AI-powered diagnostic platforms.
Within the integrated workflow tier, Dentsply Sirona and Straumann Group exemplify contrasting ecosystem strategies. Envista Holdings occupies a position among orthodontic and imaging equipment specialists targeting mid-tier expansion. These three anchors demonstrate how regulatory compliance capacity and digital integration depth separate sustainable market presence from marginal participation.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings |
| 3M |
| Henry Schein |
| Carestream Health |
| GC Corporation |
| Straumann Group |
| Ivoclar Vivadent |
| Planmeca |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles for titanium alloy feedstock concentrate pricing power with Melbourne and Sydney distributors serving ISO 13485-certified manufacturers, while freight cost premiums on precision-milled components from Asian smelters compress margins for regional Queensland clinics lacking volume scale.
Pricing Analysis
Volume-discount tiering structures separate premium implant-abutment ecosystems from standard CAD/CAM hardware and economy-grade orthodontic consumables. Price differentiation hinges on TGA Essential Principles certification tier and bundled after-sales service coverage. Cost compression in the standard tier intensifies as Victorian dental service organizations centralize procurement through supply committees demanding outcome guarantees. Mid-tier clinic chains exhibit highest price sensitivity; specialist prosthodontic practices near teaching hospitals show lowest.
Supply Chain Analysis
Strategic-stockpile preferences dominate among Melbourne distributors buffering against titanium alloy supply volatility, while just-in-time ordering prevails in Sydney's chairside milling consumables channel. Australian device manufacturers draw from Chinese, Japanese, and South Korean smelters for cobalt-chrome and zirconia ceramic feedstock. Single-source vulnerability concentrates in precision-milled titanium fixtures. Distribution runs through Port of Melbourne and Port Botany container terminals to state-level dental distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of TGA-registered regulatory affairs capacity combined with specialized prosthodontic technician expertise creates durable competitive moats for incumbents while erecting barriers for offshore suppliers lacking local compliance infrastructure.
For Market Incumbents: Shield market position by deepening captive consumable ecosystems around implant-abutment-prosthesis workflows and securing exclusive supply agreements with Victorian dental service organization procurement committees. Invest in ISO 13485 quality management system upgrades ahead of pending TGA software-as-medical-device reclassifications threatening AI-powered diagnostic platforms. For New Entrants and Emerging Players: Differentiate on mobile CAD/CAM service models targeting regional Queensland health networks where specialist prosthodontic coverage remains sparse beyond Brisbane. Penetrate through outcome-based pricing tied to same-day restoration delivery guarantees rather than capital equipment sales, leveraging lower fixed-cost structures against established distributor networks. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates seeking to divest non-core orthodontic-imaging equipment portfolios amid portfolio rationalization pressures. Long-term viability favors specialists with vertical integration into biocompatible resin 3D printing workflows and hospital system partnerships anchoring maxillofacial reconstruction service lines. Watch TGA consultation outcomes on AI diagnostic classification as inflection signal for compliance cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Pre-Market Authorization Pathway | Essential Principles compliance accelerates market access for ISO 13485-certified manufacturers against uncertified competitors. |
| Dental Service Organization Partnership | Centralized procurement committees in Victorian clinic chains demand outcome guarantees and extended service bundling from vendors. |
| Chairside CAD/CAM Integration | Intraoral scanner and milling unit deployment captures same-day restoration revenue previously lost to external laboratories. |
| Biocompatible Resin 3D Printing Scale-Up | New South Wales teaching hospital precincts pilot surgical guide workflows requiring validated photopolymer supply chains. |
| Software-as-Medical-Device Reimbursement Strategy | Pending TGA reclassification forces AI-powered radiographic analysis vendors to demonstrate clinical validation against Australian patient populations. |
Study Parameters
Desk research of TGA medical device registration databases, ISO 13485 certification records, and hospital procurement contract disclosures preceded structured interviews with prosthodontic specialists, biomedical engineers, dental service organization supply committee chairs, and GPO contracts managers. Secondary validation drew from customs import manifests for titanium alloy feedstock, SEC filings of listed device manufacturers, and Australian Dental Association continuing professional development records. Bottom-up practice-level equipment adoption estimates triangulated against top-down state-level market value assessments.
Variance decomposition across product type, application, technology, and end-user segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle analysis, consumable recurring revenue modeling, and regulatory authorization timeline distributions. Forecast inputs incorporated intraoral scanner penetration rates in metropolitan versus regional practices and clear-aligner retreatment cycle frequencies in adult orthodontic segments.
Decision-makers should treat outputs as directional under assumptions of stable TGA regulatory pathways and continued titanium alloy supply availability; material deviation would warrant model refresh. Revision becomes warranted when TGA software-as-medical-device consultation outcomes or titanium feedstock tariff structures cross thresholds altering manufacturer compliance cost profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
CBCT Dental Imaging Market
Dental Devices
China Dental Devices Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Fittings Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Restoration Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Malocclusion Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental CAD Market