
 Global Pharmacy Information System Market | 2026-2036
Global Pharmacy Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacy Information System Market Foresight
Pharmacy informatics talent scarcity is bifurcating the competitive landscape into vendors with captive clinical workflow expertise versus those dependent on third-party integration. McKesson Corporation leverages its wholesale distribution footprint to anchor hospital pharmacy system deployments across integrated delivery networks. Cerner Corporation sustains competitive positioning through deep electronic health record interoperability that reduces standalone pharmacy system switching. Epic Systems Corporation dominates academic medical center pharmacy modules by controlling the inpatient medication administration record as a core workflow.
A pharmacy information system constitutes software infrastructure that manages medication ordering, dispensing, inventory control, and clinical decision support across healthcare settings, typically integrating barcode medication administration verification and real-time drug interaction screening to prevent adverse events. Cloud-based deployments are capturing share fastest among retail pharmacy chains seeking centralized multi-location inventory visibility, while on-premise installations retain margin pools in hospital pharmacies governed by stringent institutional data residency policies. Artificial intelligence segments within pharmacy technology are concentrating investment around predictive shortage forecasting and automated prior authorization, whereas blockchain applications remain nascent outside pilot traceability programs.
FDA DSCSA requirements and HIPAA privacy frameworks collectively shape vendor product roadmaps by mandating interoperable track-and-trace capabilities alongside encrypted patient medication histories. The EMA's Falsified Medicines Directive imposes equivalent serialization standards across European supply chains, compelling multinational pharmacy system vendors to maintain dual compliance architectures. Stakeholders must monitor whether emerging EU AI Act risk classifications will recategorize clinical decision support algorithms as high-risk systems subject to conformity assessment.
Market Dynamics
Health system consolidation is compressing vendor selection cycles as integrated delivery networks demand enterprise-wide pharmacy IT standardization across dozens of hospital sites simultaneously.
Growth Catalysts
- FDA DSCSA mandates:Serialization requirements for wholesale distributors and dispensers are forcing infrastructure upgrades across the pharmaceutical supply chain.
- Cloud migration:Retail pharmacy chains are adopting centralized multi-location inventory visibility platforms to reduce stockouts and surplus.
- United States:Hospital network mergers are consolidating purchasing power and accelerating enterprise pharmacy system rollouts.
Market Restraints
- Technical debt:On-premise legacy installations in hospital pharmacies create migration friction against cloud-native architectures.
- Input concentration:Specialized pharmacy informatics talent scarcity limits vendor expansion and implementation velocity.
- Regulatory fragmentation:Divergent FDA and EMA serialization standards force vendors to maintain dual compliance architectures.
Strategic Opportunities
- India:Underpenetrated hospital pharmacy automation presents white space for integrated dispensing platform vendors.
- AI convergence:Predictive shortage forecasting algorithms combined with automated prior authorization workflows create new product categories.
- EU AI Act:Emerging risk classifications for clinical decision support systems may recategorize algorithms as high-risk, creating conformity assessment service demand.
Industry Challenges
- Workflow integration:Pharmacy information systems must synchronize with electronic health record medication administration records, creating complex interoperability requirements.
- Certification timelines:FDA validation processes for clinical decision support modules extend product launch schedules and inflate development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacy Information System Market |
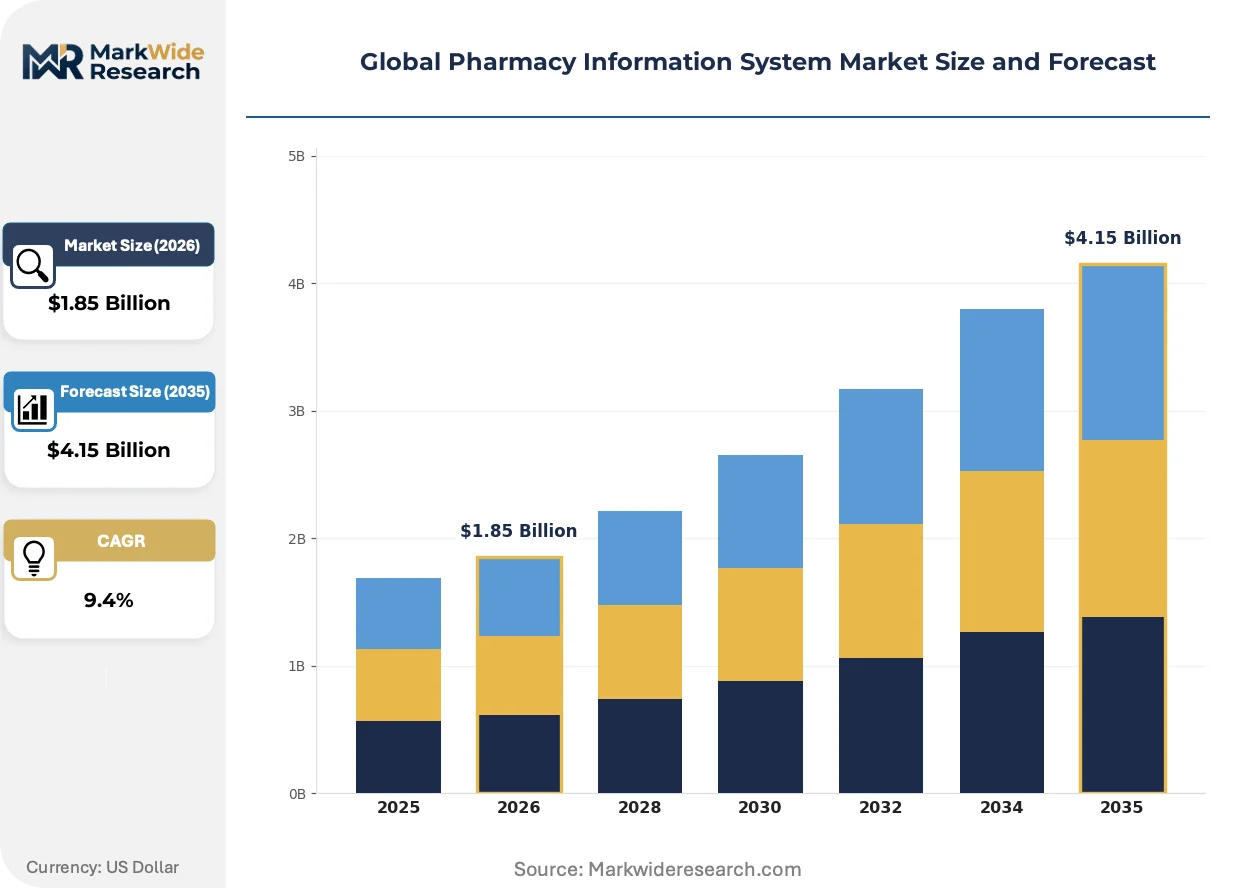
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile Apps End User: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Drug Manufacturers Technology: Artificial Intelligence, Blockchain, Internet of Things, Data Analytics Deployment Model: Public Cloud, Private Cloud, Community Cloud, Others |
| Companies Covered | McKesson Corporation, Cerner Corporation, Epic Systems Corporation, Allscripts Healthcare Solutions, Omnicell Inc., Oracle, Optum, QS/1 Data Systems, PioneerRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacy Information System Market Shifts & Advancements
Artificial intelligence is penetrating pharmacy operations at three distinct layers: predictive supply chain analytics, clinical decision automation, and patient engagement personalization.
Real-time inventory optimization algorithms are supplanting periodic manual stock counts in hospital pharmacy operations. Large health systems in the United States are deploying these platforms across consolidated networks within eighteen-month implementation windows. This technology is compressing working capital requirements while reducing medication waste from expired products.
EMA's Falsified Medicines Directive imposes equivalent serialization standards to FDA DSCSA across European supply chains. Multinational pharmacy system vendors must engineer interoperable track-and-trace capabilities that satisfy both regulatory frameworks simultaneously. European wholesale distributors are prioritizing vendors with pre-certified dual-compliance architectures to avoid operational disruption.
Subscription-based software licensing is displacing perpetual license purchases among mid-sized retail pharmacy chains. These buyers prefer operational expenditure models that bundle implementation, training, and continuous updates. Germany and France show the fastest migration toward this procurement structure as independent pharmacy cooperatives consolidate technology purchasing.
Global Pharmacy Information System Market Segmentation
Pharmacy information system segmentation reveals where infrastructure investments concentrate and which technology configurations face displacement risk from adjacent healthcare IT platforms. Deployment architecture and end-user workflow requirements create distinct competitive arenas with diverging margin structures and vendor specialization patterns.
Product Type:
Substitution pressure weighs heaviest on on-premise installations as health systems accelerate cloud migration timelines and retail chains pursue centralized operational visibility.
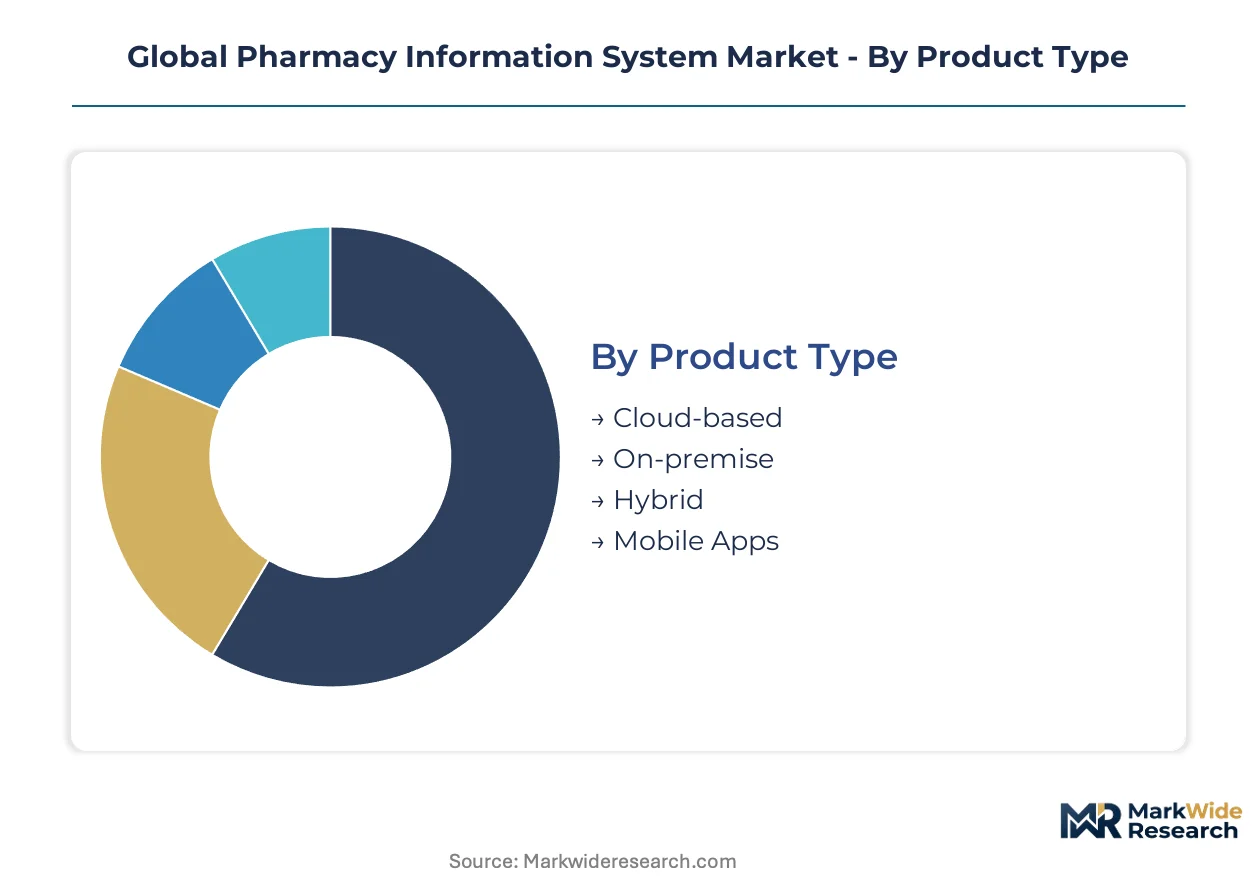
- Cloud-based:Multi-tenant SaaS architectures enable real-time inventory synchronization across hundreds of pharmacy locations from a single control plane. United States hospital networks consolidating under single enterprise agreements are driving demand for cloud-native dispensing platforms that eliminate data center maintenance overhead.
- On-premise:Legacy server installations governed by institutional data residency policies retain footholds in academic medical centers and government hospital systems. Stringent HIPAA encryption requirements and specialized clinical decision support module validation cycles extend replacement timelines for these deployments.
- Hybrid:Split architectures partition sensitive patient medication histories on local servers while pushing inventory analytics to cloud infrastructure. German hospital pharmacy cooperatives favor this model to satisfy both BSI cybersecurity standards and operational efficiency targets.
- Mobile Apps:Point-of-care medication administration verification tools running on hardened tablets and smartphones. These lightweight clients gain traction among home infusion pharmacy services requiring bedside barcode scanning capabilities.
On-premise retains volume leadership; cloud-based holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise health system deployments from independent retail pharmacy procurement patterns, with drug manufacturers representing a distinct capital expenditure profile driven by regulatory compliance mandates.
- Retail Pharmacies:Chain and independent dispensers prioritize inventory turnover optimization and automated refill management. CVS Health and Walgreens Boots Alliance procurement specifications are setting interoperability standards for multi-location visibility platforms across the United States.
- Hospital Pharmacies:Inpatient medication administration record integration dominates system requirements. Epic Systems and Cerner Corporation EHR anchoring creates high switching costs for standalone pharmacy module vendors seeking entry into academic medical center environments.
- Online Pharmacies:Direct-to-consumer dispensers require cold chain tracking integration and automated prior authorization workflows. Amazon Pharmacy infrastructure investments are establishing benchmark specifications for last-mile medication delivery traceability.
- Drug Manufacturers:Serialization and track-and-trace compliance investments anchor demand for production-to-dispenser visibility platforms. FDA DSCSA and EMA Falsified Medicines Directive deadlines are forcing wholesale distributor and manufacturer system upgrades simultaneously.
Hospital pharmacies command the highest per-site contract values; online pharmacies are climbing fastest in new system installations.
Technology:
Application maturity varies sharply across this dimension, with data analytics achieving production deployment at scale while blockchain pilots remain confined to traceability proof-of-concepts.
- Artificial Intelligence:Predictive shortage forecasting algorithms analyze procurement patterns across hospital networks to anticipate supply disruptions. These systems are reducing working capital requirements for large United States health systems managing consolidated formulary purchasing.
- Blockchain:Distributed ledger architectures for pharmaceutical provenance tracking remain in pilot phase outside European Falsified Medicines Directive compliance programs. Scalability constraints and interoperability standardization gaps limit production deployment timelines.
- Internet of Things:Sensor networks for temperature-controlled medication storage and automated dispensing cabinet inventory monitoring. These deployments concentrate in hospital pharmacy clean rooms and specialty pharmacy distribution centers.
- Data Analytics:Descriptive and predictive platforms for medication adherence scoring, formulary optimization, and adverse event pattern detection. Mature vendor offerings from established healthcare IT players dominate this segment with proven ROI measurement frameworks.
Data analytics commands the largest installed base; artificial intelligence is gaining share fastest among new procurement decisions.
Deployment Model:
Customer type and security classification requirements segment this category, with public cloud facing the strongest competitive pressure from private and community alternatives in regulated healthcare environments.
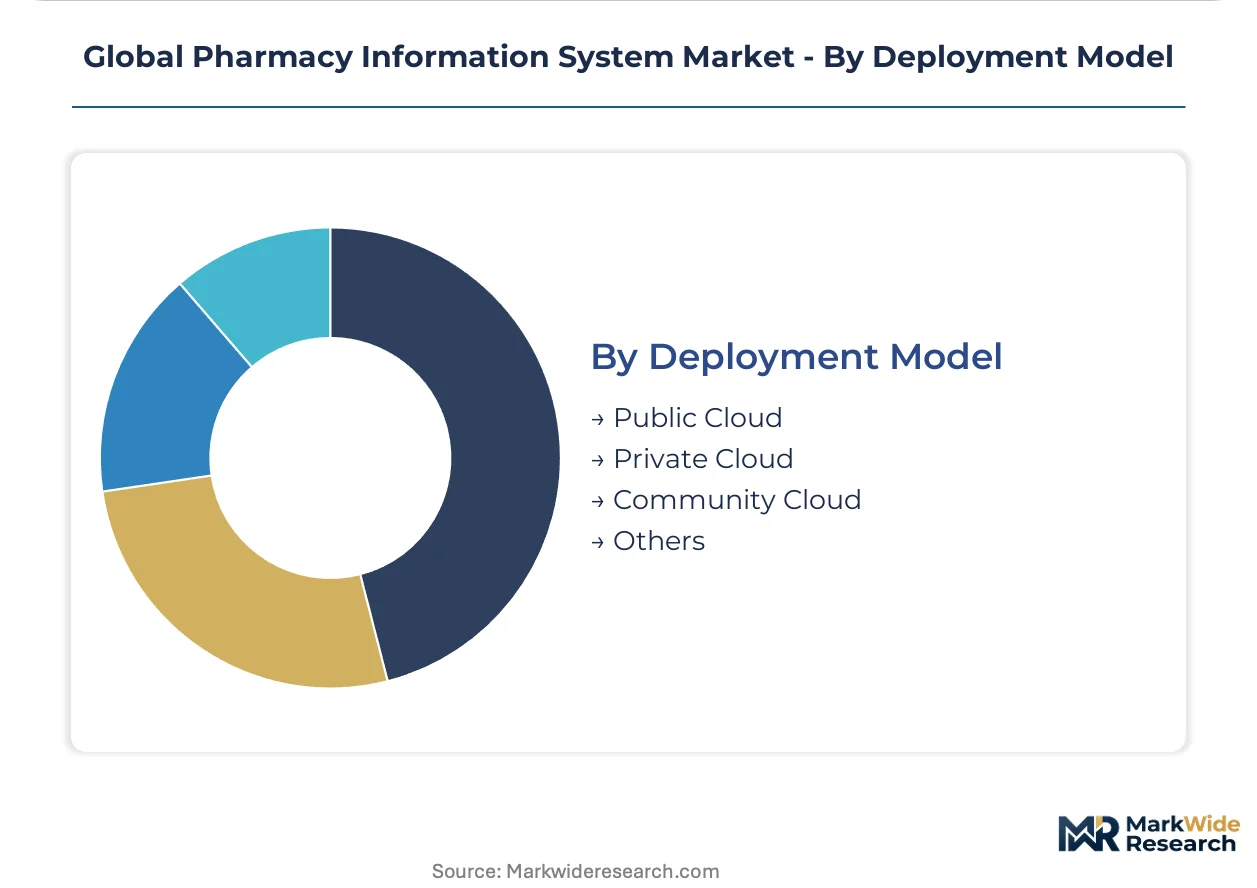
- Public Cloud:Shared infrastructure deployments from Amazon Web Services, Microsoft Azure, and Google Cloud Platform. Retail pharmacy chains with standardized security requirements leverage these platforms for rapid geographic expansion without capital-intensive data center construction.
- Private Cloud:Single-tenant dedicated environments satisfying HIPAA business associate agreement stipulations for covered entities. United States hospital systems with institutional risk management policies mandate these configurations for all patient-facing medication systems.
- Community Cloud:Collaborative infrastructure shared among pharmacy cooperatives and regional health information exchanges. French and German independent pharmacy associations are consolidating procurement through these shared service models to achieve enterprise-grade capabilities.
- Others:Edge computing deployments for remote pharmacy locations and disaster recovery configurations with active-active redundancy. These specialized architectures serve military health facilities and rural critical access hospitals with intermittent connectivity.
Private cloud retains the dominant contract value; community cloud is expanding most quickly among European cooperative purchasing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor United States infrastructure spending, while EMA track-and-trace requirements drive parallel European investments. India and China present contrasting automation trajectories shaped by hospital network consolidation and regulatory modernization timelines.
United States
Hospital network mergers are compressing vendor selection cycles as integrated delivery networks demand enterprise-wide standardization across dozens of sites simultaneously. FDA DSCSA enforcement deadlines are forcing wholesale distributors and dispensers to upgrade traceability infrastructure before compliance windows close. The Greater Boston and San Francisco Bay Area clusters concentrate health system IT procurement decision-making for academic medical center deployments.
Germany
Independent pharmacy cooperatives are consolidating technology purchasing through shared service models to achieve enterprise-grade capabilities previously accessible only to chains. BSI cybersecurity standards and EMA Falsified Medicines Directive requirements shape vendor certification priorities. The Rhine-Ruhr metropolitan region anchors hospital pharmacy automation deployment velocity, with Bavarian academic medical centers driving EHR-integrated module specifications.
India
Underpenetrated hospital pharmacy automation presents white space for integrated dispensing platform vendors as private hospital chains expand bed capacity. CDSCO track-and-trace pilot programs are establishing serialization infrastructure precedents for domestic manufacturers. Mumbai and Bangalore hospital networks are piloting barcode medication administration systems as quality differentiation investments.
China
NMPA pharmaceutical traceability regulations are accelerating serialization system adoption among domestic drug manufacturers and hospital dispensers. Public hospital pharmacy automation lags private facility investment, creating segmented procurement patterns. Shanghai and Beijing tertiary hospitals are deploying automated dispensing cabinets as part of smart hospital construction mandates.
United Kingdom
NHS England pharmacy integration programs are driving EHR-linked medication management system tenders across acute hospital trusts. MHRA serialization requirements align with EMA standards, simplifying vendor compliance architectures for multinational suppliers. The Oxford-Cambridge-London corridor concentrates digital health procurement expertise and pilot program evaluation capacity.
Global Pharmacy Information System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across deployment scales. Consolidated health system purchasing in the United States favors vendors with captive clinical workflow expertise, while fragmented retail pharmacy markets sustain specialized point-solution providers. Two strategic archetypes dominate: wholesale distribution-anchored platforms leveraging supply chain integration, and EHR-native modules controlling inpatient medication administration records. Competitive moves concentrate on strategic partnerships with health system consolidators and geographic expansion through cooperative purchasing networks.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation exemplify archetypes that reduce standalone pharmacy system switching through deep interoperability. McKesson Corporation occupies a position representing wholesale distribution-anchored deployment models across integrated delivery networks. These three companies illustrate how vertical integration depth and clinical workflow control create divergent competitive moats.
| Leading Market Players |
|---|
| McKesson Corporation |
| Cerner Corporation |
| Epic Systems Corporation |
| Allscripts Healthcare Solutions |
| Omnicell Inc. |
| Oracle |
| Optum |
| QS/1 Data Systems |
| PioneerRx |
| Others |
Supply & Pricing Matrix
Long-term enterprise agreements with integrated delivery networks lock in multi-year SaaS subscriptions that guarantee vendor revenue visibility while capping customer pricing exposure. These arrangements concentrate purchasing power among United States hospital consolidators and tie pricing trajectories to implementation velocity across cloud-native platform rollouts.
Pricing Analysis
United States contract values run 40-60% above German hospital system equivalents due to EHR integration complexity and FDA validation requirements. Three-tier pricing structure across premium, standard, and economy levels segments by deployment scale, with academic medical centers paying premium tiers for customized clinical decision support modules while retail chains negotiate volume discounts. Pricing pressure stems from subscription fatigue among mid-sized retail pharmacy cooperatives consolidating procurement. Independent retail pharmacies exhibit highest price sensitivity; integrated delivery networks with captive IT budgets show least.
Supply Chain Analysis
Inventory optimization algorithms have compressed pharmaceutical distribution lead times from weeks to days across United States hospital networks. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from hyperscaler data centers in Virginia, Frankfurt, and Mumbai. Specialized pharmacy informatics talent scarcity creates single-source vulnerability for implementation services. Distribution runs through wholesale distributor-anchored platforms and EHR-native module channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of professionals bridging clinical pharmacy workflows with health informatics engineering bifurcates competitive advantage between vendors with captive expertise and integration-dependent challengers.
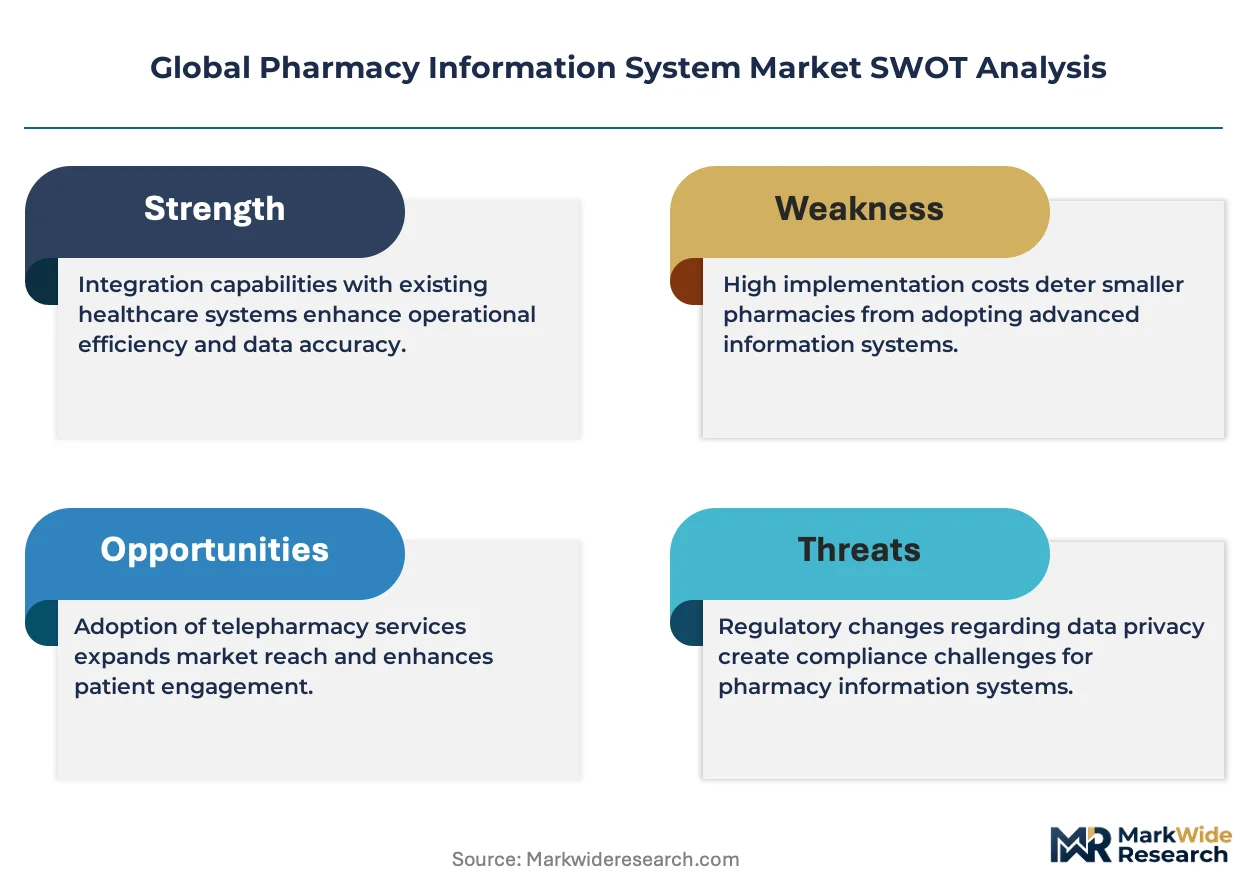
For Market Incumbents: Shield installed base relationships by embedding clinical decision support modules deeper into EHR medication administration records, raising switching costs for standalone pharmacy system competitors. Accelerate backward integration into specialized pharmacy informatics training programs to reduce talent dependency on third-party implementation partners. For New Entrants and Emerging Players: FDA 510(k) fast-track certification for barcode medication administration verification tools opens entry pathways into hospital pharmacy automation. Target India's underpenetrated private hospital chain segment where Epic and Cerner anchoring remains incomplete. Pursue cooperative purchasing network partnerships in Germany and France to bypass direct enterprise sales capacity gaps. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native pharmacy platform vendors with demonstrated FDA DSCSA compliance architectures and recurring revenue bases above 70%. Monitor EU AI Act risk classification timelines as the critical inflection signal for clinical decision support algorithm conformity assessment service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep EHR interoperability with Epic and Cerner medication administration records reduces customer churn. |
| Acquisition of Specialist Firm | Captive pharmacy informatics talent pools accelerate implementation velocity across health system consolidators. |
| Regulatory Approval Pathway | FDA DSCSA pre-certification enables wholesale distributor procurement specification compliance. |
| Strategic Partnership | Cooperative purchasing network alliances in France and Germany unlock mid-market retail pharmacy access. |
| Geographic Expansion | India private hospital chain deployments establish foothold before EHR-native vendor consolidation completes. |
Research Methodology
A spread of perspectives from hospital pharmacy directors, health system CIOs, EHR integration specialists, and wholesale distributor operations executives converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA DSCSA guidance documents, EMA Falsified Medicines Directive implementation reports, hospital procurement databases, and GPO contract filings. Bottom-up deployment counts across cloud, on-premise, and hybrid architectures were triangulated against top-down vendor revenue segmentation.
Segmentation dimensions modeled include deployment architecture, end-user workflow type, technology application layer, and geographic regulatory cluster across the analysis window. CAGRs were derived from fitted growth curves anchored to disclosed health system consolidation timelines and FDA enforcement deadline proximity. Forecast inputs incorporated pharmacy informatics talent pipeline constraints and cloud migration friction coefficients from legacy on-premise installations.
Decision-makers should treat outputs as directional under assumptions of steady FDA DSCSA enforcement and stable health system merger velocity; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Case Coder Market