
 Global Public Sector Consulting and Advisory Services Market | 2026-2036
Global Public Sector Consulting and Advisory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Sector Consulting and Advisory Services Market Insights
GDPR enforcement is hardening compliance requirements for public sector data systems across European agencies. Accenture leverages its federal digital infrastructure practice to anchor large-scale government modernization contracts in the United States. Deloitte sustains competitive positioning through deep operational consulting benches serving defense procurement offices.
Public sector consulting and advisory services encompass strategy formulation, operational redesign, financial restructuring, and technology implementation delivered to governmental and quasi-governmental institutions under formal procurement frameworks. These engagements typically operate through structured request-for-proposal processes with defined performance metrics, security clearances, and audit trails to ensure accountability of public expenditure. Technology consulting leads structural growth as agencies migrate legacy systems to cloud-native architectures and cybersecurity-hardened platforms. Strategy consulting occupies mature margin pools in defense and international organization segments where multi-year frameworks dominate procurement calendars.
The EU AI Act and CSRD disclosure rules are expanding the scope of mandatory advisory engagements for public agencies managing algorithmic decision systems and sustainability reporting. India's BIS standards and PLI scheme incentives are creating dedicated consulting demand around domestic capability building and vendor qualification. Stakeholders must monitor how procurement rule changes in the United States and European Union reshape eligibility criteria for performance-based contracting vehicles.
Market Dynamics
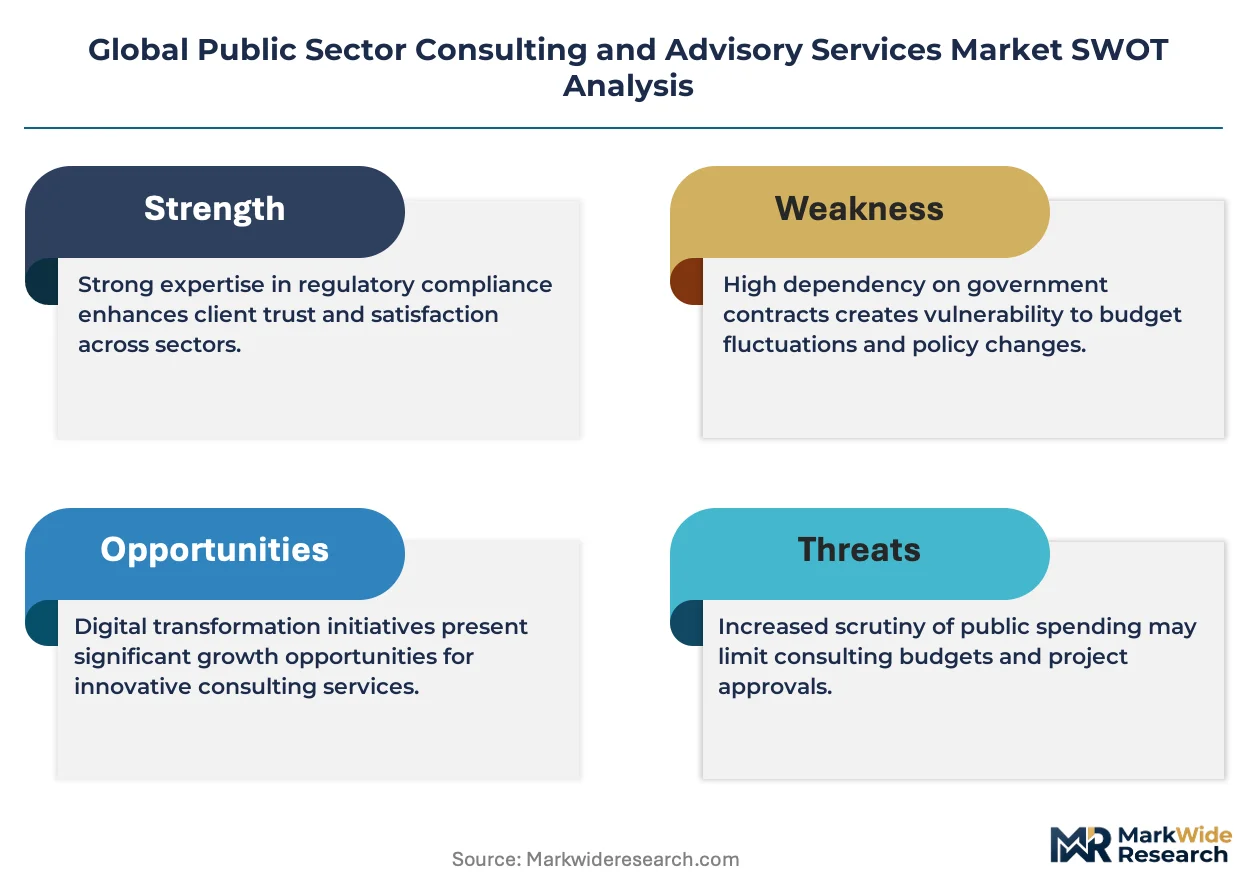
Technology consulting engagements are displacing traditional strategy work as public agencies accelerate cloud migration and cybersecurity hardening under tightened fiscal accountability frameworks.
Growth Catalysts
- EU AI Act compliance mandates:Public agencies across Germany, France, and the Netherlands must conduct algorithmic impact assessments, creating dedicated advisory demand for risk governance and documentation frameworks.
- India's PLI scheme incentives:Domestic manufacturing subsidies require vendor qualification and capability-building consulting for local suppliers seeking public procurement eligibility.
- Cloud-native architecture migration:Southeast Asian administrative reform programs in Indonesia, Thailand, and Vietnam are driving sustained technology consulting volume for legacy system modernization.
Market Restraints
- Security clearance bottlenecks:Defense and intelligence consulting contracts in the United States face 12-18 month personnel vetting delays that constrain consultant deployment velocity.
- Procurement cycle compression:Brazilian federal agencies under fiscal consolidation mandates have shortened RFP evaluation windows from 180 to 90 days, squeezing proposal development resources.
- Technical debt accumulation:European public health agencies running 1990s-era COBOL systems require parallel consulting tracks for maintenance and replacement, diverting budget from transformation initiatives.
Strategic Opportunities
- CSRD disclosure implementation:The EU's Corporate Sustainability Reporting Directive creates mandatory advisory scope for public agencies managing sustainability-linked procurement and carbon accounting systems.
- Urban digital twin deployments:Singapore's Smart Nation initiative and Dubai's AI Roadmap are opening systems integration consulting for city-scale simulation and predictive infrastructure management.
- Performance-based contracting vehicles:United States federal agencies are piloting outcome-linked fee structures that reward measurable efficiency gains rather than time-and-materials billing.
Industry Challenges
- Specialized talent scarcity:Cybersecurity-cleared consultants with federal experience command 40-60% compensation premiums, constraining project staffing for mid-tier advisory firms.
- Interoperability complexity:India's national e-governance mandates require integration across 28 state-level legacy systems with incompatible data standards and authentication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Sector Consulting and Advisory Services Market |
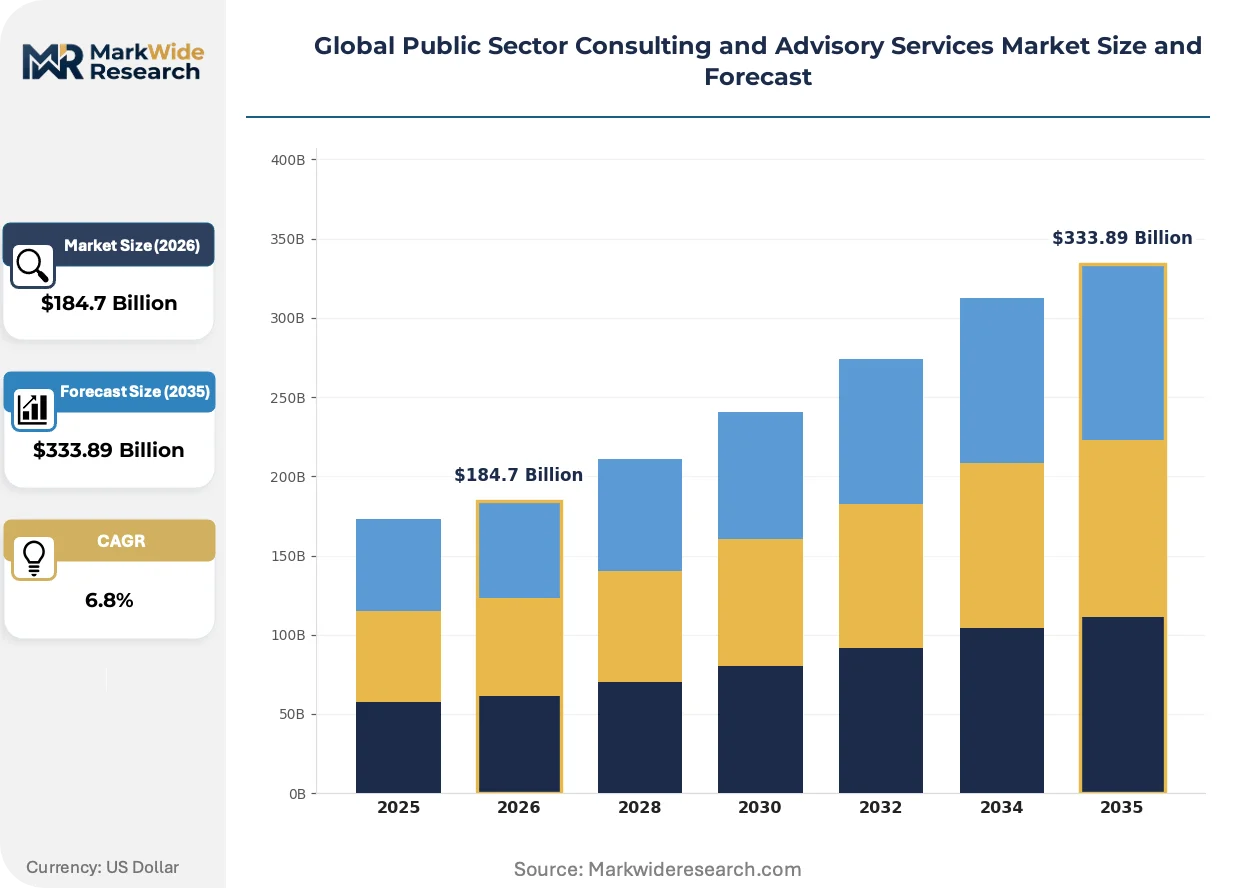
| Market Size in 2026 | $184.7 Billion |
| Market Size in 2035 | $333.89 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operational Consulting, Financial Advisory, Technology Consulting Client Type: Government Agencies, Non-Profit Organizations, International Organizations, Defense Sector Engagement Model: Fixed Fee, Retainer, Time and Materials, Performance-Based Project Size: Small Scale, Medium Scale, Large Scale, Multi-Year |
| Companies Covered | McKinsey & Company, PwC, Accenture, KPMG, EY, Deloitte, Boston Consulting Group, Capgemini, Booz Allen Hamilton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Sector Consulting and Advisory Services Market Trends and Innovations
Advisory delivery models are fragmenting as public buyers demand embedded technical specialists over traditional partner-led project structures, compressing engagement economics and reshaping firm talent strategies.
Generative AI tooling is modularizing how public sector consultants prototype policy scenarios and automate compliance documentation workflows. United States federal agencies are piloting large language models for regulatory analysis, compressing research phases from weeks to days while raising new governance questions about algorithmic transparency in advisory outputs.
The EU Green Deal's taxonomy requirements are forcing sustainability disclosure into every major public procurement framework. French and German agencies now mandate carbon footprint calculations in consulting RFPs, pushing advisory firms to build in-house climate accounting capabilities or partner with specialized data providers.
Fixed-price outcome contracts are displacing time-based billing in United Kingdom central government procurement. The Crown Commercial Service's consultancy frameworks now tie 30-50% of fees to measurable operational improvements, transferring performance risk to vendors and demanding new project governance structures from advisory firms.
Global Public Sector Consulting and Advisory Services Market Segmentation
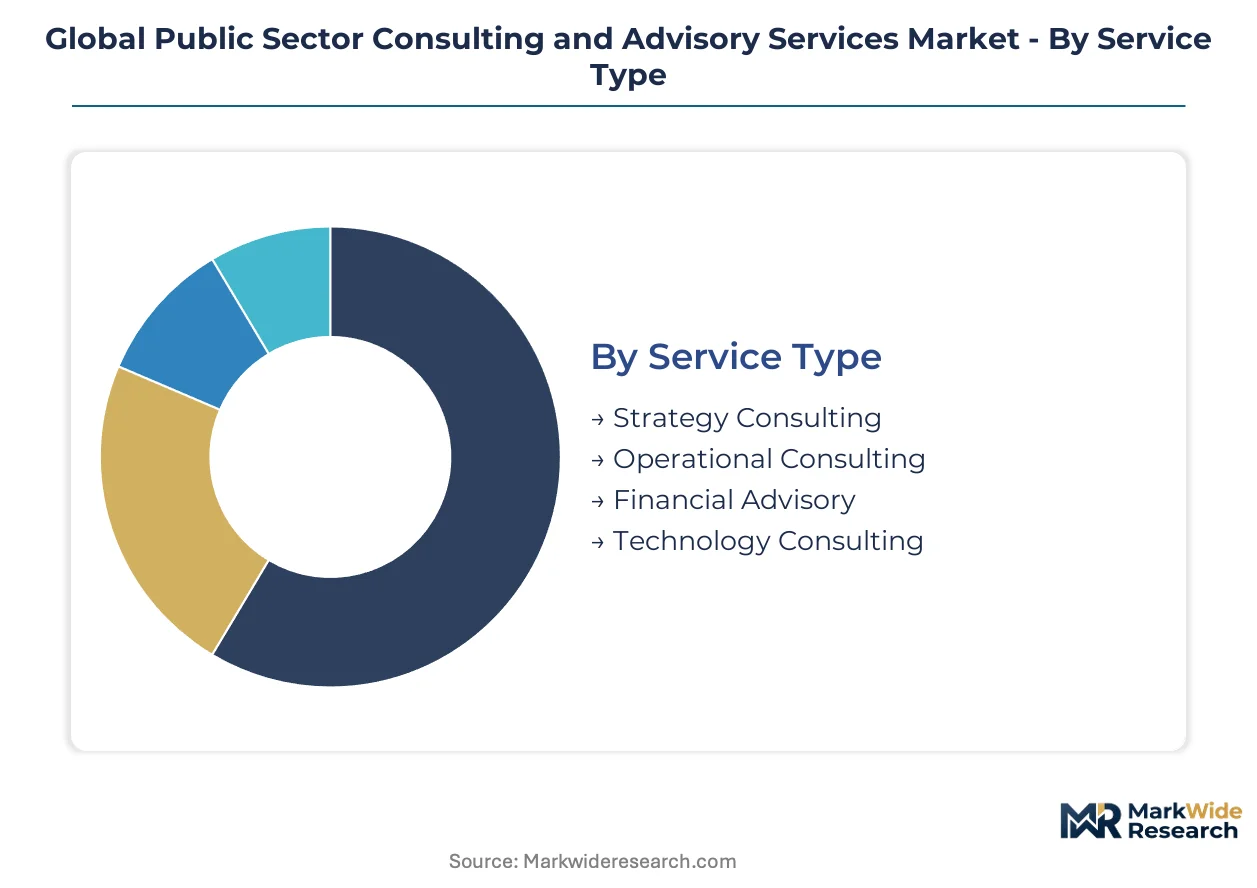
Public sector procurement frameworks impose distinct contracting logics that reshape how advisory services bundle, price, and deliver value across different institutional contexts. Understanding these segment boundaries clarifies where margin pools concentrate and where competitive positioning fractures.
Service Type:
Customization intensity varies sharply across this category, from highly tailored strategy engagements to increasingly productized technology implementation.
- Strategy Consulting:Senior partner-led engagements addressing policy formulation, organizational restructuring, and long-term capital planning for cabinet-level agencies. Demand concentrates in defense ministries and international organizations where multi-year frameworks dominate procurement calendars and security clearances create vendor stickiness.
- Technology Consulting:Cloud migration, cybersecurity architecture, and legacy system modernization delivered through structured implementation methodologies. Southeast Asian administrative reform programs in Indonesia, Thailand, and Vietnam are driving sustained volume as agencies accelerate digital transformation under national e-governance mandates.
- Operational Consulting:Process redesign, supply chain optimization, and performance management for service delivery agencies. Procurement offices favor standardized playbooks that compress scoping timelines.
- Financial Advisory:Debt restructuring, privatization preparation, and public-private partnership structuring for treasury departments. EU Green Deal taxonomy compliance is expanding carbon accounting and sustainability-linked financing advisory scope.
Leading the category by volume: Technology Consulting. Expanding most quickly: Technology Consulting.
Client Type:
Contracting sophistication and payment security vary dramatically across institutional categories, from mature federal procurement systems to fragmented non-profit funding streams.
- Government Agencies:Central ministries, regulatory bodies, and local authorities operating under formal public procurement law with defined audit trails and performance metrics. India's BIS standards and PLI scheme incentives are creating dedicated consulting demand around domestic capability building and vendor qualification.
- Defense Sector:Military procurement offices and intelligence agencies requiring personnel security clearances and facility access certifications. United States federal contracts face 12-18 month vetting delays that constrain consultant deployment velocity and favor incumbent vendors.
- International Organizations:Multilateral development banks, UN agencies, and regional development funds with harmonized procurement rules and multi-year programming cycles. Framework agreements reduce transaction costs for repeat advisory purchases.
- Non-Profit Organizations:Publicly funded NGOs and social service providers with restricted overhead allowances and donor-driven reporting requirements. Smaller scale engagements favor fixed-fee structures over time-based billing.
Dominating procurement value: Government Agencies. Steepest expansion trajectory: Defense Sector.
Engagement Model:
Risk allocation between client and vendor shifts markedly across pricing structures, reshaping project governance and talent deployment economics.
- Performance-Based:Outcome-linked fee structures tying 30-50% of compensation to measurable efficiency gains or cost reductions. United Kingdom Crown Commercial Service frameworks are piloting these vehicles, transferring operational risk to advisory firms and demanding new delivery metrics.
- Fixed Fee:Lump-sum contracts for well-scoped deliverables with defined milestones and acceptance criteria. Brazilian federal agencies under fiscal consolidation mandates have compressed RFP evaluation windows, squeezing proposal development resources for complex fixed-price bids.
- Retainer:Standing advisory relationships providing on-call expertise for emerging policy or operational challenges. International organizations favor retainers for rapid response to shifting funding priorities.
- Time and Materials:Hourly or daily billing with capped ceilings and milestone-based authorization. Traditional model losing share to outcome-based alternatives in OECD public procurement systems.
Highest revenue concentration: Fixed Fee. Gaining share fastest: Performance-Based.
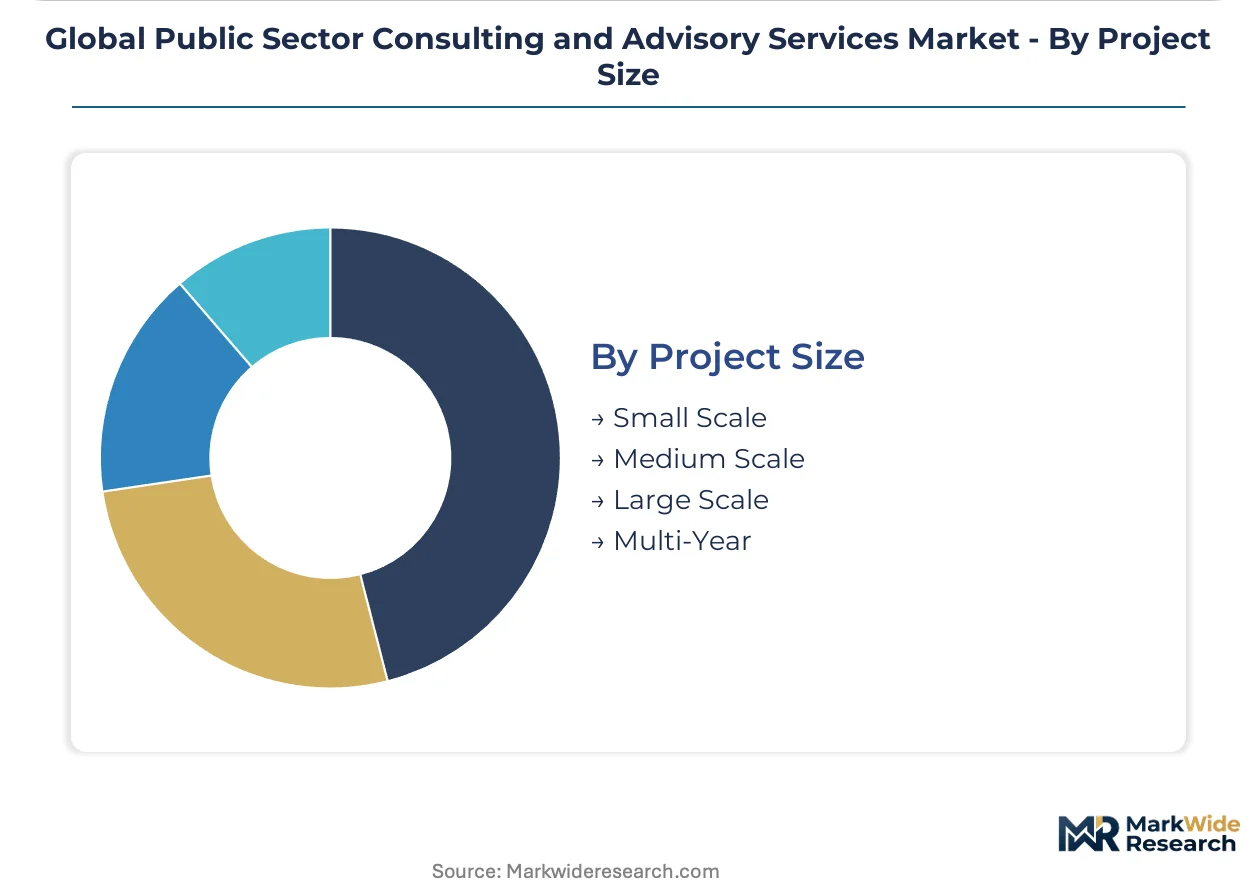
Project Size:
Resource mobilization requirements and partner attention intensity scale non-linearly with engagement magnitude, creating distinct competitive arenas.
- Multi-Year:Framework contracts spanning three to seven years with annual task order competitions and relationship-based renewal logic. United States federal digital infrastructure modernization and EU AI Act compliance programs favor these structures for algorithmic governance advisory.
- Large Scale:Single engagements exceeding substantial contract thresholds requiring joint venture structures and subcontractor management. Urban digital twin deployments in Singapore and Dubai demand systems integration capabilities across simulation, predictive analytics, and infrastructure management.
- Medium Scale:Discrete projects with defined deliverables and six-to-eighteen month timelines. Standard competitive tendering dominates procurement.
- Small Scale:Rapid-response assignments and technical assistance under simplified procurement thresholds. State and local agencies use these for specialized expertise without lengthy RFP processes.
Capturing majority of advisory revenue: Multi-Year. Climbing the fastest: Large Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and national digital transformation corridors concentrate public sector consulting demand across five major economies. Government modernization programs and regulatory compliance mandates drive advisory service procurement in distinct regional clusters.
United States
Federal digital infrastructure contracts and defense procurement sustain the largest advisory market. Security clearance requirements under NIST frameworks create vendor stickiness for incumbent consultants. Washington DC and Northern Virginia host dense concentrations of contractors serving federal agencies.
Germany
EU AI Act compliance mandates and CSRD disclosure rules generate sustained advisory demand for algorithmic governance. Federal agencies in Berlin and Munich procure risk assessment and documentation framework services. The Rhine-Ruhr corridor concentrates sustainability-linked consulting for industrial transition programs.
India
BIS standards implementation and PLI scheme vendor qualification drive domestic capability-building advisory. National e-governance mandates require integration across 28 state-level legacy systems. Delhi-NCR and Bangalore clusters specialize in public digital transformation consulting.
Singapore
Smart Nation initiative urban digital twin deployments open systems integration consulting for city-scale simulation. Government Technology Agency procurement favors outcome-based contracting for predictive infrastructure management. The city-state anchors Southeast Asian administrative reform advisory.
Brazil
Fiscal consolidation mandates have compressed federal RFP evaluation windows from 180 to 90 days. National e-governance expansion drives digital transformation advisory procurement. São Paulo and Brasília concentrate consulting engagements for federal administrative reform.
Global Public Sector Consulting and Advisory Services Market Competitive Landscape
United States-based firms anchor the premium-tier advisory segment; European specialists hold compliance-intensive mandates. The market structures around three tiers: global strategy houses, technology-integrated consultancies, and defense-cleared boutiques. Strategic archetypes include federal infrastructure anchors, EU regulatory compliance specialists, and emerging market capability builders. Competitive moves center on performance-based contracting capabilities and specialized talent acquisition.
Within the federal infrastructure tier, Accenture and Booz Allen Hamilton occupy positions as security-cleared delivery anchors. Among global strategy houses, McKinsey & Company and Boston Consulting Group exemplify senior partner-led policy advisory. These named entities represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| McKinsey & Company |
| PwC |
| Accenture |
| KPMG |
| EY |
| Deloitte |
| Boston Consulting Group |
| Capgemini |
| Booz Allen Hamilton |
| Others |
Pricing and Supply Chain Analysis
Consultant billing rate indices from the Bureau of Labor Statistics Professional and Business Services segment cascade through public sector procurement tiers, compressing margins for mid-tier advisory firms while federal security-cleared specialists capture premium positioning in United States defense contracting.
Pricing Analysis
Expedited security clearance timelines command 25-40% rate premiums over standard-vetted personnel in United States federal advisory contracts. Three-tier pricing structure across partner-led strategy, manager-delivered implementation, and analyst-supported research separates premium advisory firms from standard consultancies and economy-tier staffing agencies. Cost compression in operational consulting is intensifying because Brazilian federal agencies compressed RFP windows from 180 to 90 days under fiscal consolidation mandates. State and local procurement offices exhibit highest price sensitivity, while defense intelligence agencies demonstrate lowest sensitivity due to security clearance bottlenecks constraining supplier alternatives.
Supply Chain Analysis
Freight and logistics costs for on-site consultant deployment absorb 8-12% of engagement economics in Southeast Asian administrative reform programs spanning Indonesia, Thailand, and Vietnam. Talent supply concentrates in the United States, United Kingdom, and India, with Delhi-NCR and Bangalore clusters specializing in public digital transformation consulting. Raw material dependencies include cybersecurity-cleared personnel pools, proprietary methodology licenses, and cloud infrastructure access credentials. Single-source vulnerability runs through United States federal security clearance processing pipelines, where 12-18 month vetting delays create deployment bottlenecks. Distribution runs through direct federal procurement vehicles, framework agreements, and subcontractor networks to prime contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Security clearance processing capacity constraints prop pricing premiums for cleared consultants, creating a supply-constrained market structure favoring incumbent vendors with established federal relationships.
For Market Incumbents: Anchor federal digital infrastructure practice capabilities through accelerated security clearance pipeline investments and exclusive teaming agreements with cleared personnel brokers. Counter emerging boutique cybersecurity specialists by embedding technical architects directly within agency delivery teams, transferring performance risk through outcome-based contracting vehicles while capturing multi-year framework renewals.
For New Entrants and Emerging Players: Cloud-native advisory platforms targeting mid-tier state and local agencies offer the most penetrable entry vector, bypassing federal security clearance barriers that constrain incumbent mobility. Pursue EU AI Act compliance documentation automation as a white-space opportunity in Germany, France, and Netherlands public agencies. Deploy fixed-price productized service modules through government technology marketplaces to circumvent lengthy RFP cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cybersecurity boutiques with existing United States federal facility clearances in Northern Virginia and Washington DC corridors. Long-term viability hinges on algorithmic governance advisory capabilities expanding across European public procurement mandates. Monitor CSRD disclosure implementation velocity as the inflection indicator for sustainability-linked consulting demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Security Clearance Pipeline Investment | Accelerates consultant deployment velocity for United States federal contracts under NIST frameworks. |
| EU Regulatory Compliance Specialization | Captures mandatory advisory scope from EU AI Act and CSRD disclosure rules in Berlin and Munich agencies. |
| Outcome-Based Contracting Capability | Aligns with United Kingdom Crown Commercial Service frameworks tying fees to measurable operational improvements. |
| Urban Digital Twin Systems Integration | Opens Singapore Smart Nation and Dubai AI Roadmap city-scale simulation consulting opportunities. |
| India PLI Scheme Advisory Practice | Addresses BIS standards implementation and domestic vendor qualification demand in Delhi-NCR clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving federal procurement officers, state digital transformation leads, defense contracting specialists, and international organization framework managers. Secondary sources encompassed SEC 10-K disclosures from listed advisory firms, EU public procurement databases, Indian government tender portals, and United States Federal Procurement Data System extracts. Bottom-up engagement-level sizing triangulated against top-down market aggregation from national consulting industry associations.
Segmentation granularity modeled service type, client category, engagement model, and project size dimensions at the country level across the analysis window, with technology consulting and strategy consulting tracked separately for cloud migration versus policy advisory revenue pools. CAGRs derived from weighted least-squares fitting of annual contract award values, incorporating EU Green Deal procurement rule changes and India's national e-governance mandate implementation schedules as structural break adjustments.
The model holds under stable security clearance processing timelines and sustained fiscal consolidation mandates; deviation in federal procurement rule changes or geopolitical restrictions on cross-border advisory delivery would shift competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Healthcare Consulting Services Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Healthcare ERP Consulting Services Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market