
 Healthcare IT Services Market | 2026-2036
Healthcare IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare IT Services Market Analytics
Subscription-based managed services is decoupling software ownership from operational control in hospital IT procurement. Epic Systems anchors its competitive stance through deep clinical workflow integration across academic medical centers. Cognizant leverages global delivery networks to sustain cost advantages in large-scale EMR implementation programs. Tata Consultancy Services competes on hybrid cloud orchestration, positioning its healthcare vertical for multi-year infrastructure transformation contracts.
Healthcare IT Services encompass the design, deployment, integration, and ongoing management of digital infrastructure that processes clinical, financial, and operational data across provider organizations, typically operating under 99.9% uptime SLAs with HIPAA-compliant encryption protocols. Their primary purpose is to reduce medical errors, accelerate reimbursement cycles, and enable real-time care coordination across distributed clinical teams. Cloud-Based deployment now captures the fastest expansion as hospitals exit capital-intensive data center ownership, while On-Premises systems retain margin concentration among security-sensitive academic institutions. Revenue Cycle Management applications sit at the center of vendor competition because billing complexity creates sticky, long-term client relationships with high switching costs.
FDA 21st Century Cures Act rules, HIPAA Security Rule amendments, and ONC certification requirements collectively mandate interoperable data exchange and penalize information blocking across provider networks. These frameworks force IT services vendors to embed standardized APIs and audit-ready access logs into every implementation, raising compliance costs but also creating contractual stickiness. Stakeholders must monitor whether emerging state-level privacy laws fragment interoperability standards or consolidate around federal benchmarks.
Market Dynamics
Cloud-based electronic medical record platforms are decoupling hospital IT procurement from capital-intensive data center ownership, forcing legacy system vendors to pivot toward subscription architectures.
Growth Catalysts
- FDA 21st Century Cures Act:Interoperability mandates compel provider networks to replace siloed systems with standardized API architectures, creating mandatory upgrade cycles across hospital systems.
- Remote patient monitoring infrastructure:Telehealth platforms now require real-time data pipelines that integrate wearable biosensors with clinical decision support systems.
- United States federal incentive programs:Medicare reimbursement adjustments reward hospitals demonstrating meaningful use of certified health IT, sustaining multi-year modernization budgets.
Market Restraints
- HIPAA compliance cost escalation:Encryption protocol upgrades and audit-ready access logging impose recurring operational burdens that compress margins for mid-sized provider networks.
- Legacy system technical debt:Decades-old on-premises architectures resist API integration, forcing expensive middleware layers that delay cloud migration timelines.
- Cyber insurance premium volatility:Ransomware frequency spikes against hospital networks have doubled coverage costs, diverting capital from innovation budgets.
Strategic Opportunities
- Rural health clinic digitization:Federally qualified health centers in underserved counties lack EMR infrastructure, creating greenfield deployment opportunities for cloud-native platforms.
- AI-augmented clinical documentation:Natural language processing convergence with voice recognition is automating physician note generation, reducing administrative burden.
- Outcome-based reimbursement models:Value-based care contracts reward predictive analytics capabilities that identify high-risk patient cohorts before acute episodes.
Industry Challenges
- Health informatics talent scarcity:Clinical workflow analysts who bridge medical knowledge with system configuration command premium compensation, constraining implementation velocity.
- Multi-vendor integration complexity:Best-of-breed architectures spanning separate EMR, revenue cycle, and imaging platforms create data synchronization failures that disrupt care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare IT Services Market |
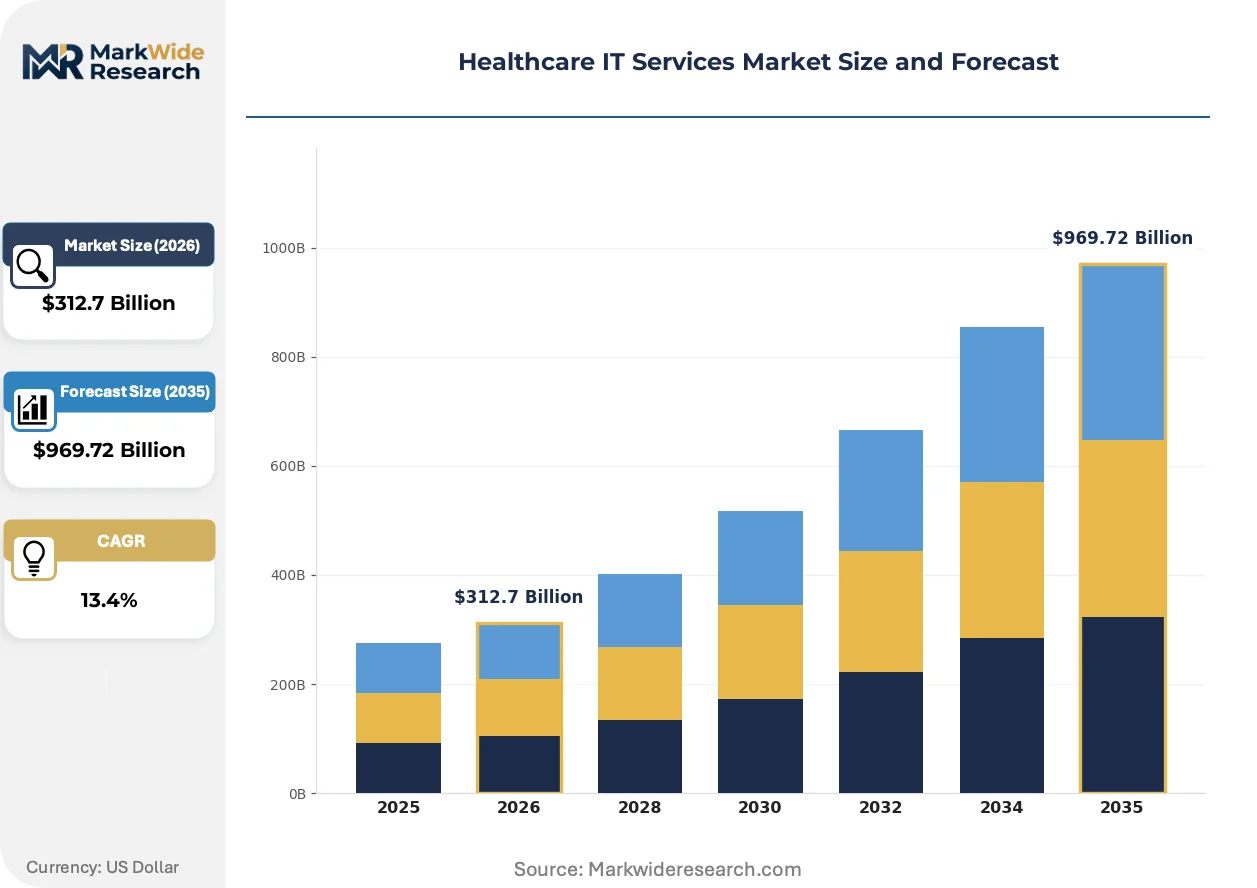
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $969.72 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electronic Medical Records, Telemedicine, Healthcare Analytics, Clinical Workflow End User: Hospitals, Physician Practices, Diagnostic Laboratories, Rehabilitation Centers Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services Application: Patient Management, Revenue Cycle Management, Data Integration, Population Health Management |
| Companies Covered | Accenture, Epic Systems, Cognizant, Infosys, Tata Consultancy Services, Wipro, Oracle Health, Dell Technologies, Optum Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare IT Services Market Evolving Landscape
Healthcare IT services are pivoting from licensed software sales toward continuous operational partnerships, embedding vendors into clinical workflow management rather than discrete technology transactions.
Interoperability middleware is consolidating previously fragmented data exchange protocols into unified platforms that normalize inputs from disparate EMR systems. Large academic medical centers in the United States are adopting these layers to connect acquired community hospitals without forcing wholesale system replacements. The technology is consolidating vendor landscapes by absorbing point-solution connectivity tools into comprehensive integration suites.
The ONC 21st Century Cures Act Final Rule enforcement is compelling health information networks to certify against standardized APIs or face information blocking penalties. Vendor engineering roadmaps now prioritize FHIR-based data exchange over proprietary formats. Small physician practices lacking compliance resources are consolidating into larger groups that can absorb certification costs.
Hospital procurement committees are demanding subscription pricing with embedded uptime guarantees rather than perpetual licenses with separate maintenance contracts. This restructures vendor cash flows toward recurring revenue models and lengthens contract evaluation cycles. The shift is most visible in United States health systems where capital expenditure constraints favor operational expense treatment for IT investments.
Healthcare IT Services Market Segmentation
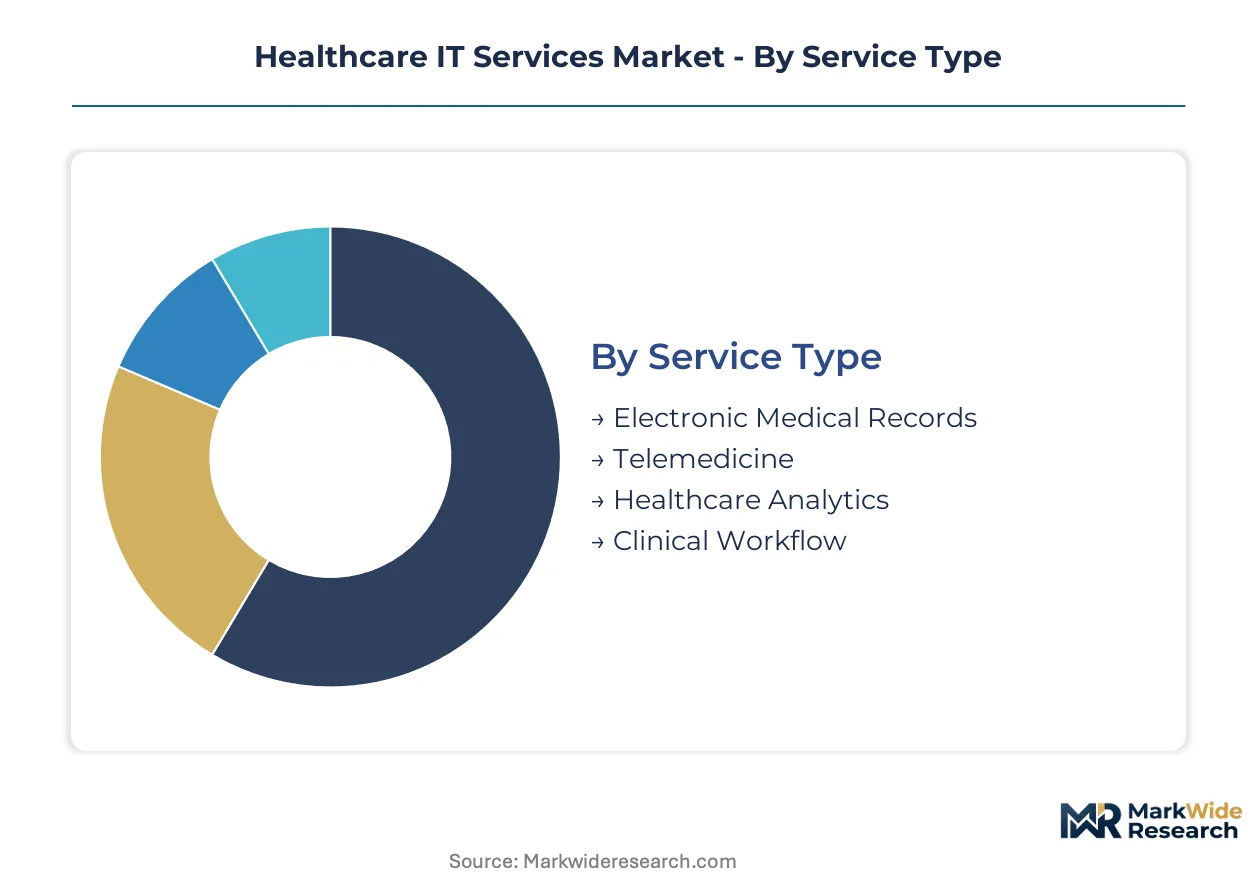
Healthcare IT services segmentation reveals divergent capital requirements across service architectures. Procurement committees weigh upfront infrastructure investment against long-term operational flexibility when selecting deployment models and application portfolios.
Service Type:
Electronic Medical Records demands the heaviest capital commitment for initial system configuration and data migration. Telemedicine infrastructure requires lower upfront investment but escalates rapidly with endpoint scaling.
- Electronic Medical Records:Core clinical data repositories integrating patient history, medication records, and diagnostic results across care episodes. Academic medical centers in the United States concentrate procurement here, driven by federal meaningful use incentive structures that penalize non-compliance. Epic Systems and Cerner installations dominate this tier with multi-year implementation timelines.
- Telemedicine:Real-time video consultation platforms with embedded clinical documentation workflows. Rural health clinics across underserved United States counties are accelerating adoption, compelled by reimbursement parity mandates that equalize virtual and in-person visit payments. Platform differentiation centers on EHR integration depth rather than video quality alone.
- Healthcare Analytics:Predictive modeling tools processing claims and clinical data to identify cost drivers and outcome variations. Health systems deploy these for population risk stratification.
- Clinical Workflow:Task automation and care coordination platforms reducing administrative burden on nursing staff. Demand concentrates in hospitals facing labor shortages.
Most installed capacity flows through Electronic Medical Records. Expansion is steepest in Telemedicine.
End User:
Hospital procurement cycles stretch 18-36 months with committee-driven vendor selection. Physician practices execute faster decisions but demand lighter implementation footprints.
- Hospitals:Integrated delivery networks operating emergency, inpatient, and ambulatory services under unified governance. Large United States health systems anchor demand, compelled by FDA 21st Century Cures Act mandates requiring interoperable data exchange across acquired facilities. Capital budgets here absorb multi-million dollar EMR replacement projects.
- Physician Practices:Outpatient clinics and group practices delivering primary and specialty care. Independent practices in the United States are consolidating into larger groups to share certification costs for ONC compliance. Cloud-native platforms displace server-based systems as ownership economics shift toward subscription models.
- Diagnostic Laboratories:Clinical and anatomic pathology services processing specimens for referring providers. Integration with ordering EMR systems drives vendor selection.
- Rehabilitation Centers:Post-acute facilities managing physical, occupational, and speech therapy workflows. Long-term care documentation requirements shape system requirements.
Procurement volume concentrates in Hospitals. Physician Practices are gaining share fastest as consolidation creates scalable buying power.
Deployment:
Cloud-Based architectures eliminate data center capital expenditure but introduce recurring operational commitments. On-Premises retention correlates with security sensitivity and legacy integration complexity.
- Cloud-Based:Multi-tenant SaaS platforms with vendor-managed infrastructure and automatic security patching. United States community hospitals are accelerating migration here, exiting owned data center operations to redirect capital toward clinical equipment. AWS and Azure healthcare-specific instances dominate infrastructure choices.
- On-Premises:Client-owned server installations with direct hardware control and customized security configurations. Academic medical centers with research data requirements maintain this model for sensitive genomic and imaging repositories.
- Hybrid:Split architectures placing patient-facing systems in cloud while retaining sensitive research or financial data on local infrastructure. Transitional deployments dominate mid-tier health systems.
- Managed Services:Outsourced IT operations with vendor assumption of uptime, security, and compliance responsibilities. Rural hospitals lacking internal technical depth favor this model.
Cloud-Based deployments capture the majority of new contract value. Hybrid configurations are expanding most quickly as staged migration strategies prevail.
Application:
Revenue Cycle Management applications generate the stickiest vendor relationships due to billing complexity and switching costs. Patient Management systems face commoditization pressure from standardized interoperability requirements.
- Revenue Cycle Management:Claims processing, denial management, and patient financial engagement platforms optimizing reimbursement velocity. United States hospitals concentrate investment here as Medicare Advantage penetration complicates billing workflows. Vendors embed AI-driven denial prediction to differentiate commoditized transaction processing.
- Patient Management:Scheduling, registration, and care navigation systems coordinating access across service lines. Large physician groups deploy these to reduce no-show rates and optimize panel capacity.
- Data Integration:Interoperability middleware normalizing inputs from disparate EMR, laboratory, and imaging systems. Health information exchanges mandate these layers for Cures Act compliance.
- Population Health Management:Risk stratification and care gap identification tools for value-based contract performance. Accountable care organizations anchor demand as downside risk exposure grows.
Revenue Cycle Management commands the largest installed base. Population Health Management is climbing the fastest as value-based reimbursement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as HIPAA compliance costs in the United States push mid-tier providers toward offshore-managed service partnerships. Cloud infrastructure investments concentrate where federal incentive programs offset migration expenses.
United States
Hospital systems in Texas and Florida are consolidating EMR procurement through multi-year cloud migration contracts. The FDA 21st Century Cures Act mandates API-standardized data exchange, forcing legacy system replacements across community hospital networks. Epic Systems anchors deployments in academic medical centers throughout the Midwest and Northeast corridors.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are adopting hybrid cloud architectures for clinical research data management. The EU Medical Device Regulation (MDR) and GDPR compliance requirements drive investment in audit-ready health information systems. Berlin-Brandenburg health information exchanges are deploying interoperability middleware to connect fragmented regional networks.
United Kingdom
NHS trusts in London and the Midlands are accelerating procurement of AI-augmented clinical documentation platforms. NHS Digital interoperability standards mandate FHIR-based data exchange across primary and secondary care boundaries. Manchester and Birmingham health systems are piloting population health management tools for value-based contract performance.
India
IT services exporters in Bangalore and Hyderabad are capturing multi-year EMR implementation contracts from United States hospital systems. The Digital India health stack and CDSCO medical device regulations create domestic compliance frameworks for clinical software deployment. Apollo and Max Healthcare networks in Delhi-NCR and Maharashtra are deploying indigenous telemedicine platforms at scale.
Japan
Metropolitan hospital networks in Tokyo and Osaka are migrating from legacy on-premises systems to vendor-managed cloud infrastructure. PMDA pharmaceutical regulations and METI digital health initiatives mandate standardized electronic prescribing across provider tiers. Nagoya medical device manufacturers are integrating clinical workflow software into diagnostic equipment platforms.
Healthcare IT Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with deep clinical workflow integrators commanding premium positioning in academic medical centers while global delivery networks capture scale-driven implementation contracts. The vendor base concentrates around three strategic archetypes: clinical platform specialists anchoring high-switching-cost EMR relationships, IT services conglomerates leveraging offshore labor arbitrage, and cloud infrastructure providers monetizing compute consumption. Competitive moves center on subscription pricing transitions and interoperability certification acceleration.
Among United States-based clinical platform developers, Epic Systems exemplifies the deep-integration archetype through multi-year academic medical center deployments. Cognizant and Tata Consultancy Services occupy positions within the global delivery tier, sustaining cost advantages in large-scale EMR migration programs through offshore technical workforce deployment. Accenture represents the consulting-led integration model, embedding advisory services into infrastructure transformation contracts.
| Leading Market Players |
|---|
| Accenture |
| Epic Systems |
| Cognizant |
| Infosys |
| Tata Consultancy Services |
| Wipro |
| Oracle Health |
| Dell Technologies |
| Optum Inc. |
| Others |
Value Network & Pricing Analysis
FDA 21st Century Cures Act interoperability mandates gate qualified supply access for healthcare IT vendors, restricting premium-tier pricing to those with certified FHIR-based API architectures and audit-ready compliance frameworks. Hospital procurement committees leverage this qualification threshold to consolidate vendor selection around subscription models with embedded uptime guarantees, compressing margins for uncertified competitors while elevating pricing power for compliant incumbents.
Pricing Analysis
Capacity additions in India are reshaping price floors for EMR implementation services as offshore technical workforces expand delivery bandwidth for United States hospital systems. Subscription-based SaaS-tiered pricing dominates hospital procurement, with differentiation driven by ONC certification level and geographic delivery cost from nearshore versus offshore configuration teams. Pricing pressure stems from ransomware-driven cyber insurance premium spikes diverting hospital capital from innovation budgets. Community hospital networks exhibit highest price sensitivity, while academic medical centers with research data requirements absorb premium tiers for customized security configurations.
Supply Chain Analysis
ONC certification requirements gate vendor participation, restricting qualified supply to firms with FHIR-standardized development pipelines and HIPAA-compliant encryption protocols. Engineering talent concentrates in India, the United States, and Germany, with clinical workflow analysts bridging medical knowledge and system configuration commanding premium compensation. Raw material dependencies include cloud infrastructure from AWS and Azure healthcare-specific instances, specialized health informatics labor pools, and interoperability middleware licenses. Single-source vulnerability runs through concentrated hyperscaler infrastructure providers. Distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA 21st Century Cures Act enforcement cycles create mandatory upgrade demand across provider networks regardless of macroeconomic conditions.
For Market Incumbents: Lock in multi-year managed services contracts with rural health clinics before federal qualified health center digitization programs accelerate competitive bidding. Deepen clinical workflow integration through AI-augmented documentation modules to elevate switching costs against cloud-native challengers. Vertical integration into cybersecurity operations addresses ransomware exposure threatening hospital client retention. For New Entrants and Emerging Players: Cloud-native platform vendors represent the most penetrable channel partner type for rural health clinic digitization opportunities in underserved United States counties lacking EMR infrastructure. Target federally qualified health centers with lightweight implementation footprints and subscription pricing that converts capital expenditure to operational expense. Deploy outcome-based reimbursement analytics as a differentiated go-to-market wedge against legacy revenue cycle incumbents. For Investors and Strategic Acquirers: Roll-up economics work for clinical workflow specialists because health informatics talent scarcity constrains organic hiring velocity across mid-tier health systems. Platform consolidation around interoperability middleware creates defensible moats as Cures Act enforcement intensifies. Watch for Medicare Advantage penetration rates as the inflection signal accelerating demand for predictive analytics capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Acceleration | ONC compliance deadlines force engineering roadmap prioritization toward standardized APIs over proprietary formats. |
| AI-Augmented Documentation Development | NLP convergence with voice recognition automates physician note generation for labor-constrained hospital networks. |
| Rural Health Clinic Partnership | Federally qualified health centers in underserved counties present greenfield cloud-native deployment opportunities. |
| Interoperability Middleware Acquisition | Consolidation of point-solution connectivity tools into unified integration suites absorbs fragmented vendor landscapes. |
| Outcome-Based Reimbursement Analytics | Value-based care contracts reward predictive capabilities identifying high-risk patient cohorts before acute episodes. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, health system CIO discussions, and GPO contract database analysis — were reconciled against secondary validation from CMS Medicare reimbursement data, FDA 510(k) filings, and ONC certification registries. Primary fieldwork engaged clinical workflow analysts, biomedical engineers, and hospital purchasing directors across academic medical centers and community hospital networks. Bottom-up segmentation modeling triangulated against top-down market sizing from health IT expenditure surveys and federal incentive program disbursement records.
Data-stream reconciliation anchored volume and value outputs across deployment models, organization size tiers, application portfolios, and regional regulatory clusters. CAGRs were derived from segmented growth trajectory analysis incorporating Medicare Advantage penetration curves, Cures Act enforcement timelines, and cloud migration velocity indicators. Forecast inputs included health informatics labor supply constraints, cyber insurance premium volatility patterns, and federal meaningful use incentive program continuity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level privacy law fragmentation, ransomware frequency trajectories, and federal reimbursement policy shifts. Model outputs reflect documented assumptions regarding interoperability standard adoption rates and hospital capital expenditure recovery post-pandemic. A model refresh is warranted upon material change in ONC information blocking penalty enforcement intensity or Medicare reimbursement adjustment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Clinical Communication and Collaboration Market