
 Global Healthcare Consulting Services Market | 2026-2036
Global Healthcare Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Consulting Services Market Foresight
The shift from single-source advisory contracts to multi-vendor ecosystems is pivoting how health systems procure expertise. Deloitte leverages its regulatory compliance practice to anchor large hospital network engagements across North America. McKinsey & Company competes on strategy advisory mandates for pharmaceutical clients navigating pricing pressure. IQVIA sustains dominance in clinical research consulting through proprietary real-world evidence platforms.
Healthcare consulting services encompass advisory engagements that apply clinical workflow analysis, health economics modeling, and interoperability standards to improve institutional performance and patient outcomes. These services primarily enable providers, payers, and life sciences firms to reduce operational waste while maintaining care quality. Strategy Advisory commands the largest fee pool as health systems pursue merger integration and service line rationalization, while Digital Transformation represents the fastest-expanding segment as telehealth infrastructure and AI governance frameworks mature. Regulatory Compliance maintains durable margins in Europe and North America where FDA, EMA, and EU MDR submission requirements intensify.
FDA digital health guidance, EU MDR implementation timelines, and HIPAA security rule enforcement collectively shape consultant demand by mandating specialized expertise that internal teams rarely possess. The EU AI Act introduces additional compliance layers for algorithmic clinical decision tools, creating new advisory categories. Stakeholders must monitor how regulatory fragmentation between the FDA's pre-certification pathway and EU conformity assessment procedures affects cross-border service standardization and talent deployment.
Market Dynamics
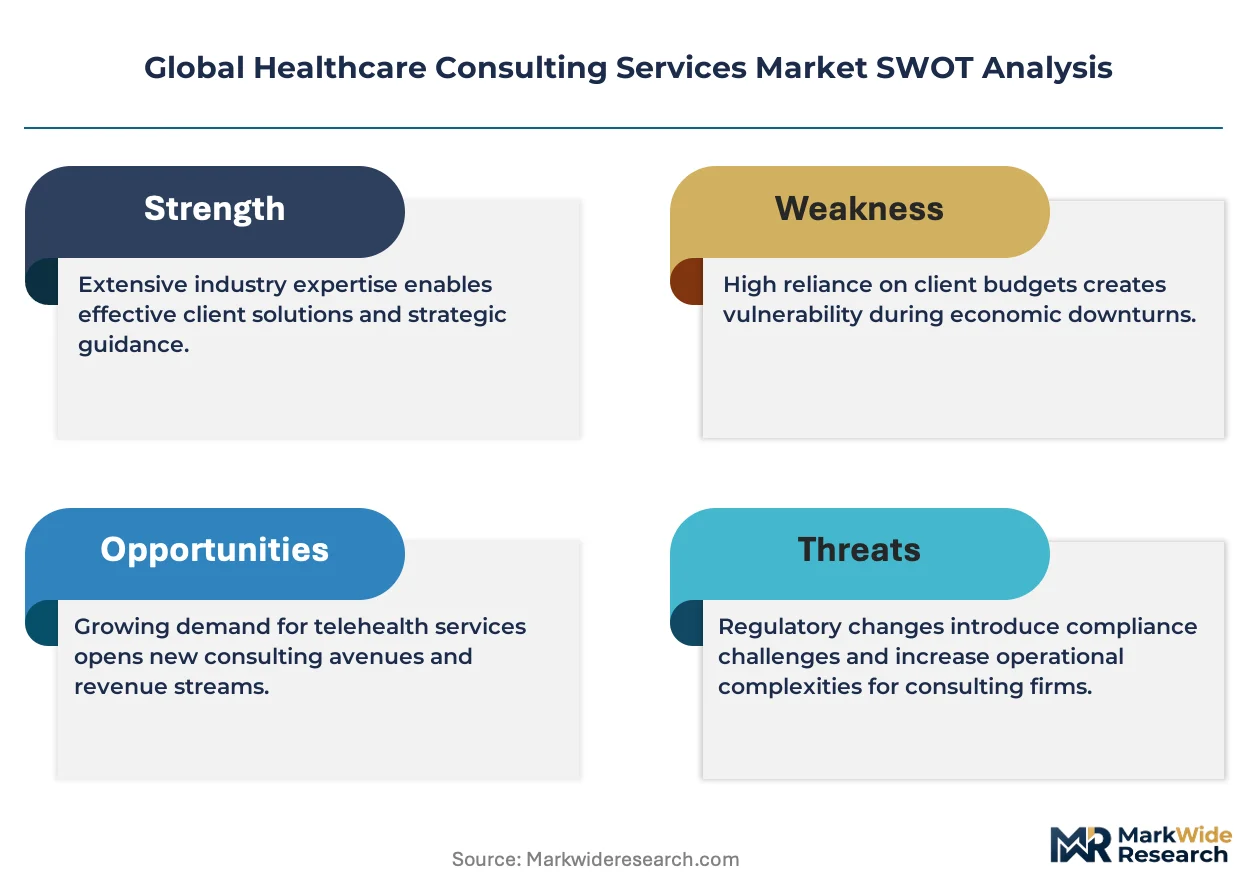
Hospital systems are fragmenting their advisory procurement across specialized boutiques rather than consolidating with full-service firms, compressing contract values while expanding vendor rosters. This structural unbundling is forcing consultancies to defend engagement scope through proprietary data assets and regulatory credentialing.
Growth Catalysts
- EU MDR compliance deadlines:Medical device manufacturers in Germany and France are retaining consultants to navigate clinical evidence requirements and notified body backlogs.
- Telehealth infrastructure scale-up:Health systems are engaging workflow specialists to integrate remote monitoring platforms with existing EHR architectures.
- FDA pre-certification pathway:Software-as-a-medical-device developers require submission support for algorithm validation and real-world performance monitoring.
Market Restraints
- Talent scarcity in health economics:The shallow pool of consultants holding advanced degrees in pharmacoeconomics and outcomes research inflates project staffing costs.
- Client procurement standardization:Large hospital networks are imposing uniform contracting templates that strip consultancies of pricing flexibility and intellectual property protections.
- Substitution by internal analytics teams:Health systems with mature data science functions are insourcing clinical workflow analysis previously contracted externally.
Strategic Opportunities
- EU AI Act implementation:Risk management system requirements for clinical decision support algorithms create advisory demand for conformity assessment documentation.
- Japan's digital therapeutics pathway:PMDA's evolving framework for software-based interventions opens consulting mandates for market entry strategy and local partnership structuring.
- AI governance and bias auditing:Convergence of machine learning validation with HIPAA security assessments enables bundled service offerings for algorithmic accountability.
Industry Challenges
- Legacy EHR integration complexity:Consulting teams face extended timelines and cost overruns when embedding new digital tools into entrenched Cerner and Epic installations.
- Cross-border credential recognition:Consultants credentialed under FDA pathways lack automatic standing for EU MDR submissions, fragmenting project staffing across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Consulting Services Market |
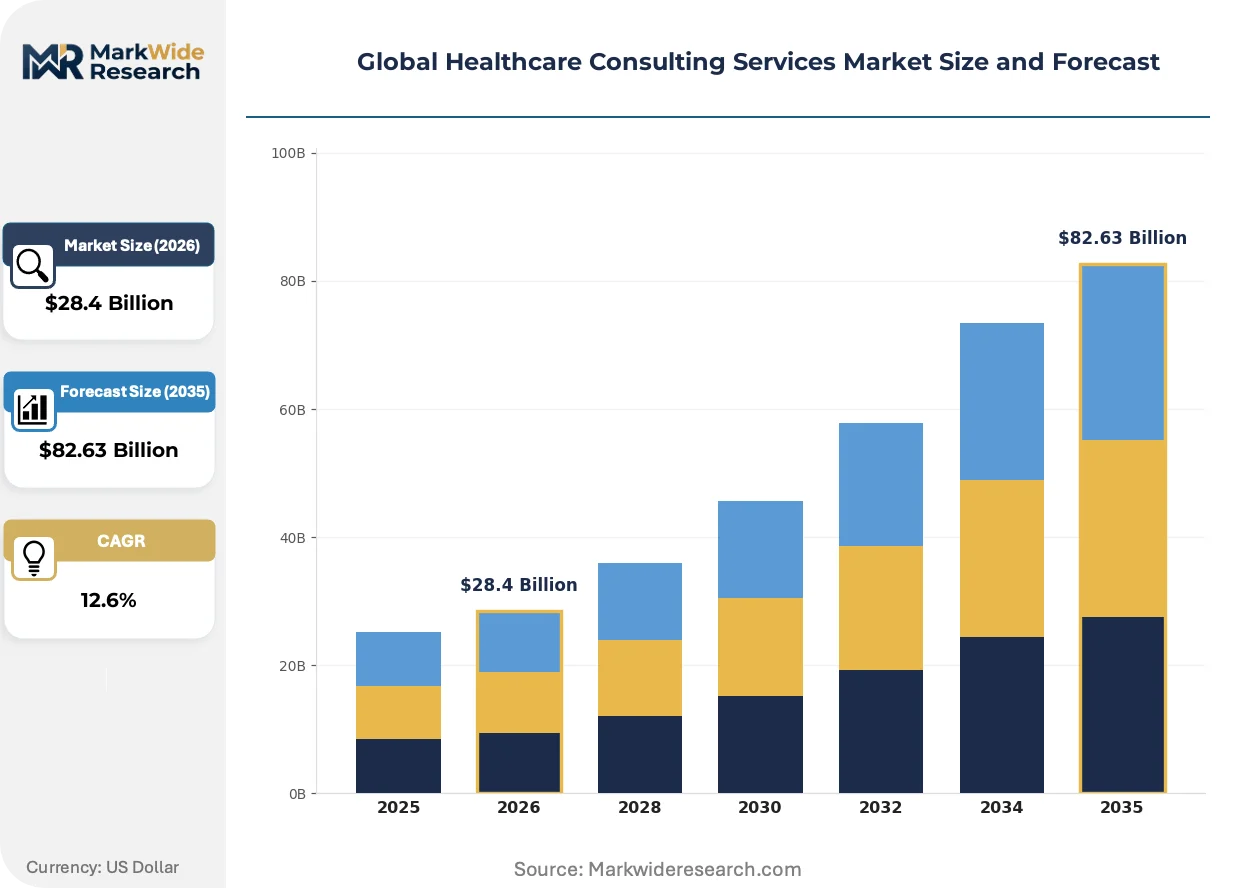
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $82.63 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Advisory, Regulatory Compliance, Operational Improvement, Digital Transformation, Risk Management Client Type: Hospitals, Pharmaceutical Firms, Biotechnology Companies, Medical Device Manufacturers, Health Insurers Delivery Model: Onsite Consulting, Remote Support, Managed Services, Project-based Engagements, Training & Development Application Area: Patient Care Optimization, Clinical Research, Healthcare IT Integration, Supply Chain Management, Cost Containment |
| Companies Covered | Accenture, Bain & Company, Deloitte, L.E.K. Consulting, Huron Consulting Group, McKinsey & Company, PwC, IQVIA, Boston Consulting Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Consulting Services Market Shifts & Advancements
Advisory delivery models are compressing from multi-year transformation programs into sprint-based engagements with discrete deliverables. This acceleration reflects client demand for faster evidence generation and reduced commitment risk.
Cloud-native clinical analytics platforms are modularizing how consultants deploy real-world evidence capabilities. Mid-sized health systems in the United States are adopting these tools on twelve-week implementation cycles, bypassing traditional eighteen-month bespoke builds. The technology is modularizing project economics and enabling subscription-based advisory relationships.
EMA's tightened guidance on external control arms in oncology trials is reshaping clinical development strategy. Pharmaceutical sponsors now require consultant support to design synthetic comparator methodologies and navigate health technology assessment scrutiny. European markets are responding by consolidating advisory spend with firms holding both regulatory and health economics capabilities.
Buying committees are unbundling strategy advisory from implementation support, awarding these phases to separate vendors. Hospital procurement departments in Germany are driving this bifurcation through mandated competitive tendering for contracts exceeding defined thresholds. The pattern concentrates strategy mandates with established names while dispersing execution work to specialized boutiques.
Global Healthcare Consulting Services Market Segmentation
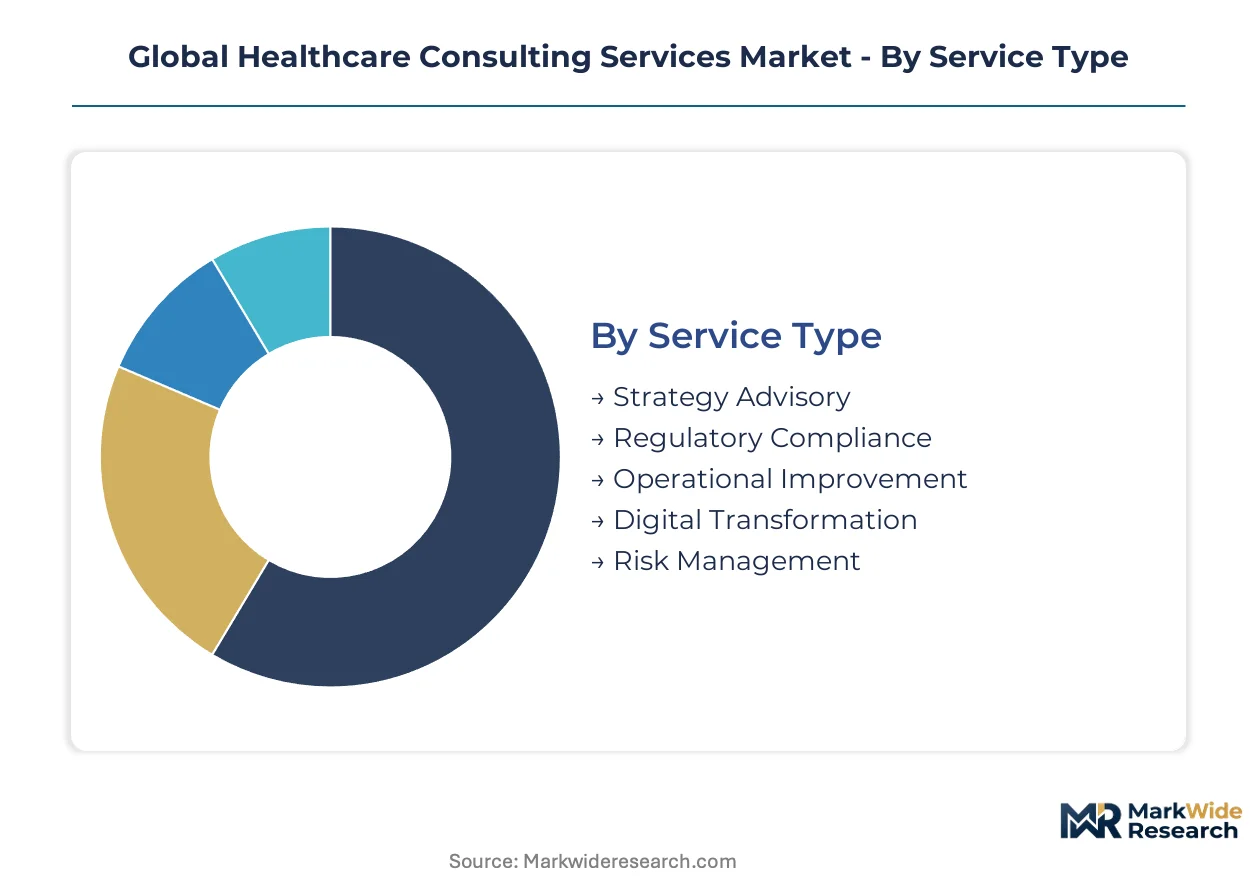
Healthcare consulting services fragment across four structural axes that determine pricing, engagement duration, and capability requirements. Service type and client type together account for the majority of fee variance, while delivery model and application area shape talent deployment patterns.
Service Type:
Technical sophistication and regulatory credentialing define competitive positioning across service categories.
- Strategy Advisory:Encompasses merger integration, service line rationalization, and portfolio restructuring for health systems. Hospital networks in Germany and the United States concentrate demand here as consolidation accelerates. Fee structures reflect partner-level involvement and proprietary market intelligence.
- Digital Transformation:Covers telehealth infrastructure design, AI governance frameworks, and cloud-native EHR integration. Biotechnology companies in Japan and medical device manufacturers navigating FDA pre-certification drive the steepest expansion trajectory. Implementation cycles compress from eighteen months to twelve weeks.
- Regulatory Compliance:EU MDR submission support, FDA validation documentation, and HIPAA security assessments. Medical device manufacturers facing notified body backlogs sustain durable margins.
- Operational Improvement:Clinical workflow analysis, capacity planning, and supply chain optimization. Health insurers seeking cost containment anchor recurring engagements.
- Risk Management:Enterprise risk frameworks, cybersecurity assessments, and business continuity planning. Hospital systems post-ransomware incidents drive episodic demand.
Mature deployment sits with Strategy Advisory. Newer deployment is concentrated in Digital Transformation.
Client Type:
Procurement sophistication varies sharply across buyer categories, with pharmaceutical firms demanding outcome-based structures and hospitals favoring time-and-materials.
- Pharmaceutical Firms:Require health economics modeling, market access strategy, and clinical trial design. EMA's tightened external control arm guidance reshapes advisory spend toward firms with regulatory and outcomes research capabilities.
- Hospitals:Engage workflow specialists for EHR integration and operational redesign. German hospital networks fragment procurement across boutiques rather than consolidating with full-service firms.
- Biotechnology Companies:Early-stage sponsors need regulatory pathway navigation and investor-facing strategy. Japan's PMDA digital therapeutics framework opens new advisory categories.
- Medical Device Manufacturers:EU MDR compliance deadlines and FDA pre-certification requirements sustain dual-track advisory demand. Notified body capacity constraints extend project timelines.
- Health Insurers:Focus on actuarial consulting, fraud detection, and value-based care program design. Real-world evidence platforms enable subscription relationships.
Fee concentration clusters with Pharmaceutical Firms. Volume expansion is fastest among Biotechnology Companies.
Delivery Model:
Engagement architecture determines margin structure and talent utilization rates across consulting practices.
- Project-based Engagements:Discrete mandates with defined deliverables and fixed fees. Health systems increasingly prefer this structure to reduce commitment risk and accelerate evidence generation.
- Managed Services:Long-term advisory relationships with subscription economics. Cloud-native clinical analytics platforms enable this model for mid-sized United States hospitals.
- Onsite Consulting:Embedded teams for transformation programs and implementation support. Legacy EHR integration complexity extends timelines and inflates cost overruns.
- Remote Support:Distributed advisory for regulatory documentation and health economics modeling. Talent scarcity in pharmacoeconomics constrains scaling.
- Training & Development:Capability building for internal analytics teams and clinical staff. Health systems insourcing previously contracted workflow analysis limits growth.
Revenue weight rests with Project-based Engagements. Margin expansion is strongest in Managed Services.
Application Area:
Use case specificity determines whether advisory mandates require clinical credentials, technical engineering, or operational expertise.
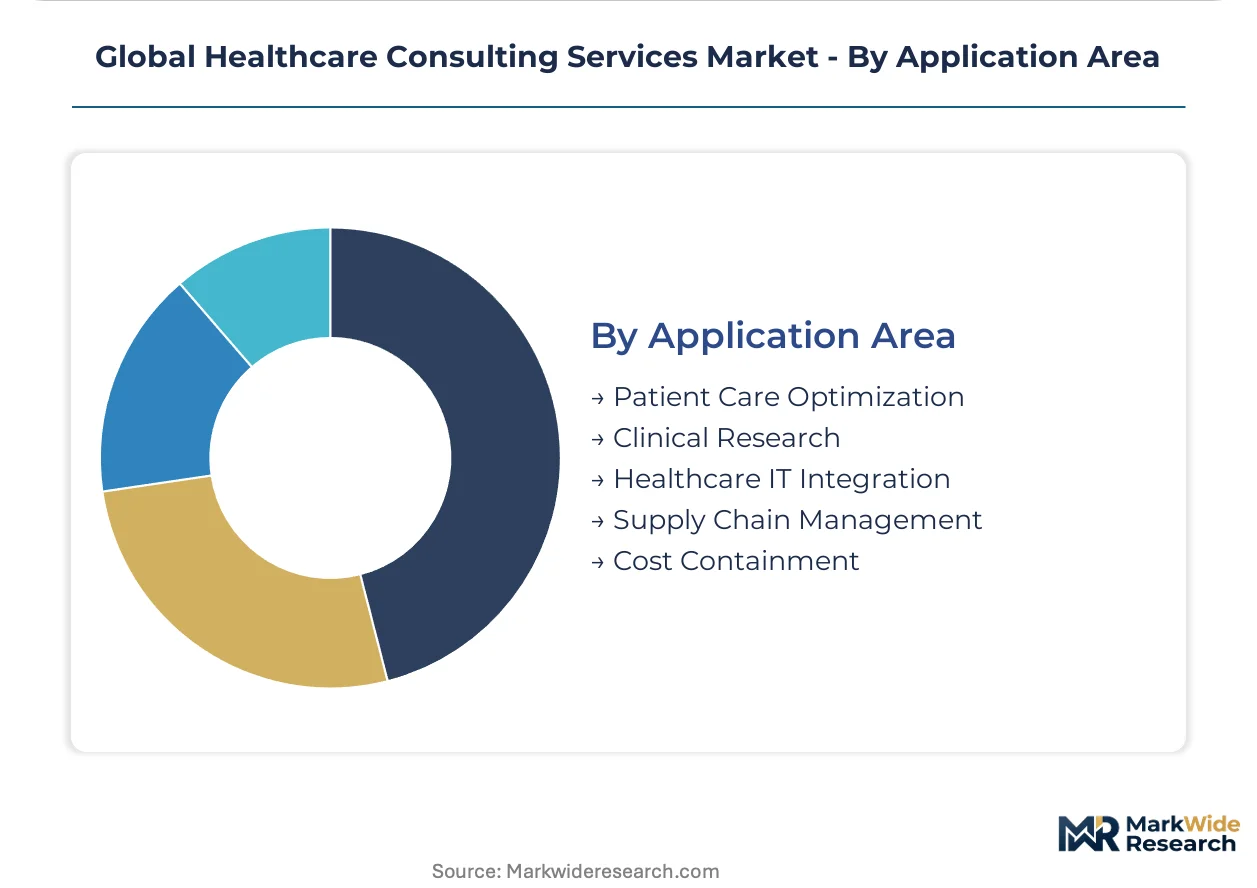
- Clinical Research:Trial design, patient recruitment strategy, and regulatory submission support. Synthetic comparator methodologies for oncology trials reshape consultant demand in Europe.
- Healthcare IT Integration:EHR interoperability, telehealth platform deployment, and data architecture. Cerner and Epic installation complexity creates execution risk.
- Patient Care Optimization:Clinical pathway redesign and quality metric improvement. Hospital value-based purchasing programs sustain demand.
- Supply Chain Management:Procurement optimization, inventory management, and vendor consolidation. Post-pandemic resiliency planning drives episodic engagement.
- Cost Containment:Service line profitability analysis and administrative waste reduction. Health insurers and self-funded employers anchor this segment.
Advisory depth concentrates in Clinical Research. Technology intensity is highest in Healthcare IT Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States concentrate the largest advisory fee pools, while EU MDR compliance deadlines and Japan's PMDA digital therapeutics pathway are redistributing demand across three additional national markets.
United States
FDA pre-certification pathway requirements and telehealth infrastructure scale-up drive consultant retention by software-as-a-medical-device developers and health systems. HIPAA security rule enforcement mandates specialized cybersecurity assessments that internal teams rarely possess. Hospital networks in the Northeast Corridor fragment procurement across boutiques rather than consolidating with full-service firms.
Germany
Hospital consolidation and notified body backlogs for EU MDR submissions sustain durable advisory margins for medical device manufacturers. The country's national pharmaceutical regulator imposes stringent clinical evidence requirements that extend project timelines. Industrial clusters in Bavaria and Baden-Württemberg anchor device manufacturer advisory spending.
United Kingdom
EMA's tightened guidance on external control arms in oncology trials reshapes pharmaceutical sponsor demand toward synthetic comparator methodologies. NHS procurement standardization strips consultancies of pricing flexibility through uniform contracting templates. London-based health economics specialists face talent scarcity that inflates project staffing costs.
Japan
PMDA's evolving framework for digital therapeutics opens consulting mandates for market entry strategy and local partnership structuring. METI's push toward AI governance creates advisory demand for algorithmic clinical decision tools. Biotechnology companies in the Kanto/Tokyo region anchor early-stage sponsor advisory spending.
France
ANSM oversight of EU MDR implementation and health technology assessment scrutiny concentrate advisory demand with firms holding dual regulatory and outcomes research capabilities. The country's national data protection authority enforces GDPR compliance layers for clinical data platforms. Medical device manufacturers in the Île-de-France region retain consultants to navigate notified body capacity constraints.
Global Healthcare Consulting Services Market Competitive Landscape
Multi-vendor ecosystem formation dominates the current landscape as hospital procurement departments unbundle strategy advisory from implementation support. The vendor base organizes into three tiers: full-service networks anchoring large health system engagements, specialized boutiques capturing execution work, and analytics platforms enabling subscription relationships. Two strategic archetypes predominate: regulatory credentialing specialists defending engagement scope through FDA and EU MDR expertise, and cloud-native platform operators modularizing real-world evidence capabilities. M&A activity concentrates on boutique acquisitions for clinical workflow capabilities, while strategic partnerships between consultancies and EHR vendors address legacy integration complexity.
Within the full-service tier, Deloitte leverages its regulatory compliance practice across North American hospital networks, while McKinsey & Company competes on pharmaceutical strategy mandates. IQVIA occupies a distinct position through proprietary real-world evidence platforms that sustain dominance in clinical research consulting.
| Leading Market Players |
|---|
| Accenture |
| Bain & Company |
| Deloitte |
| L.E.K. Consulting |
| Huron Consulting Group |
| McKinsey & Company |
| PwC |
| IQVIA |
| Boston Consulting Group |
| Others |
Supply & Pricing Matrix
Cloud-native clinical analytics platforms are modularizing project economics and compressing implementation cycles from eighteen months to twelve weeks, simultaneously reshaping cost structures and concentrating supply with platform operators who control proprietary data pipelines.
Pricing Analysis
Service bundling separates strategy advisory from implementation support, with EU MDR submission support and FDA validation documentation commanding premium fees due to regulatory credentialing scarcity. Price differentiation rests on certification tier—firms holding dual FDA and EU notified body expertise extract 40-60% fee premiums over generalist competitors. Cost compression in operational improvement engagements is intensifying as health systems with mature data science functions insource clinical workflow analysis. Biotechnology companies exhibit highest price sensitivity due to capital constraints, while pharmaceutical firms prioritize outcome-based structures over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with the shallow talent pool of pharmacoeconomics specialists holding advanced degrees in outcomes research, creating staffing bottlenecks that extend project timelines. Advisory capability concentrates in the United States, Germany, and the United Kingdom, where regulatory complexity sustains specialist firm density. Raw material dependencies include proprietary real-world evidence platforms, cloud infrastructure subscriptions, and regulatory submission software licenses. Tariff exposure runs minimal, though cross-border credential recognition gaps fragment project staffing across jurisdictions. Distribution runs through direct enterprise sales teams and hospital procurement committees, with GPO contracts governing mid-sized health system access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Talent scarcity in health economics and regulatory credentialing props pricing power for incumbent specialists, constraining supply expansion despite accelerating demand from EU MDR and FDA digital health pathways.
For Market Incumbents: Deepen vertical integration into proprietary real-world evidence platforms to defend engagement scope against cloud-native modularization threats. Acquire specialized boutiques for clinical workflow capabilities to anchor multi-vendor ecosystem positioning. Expand EU MDR and FDA dual-credentialing investments to capture cross-border submission mandates that generalists cannot staff. For New Entrants and Emerging Players: Begin with AI governance and bias auditing services for mid-sized United States hospitals seeking bundled algorithmic accountability offerings. Target Japan's PMDA digital therapeutics pathway, where local partnership structuring demand outpaces established consultancy presence. Pursue subscription-based managed services enabled by cloud-native analytics platforms to bypass capital-intensive bespoke build competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by full-service networks seeking boutique clinical workflow capabilities and regulatory credentialing depth. Long-term viability favors firms with durable data asset moats and cross-jurisdictional submission expertise spanning FDA, EMA, and EU MDR frameworks. Monitor EU AI Act implementation velocity as the critical inflection signal for algorithmic advisory demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Credentialing Investment | Dual FDA-EU MDR expertise commands fee premiums and defends vendor roster positioning. |
| Cloud-Native Platform Development | Modular real-world evidence capabilities enable subscription economics and compress implementation cycles. |
| Boutique Acquisition | Clinical workflow specialists anchor execution-phase work unbundled from strategy mandates. |
| AI Governance Service Launch | EU AI Act risk management requirements create advisory demand for algorithmic conformity assessment. |
| Japan Market Entry Partnership | PMDA digital therapeutics pathway opens consulting mandates for local partnership structuring. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement directors, regulatory affairs consultants, health economics specialists, and GPO contracts managers. FDA 510(k) databases, EMA submission portals, hospital procurement databases, and CMS Medicare cost reports provided validation layers. Bottom-up service line estimates triangulated against top-down health system advisory spending benchmarks.
Data-stream reconciliation across project-based engagement records, managed services subscription data, and regulatory submission timelines informed the analytical framework. Segmentation dimensions modeled include service type, client category, delivery architecture, and application area across the projection horizon. CAGRs derived from regression analysis of historical advisory spending patterns against regulatory deadline schedules and health system consolidation velocity. Forecast inputs incorporated EU MDR notified body capacity constraints and FDA pre-certification pathway adoption curves.
Underlying measurement precision varies by segment; strategy advisory and regulatory compliance carry tighter precision than operational improvement due to more transparent fee structures and defined submission timelines. Forecasts reflect documented assumptions regarding regulatory deadline adherence and hospital procurement standardization trajectories, with EU AI Act implementation velocity and talent pipeline expansion representing key revision variables. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Consulting
Global Public Sector Consulting and Advisory Services Market
Healthcare Consulting
Consulting Service Market
Healthcare Consulting
Global Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Italy Operations Service Consulting Market
Healthcare Consulting
Global Regulatory Affairs Market
Healthcare Consulting
Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Africa Pharmaceutical Regulatory Affairs Market
Healthcare Consulting
Global Strategic Consulting Services Market
Healthcare Consulting
Healthcare Regulatory Affairs Outsourcing Market
Healthcare Consulting
UK Healthcare Consulting Market
Healthcare Consulting
Global Healthcare IT Consulting Market
Healthcare Consulting
Europe Medical Device Regulatory Affairs Outsourcing Market
Healthcare Consulting
Healthcare Contract Sales Organizations Market
Healthcare Consulting
Healthcare ERP Consulting Services Market