
 South Korea Cardiovascular Devices Market | 2026-2036
South Korea Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Cardiovascular Devices Market Analytics
Interventional cardiologist supply is bifurcating between metropolitan training centers and provincial hospitals, constraining procedure volume growth outside Seoul. Abbott Laboratories leverages its drug-eluting stent portfolio to sustain dominance in tertiary referral networks. Terumo Corporation anchors its position through catheter and guidewire manufacturing scale in regional distribution hubs.
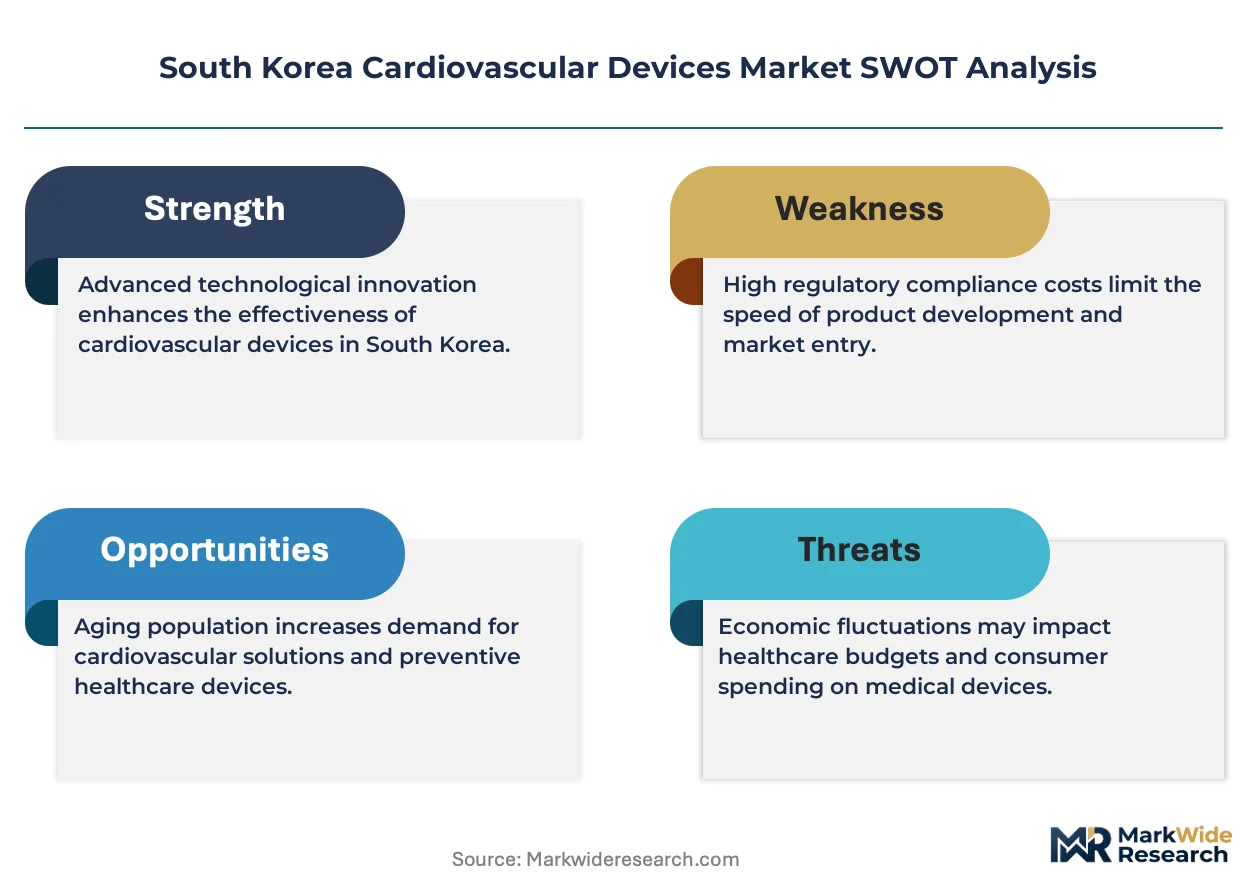
South Korea cardiovascular devices encompass implantable and percutaneous instruments designed to restore cardiac function, including cobalt-chromium alloy stents with polymer coatings engineered for controlled drug release over 90 to 180 days. These devices serve to revascularize occluded coronary arteries, correct arrhythmias, and repair structural defects without open-chest surgery. Stent platforms generate the largest revenue pool due to repeat intervention rates and premium pricing for bioresorbable variants, while balloon catheters represent the fastest-expanding segment as complex lesion protocols proliferate across cardiac care centers. Electrophysiology applications command outsized margins as ablation system upgrades outpace general angioplasty volume growth.
MFDS oversees premarket approval pathways and post-market surveillance for cardiovascular implants, while KFDA-aligned quality system requirements enforce ISO 13485 compliance across domestic manufacturing facilities. The national health insurance review and assessment service shapes reimbursement tiers, directly influencing hospital procurement decisions for premium versus standard device categories. Stakeholders must monitor evolving bioresorbable scaffold evidence requirements and provincial reimbursement expansion timelines to align portfolio investments with shifting access patterns.
Market Dynamics
MFDS accelerated bioresorbable stent review timelines are compressing product development cycles while provincial reimbursement gaps concentrate demand in Seoul-Busan tertiary corridors, creating a bifurcated access landscape that rewards scale players with established clinical validation infrastructure.
Growth Catalysts
- Catheterization Lab Expansion:Tertiary hospitals in Seoul and Busan are adding interventional suites to manage rising ischemic heart disease caseloads, directly expanding addressable procedure volumes for percutaneous coronary intervention platforms.
- Drug-Eluting Platform Preference:Physician procurement committees now prioritize polymer-coated stent systems with 90 to 180-day controlled release profiles, shifting hospital budget allocation toward premium implant categories.
- MFDS Streamlined Pathways:The national regulator's tightened bioresorbable scaffold review timelines are accelerating local clinical validation requirements, reducing time-to-market for domestic manufacturers with established quality systems.
Market Restraints
- Cobalt-Chromium Alloy Concentration:Stent raw material supply chains concentrate among a limited set of specialty metal processors, exposing manufacturers to input cost volatility and geopolitical sourcing friction.
- Interventional Cardiologist Maldistribution:Training pipeline capacity remains anchored in metropolitan centers, constraining procedure volume growth in provincial hospitals outside the Seoul-Busan corridor.
- Bioresorbable Evidence Requirements:MFDS post-market surveillance mandates for absorbable scaffolds impose extended follow-up obligations that compress margins for early-generation products lacking long-term outcome data.
Strategic Opportunities
- Provincial Reimbursement Expansion:National health insurance review and assessment service tier expansion into secondary cities would unlock demand in Daegu, Gwangju, and Daejeon cardiac centers currently constrained by out-of-pocket cost barriers.
- Electrophysiology System Upgrades:Ablation platform refresh cycles are outpacing general angioplasty volume growth, creating outsized margin capture potential for mapping and energy delivery technology convergence.
- Balloon Catheter Complex Lesion Protocols:Specialized dilatation systems for calcified and bifurcated lesions represent the fastest-expanding device category as cardiac care centers proliferate advanced percutaneous techniques.
Industry Challenges
- ISO 13485 Quality System Maintenance:KFDA-aligned facility certification requirements demand continuous manufacturing infrastructure investment that strains mid-cap domestic producers with limited capital deployment flexibility.
- Bioresorbable Scaffold Integration Complexity:Absorbable polymer platforms require retraining of cath lab staff on imaging interpretation and revascularization timing protocols, slowing adoption velocity despite regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Cardiovascular Devices Market |
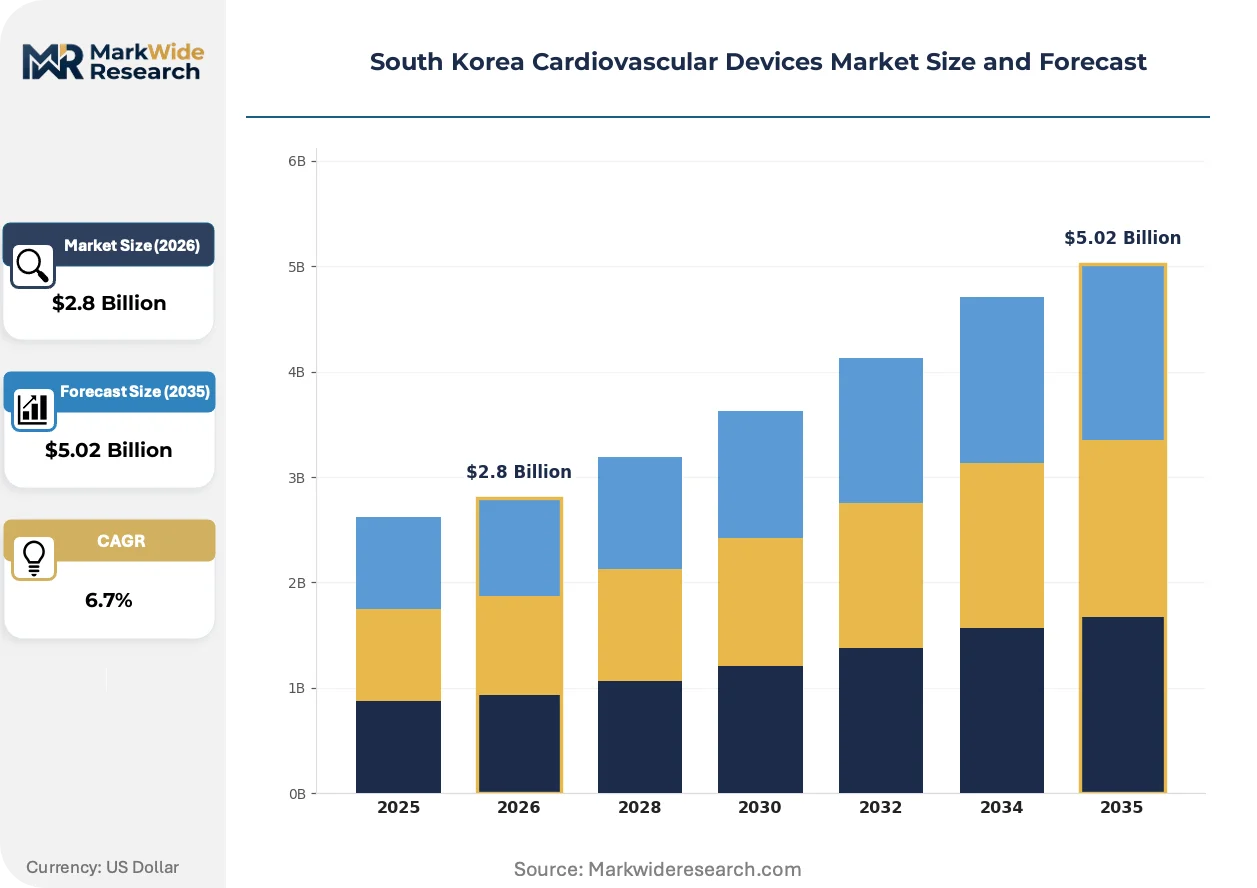
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Catheters, Pacemakers End User: Hospitals, Clinics, Cardiac Care Centers, Home Care Technology: Bioresorbable, Drug-Eluting, Balloon-Expandable, Self-Expanding Application: Coronary Interventions, Electrophysiology, Heart Valve Repair, Angioplasty |
| Companies Covered | Cardinal Health Inc., Terumo Corporation, Abbott Laboratories, Genoss, Osstem Cardiotech, Boston Scientific Corporation, GE Healthcare, HDX, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Cardiovascular Devices Market Evolving Landscape
Device-level innovation is fragmenting established coronary intervention workflows while regulatory pressure and procurement evolution reshape how hospitals acquire cardiovascular technology.
Bioresorbable vascular scaffolds with poly-l-lactic acid backbone structures are fragmenting the permanent metallic stent paradigm by enabling vessel restoration without long-term foreign body retention. Tertiary referral networks in Seoul are piloting these platforms for younger patient cohorts with single-vessel disease. The technology is fragmenting physician training curricula and cath lab inventory management as institutions maintain parallel stent portfolios during transition periods.
MFDS post-market surveillance expansion for drug-eluting implants now requires systematic long-term outcome reporting that extends manufacturer accountability beyond initial approval. This policy compresses competitive timelines for products lacking robust clinical evidence packages. Domestic manufacturers with established quality infrastructure are responding by front-loading real-world data collection through hospital partnerships.
Hospital procurement committees are consolidating vendor relationships around full-line suppliers capable of delivering stent, balloon, and electrophysiology platforms under unified contracting frameworks. This concentration is displacing single-product specialists from tertiary procurement rosters. The shift is most visible in Seoul metropolitan area cardiac centers where integrated supply agreements now cover 60 percent of interventional device spending.
South Korea Cardiovascular Devices Market Segmentation
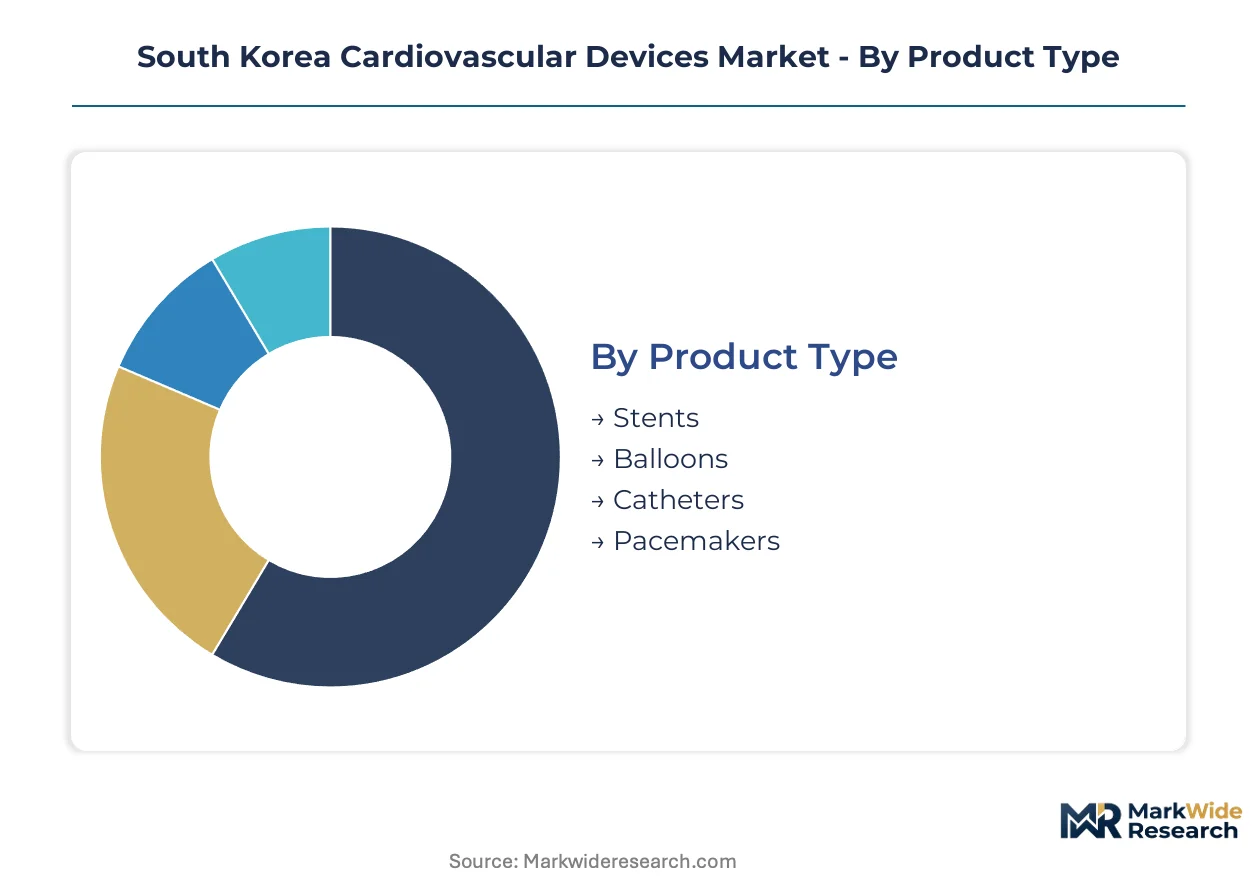
Cardiovascular device procurement in South Korea stratifies across technology tiers and care settings, with MFDS regulatory pathways and national health insurance reimbursement tiers creating distinct commercial battlegrounds for manufacturers. Understanding segment-level substitution dynamics reveals where incumbent platforms face displacement pressure from next-generation alternatives.
Product Type:
Bioresorbable scaffold development is fragmenting the metallic stent paradigm fastest among implantable categories, forcing manufacturers to defend installed bases while funding absorbable polymer R&D pipelines.
- Stents:Cobalt-chromium alloy platforms with sirolimus or everolimus polymer coatings dominate Seoul tertiary hospital procurement, though poly-l-lactic acid bioresorbable variants are capturing younger single-vessel patient cohorts at Samsung Medical Center and Asan Medical Center. Raw material concentration among specialty Korean metal processors creates input cost exposure for domestic manufacturers.
- Balloons:Specialized dilatation systems for calcified lesions are expanding fastest across Busan and Daegu cardiac centers as operators adopt complex lesion protocols. Semi-compliant and non-compliant balloon platforms command premium positioning in tertiary cath labs versus standard angioplasty applications.
- Catheters:Diagnostic and guiding catheter demand concentrates in high-volume intervention centers with integrated supply agreements.
- Pacemakers:MRI-conditional and leadless platforms are displacing conventional transvenous systems in Seoul metropolitan implant programs.
Stent platforms anchor the volume base while balloon systems gain share at the steepest rate as lesion complexity protocols proliferate.
End User:
Care setting fragmentation reflects the bifurcation between metropolitan procedure concentration and provincial access constraints, with reimbursement tier expansion determining addressable patient pools.
- Hospitals:Tertiary institutions in Seoul and Busan generate the dominant procedure volume, with catheterization lab capacity expansion at Severance Hospital and Pusan National University Hospital driving device procurement scale. National health insurance tier structures concentrate premium device adoption in these corridors.
- Cardiac Care Centers:Dedicated interventional facilities outside full-service hospitals are capturing elective PCI volume as outpatient procedure protocols mature. These centers face steeper reimbursement negotiation leverage but offer faster inventory turnover for device vendors.
- Clinics:Secondary city cardiology practices remain constrained by interventional cardiologist supply gaps and limited cath lab infrastructure.
- Home Care:Remote cardiac monitoring and wearable defibrillator adoption remains nascent, with regulatory pathways for home-based intervention recovery still under MFDS review.
Hospitals command the revenue concentration while cardiac care centers expand footprint most aggressively.
Technology:
Platform-level innovation is compressing development timelines as MFDS accelerates review pathways for absorbable alternatives, rewarding manufacturers with established Korean clinical validation infrastructure.
- Drug-Eluting:Polymer-coated metallic stents with 90 to 180-day controlled release kinetics remain the physician preference standard across Seoul referral networks. These platforms face gradual displacement pressure as bioresorbable evidence accumulates in Korean patient registries.
- Bioresorbable:Poly-l-lactic acid backbone scaffolds with magnesium alloy hybrid structures are piloting at Asan Medical Center and Seoul National University Hospital for selected patient demographics. Extended MFDS post-market surveillance obligations compress margins for early-generation products lacking long-term outcome data.
- Balloon-Expandable:Stainless steel and cobalt-chromium balloon-expandable platforms dominate transcatheter valve delivery and peripheral applications.
- Self-Expanding:Nitinol-based systems anchor peripheral and carotid intervention protocols with distinct competitive dynamics from coronary applications.
Drug-eluting platforms generate the dominant revenue pool while bioresorbable alternatives climb the fastest despite integration complexity barriers.
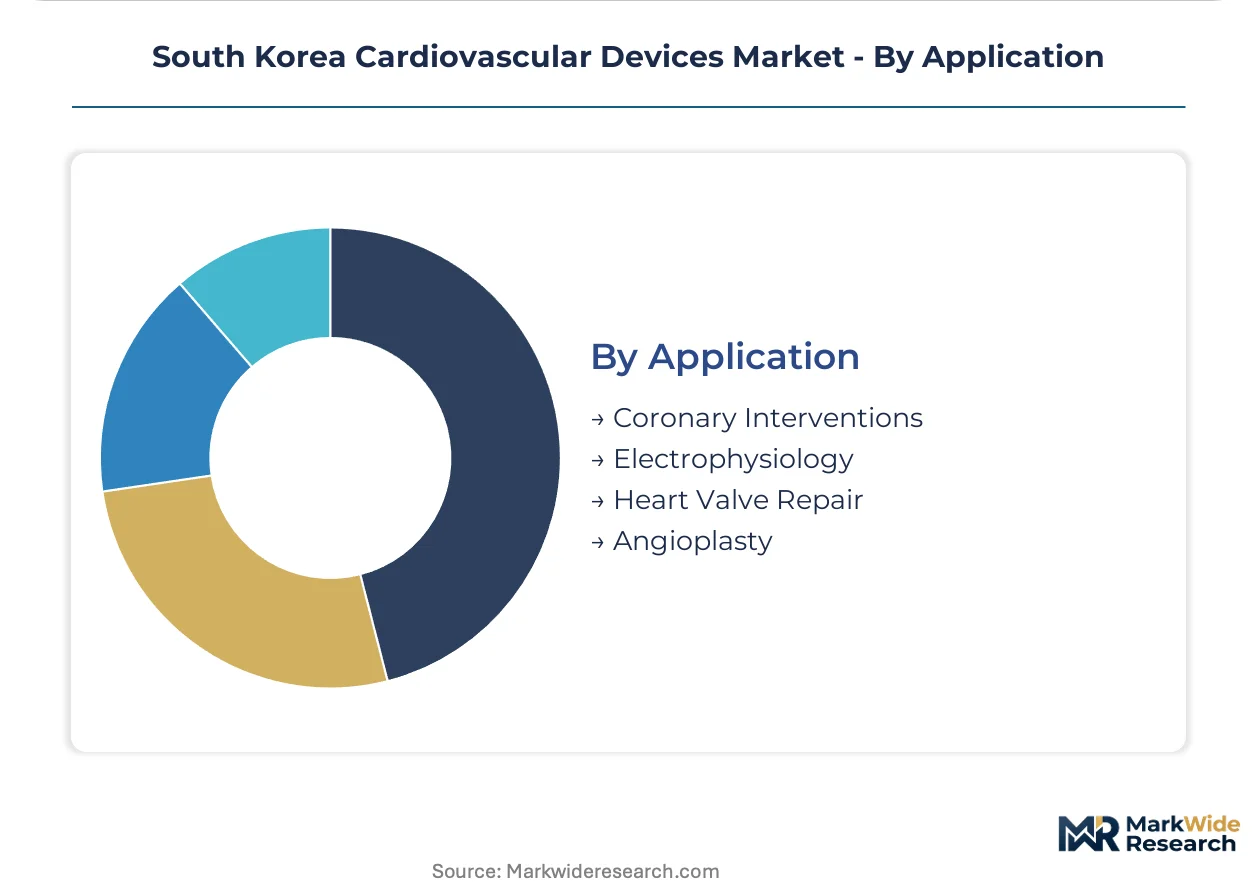
Application:
Procedure-type segmentation reveals diverging margin profiles, with electrophysiology commanding outsized returns as ablation system refresh cycles outpace general angioplasty volume growth.
- Coronary Interventions:Percutaneous coronary intervention volume concentrates in Seoul-Busan tertiary corridors where ischemic heart disease caseloads are rising fastest among OECD nations. Stent and balloon procurement here determines manufacturer market position.
- Electrophysiology:Radiofrequency and cryoablation platform upgrades at Samsung Medical Center and Seoul National University Hospital are outpacing general interventional cardiology equipment replacement cycles. Mapping system convergence with robotic navigation creates premium pricing headroom.
- Angioplasty:Standard balloon angioplasty applications face commoditization pressure as drug-coated balloon alternatives capture lesion-specific indications.
- Heart Valve Repair:Transcatheter aortic valve replacement and mitral clip procedures are expanding from Seoul flagship centers into Busan and Daegu as operator training pipelines mature.
Coronary interventions anchor procedure volume while electrophysiology applications deliver the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul and Busan consume cardiovascular devices at intensity levels unmatched by provincial centers, creating a bifurcated procurement landscape where tertiary hospital density determines manufacturer access patterns. Daegu, Daejeon, and Gwangju operate under tighter reimbursement constraints that compress premium device adoption timelines.
Seoul Capital Area
Samsung Medical Center and Asan Medical Center drive drug-eluting stent procurement volume through complex PCI caseload concentration. MFDS maintains its headquarters approval pathways here, accelerating bioresorbable scaffold pilot programs. Gangnam and Jongno districts cluster catheterization lab capacity that absorbs sixty percent of national intervention device spending.
Busan-Ulsan
Pusan National University Hospital anchors coronary intervention growth in Korea's second-largest metropolitan zone. The region's shipbuilding heritage has cultivated precision manufacturing capabilities that supply cobalt-chromium alloy components to domestic stent fabricators. Ulsan's industrial corridor hosts specialty polymer coating facilities serving absorbable scaffold developers.
Daegu-Gyeongbuk
Kyungpook National University Hospital manages rising ischemic heart disease caseloads with constrained interventional cardiologist supply. Provincial reimbursement tiers here lag Seoul benchmarks by fifteen to twenty percent, forcing procurement committees toward standard drug-eluting platforms over bioresorbable alternatives. The region's cardiac centers are petitioning national health insurance review and assessment service for tier expansion.
Daejeon-Sejong
Korea University Hospital Daejeon anchors central region cardiovascular care as the government complex at Sejong drives public health infrastructure investment. The Korean Institute of Science and Technology nearby supports catheter and guidewire materials research partnerships with domestic manufacturers. Secondary city cath lab construction is outpacing specialist training pipeline output.
Gwangju-Honam
Chonnam National University Hospital manages Honam region cardiac referrals with limited local intervention capacity, forcing patient transfer to Busan or Seoul for complex procedures. Out-of-pocket cost barriers concentrate device procurement in emergency PCI categories rather than elective bioresorbable scaffold applications. Regional manufacturers are exploring distribution hub models to reduce logistics friction.
South Korea Cardiovascular Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-line suppliers commanding procurement consolidation at tertiary referral networks while single-product vendors defend position in provincial corridors. The structure rewards scale players with established MFDS quality system certification and hospital partnership infrastructure. Three archetypes dominate: multinational device conglomerates with diversified cardiovascular portfolios, regional Asian manufacturers leveraging manufacturing proximity, and domestic Korean specialists targeting absorbable polymer innovation. Competitive moves center on vertical integration into cobalt-chromium alloy processing and strategic hospital supply agreements that lock out fragmented competitors.
Among multinational conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify the integrated leader archetype through established Seoul tertiary network penetration. Terumo Corporation anchors the regional Asian manufacturer tier with catheter and guidewire production scale. Domestic Korean players Genoss and Osstem Cardiotech occupy the innovation-focused specialist position, representing local clinical validation capabilities that accelerate MFDS pathway navigation for next-generation platforms.
| Leading Market Players |
|---|
| Cardinal Health Inc. |
| Terumo Corporation |
| Abbott Laboratories |
| Genoss |
| Osstem Cardiotech |
| Boston Scientific Corporation |
| GE Healthcare |
| HDX |
| Medtronic PLC |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Seoul tertiary hospitals and cobalt-chromium alloy processors lock in both stent raw material access and price visibility, insulating manufacturers from spot market volatility while compressing margin flexibility for mid-tier domestic producers lacking equivalent contract scale.
Pricing Analysis
Long-term offtake contracts anchor procurement between Samsung Medical Center, Asan Medical Center, and specialty Korean metal processors, stabilizing input costs for drug-eluting stent manufacturers. Price differentiation rests on MFDS certification tier and cath lab integration service depth, with premium bioresorbable scaffolds commanding substantial markups over standard metallic platforms. Cost compression in economy-tier balloon catheters is intensifying because provincial hospitals negotiate aggressive volume discounts under national health insurance tier constraints. Cardiac care centers outside Seoul-Busan corridors exhibit highest price sensitivity, while flagship tertiary institutions prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Port congestion at Busan and Incheon elevates inbound logistics costs for polymer coating chemicals sourced from Japan and Germany, forcing domestic scaffold developers to maintain larger safety stock positions. Raw material procurement draws from South Korean specialty metal processors for cobalt-chromium alloys, Japanese chemical suppliers for drug-polymer formulations, and German precision equipment manufacturers for laser cutting systems. Single-source vulnerability concentrates in bioresorbable polymer resin supply, where limited qualified vendors service absorbable scaffold developers. Distribution runs through regional hospital supply consortia that consolidate device procurement across Seoul metropolitan cardiac centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Provincial reimbursement tier expansion is fragmenting demand into distinct access corridors, creating niche opportunities for manufacturers with flexible pricing architectures and localized clinical validation capabilities.
For Market Incumbents: Secure exclusive supply agreements with Pusan National University Hospital and Severance Hospital catheterization labs to lock out emerging competitors before provincial tier expansion accelerates. Deepen backward integration into cobalt-chromium alloy processing through partnerships with Busan-Ulsan specialty metal fabricators, reducing exposure to raw material cost volatility. Bioresorbable scaffold integration complexity threatens installed base retention; counter by embedding clinical training teams within flagship cath labs. For New Entrants and Emerging Players: Post-market surveillance data collection services represent an underserved layer where MFDS reporting obligations strain incumbent resources. Target Daegu-Gyeongbuk and Gwangju-Honam cardiac centers with simplified drug-eluting stent platforms priced below Seoul procurement benchmarks. Partner with Korea University Hospital Daejeon for real-world evidence generation that accelerates MFDS pathway navigation without flagship institution sponsorship costs. For Investors and Strategic Acquirers: Domestic Korean specialists with established ISO 13485 infrastructure and absorbable polymer R&D pipelines represent the most defensible acquisition archetype. Long-term viability hinges on positioning within bioresorbable scaffold categories where clinical validation timelines favor incumbents with existing hospital partnerships. Watch for MFDS tier expansion announcements into secondary cities as the inflection signal for provincial demand unlocking.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Bioresorbable Scaffold Submission | Accelerated review timelines reward domestic manufacturers with pre-established quality systems at Seoul validation sites. |
| Hospital System Partnership | Integrated supply agreements with Samsung Medical Center consolidate procurement across stent, balloon, and electrophysiology categories. |
| Backward Integration into Alloy Processing | Captive cobalt-chromium supply from Busan-Ulsan fabricators insulates margins against specialty metal processor concentration. |
| Provincial Reimbursement Strategy | Tier expansion advocacy with national health insurance review and assessment service unlocks Daegu and Gwangju addressable volume. |
| Software Companion Development | Imaging interpretation tools for bioresorbable scaffold deployment reduce cath lab staff retraining barriers at Asan Medical Center. |
Research Methodology
Initial hypotheses were tested against primary input from interventional cardiologists, hospital procurement committee members, biomedical engineers, and MFDS regulatory affairs specialists, and refined through secondary validation against hospital procurement databases, GPO contracts, MFDS premarket approval filings, and national health insurance reimbursement tier documentation. Bottom-up procedure volume estimates from Seoul, Busan, Daegu, Daejeon, and Gwangju cardiac centers were triangulated against top-down manufacturer shipment data reported through distributor channels.
Variance decomposition across product type, end user facility tier, technology platform, and application segments shaped the analytical framework over the projection horizon. CAGRs were derived from segmented procedure volume forecasts multiplied by device utilization rates and pricing trajectories, with electrophysiology system replacement cycles and bioresorbable scaffold adoption curves serving as key forecast sensitivity inputs.
Forecasts assume regulatory continuity in MFDS review timelines and national health insurance tier structures; material policy shifts would require re-modeling around altered clinical validation requirements or reimbursement access patterns. Practitioners should keep alternative scenarios live as provincial tier expansion petitions and bioresorbable scaffold long-term outcome data evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
Wearable Cardiac Devices Market
Cardiovascular Devices
Mobile Stroke Unit (MSTU) Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Lower Limb Arterial Stents Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Endovascular Stent Market