
 Allergy Care Market | 2026-2036
Allergy Care Market Size, Share, and Industry Trends Forecast 2026-2036
Allergy Care Market Analysis
Germany is rewriting the competitive map for sublingual immunotherapy manufacturing with new GMP-certified production campuses in the Rhine-Main region. Sanofi leverages its vertically integrated allergen extraction capabilities to secure raw material supply chains. GSK plc anchors European regulatory submissions with dedicated EMA liaison teams in London. Bayer competes through OTC antihistamine brand strength in pharmacy channels across German-speaking markets.
Allergy care encompasses diagnostic, therapeutic, and preventive interventions targeting hypersensitive immune responses, including IgE-mediated reactions quantified by specific allergen concentrations measured in kU/L and formulated as standardized extracts or recombinant proteins for desensitization protocols. The field serves clinical immunologists, primary care physicians, and self-managing consumers seeking symptom control or disease modification. Antihistamines dominate current prescription volumes as the established first-line symptomatic category, while allergy shots command premium pricing due to multi-year treatment protocols and specialist administration requirements. Nasal sprays capture growing share among seasonal allergy sufferers seeking rapid onset without systemic exposure, particularly in markets where direct pharmacy access expands.
The FDA governs biologics licensing for novel immunotherapies through BLA pathways with mandatory REMS programs, while the EMA enforces MDR compliance for companion diagnostic devices used in allergen-specific IgE testing. REACH restrictions on chemical preservatives in multidose formulations push manufacturers toward single-use vial formats, altering packaging economics. Stakeholders must monitor evolving pharmacovigilance mandates and allergen standardization protocols to preserve market access and reimbursement positioning.
Market Dynamics
Pediatric immunotherapy programs in hospital outpatient departments are expanding uptake across the allergy care landscape, reshaping how desensitization protocols reach younger patient populations and altering referral patterns between primary care and specialist networks.
Growth Catalysts
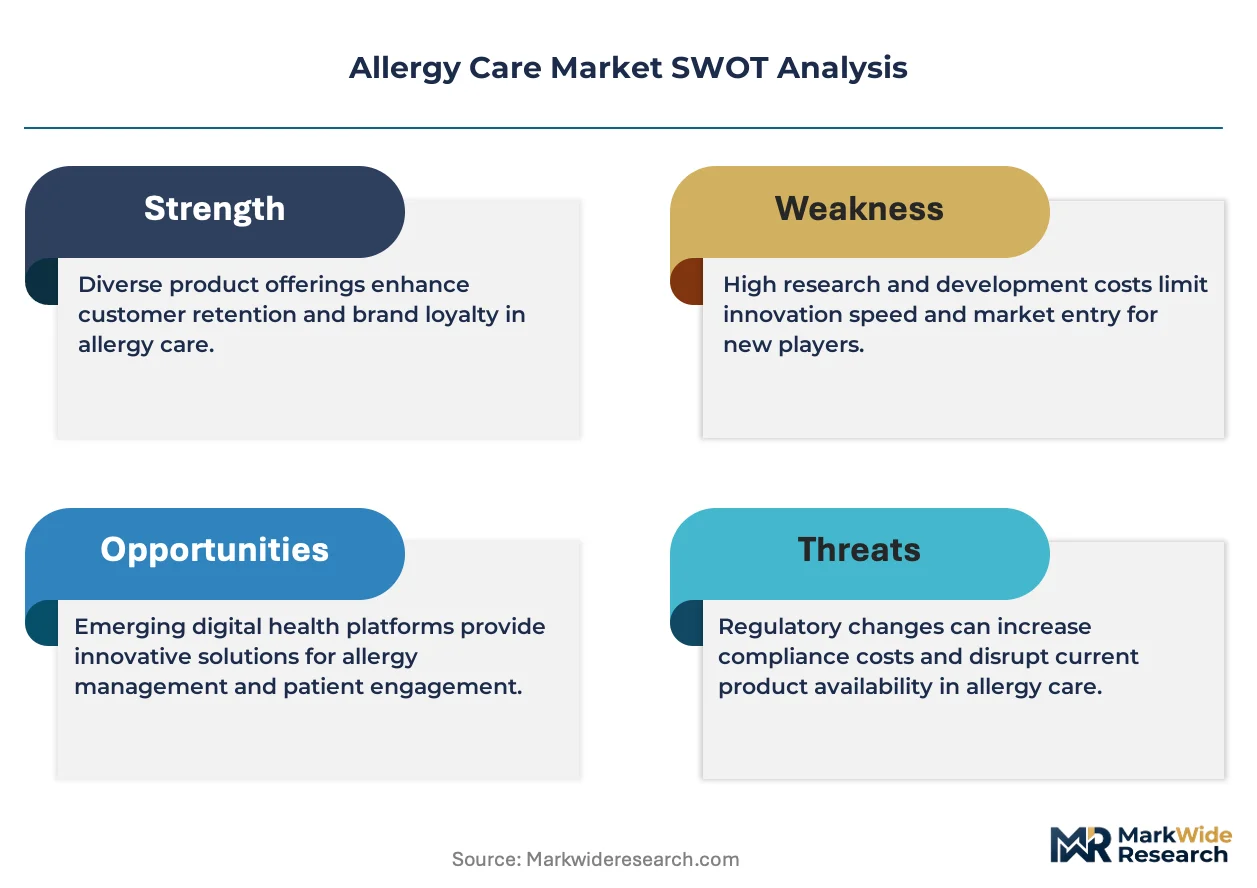
- EMA Pharmacovigilance Mandates:Tightened requirements for biologic allergy treatments are forcing manufacturers to invest in robust safety monitoring infrastructure, elevating clinical data quality and physician confidence in novel immunotherapies.
- Sublingual Immunotherapy Manufacturing:New GMP-certified production campuses in Germany's Rhine-Main region are expanding capacity for standardized allergen extracts, reducing supply bottlenecks for European markets.
- Direct-to-Consumer Diagnostics:Self-administered IgE testing kits are bypassing traditional laboratory channels, accelerating patient identification and treatment initiation timelines in the United States.
Market Restraints
- Multi-Year Treatment Economics:Allergy shot protocols require sustained specialist administration and patient compliance, compressing reimbursement margins and limiting accessibility in cost-constrained healthcare systems.
- Allergen Extraction Concentration:Raw material supply chains for standardized extracts depend on a narrow base of specialized extraction facilities, creating vulnerability to climatic variability and crop yield fluctuations.
- REMS Program Burden:FDA-mandated Risk Evaluation and Mitigation Strategies for novel biologics impose distribution restrictions and prescriber certification requirements that slow commercial rollout.
Strategic Opportunities
- Pharmacy Channel Expansion:Direct pharmacy access for nasal sprays and OTC antihistamines is capturing seasonal allergy sufferers seeking rapid symptom relief without physician visits.
- Companion Diagnostic Integration:Allergen-specific IgE testing devices aligned with MDR compliance are enabling precision-matched immunotherapy selection, improving treatment outcomes and protocol adherence.
- Recombinant Protein Formulation:Engineered allergen proteins are reducing batch-to-batch variability inherent in natural extracts, opening pathways for modified immunotherapy protocols with shorter induction phases.
Industry Challenges
- Specialist Workforce Scarcity:Clinical immunologist training programs are failing to match rising patient volumes, extending appointment wait times and delaying treatment initiation for complex cases.
- Legacy System Integration:Electronic health record fragmentation between primary care, specialist practices, and hospital outpatient departments is disrupting care coordination for multi-year immunotherapy tracking.
- Preservation Chemistry Constraints:REACH restrictions on chemical preservatives in multidose vials are forcing rapid packaging format transitions, straining manufacturing line flexibility and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allergy Care Market |
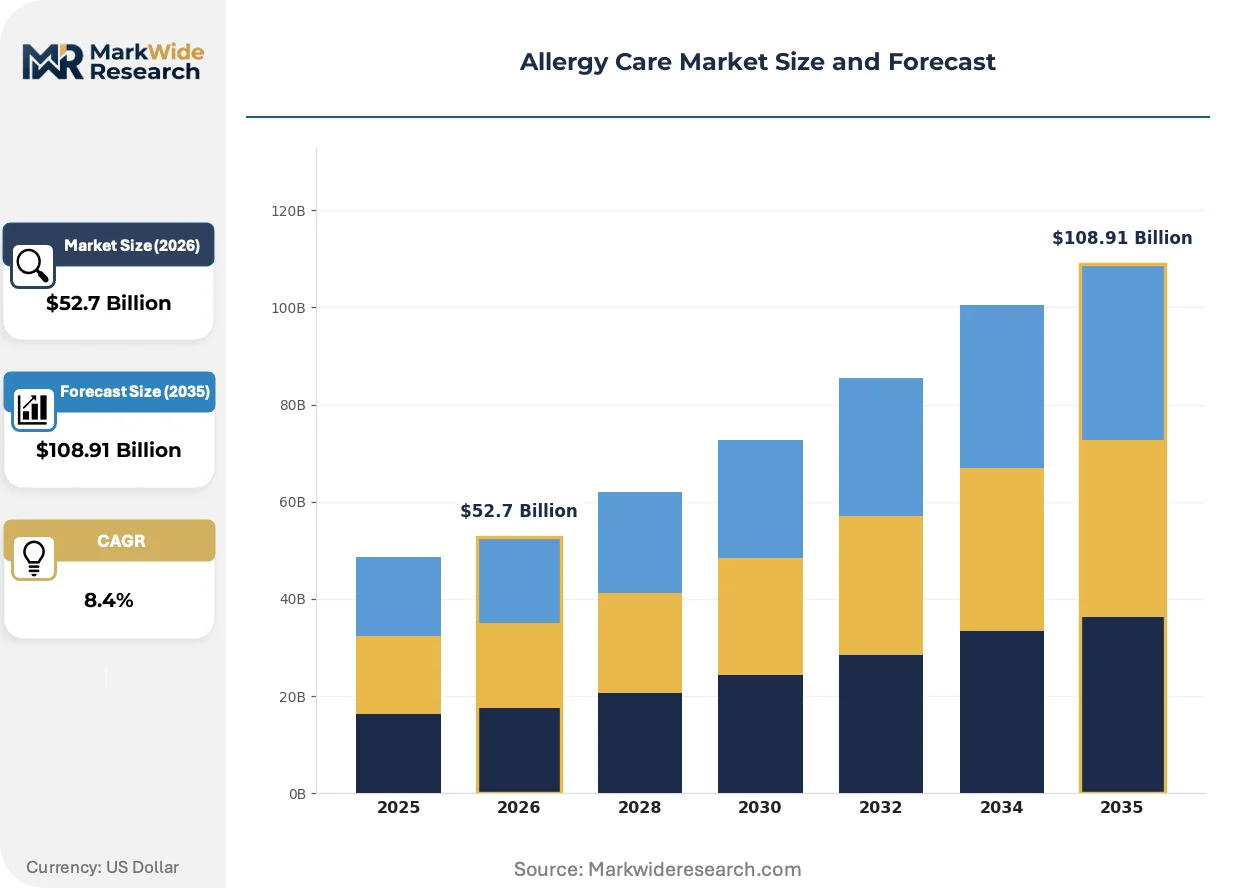
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Nasal Sprays, Allergy Shots, Eye Drops Application: Food Allergies, Environmental Allergies, Drug Allergies, Seasonal Allergies End User: Adults, Children, Elderly, Patients Delivery Mode: Oral, Topical, Injectable, Inhalation |
| Companies Covered | Sanofi, GSK plc, Johnson & Johnson, Novartis, ALK-Abelló, STALLergenes Greer, Bayer, Haleon, Allergy Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allergy Care Market Emerging Trajectories
Digital health infrastructure is virtualizing patient monitoring and protocol adherence tracking, compressing the traditional in-clinic model and enabling remote dose escalation supervision.
Artificial intelligence-driven symptom prediction algorithms are virtualizing the diagnostic pathway for seasonal allergy sufferers. Mobile health platforms incorporating pollen forecasting and medication reminders are capturing patient engagement among tech-enabled demographics. This virtualization is compressing the interval between symptom onset and therapeutic intervention, reducing acute care utilization.
REACH regulations on chemical preservatives are forcing multidose-to-single-use vial transitions across European manufacturing. Packaging economics are shifting toward higher per-unit costs offset by reduced pharmacovigilance liability and simplified cold chain requirements. German and Swiss manufacturers are responding fastest, leveraging existing aseptic fill-finish capabilities.
Self-managing consumers are unbundling after-sales clinical support from product purchase, demanding standalone digital coaching tools and peer community access. Pharmacy channels in German-speaking markets are capturing this preference through staffed consultation counters and subscription-based adherence programs. The United States lags in formalizing this channel role, though direct-to-consumer brands are filling the gap.
Allergy Care Market Segmentation
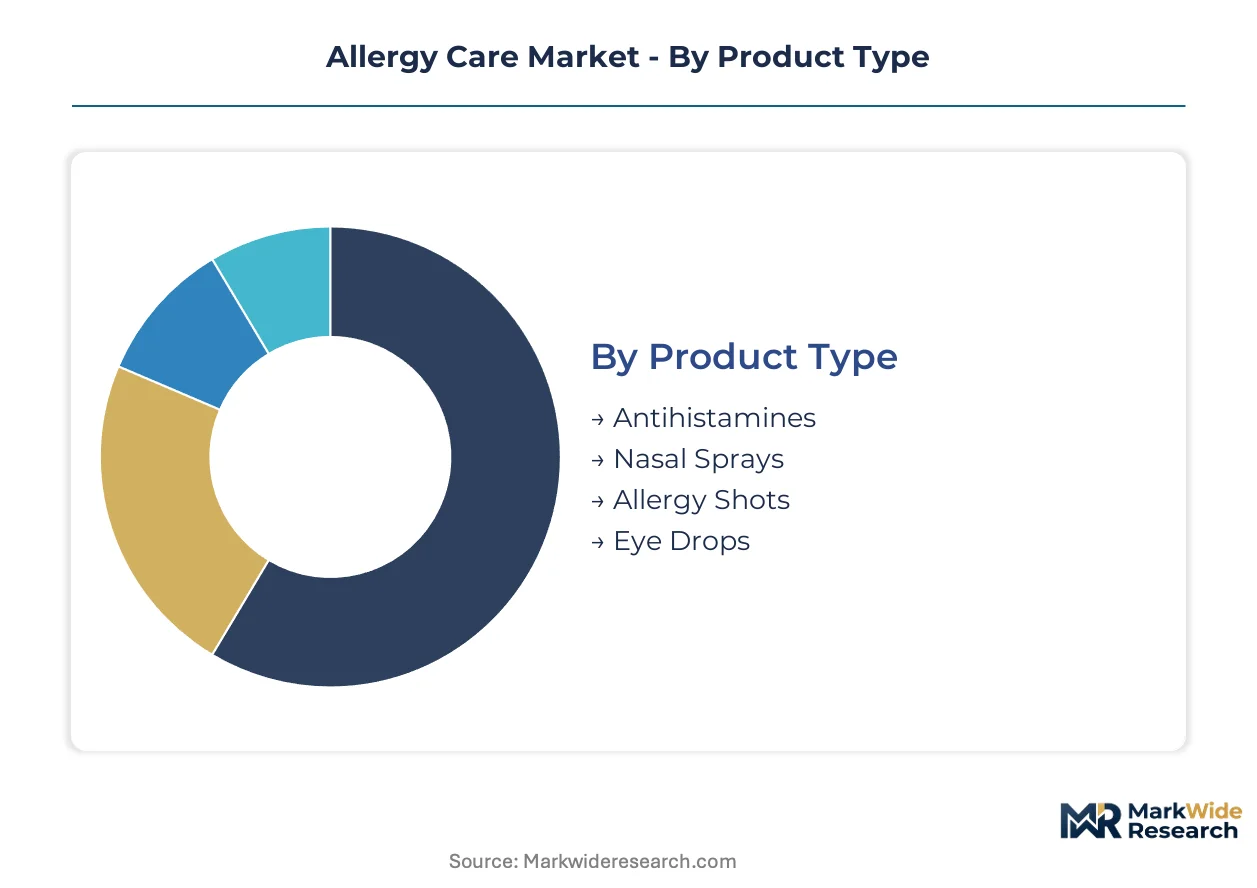
Allergy care segmentation reveals divergent margin structures across symptomatic relief versus disease-modifying interventions. Product form and patient life stage determine reimbursement pathways, regulatory classification, and channel access.
Product Type:
Mature oral formulations coexist with emerging biologic delivery systems, creating a bifurcated competitive landscape between commodity generics and premium immunotherapy.
- Antihistamines:First-generation and second-generation H1 receptor antagonists formulated as tablets, capsules, and liquids for systemic histamine blockade. Demand concentrates in United States pharmacy channels where direct-to-consumer brands bypass prescription requirements for seasonal symptom management.
- Nasal Sprays:Intranasal corticosteroids and antihistamine sprays delivering localized mucosal anti-inflammatory action with rapid onset. United States seasonal allergy sufferers drive volume through pharmacy access expansion, favoring convenience over specialist consultation.
- Allergy Shots:Subcutaneous immunotherapy protocols using standardized allergen extracts or recombinant proteins for multi-year desensitization. Specialist allergist networks in Germany and Switzerland administer the majority of European protocols.
- Eye Drops:Topical antihistamine and mast cell stabilizer formulations for ocular surface symptom relief. Self-managing consumers in German-speaking markets purchase through staffed pharmacy consultation counters.
Antihistamines retain volume leadership; nasal sprays hold the steepest expansion curve.
Application:
Cost tier stratification separates acute symptomatic management from chronic disease modification protocols.
- Food Allergies:IgE-mediated hypersensitivity reactions requiring strict avoidance and emergency epinephrine preparedness. Pediatric immunotherapy programs in United States hospital outpatient departments are expanding oral immunotherapy protocols.
- Environmental Allergies:Perennial and seasonal responses to indoor and outdoor allergens including dust mites, pet dander, and pollen. German sublingual immunotherapy manufacturing capacity serves European demand for standardized extracts.
- Drug Allergies:Hypersensitivity reactions to pharmaceutical compounds necessitating alternative therapeutic selection. Companion diagnostic integration enables precision-matched immunotherapy selection in Swiss clinical settings.
- Seasonal Allergies:Intermittent rhinitis and conjunctivitis triggered by temporal pollen exposure patterns. Mobile health platforms with pollen forecasting capture patient engagement among United States tech-enabled demographics.
Environmental allergies command the largest addressable population; food allergies are climbing the fastest regulatory investment curve.
End User:
Volume concentration shifts toward younger demographics as pediatric immunotherapy protocols reshape referral patterns.
- Adults:Working-age patients managing chronic or intermittent symptoms through self-directed pharmacy purchases. United States direct-to-consumer diagnostic kits accelerate treatment initiation timelines.
- Children:Pediatric populations requiring weight-based dosing and specialist-supervised desensitization protocols. Hospital outpatient departments in Germany and the United States are expanding dedicated immunotherapy programs.
- Elderly:Aging patients with polypharmacy considerations and comorbid respiratory conditions. Swissmedic and FDA pharmacovigilance mandates elevate safety monitoring requirements for this cohort.
- Patients:Broad clinical designation encompassing diagnosed allergy sufferers across age spectrums. Electronic health record fragmentation disrupts care coordination for multi-year immunotherapy tracking.
Adults retain volume leadership; children hold the steepest expansion curve.
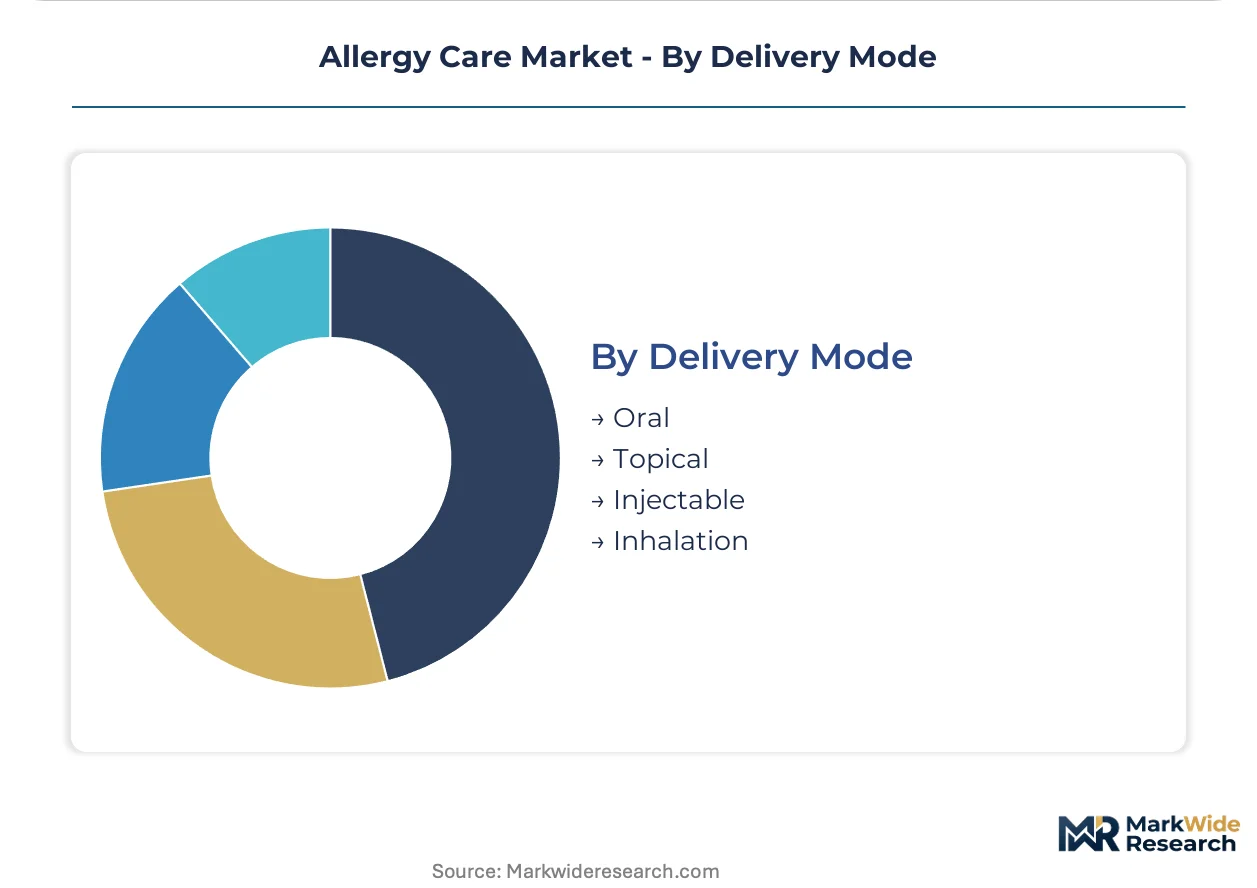
Delivery Mode:
Supply concentration in aseptic fill-finish capabilities favors formats compatible with preservative-free packaging transitions.
- Oral:Tablets, capsules, and liquids for systemic drug absorption and histamine receptor blockade. Antihistamines dominate prescription volumes as the established first-line category.
- Topical:Cutaneous and mucosal applications including nasal sprays, eye drops, and dermal preparations. REACH restrictions on chemical preservatives push manufacturers toward single-use vial formats.
- Injectable:Subcutaneous and intramuscular administration for immunotherapy and emergency epinephrine delivery. FDA-mandated REMS programs impose distribution restrictions on novel biologic allergy treatments.
- Inhalation:Pulmonary delivery systems for corticosteroids and bronchodilators in allergic asthma management. EMA MDR compliance requirements apply to companion diagnostic devices used in allergen-specific testing.
Oral delivery retains volume leadership; injectable holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's cold chain infrastructure anchors Central European distribution for temperature-sensitive allergen extracts, while Frankfurt Airport's pharmaceutical cargo terminals expedite transatlantic biologic shipments.
United States
Specialist allergist networks and direct-to-consumer diagnostic kits drive volume concentration. FDA REMS programs impose distribution restrictions on novel biologic allergy treatments. Hospital outpatient departments in Boston and the Research Triangle are expanding pediatric immunotherapy protocols.
Germany
Sublingual immunotherapy manufacturing capacity concentrates demand for standardized extracts. EMA pharmacovigilance mandates elevate clinical data requirements for biologic treatments. GMP-certified production campuses in the Rhine-Main region are reducing supply bottlenecks for European markets.
Switzerland
Swissmedic oversight attracts premium immunotherapy developers seeking regulatory credibility. REACH restrictions on chemical preservatives are forcing multidose-to-single-use vial transitions. Basel's pharmaceutical cluster anchors allergen extraction and formulation capabilities.
United Kingdom
NHS referral patterns for allergy shots sustain specialist clinic volumes despite cost pressures. EMA liaison teams in London coordinate European regulatory submissions for biologic developers. Manchester and Birmingham hospital networks are digitizing multi-year immunotherapy tracking systems.
France
ANSM oversight of companion diagnostic devices aligns allergen-specific IgE testing with MDR compliance. Pharmacy channel expansion for nasal sprays captures seasonal allergy sufferers in Paris and Lyon. Pediatric allergist training programs in Strasbourg are addressing workforce scarcity.
Allergy Care Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in extract supply and diagnostic substrates. The vendor base organizes around three archetypes: vertically integrated pharmaceutical conglomerates, pure-play immunotherapy developers, and diagnostic-platform specialists. Consolidation pressures favor scale players with captive allergen sourcing, while niche entrants exploit pharmacy channel openings for OTC formulations. Dominant competitive moves include backward integration into raw material extraction and strategic partnerships for digital adherence platforms.
Among European-based developers, ALK-Abelló and STALLergenes Greer exemplify the pure-play immunotherapy archetype, occupying positions centered on sublingual and subcutaneous desensitization protocols. Sanofi represents the integrated conglomerate model, leveraging in-house allergen extraction capabilities to secure upstream supply control. These three anchors illustrate the strategic divergence between specialized disease-modification focus and diversified symptomatic relief portfolios.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| Johnson & Johnson |
| Novartis |
| ALK-Abelló |
| STALLergenes Greer |
| Bayer |
| Haleon |
| Allergy Therapeutics |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Rhine-Main region GMP-certified extraction facilities determines both the premium-to-economy spread in allergen immunotherapy and the geographic clustering of fill-finish manufacturing capacity. REACH-mandated preservative transitions feed back into packaging economics, compressing margins on multidose formats while rewarding aseptic single-use investments.
Pricing Analysis
Volume-discount tiering structures separate premium recombinant protein protocols from standardized extract formulations and economy antihistamine generics. Price differentiation rests on certification grade—FDA BLA versus OTC monograph pathways—and after-sales clinical support bundling. Cost compression in subcutaneous immunotherapy intensifies as hospital outpatient departments negotiate bundled reimbursement rates. Self-managing pharmacy consumers exhibit highest price sensitivity; specialist-administered biologics retain inelastic demand.
Supply Chain Analysis
Contract-manufacturing concentration among German and Swiss aseptic fill-finish specialists anchors European supply for preservative-free vial formats. Raw material sourcing draws from specialized pollen and mite cultivation facilities in Germany, Denmark, and the United States. Single-source vulnerability in allergen extraction concentration exposes formulations to climatic yield variability. Distribution runs through pharmaceutical cold chain terminals at Frankfurt Airport and the Port of Hamburg for transatlantic biologic shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as direct-to-consumer diagnostics unbundle patient identification from specialist referral channels, creating niche entry points for digital adherence platforms and pharmacy-coaching services.
For Market Incumbents: Pre-empt disintermediation by capturing raw material supply through backward integration into allergen extraction facilities in the Rhine-Main region. Secure hospital outpatient department partnerships before pediatric protocol expansion accelerates, locking in multi-year administration contracts that emerging biologic developers cannot match. For New Entrants and Emerging Players: Underpenetration in United States pharmacy-based immunotherapy coaching creates whitespace for subscription adherence platforms targeting seasonal allergy sufferers. Target direct-to-consumer diagnostic bundling with digital coaching tools, leveraging the gap between kit purchase and specialist appointment availability. For Investors and Strategic Acquirers: EMA pharmacovigilance mandate tightening reshapes the acquisition landscape toward developers with robust safety monitoring infrastructure already deployed. Prioritize pure-play immunotherapy specialists with captive allergen sourcing and MDR-compliant companion diagnostic pipelines. Quarterly tracking of FDA REMS program expansion rates signals regulatory barrier heightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Allergen Extraction | Captive supply of standardized extracts secures formulation consistency against climatic yield shocks. |
| Companion Diagnostic Development | MDR-aligned IgE testing devices enable precision-matched immunotherapy selection in European markets. |
| Pharmacy Channel Expansion | Direct access for nasal sprays captures United States seasonal sufferers seeking rapid symptom relief. |
| Pediatric Protocol Partnerships | Hospital outpatient department alliances lock in multi-year desensitization administration commitments. |
| Digital Adherence Platform Launch | Remote dose escalation supervision reduces in-clinic burden while improving protocol completion rates. |
Methodological Framework
Desk research of FDA BLA filings, EMA regulatory submissions, ClinicalTrials.gov records, and hospital procurement databases preceded structured interviews with clinical immunologists, pharmaceutical regulatory affairs leads, formulary directors, and allergy diagnostic platform engineers. Primary fieldwork with GMP facility operators and pharmacy channel managers cross-validated secondary data on manufacturing capacity and distribution economics. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Assumptions held fixed include current FDA REMS program scope, REACH preservative restriction timelines, and specialist allergist training program graduation rates; variables tested include direct-to-consumer diagnostic penetration speed and pediatric immunotherapy protocol expansion. The analytical framework modeled product type, application, end user, and delivery mode segments across the projection horizon. CAGRs derived from epidemiological allergy prevalence trends, reimbursement rate trajectories, and biologic adoption curve analysis.
Practitioners should monitor EMA pharmacovigilance mandate implementation intensity and FDA biologic approval pathway modifications for early signals of competitive barrier shifts. Quarterly review of specialist workforce scarcity indicators and cold chain logistics cost movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
North America Laboratory Information System Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Healthcare API Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Health IT Security Market
Health Informatics
Artificial Intelligence in Epidemiology Market