
 AI in Healthcare Market | 2026-2036
AI in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Healthcare Market Analytics
The gap between FDA-cleared diagnostic algorithms and unregulated wellness applications is repositioning how hospitals evaluate AI procurement. NVIDIA Corporation leverages its GPU architecture to dominate training infrastructure for medical imaging models. Microsoft Corporation anchors enterprise deployments through its Azure cloud contracts with major hospital networks. Siemens Healthineers differentiates by embedding AI directly into imaging hardware rather than selling standalone software licenses.
AI in healthcare encompasses machine learning systems, natural language processing engines, and computer vision algorithms trained on clinical datasets to augment diagnosis, treatment planning, and operational workflow. These systems typically process structured electronic health records, unstructured physician notes, and DICOM imaging files through neural network architectures validated against ground-truth clinical outcomes. Medical imaging solutions currently occupy the largest revenue pool among product types due to the high cost of hardware-software bundles and recurring maintenance contracts. Drug discovery applications within the application dimension are attracting the fastest investment growth as pharmaceutical companies seek to compress preclinical timelines. Cloud-based delivery modes are displacing on-premises installations among mid-tier hospitals that lack dedicated IT security staff.
The FDA's Software as a Medical Device framework, the EU AI Act's high-risk system classification, and HIPAA security rule enforcement collectively determine which products reach commercial deployment and which stall in regulatory review. These frameworks shape demand by forcing developers to invest in clinical validation studies and audit trails before market access. Stakeholders must monitor how divergent approval standards between jurisdictions fragment product development roadmaps and inflate compliance costs for multi-market launches.
Market Dynamics
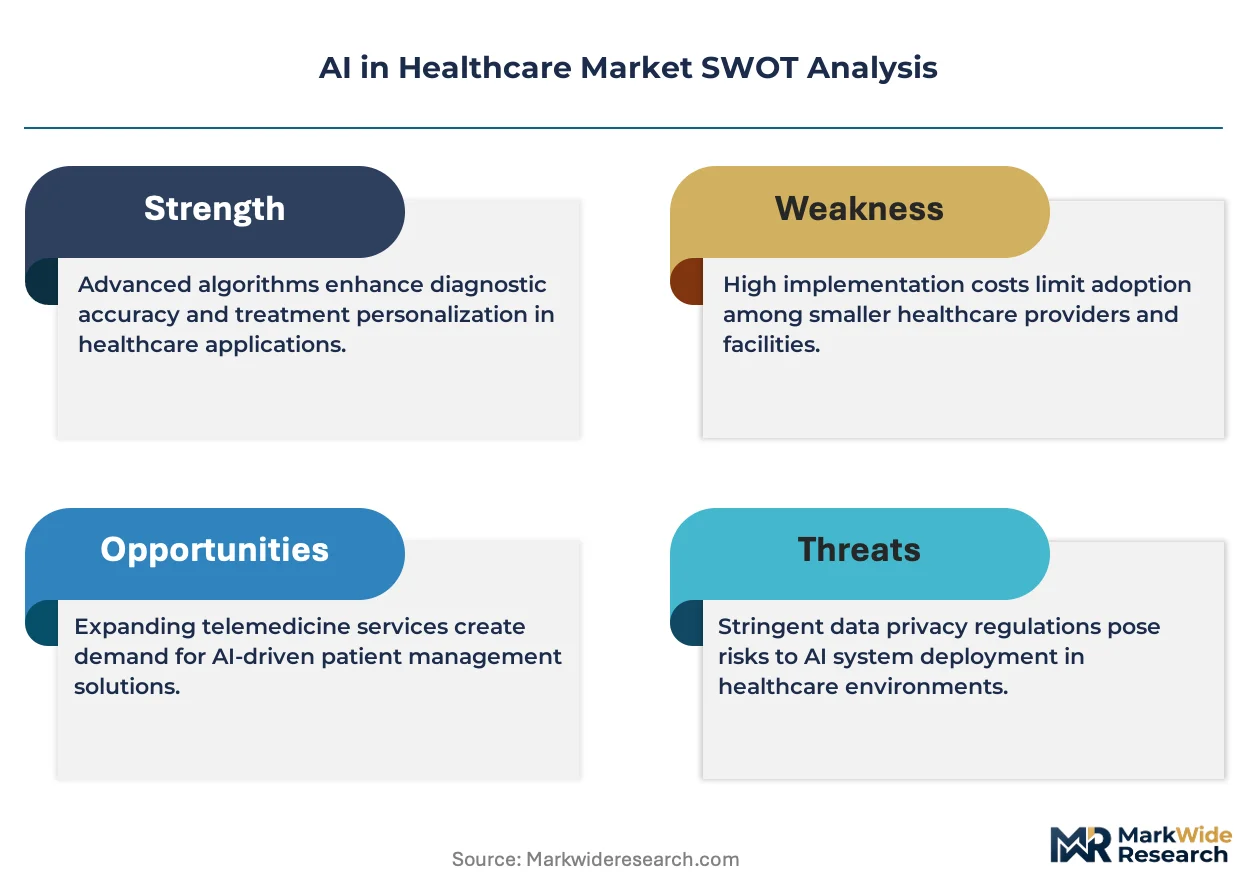
The FDA's Software as a Medical Device framework is compressing clearance timelines for machine learning algorithms while forcing developers to front-load clinical validation costs. This regulatory acceleration is bifurcating the vendor landscape between capital-rich enterprises capable of multi-year studies and resource-constrained challengers.
Growth Catalysts
- FDA SaMD Pathway:The streamlined premarket review process for AI/ML-based diagnostics is reducing time-to-market for radiology algorithms by establishing predetermined change control plans.
- Cloud Migration:Mid-tier hospital systems lacking dedicated cybersecurity staff are abandoning on-premises installations for Azure and AWS-hosted medical imaging platforms.
- Germany:The country's hospital digitization funding programs are mandating AI-readiness in radiology infrastructure procurement specifications.
Market Restraints
- GPU Supply Concentration:Training infrastructure for medical imaging models depends on NVIDIA's datacenter silicon, creating single-source vulnerability for algorithm developers.
- HIPAA Security Rule:The technical safeguard requirements for audit trails and access controls impose recurring compliance costs that disproportionately burden smaller software vendors.
- Ground-Truth Data Scarcity:Curated clinical outcome labels for rare disease populations remain concentrated at academic medical centers with restrictive licensing terms.
Strategic Opportunities
- Drug Discovery:Pharmaceutical companies are compressing preclinical timelines by applying generative models to molecular property prediction, outpacing imaging in investment velocity.
- China:National health data infrastructure investments are creating localized demand for Mandarin-language natural language processing engines trained on domestic electronic health records.
- Federated Learning:Multi-institutional model training without centralizing patient data is unifying privacy-preserving techniques with regulatory compliance across EU member states.
Industry Challenges
- Interoperability Friction:DICOM imaging archives and HL7 FHIR data standards require expensive middleware development for AI integration with legacy hospital information systems.
- Validation Timeline Compression:Prospective clinical studies for FDA clearance now demand 12-24 month follow-up periods that strain venture-funded runway constraints.
- Algorithmic Drift:Real-world performance degradation of deployed models necessitates continuous monitoring infrastructure that most health systems have not built.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Healthcare Market |
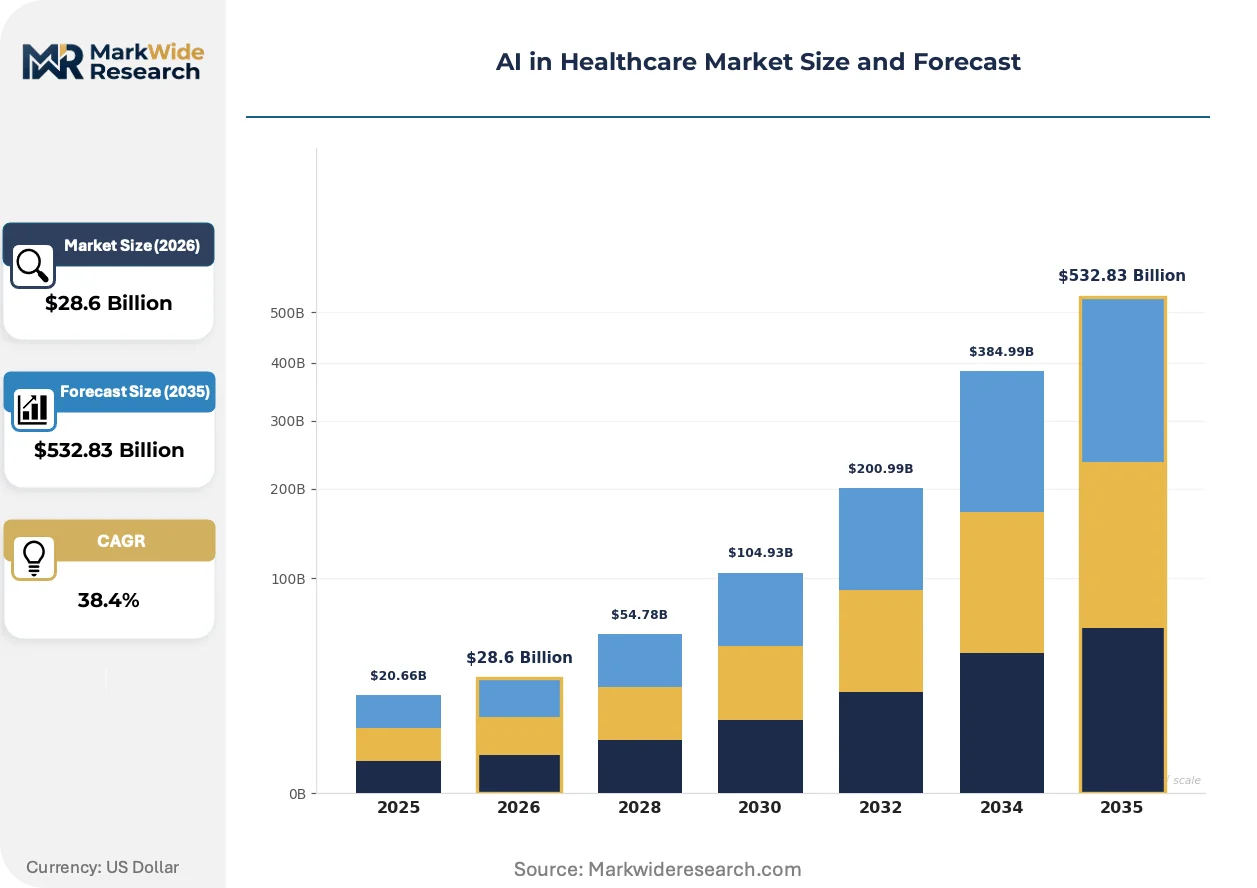
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $532.83 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Predictive Analytics, Virtual Health Assistants, Medical Imaging Solutions Application: Clinical Decision Support, Patient Monitoring, Personalized Medicine, Drug Discovery End User: Healthcare Providers, Research Institutions, Pharmaceuticals, Insurance Companies Delivery Mode: On-Premises, Cloud-Based, Hybrid Solutions, Software as a Service |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Google, IBM, Koninklijke Philips, Siemens Healthineers, GE Healthcare, Amazon Web Services, Tempus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Healthcare Market Evolving Landscape
Foundation models pretrained on multimodal clinical data are restructuring how AI capabilities reach hospital workflows. These systems reduce the labeled data requirements for downstream diagnostic tasks.
Multimodal foundation architectures are unifying computer vision, natural language processing, and structured data analysis within single neural network weights. Academic medical centers in the United States are piloting these systems for emergency department triage. The technology is compressing the traditional segmentation between radiology AI vendors and clinical decision support developers.
The EU AI Act's high-risk system classification is mandating conformity assessments for diagnostic algorithms before CE marking authorization. Medical device manufacturers must now document risk management systems and post-market monitoring protocols. Imaging AI products face the steepest compliance burden due to their direct patient impact classification.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide platform contracts rather than point solutions. Radiology departments that previously acquired standalone software licenses now favor hardware-software bundles with embedded AI from imaging equipment manufacturers. This concentration is most visible in German hospital networks undergoing regional consolidation.
AI in Healthcare Market Segmentation
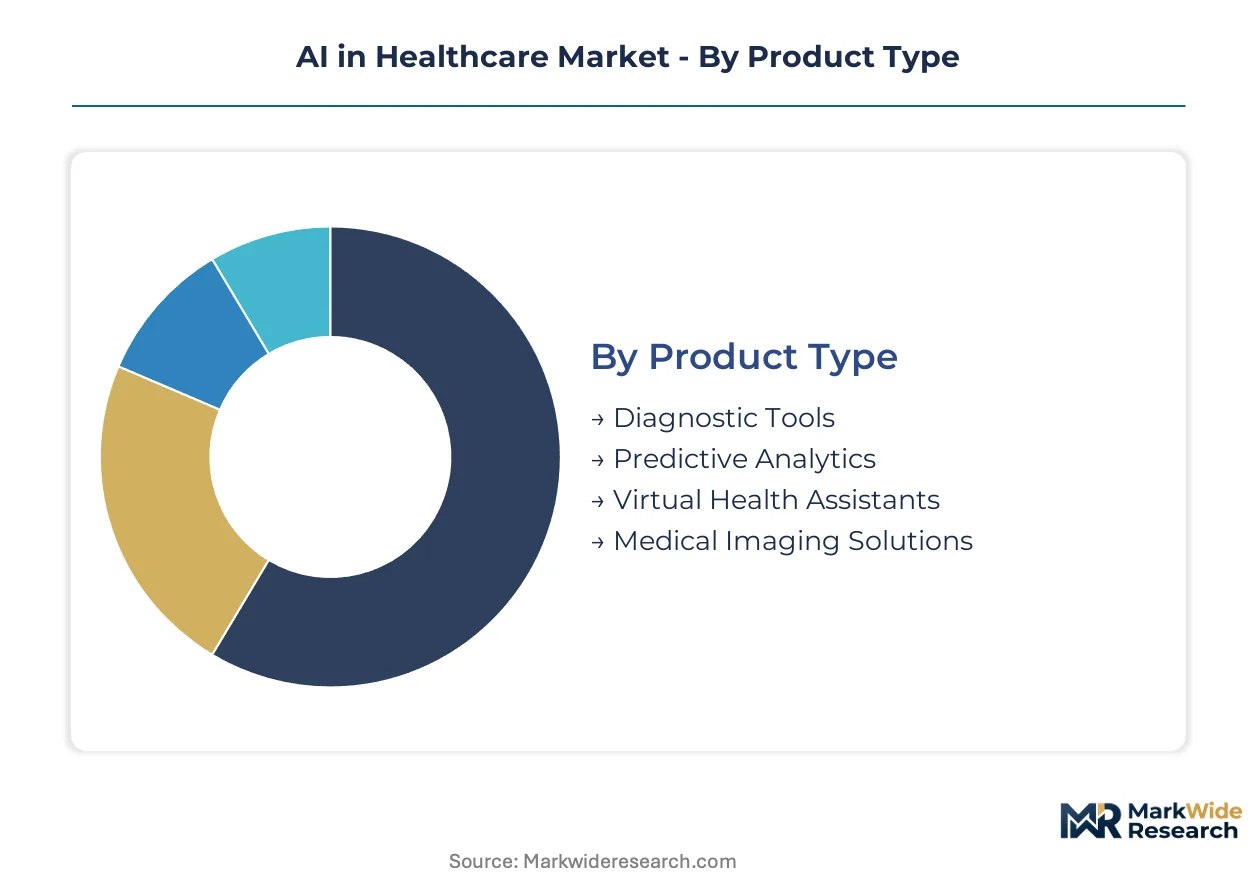
Segmentation in AI healthcare procurement reveals how purchasing committees weight regulatory clearance against integration complexity. Buyers prioritize FDA-validated diagnostic modules when capital budgets exceed operational technology spending.
Product Type:
Purchasing committees evaluate hardware-software bundles against standalone software licenses based on total cost of ownership and IT staff availability.
- Diagnostic Tools:Algorithms cleared under FDA Software as a Medical Device framework process structured EHR inputs and unstructured physician notes through neural architectures. Hospital systems in the United States concentrate procurement here, driven by radiology workflow optimization mandates and predetermined change control plans that reduce regulatory risk.
- Medical Imaging Solutions:DICOM-compatible systems embed computer vision directly into CT, MRI, and X-ray hardware rather than layering software atop existing equipment. Siemens Healthineers dominates this segment through embedded AI bundles, with German hospital digitization funding programs mandating AI-readiness in procurement specifications.
- Predictive Analytics:Machine learning models forecasting patient deterioration or readmission risk based on longitudinal EHR patterns.
- Virtual Health Assistants:Natural language processing engines automating patient intake, scheduling, and preliminary symptom triage.
Medical Imaging Solutions leads on scale; Diagnostic Tools leads on momentum.
Application:
Pharmaceutical companies allocate R&D budgets differently than hospital systems, compressing preclinical timelines through generative molecular modeling.
- Drug Discovery:Generative AI architectures predict molecular properties and optimize compound selection before wet-lab synthesis. Pharmaceutical companies in the United States and Germany concentrate investment here, driven by pressure to reduce preclinical phase duration and regulatory submission preparation costs.
- Clinical Decision Support:Systems integrating patient-specific data with evidence-based protocols to recommend treatment pathways. Academic medical centers deploy these for emergency department triage, with pilot programs testing multimodal foundation architectures that unify imaging and structured data analysis.
- Patient Monitoring:Continuous physiological signal processing for early warning of acute deterioration.
- Personalized Medicine:Genomic and phenotypic data integration for therapy selection tailored to individual patient profiles.
Clinical Decision Support dominates installed base; Drug Discovery shows steepest expansion trajectory.
End User:
IT security capabilities and data governance maturity determine which delivery contracts hospitals can execute.
- Healthcare Providers:Hospital systems and physician practices deploying AI for diagnostic augmentation and operational workflow. Mid-tier systems in the United States lacking dedicated cybersecurity staff are migrating from on-premises to Azure and AWS-hosted platforms, with HIPAA Security Rule compliance costs driving vendor consolidation.
- Pharmaceuticals:Drug manufacturers applying AI across discovery, clinical trial design, and regulatory submission preparation.
- Research Institutions:Academic medical centers training foundation models and curating ground-truth datasets for rare disease populations.
- Insurance Companies:Payers deploying predictive models for fraud detection, risk stratification, and prior authorization automation.
Healthcare Providers command largest contract volume; Pharmaceuticals expand procurement fastest.
Delivery Mode:
Cloud migration accelerates where hospital IT departments lack staff to maintain HIPAA Security Rule technical safeguards for on-premises infrastructure.
- Cloud-Based:Azure and AWS-hosted medical imaging platforms with vendor-managed security patching and audit trail maintenance. Mid-tier hospital systems in the United States concentrate here, driven by elimination of capital expenditure for server hardware and reduction of dedicated cybersecurity headcount requirements.
- Software as a Service:Subscription licensing for diagnostic algorithms with continuous model updates through predetermined change control plans. German hospital networks undergoing regional consolidation favor enterprise-wide platform contracts over point solutions.
- On-Premises:Locally installed systems retaining patient data within hospital firewall boundaries.
- Hybrid Solutions:Architectures splitting inference workloads between edge devices and cloud infrastructure.
Cloud-Based claims dominant share; Software as a Service gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data scientists and machine learning engineers concentrate in the United States, Germany, and China, anchoring the geographic distribution of AI healthcare development. Hospital digitization mandates and regulatory frameworks are diverging across these talent clusters. National health data infrastructure investments are determining which markets absorb the next wave of diagnostic algorithm deployment.
United States
FDA Software as a Medical Device clearances for radiology algorithms are accelerating hospital procurement cycles. HIPAA Security Rule enforcement is pushing mid-tier systems toward cloud-hosted platforms with vendor-managed compliance. The Boston-Cambridge corridor hosts academic medical centers curating ground-truth datasets for rare disease model training.
Germany
Hospital digitization funding programs are mandating AI-readiness in radiology infrastructure procurement specifications. The EU AI Act's high-risk system classification is imposing conformity assessment requirements before CE marking authorization. Bavaria's medical technology cluster around Munich is embedding AI directly into imaging hardware manufacturing.
China
National health data infrastructure investments are creating localized demand for Mandarin-language natural language processing engines. The National Medical Products Administration is streamlining approval pathways for diagnostic algorithms trained on domestic electronic health records. Shanghai's Pudong district is concentrating pharmaceutical AI research for molecular property prediction.
United Kingdom
NHS AI Lab procurement frameworks are standardizing evaluation criteria for clinical decision support systems. The Medicines and Healthcare products Regulatory Agency is aligning with FDA predetermined change control plans for streamlined market access. London's Golden Triangle biotech corridor is piloting multimodal foundation models for emergency department triage.
Japan
Pharmaceutical companies are deploying generative models to compress preclinical timelines for regulatory submission preparation. The Pharmaceuticals and Medical Devices Agency is establishing harmonized review standards with FDA and EMA for AI-based diagnostics. Tokyo's Koto ward is concentrating medical imaging AI development for integration into existing PACS infrastructure.
AI in Healthcare Market Competitive Landscape
Top-tier vendors anchor cloud infrastructure and hardware-software bundles, while specialized algorithm developers occupy mid-market niches. The vendor landscape bifurcates between capital-rich enterprises capable of multi-year clinical validation studies and resource-constrained challengers dependent on federated learning partnerships. Three strategic archetypes dominate: GPU architecture providers, cloud platform operators, and embedded imaging hardware manufacturers. Competitive moves center on enterprise-wide platform contracts replacing point solutions and regional hospital network consolidation driving vendor selection.
Within the cloud platform archetype, Microsoft Corporation and Amazon Web Services exemplify the infrastructure-as-a-service model penetrating mid-tier hospital systems. NVIDIA Corporation anchors the training infrastructure tier for medical imaging model development. Siemens Healthineers occupies a position representing embedded AI hardware-software bundles favored by German hospital digitization programs. These three entities collectively illustrate the strategic tension between standalone software licensing and integrated system procurement reshaping vendor relationships.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| IBM |
| Koninklijke Philips |
| Siemens Healthineers |
| GE Healthcare |
| Amazon Web Services |
| Tempus |
| Others |
Value Network & Pricing Analysis
Foundation model pretraining on multimodal clinical data is compressing development costs for algorithm developers while concentrating GPU procurement power among hyperscaler-backed vendors. This technology shift simultaneously reduces marginal training expenses and reinforces single-source dependency on NVIDIA's datacenter silicon.
Pricing Analysis
Bundled hardware-software offerings from Siemens Healthineers and GE Healthcare command premium positioning against standalone software licenses from emerging algorithm developers. Price differentiation rests on FDA clearance tier and embedded AI integration depth, with cloud-hosted SaaS tiers facing margin compression from Azure and AWS volume discounts. Hospital procurement committees exhibit highest price sensitivity in mid-tier systems lacking dedicated IT security staff, while academic medical centers prioritize validation rigor over cost.
Supply Chain Analysis
China's national health data infrastructure mandates and Germany's hospital digitization funding programs are reshaping sourcing patterns toward localized AI development. Training infrastructure draws from NVIDIA's US-based silicon fabrication, Taiwan's semiconductor packaging, and South Korea's memory component supply. Single-source vulnerability in GPU datacenter chips creates structural risk for algorithm developers dependent on NVIDIA's release cycles. Distribution runs through direct enterprise contracts with hospital networks and GPO-negotiated platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France exceed FDA SaMD pathway expenses in the United States, creating divergent investment returns across regulatory jurisdictions.
For Market Incumbents: Hedge against algorithmic commoditization by embedding AI directly into imaging hardware rather than licensing standalone software, and secure predetermined change control plans with FDA to accelerate model update cycles. NVIDIA's dominance in training silicon threatens margin compression for cloud platform operators lacking captive GPU supply. For New Entrants and Emerging Players: Enter via federated learning partnerships with EU academic medical centers seeking privacy-preserving multi-institutional training without centralized data pooling. Drug discovery applications for pharmaceutical companies represent the most penetrable white-space segment, outpacing imaging in investment velocity. Position around Mandarin-language NLP engines for China's hospital digitization mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among resource-constrained algorithm developers dependent on federated learning partnerships rather than proprietary ground-truth datasets. Long-term viability favors vendors with FDA-cleared diagnostic modules and embedded hardware-software bundles over standalone SaaS licensing models. Monitor FDA SaMD clearance velocity as the primary inflection signal for hospital procurement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predetermined Change Control Plans | FDA SaMD pathway acceleration reduces time-to-market for radiology algorithm updates. |
| Hospital System Partnership | Enterprise-wide Azure contracts displace point solutions in mid-tier US systems. |
| Embedded AI Hardware Integration | Siemens Healthineers bundles differentiate against standalone software licensing models. |
| CE Marking Pathway | EU AI Act high-risk classification mandates conformity assessments for diagnostic algorithms. |
| Reimbursement Strategy | CPT code establishment for AI-assisted diagnosis unlocks sustainable hospital budget allocation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and pharmaceutical R&D directors with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA medical device registrations. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across deployment modes.
Comparable-period anchoring linked projection assumptions to historical FDA clearance timelines and cloud migration patterns in mid-tier hospital systems. Segmentation dimensions spanned product type, application, end user, and delivery mode across the modeling period. CAGRs were derived from weighted regression of adoption curves against regulatory milestone acceleration, with inputs from pharmaceutical preclinical timeline compression and radiology workflow optimization mandates.
Inputs from hospital procurement databases and regulatory filing records were available through the study window; gaps in rare disease ground-truth dataset licensing terms introduce uncertainty bands around drug discovery segment projections. Forecasts reflect assumptions about FDA SaMD pathway continuity and EU AI Act implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Healthcare Integration Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Global Ambulatory EHR Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
High Acuity Information Systems Market