
 Implantable Port Devices Market | 2026-2036
Implantable Port Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Port Devices Market Analytics
Aftermarket service revenue is fragmenting across port maintenance, removal, and replacement procedures as manufacturers and third-party service providers compete for recurring patient touchpoints. Becton Dickinson leverages its integrated vascular access portfolio to capture follow-on service streams. AngioDynamics specializes in minimally invasive port technologies that reduce complication rates. Teleflex anchors its position through hospital GPO contracts and clinical training infrastructure.
Implantable port devices are subcutaneously implanted reservoir systems connected to a central vein via a catheter, typically constructed from titanium or polymer composite housings with silicone or polyurethane septa capable of withstanding hundreds of needle punctures for repeated drug delivery or fluid withdrawal. The devices serve patients requiring long-term venous access for chemotherapy, hemodialysis, or parenteral nutrition. Chemotherapy ports represent the dominant product category given oncology's substantial patient volume, while hemodialysis ports command premium positioning due to higher flow-rate specifications and stricter biocompatibility demands. Silicone and titanium materials lead current utilization, though polymer composites are gaining traction for their strength-to-weight advantages in pediatric applications.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern commercial entry, with both frameworks intensifying post-market surveillance obligations that extend product lifecycle accountability to manufacturers. The EPA and OSHA additionally regulate sterilization process emissions and healthcare worker exposure limits during implantation procedures. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement coding changes that could alter competitive economics across outpatient versus inpatient delivery settings.
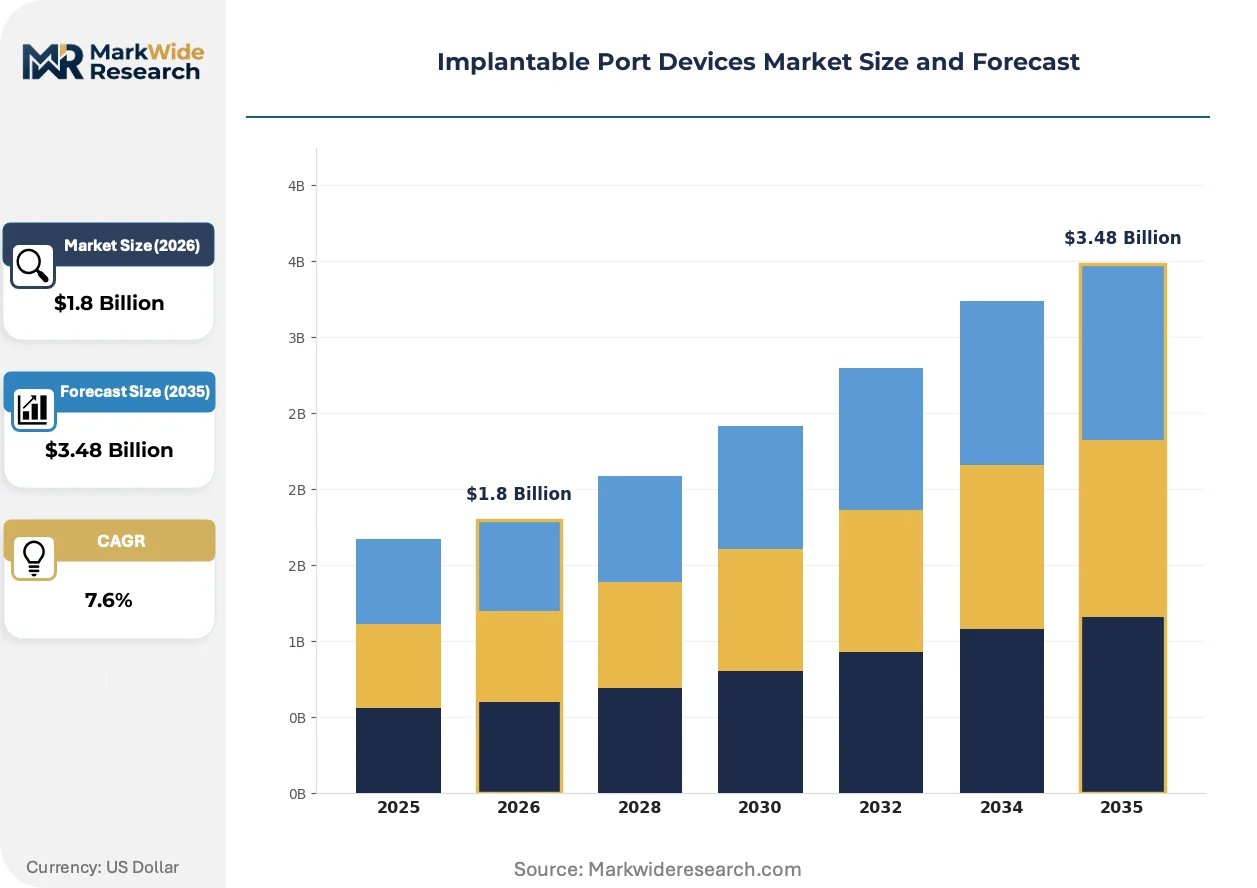
Market Dynamics
Oncology infusion therapy protocols are compressing replacement cycles for implantable port devices as hospitals prioritize infection-resistant materials and extended dwell times to reduce catheter-related complications.
Growth Catalysts
- EU MDR conformity assessments:Post-market surveillance obligations are elevating quality thresholds and filtering marginal suppliers from European hospital procurement pools.
- Hemodialysis flow-rate specifications:Rising end-stage renal disease prevalence is expanding demand for high-flow titanium ports capable of sustained high-volume blood exchange.
- Silicone septum durability:Advancements in needle-puncture resistance are extending functional device lifespans beyond five hundred access cycles in chemotherapy applications.
Market Restraints
- Titanium supply concentration:Medical-grade titanium sponge production clusters in limited supplier geographies, exposing device manufacturers to input cost volatility and alloying specification constraints.
- FDA 510(k) clearance timelines:Intensified biocompatibility documentation requirements are extending premarket notification review periods and compressing revenue recognition windows for new product introductions.
- Peripherally inserted central catheter substitution:PICC lines are capturing short-duration venous access cases previously served by implanted ports, narrowing addressable procedure volumes.
Strategic Opportunities
- Japan's aging demographic:The country's expanding geriatric oncology population is creating unmet demand for pediatric-scaled polymer composite ports adapted to fragile vasculature.
- Home infusion therapy expansion:Reimbursement coding shifts toward ambulatory settings are opening channel opportunities for manufacturers with patient self-access training infrastructure.
- ISO 10993 biocompatibility harmonization:Converging international testing standards are reducing redundant certification costs and accelerating multi-market product launches.
Industry Challenges
- Interventional radiologist training gaps:Shortages of physicians proficient in fluoroscopy-guided port implantation are creating procedural bottlenecks in community hospital settings.
- Sterilization validation complexity:Ethylene oxide emission restrictions under EPA regulations are forcing capital-intensive process revalidation for contract sterilization providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Port Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Ports, Hemodialysis Ports, Total Parenteral Nutrition Ports, Others Material: Silicone, Polyurethane, Titanium, Polymer Composites End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Clinics Delivery Mode: Implantation, Insertion, Removal, Maintenance |
| Companies Covered | Becton Dickinson, AngioDynamics, Teleflex, B. Braun Melsungen, Vygon, ICU Medical, Cook Group, Perouse Medical, PakuMed Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Port Devices Market Evolving Landscape
Material science advances and connected health integration are redefining performance benchmarks for implantable vascular access systems. Manufacturers are racing to embed sensing capabilities and streamline regulatory pathways across multiple jurisdictions.
Polymer composite housings are digitizing port device functionality through embedded RFID tracking and pressure-sensing septa that transmit dwell-time and access-frequency data to electronic health records. Academic medical centers in Germany and the United States are piloting these smart ports for remote monitoring of chemotherapy adherence. The structural consequence is digitizing aftermarket service revenue from reactive replacement toward predictive maintenance contracts.
EU MDR technical documentation requirements are intensifying post-market clinical follow-up obligations for implantable devices. Manufacturers must now submit periodic safety update reports and maintain implant registries traceable to individual patients. Hemodialysis port categories face the steepest compliance burden due to their extended patient contact duration and higher adverse event reporting thresholds.
Hospital GPO consolidation is compressing vendor selection criteria toward comprehensive vascular access portfolios rather than standalone port devices. Procurement committees now evaluate suppliers across PICC, midline, and implanted port categories simultaneously. This behavioral shift is most pronounced in United States integrated delivery networks where standardization incentives override individual physician product preferences.
Implantable Port Devices Market Segmentation
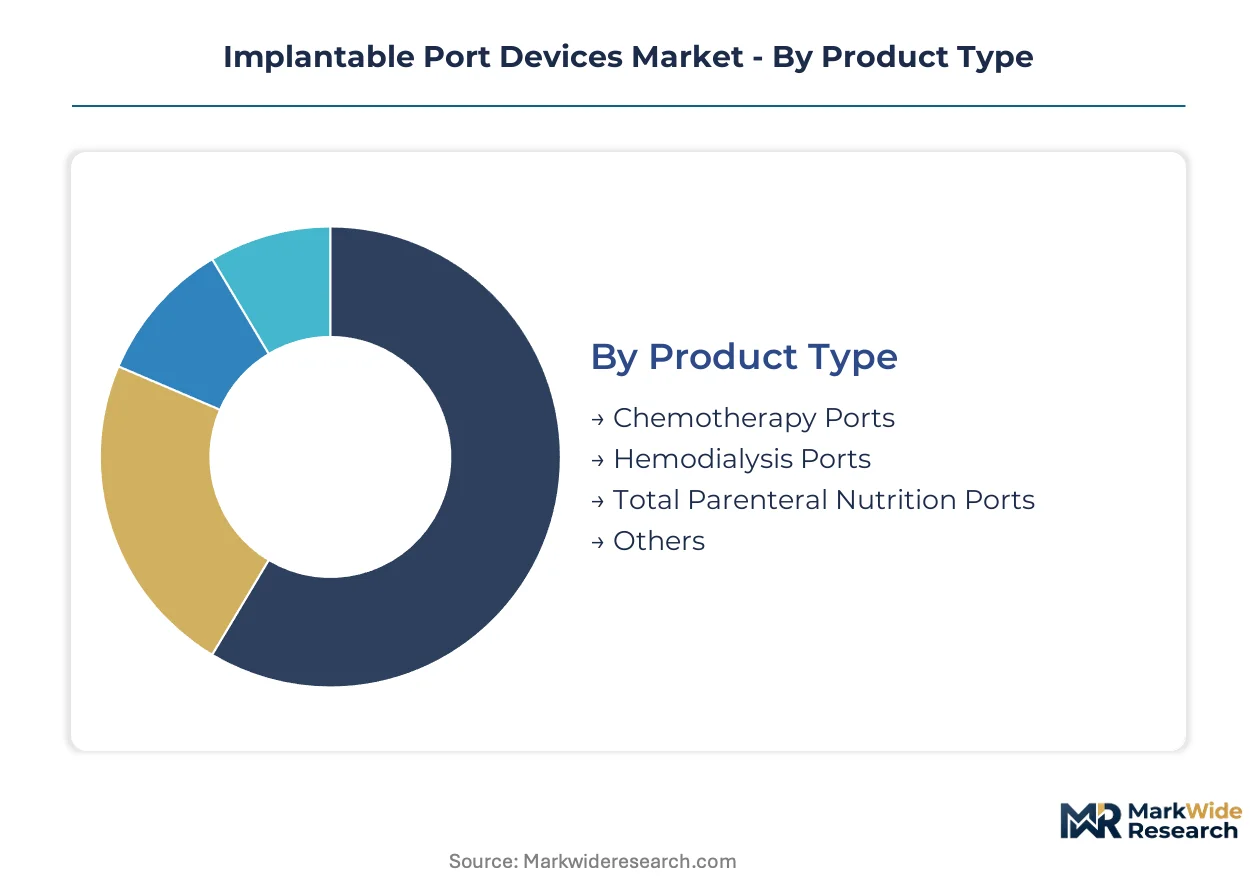
Implantable port devices generate recurring service revenue across their clinical lifecycle, making segment-level profitability analysis essential for manufacturers balancing upfront device margins against long-term maintenance contracts. Each dimension—product type, material composition, end-user channel, and procedural mode—carries distinct service intensity profiles that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across port categories, with chemotherapy ports demanding frequent access-site maintenance while hemodialysis ports require specialized flow-rate calibration protocols.
- Chemotherapy Ports:These devices feature silicone or polyurethane septa engineered for hundreds of needle punctures during multi-cycle oncology regimens. Demand concentrates in United States hospital systems where extended dwell-time protocols reduce infection risks and minimize replacement frequency. The service model pivots on access-site monitoring and septum integrity assessment rather than full device exchange.
- Hemodialysis Ports:Titanium construction enables sustained high-volume blood exchange for end-stage renal disease patients. Germany's dialysis networks drive adoption of premium-specification ports with integrated flow sensors. The elevated unit economics reflect both material costs and the specialized interventional radiologist training required for implantation.
- Total Parenteral Nutrition Ports:Smaller-bore designs serve patients with chronic intestinal failure requiring long-term nutritional support. Pediatric applications in Japan favor polymer composite variants for weight reduction.
- Others:Includes antibiotic therapy ports and blood draw reservoirs for rare disease protocols. Niche positioning limits dedicated service infrastructure investment.
By volume, chemotherapy ports lead. By growth pace, hemodialysis ports are ahead.
Material:
Cost tier stratification across material categories determines procurement committee evaluation criteria, with titanium commanding premium positioning and polymer composites disrupting mid-market segments.
- Titanium:Medical-grade sponge supply concentrates in limited supplier geographies, exposing device manufacturers to input cost volatility. United States hemodialysis specifications mandate titanium for high-flow durability, creating captive demand despite price premiums.
- Silicone:Dominates chemotherapy applications through proven biocompatibility and self-sealing septum performance. FDA 510(k) clearance pathways favor established silicone formulations with extensive predicate device histories.
- Polyurethane:Offers puncture resistance advantages for high-frequency access protocols. European outpatient clinics specify polyurethane for patient self-access training programs.
- Polymer Composites:Strength-to-weight ratios enable pediatric-scaled devices for Japan's geriatric oncology population with fragile vasculature. ISO 10993 harmonization is reducing redundant certification costs for multi-market launches.
By installed base, silicone leads. By margin expansion potential, polymer composites are climbing the fastest.
End User:
Customer type segmentation reveals diverging procurement authority structures, with hospital GPO consolidation compressing vendor selection criteria toward comprehensive vascular access portfolios.
- Hospitals:Integrated delivery networks in the United States evaluate suppliers across PICC, midline, and implanted port categories simultaneously. Standardization incentives override individual physician product preferences, favoring vendors with training infrastructure breadth.
- Outpatient Clinics:Reimbursement coding shifts toward ambulatory settings are opening channel opportunities for manufacturers with patient self-access training programs. Germany's ambulatory oncology networks lead this transition.
- Ambulatory Surgical Centers:Focus on high-volume, low-complexity implantation procedures with compressed length-of-stay metrics. Cost sensitivity elevates polymer composite preference.
- Specialty Clinics:Hemodialysis centers and parenteral nutrition clinics require device-service bundling. Japan's dialysis specialty networks demand predictive maintenance contracts.
By procedure volume, hospitals lead. By channel growth rate, outpatient clinics are expanding most quickly.
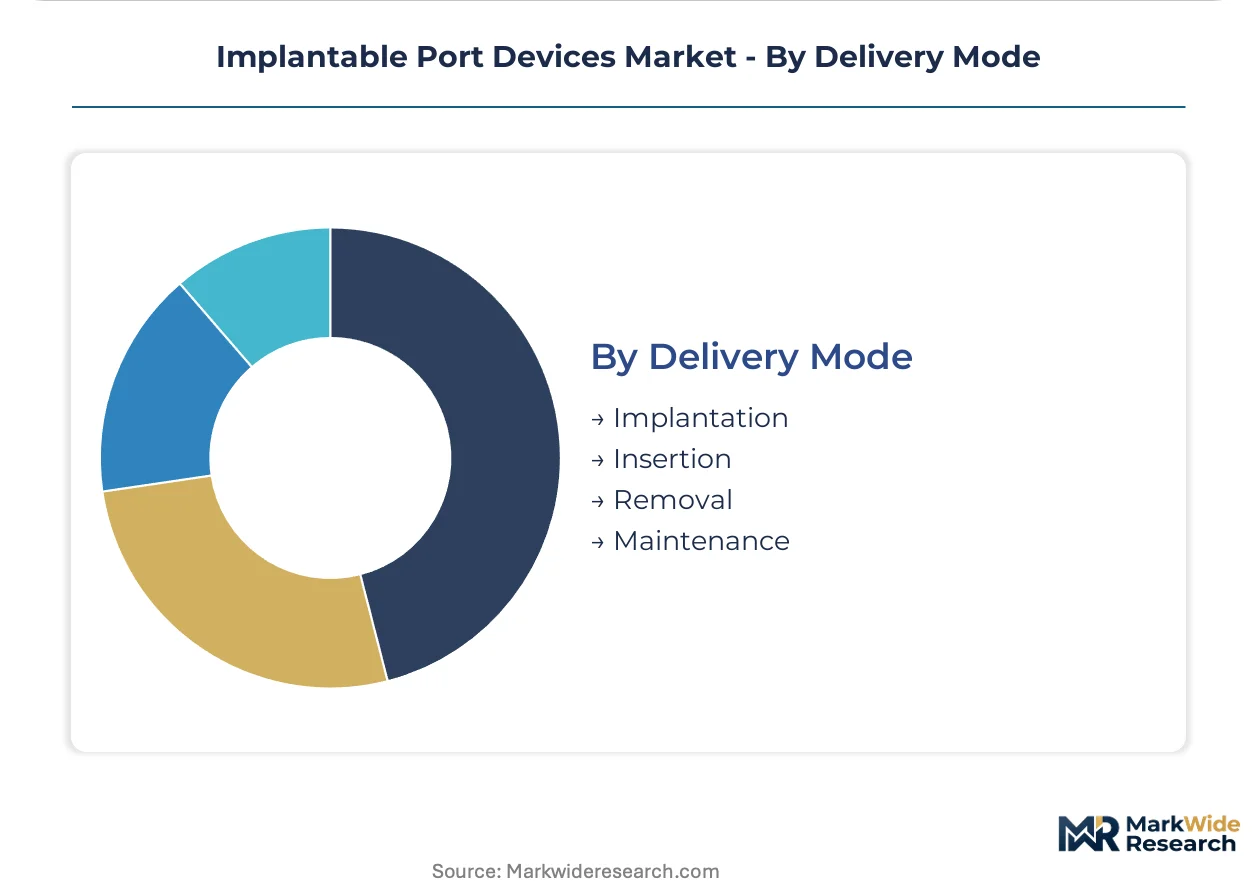
Delivery Mode:
Volume concentration in implantation procedures obscures margin migration toward removal and maintenance services as manufacturers compete for recurring patient touchpoints.
- Implantation:Fluoroscopy-guided procedures require interventional radiologist proficiency. Shortages of trained physicians create bottlenecks in United States community hospital settings.
- Insertion:Distinct from full implantation, this mode covers catheter connection to existing port reservoirs. Lower reimbursement rates limit standalone commercial focus.
- Removal:Rising revision rates for infection or device failure are elevating explant procedure economics. Third-party service providers are fragmenting this revenue stream.
- Maintenance:Access-site care, septum replacement, and flow verification generate predictable recurring revenue. Becton Dickinson leverages integrated vascular access portfolios to capture follow-on service streams.
By revenue concentration, implantation leads. By margin stability, maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets: United States hospitals prioritize extended-dwell infection-resistant materials, while Japan's geriatric oncology expansion demands pediatric-scaled devices for fragile vasculature.
United States
Oncology infusion therapy and hemodialysis networks drive device procurement in integrated delivery networks. FDA 510(k) clearance pathways govern commercial entry with intensified biocompatibility documentation requirements. Boston's academic medical centers pilot RFID-enabled smart ports for remote chemotherapy adherence monitoring.
Germany
Ambulatory oncology networks and dialysis specialty clinics anchor European demand for premium-specification ports. EU MDR conformity assessments with periodic safety update reports filter marginal suppliers from hospital procurement pools. Heidelberg's university hospital cluster leads post-market clinical follow-up registry development for hemodialysis categories.
Japan
Geriatric oncology population expansion creates unmet demand for polymer composite ports adapted to fragile vasculature. PMDA premarket approval processes align with ISO 10993 harmonization to reduce redundant certification costs. Tokyo's metropolitan hospital systems standardize on pediatric-scaled devices for elderly patient protocols.
China
End-stage renal disease prevalence and expanding cancer treatment infrastructure elevate port device procurement. NMPA medical device registration requirements intensify for imported implantable products. Shanghai's tertiary hospital network concentrates fluoroscopy-guided implantation capacity for high-flow hemodialysis specifications.
Implantable Port Devices Market Competitive Landscape
Capability concentration sits with integrated vascular access portfolios; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: comprehensive platform suppliers capturing GPO contracts, minimally invasive technology specialists, and regional manufacturers serving price-sensitive segments. Dominant competitive moves include hospital training infrastructure expansion and predictive maintenance service bundling.
Among diversified medical technology suppliers, Becton Dickinson exemplifies the integrated platform archetype through vascular access portfolio breadth. AngioDynamics occupies a specialist position in minimally invasive port technologies. Teleflex anchors the hospital contracting tier through GPO relationship depth. These three represent distinct competitive vectors rather than overlapping market positions.
| Leading Market Players |
|---|
| Becton Dickinson |
| AngioDynamics |
| Teleflex |
| B. Braun Melsungen |
| Vygon |
| ICU Medical |
| Cook Group |
| Perouse Medical |
| PakuMed Medical Products |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Los Angeles container freight corridors transmit titanium sponge cost volatility directly into manufacturer pricing power, concentrating margin pressure on polymer composite alternatives while enabling premium positioning for medical-grade titanium ports in United States hemodialysis networks.
Pricing Analysis
Long-term offtake contracts dominate procurement between United States integrated delivery networks and tier-one manufacturers, insulating volume purchasers from spot-market titanium fluctuations while outpatient clinics absorb project-based pricing for single-unit chemotherapy ports. Price differentiation rests on FDA 510(k) clearance tier and bundled after-sales service depth, with GPO-negotiated contracts commanding 15-20 point spreads over direct hospital purchases. Cost compression in polymer composite segments intensifies as Chinese manufacturers scale pediatric-scaled production for Japan's geriatric oncology demand. Ambulatory surgical centers exhibit acute price sensitivity, whereas academic medical centers prioritize septum durability specifications over unit economics.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for medical-grade titanium sponge, forcing manufacturers to qualify alternative Japanese and Russian feedstock sources under tightened alloying specification constraints. Device assembly draws from Taiwanese polymer composite molding, German precision machining, and United States silicone septum formulation. Single-source vulnerability concentrates in ethylene oxide sterilization capacity as EPA emission restrictions shutter domestic contract facilities. Distribution runs through hospital GPO consolidated procurement platforms, with direct manufacturer-to-specialty-clinic channels gaining share in Germany's ambulatory oncology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
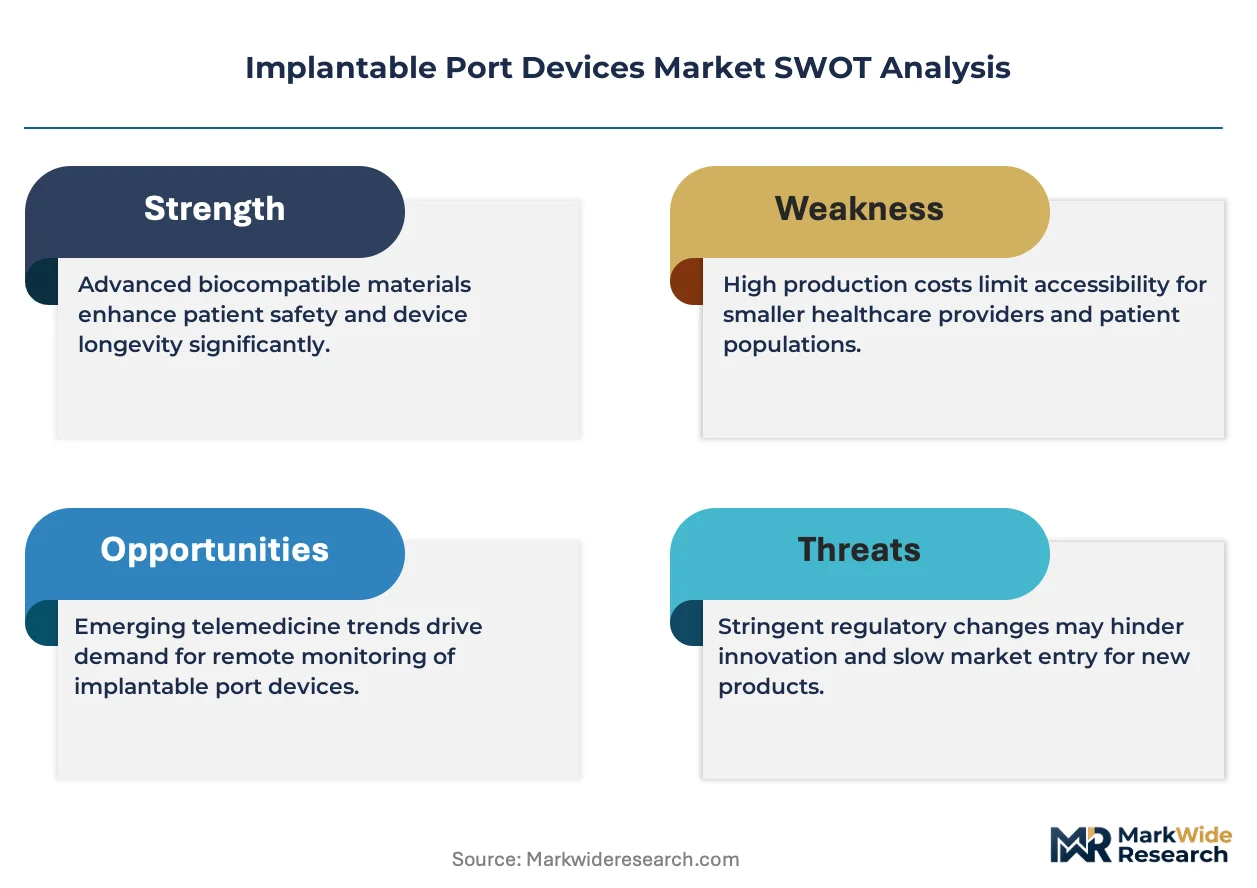
Implantable port devices function as a regulatory entrenchment market where FDA 510(k) predicate device histories and EU MDR technical documentation burdens create switching costs that cement incumbent positions against would-be challengers.
For Market Incumbents: Pre-empt PICC line substitution by embedding RFID sensing capabilities into titanium port portfolios, converting device sales into predictive maintenance subscription contracts. Secure backward integration into medical-grade titanium sponge supply through Japanese or Russian offtake agreements before tariff escalation hardens alternative sourcing economics. Fortify hospital training infrastructure to address interventional radiologist shortages that bottleneck community hospital implantation capacity. For New Entrants and Emerging Players: Pursue polymer composite pediatric-scaled devices for Japan's geriatric oncology population, where fragile vasculature specifications favor strength-to-weight advantages over incumbent titanium offerings. Target Germany's ambulatory oncology networks with patient self-access training programs that align with reimbursement coding shifts toward outpatient settings. Establish ISO 10993 harmonization as the go-to-market angle for accelerated multi-market product launches. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to monetize non-core vascular access divisions amid portfolio rationalization pressures. Five-to-ten year viability favors manufacturers with integrated service revenue streams over pure-play device vendors exposed to commoditization. Watch FDA premarket notification review period extensions as the signal indicating regulatory burden inflection that will filter marginal suppliers and concentrate share among documentation-capable incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Becton Dickinson leverages GPO contract depth to standardize vascular access portfolios across integrated delivery networks. |
| Software Companion Development | Embedded RFID tracking transforms reactive port replacement into predictive maintenance revenue streams. |
| Reimbursement Strategy | Coding alignment with ambulatory settings opens outpatient clinic channels for patient self-access training programs. |
| CE Marking Pathway | EU MDR periodic safety update reports filter marginal suppliers from European hospital procurement pools. |
| FDA Submission | Intensified biocompatibility documentation requirements extend clearance timelines and compress revenue recognition windows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital GPO contract disclosure records. Primary interviews engaged interventional radiologists, hospital purchasing committee chairs, biomedical engineers specializing in vascular access, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement coding archives, ISO 10993 biocompatibility standard harmonization protocols, and EPA ethylene oxide emission regulatory filings. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue segmentation across product type, material composition, and end-user channel dimensions.
Forecast inputs incorporate oncology infusion therapy protocol evolution, hemodialysis network expansion trajectories, and aging demographic projections across the analysis window. Segmentation modeling spans chemotherapy, hemodialysis, and parenteral nutrition port categories by titanium, silicone, polyurethane, and polymer composite material tiers. CAGRs derive from installed base growth, replacement cycle compression, and service revenue migration toward maintenance contracts. Industry-specific forecast inputs include EU MDR post-market surveillance obligation implementation timelines and Japan's geriatric oncology population scaling.
Macroeconomic conditions sit as an overlay; deviation in medical-grade titanium sponge pricing, freight corridor cost structures, or reimbursement coding trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and sterilization capacity availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Ablation Devices Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Embolization Coils Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Breast Pump Flange Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Global Hi-Tech Medical Devices Market