
 Global Healthcare EDI Market | 2026-2036
Global Healthcare EDI Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare EDI Market Foresight
Multi-source vendor strategies among payers is expanding as health systems seek redundancy in transaction processing. McKesson Corporation leverages its pharmaceutical distribution backbone to anchor EDI connectivity across hospital networks. Optum Inc. competes through integrated data analytics and payer-provider alignment tools. Cognizant sustains delivery scale through offshore development centers serving North American and European health plans.
Healthcare electronic data interchange denotes the structured computer-to-computer transmission of health information using standardized formats such as X12, HL7, and EDIFACT, replacing paper-based claims, eligibility verifications, and payment remittances with sub-second transaction cycles. EDI Software and Cloud-Based deployment together capture the dominant share of new implementations as hospitals migrate from legacy mainframe connections to API-enabled platforms. Claims Management leads application spending due to the sheer transaction volume between providers and payers, while Payment Processing grows fastest as real-time adjudication models displace batch cycles.
FDA oversight of software-as-medical-device functions, HIPAA transaction and code set standards, and the EU AI Act's risk classification for automated claims decisioning collectively shape product roadmaps and market access conditions for vendors. Health systems must validate interoperability against ONC certification criteria before procurement. Stakeholders should monitor whether CMS mandates for price transparency and prior authorization automation will force wholesale platform upgrades or favor modular API overlays.
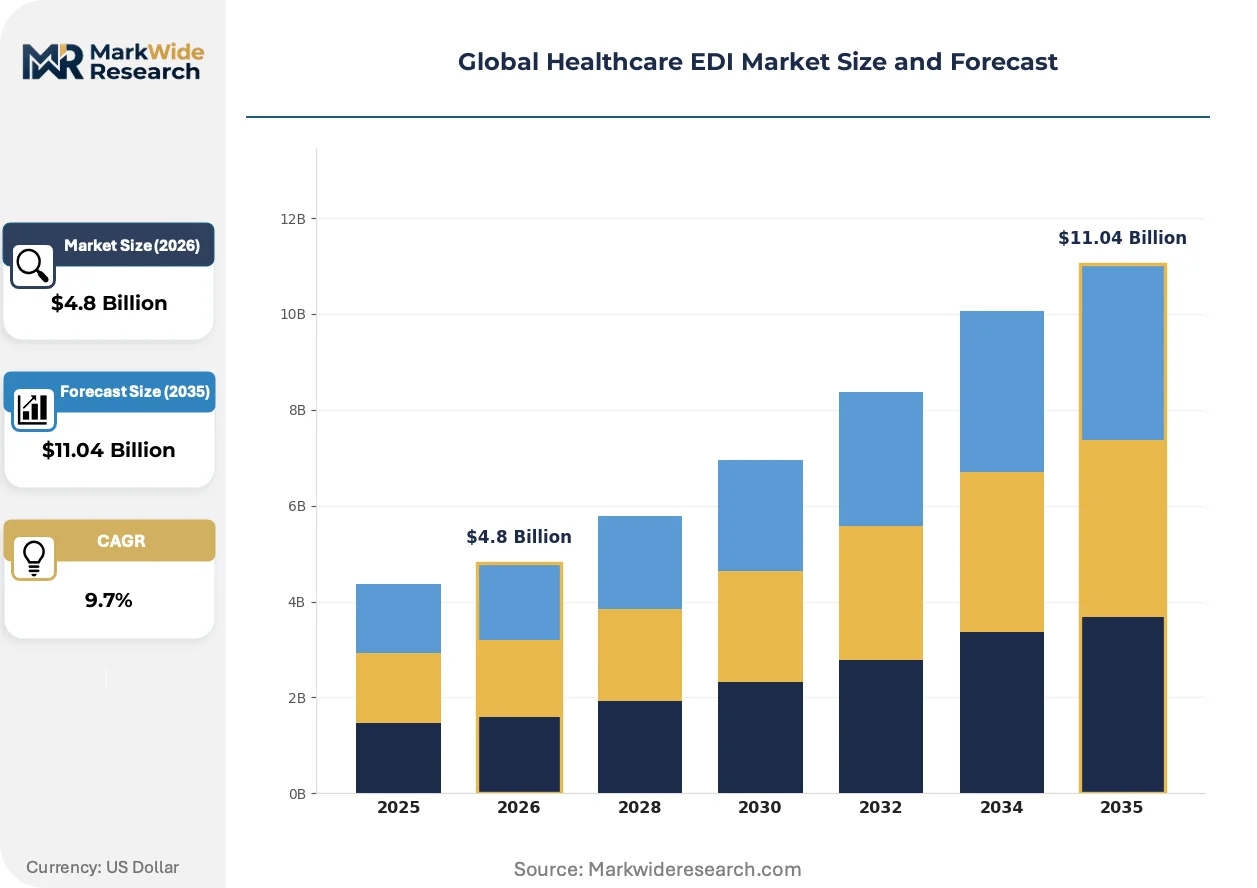
Market Dynamics
The migration from batch-based claims processing to real-time API-enabled transaction networks is compressing implementation cycles and forcing wholesale platform replacements across payer organizations.
Growth Catalysts
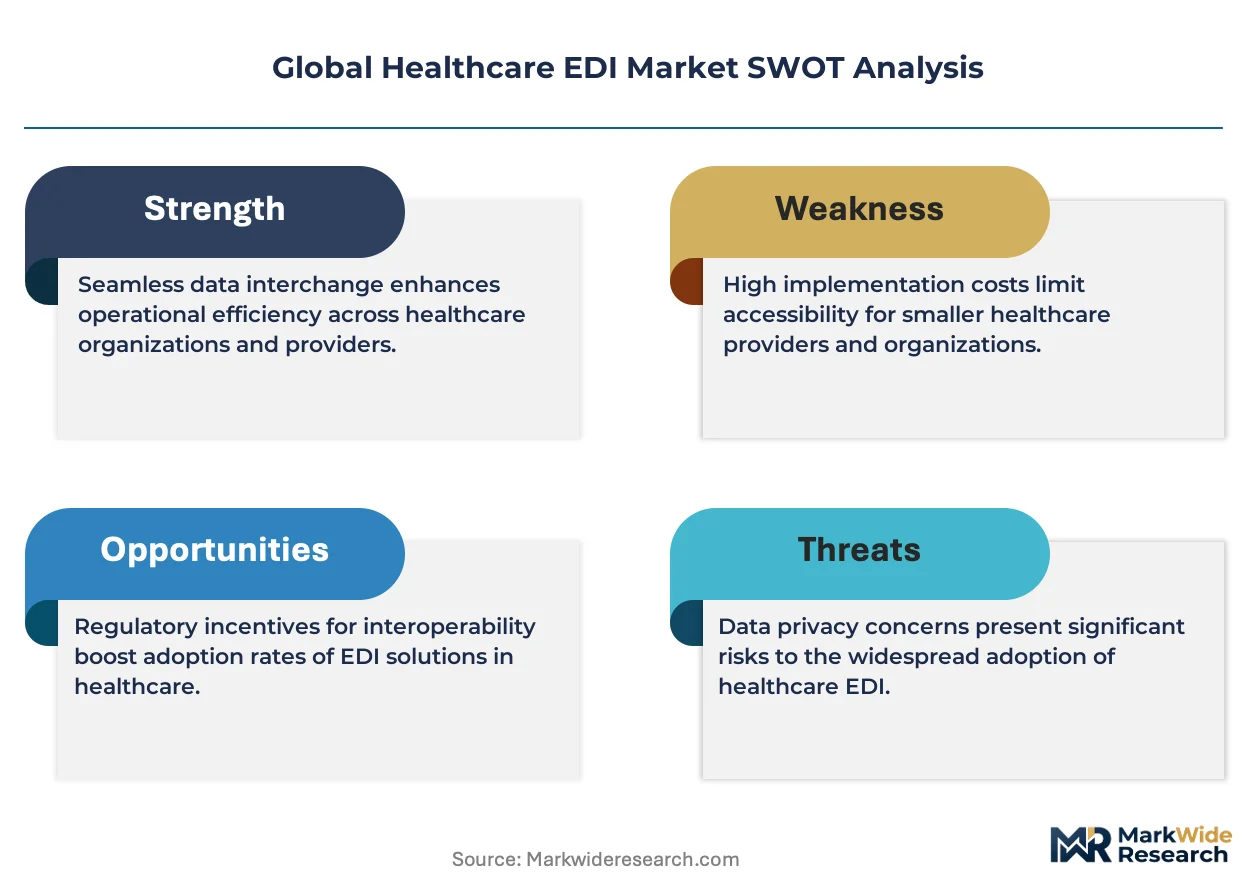
- HIPAA Transaction Standards:Mandates for electronic claims submission and standardized code sets eliminate paper-based workflows, compelling provider-payer interoperability upgrades.
- Cloud Infrastructure:Healthcare systems are abandoning on-premise mainframe EDI connections for scalable API gateways that reduce transaction latency from hours to milliseconds.
- Prior Authorization Automation:CMS requirements for automated prior authorization decisioning are expanding real-time eligibility verification volumes between hospitals and insurers.
Market Restraints
- Legacy System Entrenchment:Decades-old HL7 v2 interfaces and custom payer mappings create technical debt that slows platform migration timelines.
- Cybersecurity Compliance Burden:HIPAA Security Rule requirements for encryption, access controls, and audit logging add implementation complexity and ongoing operational overhead.
- Interoperability Standard Fragmentation:Competing frameworks including FHIR, X12, and EDIFACT force vendors to maintain multiple protocol stacks, diluting R&D resources.
Strategic Opportunities
- India Healthcare Digitization:The country's ABHA health ID infrastructure and expanding private insurance penetration create greenfield EDI deployment potential.
- Payment Processing Convergence:Real-time claims adjudication linked to instant payment rails is displacing traditional remittance cycles in ambulatory care networks.
- EU AI Act Risk Classification:Automated claims decisioning tools face new conformity requirements that favor established vendors with compliance infrastructure.
Industry Challenges
- FHIR Implementation Expertise Gap:Health systems struggle to recruit developers capable of mapping legacy data structures to modern interoperability standards.
- ONC Certification Timeline Compression:Payers must validate platforms against evolving certification criteria while maintaining uninterrupted transaction processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare EDI Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EDI Software, Network Services, Data Integration Tools, Managed Services, Consulting Services Application: Claims Management, Payment Processing, Patient Scheduling, Regulatory Reporting, Supply Chain Management End User: Hospitals, Diagnostic Centers, Physician Practices, Pharmacies, Health Insurance Providers Deployment Mode: Cloud-Based, On-Premises, Hybrid, Managed Hosting |
| Companies Covered | McKesson Corporation, Optum Inc., Cognizant, Waystar, Experian Health, Availity, LLC, Change Healthcare, The SSI Group, LLC, Veradigm LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare EDI Market Shifts & Advancements
Real-time data exchange architectures are supplanting batch-oriented systems as the default expectation for provider-payer transactions, compressing settlement windows and enabling new payment models.
API-first EDI platforms are rewriting how eligibility inquiries and claims status checks execute. Large hospital networks are deploying these interfaces to replace dial-up modem connections and scheduled file transfers. The technology is rewriting cost structures by eliminating per-transaction clearinghouse fees and enabling direct payer connectivity.
The EU AI Act's risk-based classification for automated healthcare decisioning is reshaping vendor product roadmaps. High-risk claims adjudication algorithms now face mandatory conformity assessments and human oversight requirements. European health insurers are restructuring procurement criteria to prioritize vendors with established notified body relationships.
Subscription-based platform licensing is displacing traditional per-transaction pricing in mid-market provider segments. Ambulatory surgery centers and specialty clinics are adopting flat-fee EDI connectivity to predict operational costs. Germany and the United States exhibit the fastest uptake of this model as independent practices consolidate into larger group enterprises.
Global Healthcare EDI Market Segmentation
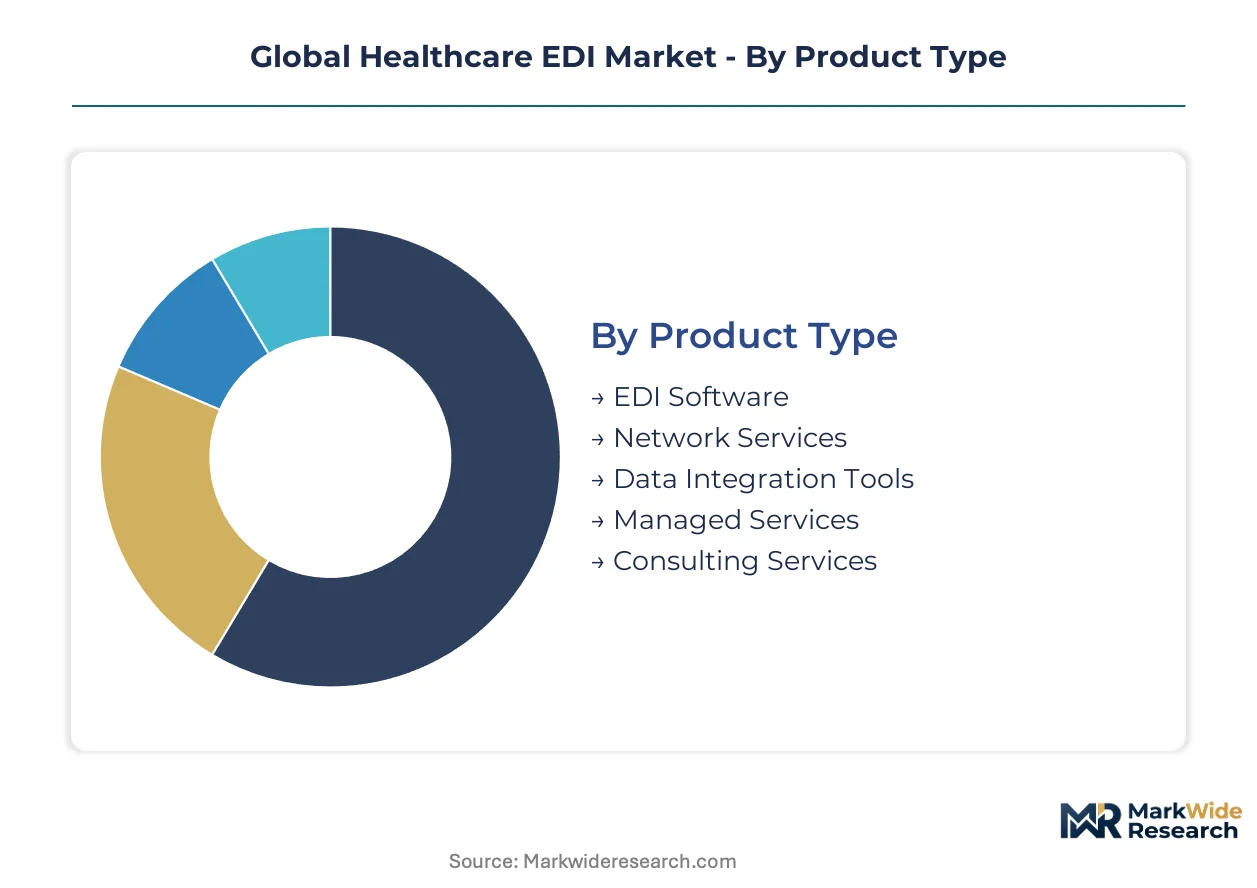
Healthcare EDI segmentation reveals distinct technology stacks competing for capital allocation across provider and payer organizations. Product architecture, deployment economics, and end-user workflow requirements create divergent growth trajectories within each dimension.
Product Type:
Volume concentrates in transaction-heavy infrastructure, while premium capture flows to advisory and integration layers that reduce implementation risk.
- EDI Software:Core transaction engines process X12, HL7, and EDIFACT formats through rules-based validation engines. United States health systems and German hospital networks drive replacement demand as legacy mainframe licenses expire.
- Network Services:Clearinghouse connectivity and direct payer routing infrastructure that eliminates intermediary fees. India's ABHA-linked private insurers and United States ambulatory surgery centers are expanding direct connection architectures to compress settlement windows.
- Data Integration Tools:FHIR mapping and legacy HL7 v2 conversion utilities bridging modern API gateways with entrenched systems.
- Managed Services:Outsourced transaction monitoring, exception handling, and compliance audit support for mid-market providers lacking internal IT scale.
- Consulting Services:ONC certification preparation, HIPAA Security Rule gap remediation, and EU AI Act conformity assessments for automated claims tools.
Today's leader: EDI Software. Tomorrow's challenger: Network Services.
Application:
Workflow automation intensity varies sharply by function, with payment velocity emerging as the decisive competitive differentiator.
- Claims Management:Eligibility verification, submission, and adjudication workflows consuming the majority of transaction volume. United States physician practices and Indian corporate hospital chains are the primary demand anchors for real-time status checking capabilities.
- Payment Processing:Remittance advice generation, ERA distribution, and instant payment rail integration. Germany's statutory health insurance funds and United States Medicare Advantage plans are accelerating real-time adjudication pilots.
- Patient Scheduling:Appointment booking, referral management, and prior authorization integration with clinical systems.
- Regulatory Reporting:CMS price transparency submissions, FDA device tracking, and EU MDR vigilance reporting automation.
- Supply Chain Management:Pharmaceutical ordering, inventory synchronization, and charge master updates between hospitals and distributors.
Claims Management commands current spend. Payment Processing is climbing the fastest as instant settlement models displace batch cycles.
End User:
Capital availability and regulatory exposure create tiered procurement patterns across provider and payer categories.
- Hospitals:Integrated delivery networks with multi-payer connectivity requirements and complex charge master maintenance. United States health systems and German university hospitals are consolidating EDI vendors to reduce interface fragmentation.
- Health Insurance Providers:Payer organizations requiring high-availability claims ingestion and automated decisioning infrastructure. India's expanding private insurance market and United States Medicaid managed care plans are investing in API-first eligibility platforms.
- Physician Practices:Solo and group practices prioritizing low-touch clearinghouse connectivity and simplified prior authorization workflows.
- Diagnostic Centers:Imaging and laboratory facilities with specialized LOINC and DICOM integration requirements alongside standard claims processing.
- Pharmacies:Retail and specialty pharmacy chains requiring real-time prescription benefit verification and inventory replenishment signaling.
Hospitals anchor procurement volume. Health Insurance Providers are gaining share fastest as real-time adjudication mandates expand.
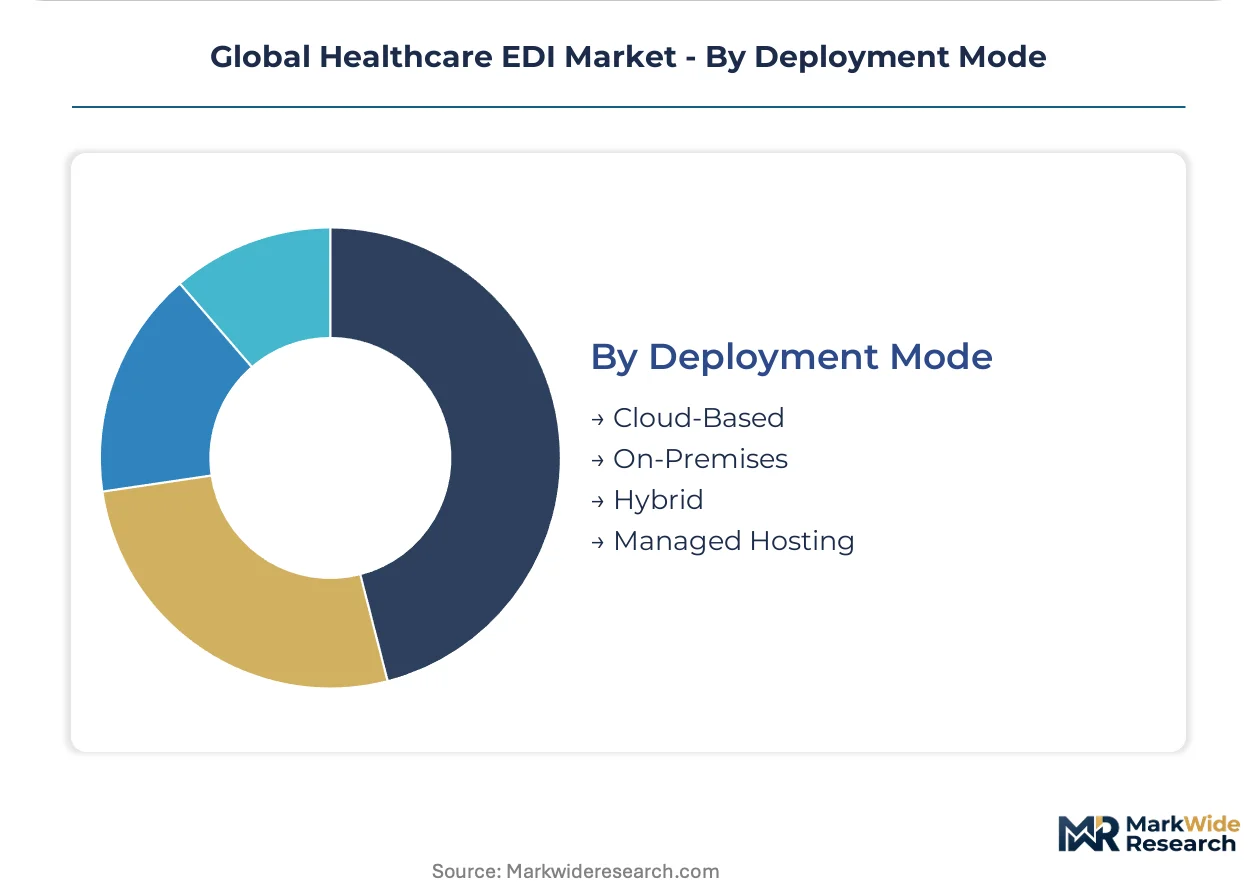
Deployment Mode:
Technical debt and risk tolerance divide the market between cloud-native adoption and controlled migration paths.
- Cloud-Based:Scalable API gateways with consumption-based pricing and automatic compliance patching. United States specialty clinics and German ambulatory care networks are abandoning owned infrastructure for operational cost predictability.
- Hybrid:Sensitive claims data retained on-premises while connectivity layers shift to cloud-hosted gateways. United States regional health systems facing HIPAA Security Rule audit scrutiny favor this architecture for controlled transition.
- On-Premises:Legacy mainframe and client-server installations in organizations with severe data residency constraints or union-mandated staffing requirements.
- Managed Hosting:Single-tenant cloud deployments with dedicated infrastructure managed by vendor operations centers, bridging control and outsourcing economics.
Cloud-Based dominates new implementations. Hybrid represents the steepest expansion trajectory as risk-averse organizations seek intermediate migration paths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States health information technology corridor anchors global EDI transaction volume, with HIPAA mandates and CMS automation requirements compressing implementation timelines across provider networks. Germany and India follow as distinct growth poles, each driven by statutory digitization programs and expanding private insurance penetration.
United States
HIPAA transaction standards and CMS prior authorization automation mandates compel health systems to replace legacy batch systems with real-time API gateways. The ONC certification program validates interoperability compliance before procurement. Texas Medical Center and Boston's Longwood Medical Area concentrate replacement demand as integrated delivery networks consolidate vendor relationships.
Germany
Statutory health insurance funds accelerate real-time adjudication pilots to reduce claims settlement windows. The EU AI Act risk classification framework imposes conformity assessments on automated decisioning tools. Berlin and Munich hospital networks drive cloud migration demand as Gematik interoperability specifications mature.
India
ABHA health ID infrastructure and expanding private insurance penetration create greenfield EDI deployment opportunities. The country's national health regulator validates software standards under the digital health mission. Bangalore and Hyderabad health tech clusters attract clearinghouse operators seeking direct payer connectivity architectures.
United Kingdom
NHS Digital integration requirements and procurement frameworks standardize electronic referral and payment processes across trusts. GDPR compliance obligations shape data residency decisions for cloud-hosted platforms. London and Manchester integrated care systems pilot real-time eligibility verification between hospitals and commissioning groups.
Canada
Provincial health authority digitization programs and federal interoperability investment funds accelerate EDI modernization. Health Canada oversight of medical device software extends to claims processing algorithms embedded in hospital systems. Toronto and Vancouver health networks consolidate clearinghouse contracts to reduce transaction fragmentation.
Global Healthcare EDI Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue API-native architectures and modular overlay solutions. The vendor base stratifies across three maturity levels: legacy clearinghouse operators with mainframe infrastructure, cloud-native platforms with consumption-based pricing, and consulting-led integrators managing certification complexity. Dominant competitive moves include strategic partnerships between software vendors and payment rail operators, plus portfolio diversification into prior authorization automation modules.
Within the integrated services tier, McKesson Corporation and Optum Inc. exemplify scale-driven positioning anchored to pharmaceutical distribution and payer data analytics respectively. Cognizant represents the offshore delivery archetype, sustaining implementation capacity through development center networks serving North American and European health plans. These three entities occupy positions that reflect distinct competitive vectors: supply chain integration, payer-provider alignment, and global service scale.
| Leading Market Players |
|---|
| McKesson Corporation |
| Optum Inc. |
| Cognizant |
| Waystar |
| Experian Health |
| Availity, LLC |
| Change Healthcare |
| The SSI Group, LLC |
| Veradigm LLC |
| Others |
Supply & Pricing Matrix
CMS mandates for prior authorization automation are compressing procurement timelines across United States health systems, forcing EDI vendors to absorb compliance development costs while maintaining subscription pricing predictability for ambulatory surgery centers and specialty clinics migrating from per-transaction models.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and cybersecurity compliance tooling is intensifying margin pressure on mid-tier EDI software vendors. The dominant pricing structure has shifted to subscription-based SaaS tiers with consumption-scaled bands, though large hospital networks retain negotiated enterprise licenses. Price differentiation centers on ONC certification grade and real-time API capability depth, with certified platforms commanding premiums over legacy clearinghouse alternatives. Pricing pressure runs downward through the mid-market as flat-fee connectivity becomes standard. Physician practices and independent diagnostic centers exhibit highest price sensitivity, while integrated delivery networks prioritize uptime guarantees over cost minimization.
Supply Chain Analysis
India's data localization requirements under its digital health mission and Germany's Gematik interoperability specifications are reshaping vendor sourcing strategies toward regional development centers and localized hosting infrastructure. Software development and cloud infrastructure provision concentrate in the United States, India, and Germany, with specialized FHIR mapping expertise clustering in Bangalore and Hyderabad health tech corridors. The supply chain draws from offshore engineering talent pools, API gateway platforms, and payment rail integration partners. Single-source vulnerability in clearinghouse connectivity creates concentration risk for ambulatory networks dependent on dominant intermediaries. Distribution runs through direct enterprise sales to hospital systems, GPO-negotiated contracts for mid-market providers, and channel partnerships with electronic health record vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Healthcare EDI Market has entered a late-cycle quality phase where procurement committees prioritize ONC-certified, API-first platforms over legacy connectivity, elevating vendors with proven interoperability validation and real-time transaction architectures.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by consolidating clearinghouse relationships into unified platform offerings and accelerating FHIR R&D investment to offset technical debt in HL7 v2 legacy installations. Defensive positioning requires deepening payer-provider alignment tools and securing notified body relationships for EU AI Act conformity assessments on automated claims decisioning modules. For New Entrants and Emerging Players: API-first direct connectivity platforms offer the most penetrable entry vector, particularly targeting India's ABHA-linked private insurers and United States ambulatory surgery centers seeking to bypass traditional clearinghouse fee structures. White-space concentration sits in real-time payment rail integration for Germany's statutory health insurance funds and prior authorization automation modules for United States Medicare Advantage plans. Go-to-market execution should anchor to channel partnerships with electronic health record vendors rather than direct hospital system sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native EDI platforms possessing established FHIR implementation expertise and existing notified body relationships for EU AI Act compliance, as these capabilities face scarcity premium in acquisition markets. Long-term viability favors vendors with diversified geographic revenue across United States HIPAA-mandated upgrades, Germany's real-time adjudication pilots, and India's greenfield digitization wave. Monitor CMS rulemaking on price transparency and prior authorization automation as the decisive inflection signal for platform replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Prior Authorization Automation Module Development | CMS mandates for automated decisioning are expanding eligibility verification volumes between hospitals and United States insurers. |
| FHIR Mapping and Legacy Conversion Utility Investment | Health systems struggle to recruit developers capable of bridging HL7 v2 interfaces with modern API gateways. |
| Notified Body Relationship Establishment | EU AI Act risk classification imposes conformity assessments on automated claims adjudication algorithms used by European health insurers. |
| Real-Time Payment Rail Integration Partnership | Germany's statutory health insurance funds are accelerating pilots to compress claims settlement windows from batch to instant cycles. |
| ABHA-Linked Direct Connectivity Architecture Deployment | India's national health ID infrastructure creates greenfield EDI opportunities for private insurers expanding beyond legacy paper workflows. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Canada, with primary inputs from each market's health system procurement committees, payer technology executives, EDI vendor product managers, and regulatory affairs specialists specializing in HIPAA, EU AI Act, and Gematik compliance. Secondary validation drew from CMS Medicare claims data, hospital procurement databases, GPO contract filings, FDA software-as-medical-device guidance documents, and EMA notified body conformity assessment records. The analytical framework combined bottom-up transaction volume modeling with top-down healthcare IT expenditure allocation analysis.
Granularity-level modeling segmented the market by product architecture, deployment mode, application workflow, and end-user category, with additional dimensioning by interoperability standard adoption pattern and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical EDI transaction volume trajectories and projected healthcare digitization investment flows across the analysis window. Forecast inputs incorporated cloud infrastructure capex disclosures from major platform providers, health system EHR replacement cycle timing, and statutory automation mandate implementation schedules.
The model assumes a particular technology adoption path favoring API-first architectures over legacy batch systems; alternative pathways for HL7 v2 interface persistence or hybrid cloud retention would alter the outlook for platform replacement velocity and vendor market share distribution. Forecasts reflect assumptions regarding regulatory timeline adherence, interoperability standard convergence, and payer consolidation patterns that could compress or extend implementation windows. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Consumer Genomics Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
AI in Healthcare Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
EHR EMR Market
Health Informatics
Clinical Intelligence Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Laboratory Informatics Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Global Health IT Security Market