
 Ambulatory Electronic Health Record Market | 2026-2036
Ambulatory Electronic Health Record Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Electronic Health Record Market Intelligence
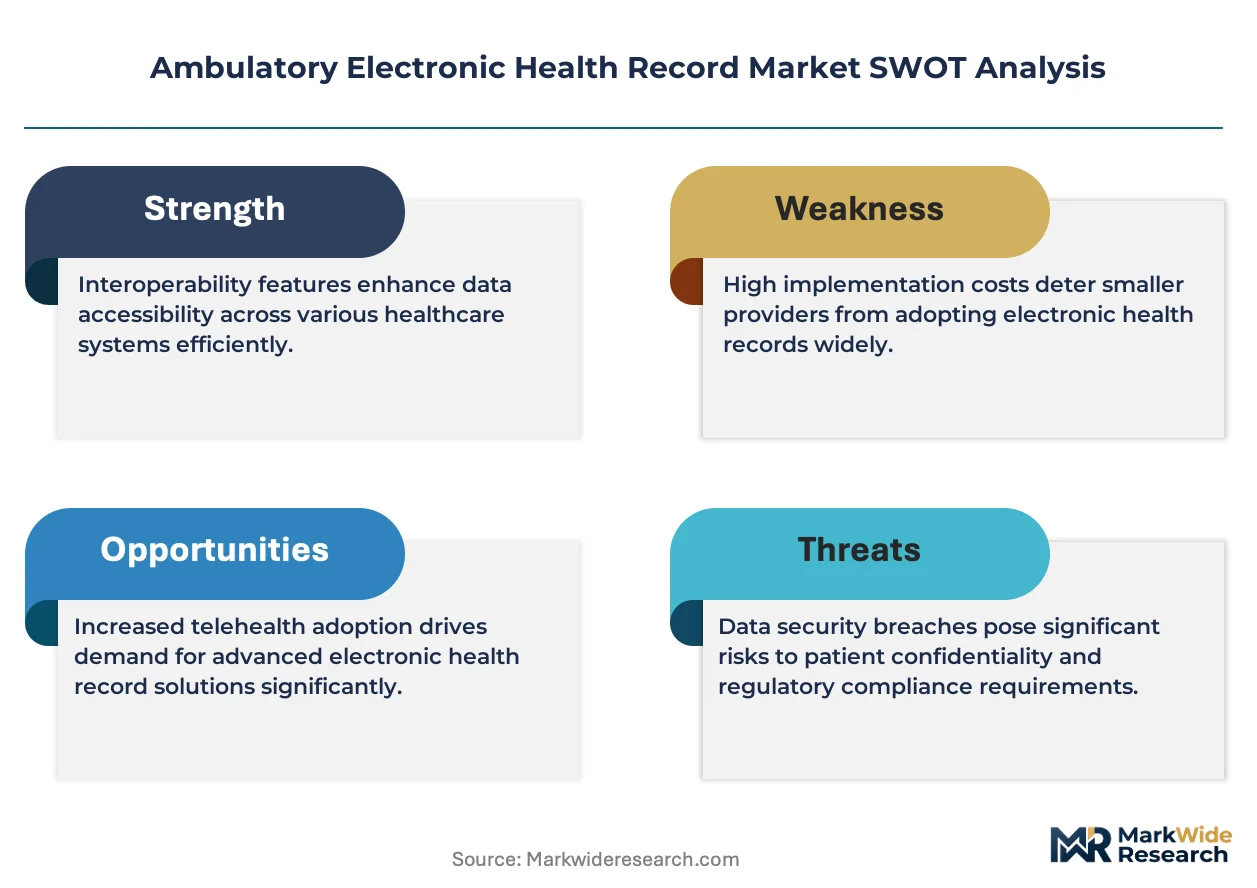
ONC Health IT Certification is rotating the competitive landscape by mandating standardized APIs and interoperability protocols that determine vendor eligibility for federal reimbursement programs. Epic Systems Corporation leverages its deep integration with academic medical centers to extend ambulatory reach into affiliated outpatient networks. Oracle Cerner anchors enterprise-scale deployments across multi-site physician practices with heavy R&D investment in cloud migration toolkits. MEDITECH competes on cost-efficient on-premise solutions that sustain loyalty among mid-sized community clinics with limited IT budgets.
An ambulatory electronic health record is a digital information system designed for outpatient care settings, typically featuring clinical documentation templates, e-prescribing modules, and bidirectional health information exchange capabilities operating on HL7 FHIR standards. Its primary purpose is to coordinate patient encounters across non-hospital settings while enabling quality reporting and revenue cycle management. Cloud-based product types are capturing the fastest expansion as physician practices abandon capital-intensive server infrastructure, though on-premise installations retain margin pools among security-sensitive specialty clinics. Deployment through Software as a Service models concentrates demand among urgent care facilities seeking rapid scalability without dedicated IT staff.
ONC certification requirements and HIPAA security rules in the United States create compliance thresholds that filter smaller vendors from federal incentive eligibility. The EU AI Act and GDPR impose additional algorithmic transparency and data residency constraints on ambulatory EHR vendors serving European outpatient networks. Stakeholders must monitor how interoperability mandates in multiple jurisdictions reshape R&D allocation between cloud-native architecture and legacy system modernization.
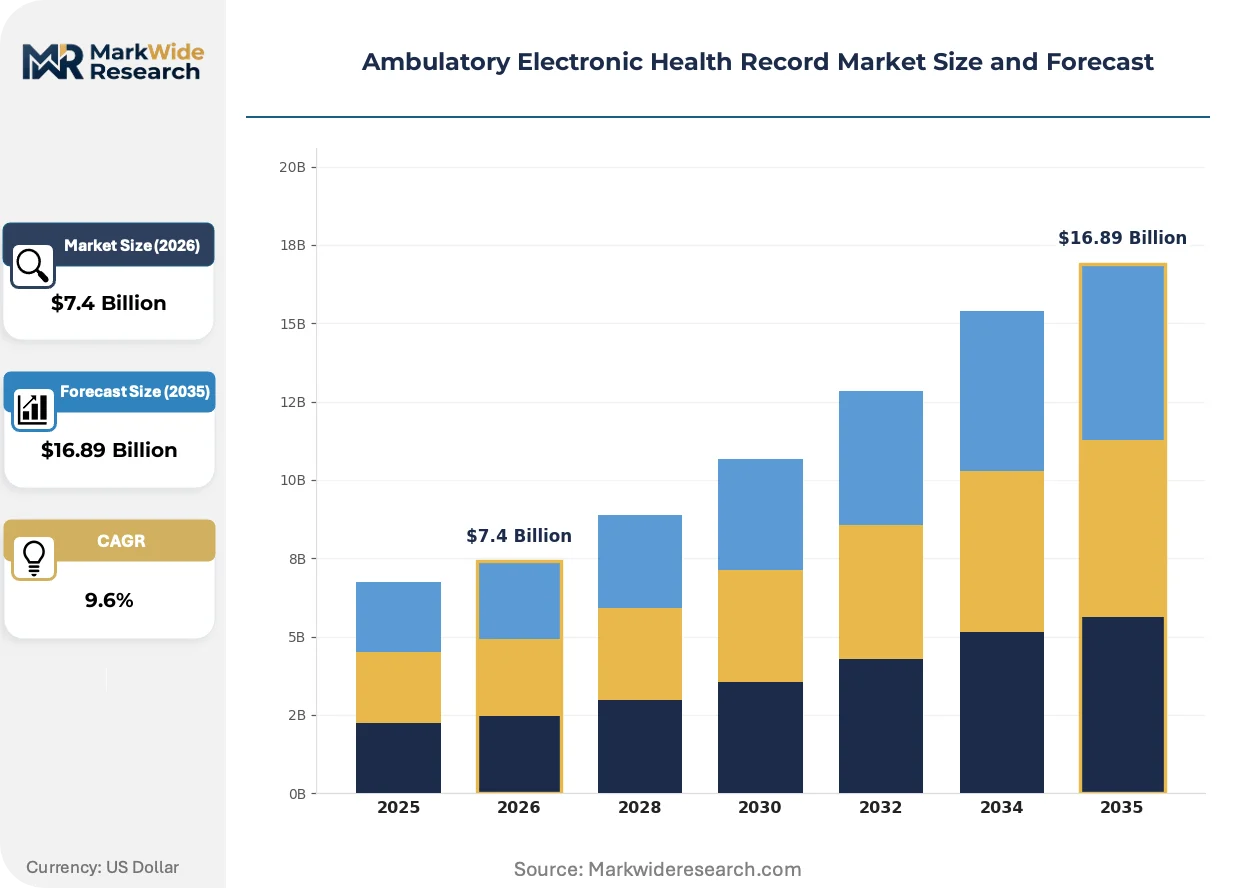
Market Dynamics
Cloud migration is decomposing the installed base of on-premise ambulatory EHR systems, forcing vendors to restructure pricing models and support architectures around subscription economics rather than perpetual licenses.
Growth Catalysts
- 21st Century Cures Act:ONC interoperability mandates in the United States compel outpatient networks to upgrade certified systems, creating replacement demand across physician practices.
- HL7 FHIR APIs:Standardized data exchange protocols enable bidirectional connectivity between ambulatory clinics and hospital networks, reducing integration friction.
- Specialty clinic expansion:Dermatology and cardiology outpatient centers in Texas and Florida are deploying scalable EHR modules to manage patient volume spikes.
Market Restraints
- HIPAA security rule compliance:Encryption and access control requirements impose ongoing operational costs that strain independent physician practices with limited IT staffing.
- Data center concentration:Cloud infrastructure dependencies on hyperscale providers in Northern Virginia and Oregon create geographic resilience risks for SaaS-based deployments.
- Legacy system entrenchment:Decades of customized on-premise configurations in community health centers generate switching friction that delays modernization timelines.
Strategic Opportunities
- EU AI Act algorithmic transparency:European outpatient networks require explainable clinical decision support modules, opening demand for compliant AI-integrated EHR platforms.
- Rural health clinic penetration:Federally qualified health centers in Mississippi and Alabama remain underpenetrated by cloud-native vendors due to broadband infrastructure gaps.
- Remote patient monitoring convergence:Integration of wearable device data streams with ambulatory EHR workflows creates new subscription revenue pools for chronic care management.
Industry Challenges
- ONC certification timeline compression:Version upgrade cycles for federal incentive eligibility require engineering resources that smaller vendors struggle to allocate.
- Interoperability testing complexity:Validating bidirectional data exchange across heterogeneous EHR platforms demands specialized integration engineering talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Electronic Health Record Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.89 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Web-based Therapy Area: Primary Care, Dermatology, Psychiatry, Cardiology, Endocrinology End User: Physician Practices, Ambulatory Surgery Centers, Specialty Clinics, Urgent Care Facilities Deployment: Software as a Service, Licensed Software, Managed Services, Hosted Solutions |
| Companies Covered | Epic Systems Corporation, Oracle Cerner, MEDITECH, TruBridge, Veradigm Inc, athenahealth, NextGen Healthcare, eClinicalWorks, AdvancedMD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Electronic Health Record Market Strategic Shifts & Innovations
Containerized microservices architectures are fragmenting monolithic EHR codebases, enabling modular deployment that aligns vendor capabilities with specific outpatient workflow requirements rather than forcing standardized suites.
Serverless computing infrastructure is decomposing traditional three-tier application stacks in ambulatory EHR deployments. Urgent care chains in Arizona and Nevada are adopting function-as-a-service backends to eliminate server maintenance overhead. This shift is compressing total cost of ownership for multi-site physician practices while accelerating feature release cycles.
GDPR data residency requirements in Europe are mandating regional cloud instance isolation for ambulatory EHR vendors serving German and French outpatient networks. The regulation forces architectural replication across sovereign data centers. Specialty clinics in Bavaria and Île-de-France are prioritizing vendors with EU-based infrastructure over US-centric hosting.
Subscription-based procurement is displacing capital expenditure models among independent physician associations in California and New York. Purchasers are unbundling implementation services from software licenses and negotiating outcome-based support tiers. This behavioral shift concentrates negotiating leverage with large group purchasing organizations at the expense of direct vendor relationships.
Ambulatory Electronic Health Record Market Segmentation
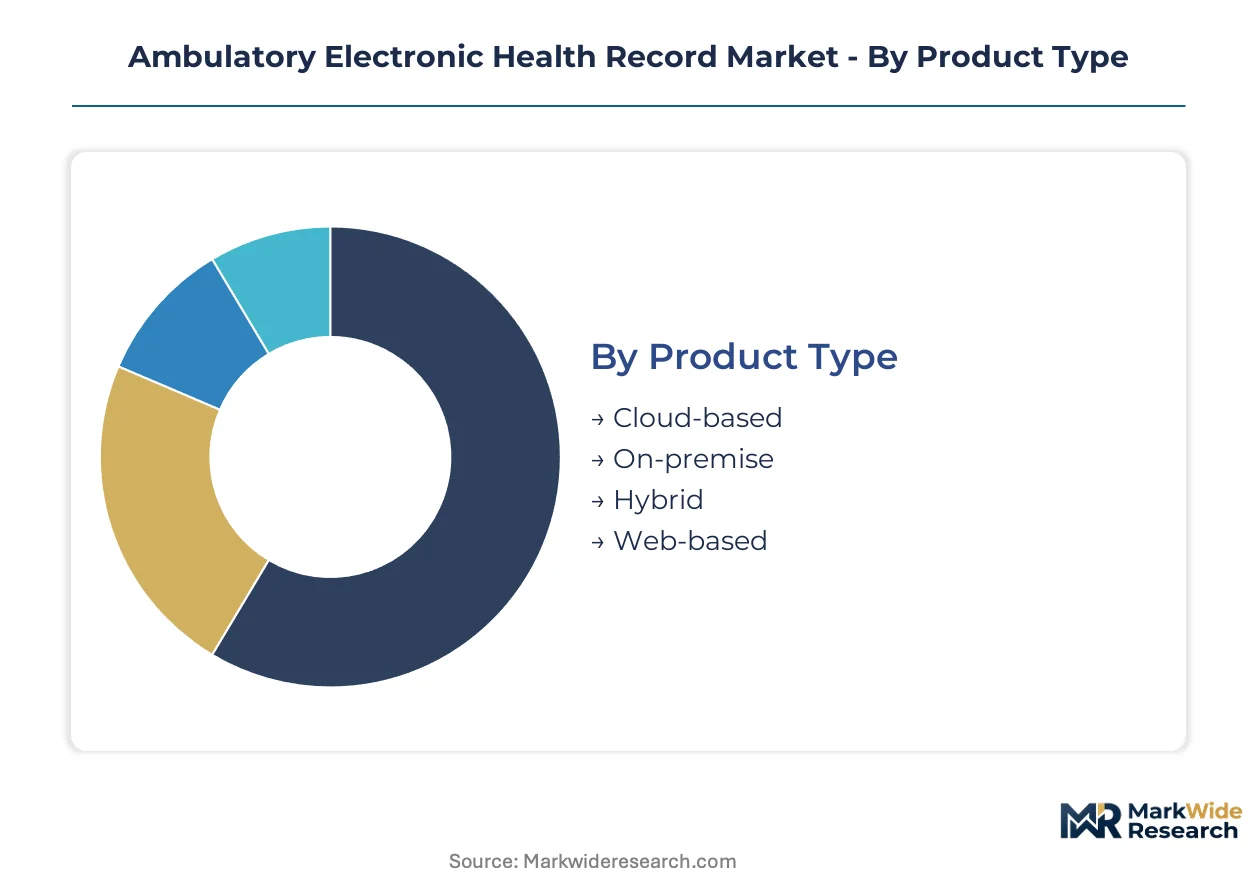
Segmentation in ambulatory EHR markets reveals how regulatory mandates and infrastructure constraints reshape procurement patterns across outpatient networks. Vendors must align certification status, deployment architecture, and specialty workflow modules to capture replacement cycles triggered by ONC interoperability deadlines.
Product Type:
ONC certification requirements and HIPAA security rules create divergent compliance burdens across deployment architectures, filtering vendor eligibility for federal incentive programs.
- Cloud-based:Multi-tenant SaaS architectures eliminate capital-intensive server infrastructure for physician practices. Demand concentrates among urgent care chains in Texas and Florida seeking rapid scalability without dedicated IT staffing. ONC mandates for standardized APIs accelerate replacement of legacy client-server installations.
- On-premise:Locally hosted systems retain dedicated hardware stacks within clinic data centers. Security-sensitive specialty clinics in Bavaria and Île-de-France prioritize these configurations to satisfy GDPR data residency requirements over US-centric cloud hosting. Customized configurations generate switching friction that delays modernization.
- Hybrid:Split architectures maintain sensitive patient data on local servers while routing administrative functions to cloud tiers.
- Web-based:Browser-accessible platforms deliver thin-client functionality without local installation requirements.
Established volume favors on-premise; emerging adoption favors cloud-based.
Therapy Area:
Specialty-specific documentation templates and quality reporting requirements drive divergent R&D allocation across clinical domains.
- Primary Care:Generalist workflows encompass preventive care, chronic disease management, and referral coordination across heterogeneous patient populations. Federally qualified health centers in Mississippi and Alabama deploy these modules to satisfy Medicaid quality metrics. HL7 FHIR integration enables bidirectional exchange with hospital networks.
- Dermatology:Image-centric documentation systems incorporate dermoscopy storage, lesion tracking algorithms, and pathology interface requirements. Outpatient centers in Arizona and Nevada prioritize scalable modules to manage volume spikes from cosmetic procedure demand. EU AI Act transparency mandates reshape clinical decision support procurement.
- Psychiatry:Behavioral health platforms emphasize discrete encounter documentation and controlled substance monitoring.
- Cardiology:ECG integration, implantable device data ingestion, and procedural coding complexity define vendor selection criteria.
- Endocrinology:Continuous glucose monitor data streams and insulin dosing algorithms require specialized interoperability protocols.
Primary care commands the largest installed base; dermatology exhibits the steepest expansion trajectory.
End User:
Procurement authority and IT staffing levels determine deployment complexity tolerance across outpatient facility types.
- Physician Practices:Independent and group practices prioritize subscription economics over capital expenditure, unbundling implementation services from software licenses. Purchasers in California and New York negotiate outcome-based support tiers through group purchasing organizations.
- Ambulatory Surgery Centers:Same-day surgical facilities require anesthesia documentation, implant tracking, and ASC-specific quality reporting modules. Regulatory compliance with Medicare conditions for coverage shapes vendor certification requirements.
- Specialty Clinics:Focused outpatient centers demand procedure-specific templates and device integration capabilities.
- Urgent Care Facilities:High-volume, episodic care settings prioritize rapid patient throughput and minimal training overhead.
Physician practices anchor current revenue; ambulatory surgery centers are gaining share fastest.
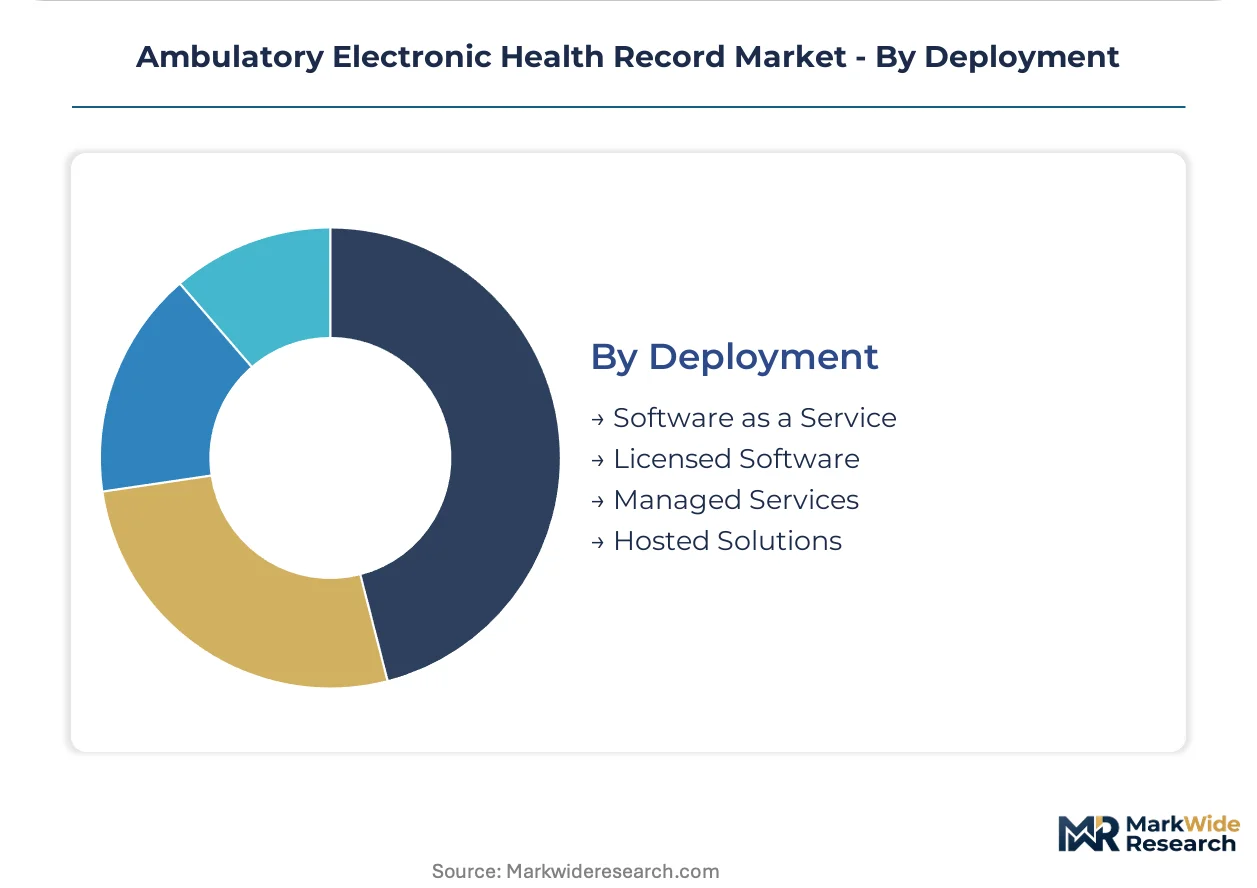
Deployment:
Pricing model selection reflects working capital constraints and risk transfer preferences across purchaser segments.
- Software as a Service:Subscription pricing eliminates upfront license fees while transferring infrastructure maintenance to vendors. Urgent care chains adopt function-as-a-service backends to compress total cost of ownership.
- Licensed Software:Perpetual ownership models retain margin pools among security-sensitive buyers with established IT departments.
- Managed Services:Outsourced operational responsibility bundles hosting, security monitoring, and version management under fixed fees.
- Hosted Solutions:Single-tenant cloud deployments isolate client data within dedicated virtual infrastructure.
Licensed software dominates legacy accounts; SaaS is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal reimbursement eligibility drives procurement urgency across outpatient networks. The 21st Century Cures Act mandates ONC-certified interoperability standards that filter vendor participation in incentive programs. Geographic variation in compliance timelines and infrastructure maturity shapes replacement cycles.
United States
Physician practices in Texas and Florida deploy cloud-based modules to manage volume spikes from specialty clinic expansion. HIPAA security rules and ONC certification requirements create compliance thresholds that strain independent practices with limited IT staffing. Northern Virginia and Oregon host hyperscale data centers that concentrate SaaS infrastructure for urgent care chains.
Germany
Specialty clinics in Bavaria prioritize on-premise configurations to satisfy GDPR data residency requirements over US-centric cloud hosting. The EU AI Act imposes algorithmic transparency mandates that reshape clinical decision support procurement patterns. Frankfurt and Munich anchor regional cloud instance deployments for vendors serving German outpatient networks.
France
Outpatient centers in Île-de-France select vendors with EU-based infrastructure to meet GDPR sovereignty constraints. The CNIL enforces data localization rules that force architectural replication across sovereign data centers. Paris clusters host specialized dermatology and cardiology practices deploying scalable EHR modules.
United Kingdom
NHS Digital interoperability frameworks compel ambulatory networks to upgrade certified systems for bidirectional hospital connectivity. The Medicines and Healthcare products Regulatory Agency oversees software as medical device classifications affecting clinical decision support modules. London and Greater Manchester concentrate multi-site physician practices negotiating subscription-based procurement.
India
Telemedicine expansion in Karnataka and Telangana drives demand for web-accessible EHR platforms among outpatient networks. The Ministry of Health and Family Welfare promotes digital health mission standards that accelerate cloud adoption. Bangalore and Hyderabad host health-tech clusters developing modular ambulatory systems for domestic and export markets.
Ambulatory Electronic Health Record Market Key Industry Players
Player mix skews toward integrated health IT conglomerates with enterprise-scale deployment capabilities. The vendor base concentrates around three tiers: academic medical center anchors, mid-market SaaS specialists, and legacy on-premise incumbents. Dominant competitive moves include cloud migration toolkit development and interoperability certification acceleration.
Within the academic medical center tier, Epic Systems Corporation and Oracle Cerner occupy positions as scale-driven deployers across multi-site outpatient networks. MEDITECH represents the cost-efficient on-premise archetype sustaining loyalty among budget-constrained community clinics. These three entities exemplify the strategic divergence between cloud-native expansion and legacy system entrenchment reshaping vendor competitive dynamics.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Cerner |
| MEDITECH |
| TruBridge |
| Veradigm Inc |
| athenahealth |
| NextGen Healthcare |
| eClinicalWorks |
| AdvancedMD |
| Others |
Cost & Logistics Intelligence
ONC Health IT Certification gates both vendor qualification and price differentiation simultaneously, filtering smaller developers from federal reimbursement eligibility while stratifying subscription tiers across deployment architectures. Cloud-native vendors command premium positioning against legacy on-premise incumbents serving budget-constrained community clinics.
Pricing Analysis
Certification level creates the primary spread across subscription tiers, with ONC-certified SaaS platforms commanding 40-60% premiums over non-certified alternatives among physician practices seeking federal incentive eligibility. Price differentiation rests on interoperability maturity and specialty workflow depth, with dermatology and cardiology modules extracting higher per-seat fees than primary care configurations. Pricing pressure stems from hyperscaler infrastructure cost compression as AWS and Azure compete for healthcare workloads. Independent physician associations exhibit highest price sensitivity, while academic medical center networks prioritize integration depth over unit economics.
Supply Chain Analysis
Just-in-time deployment preferences dominate urgent care procurement, with containerized microservices enabling rapid provisioning without capital-intensive hardware staging. Software engineering talent concentrates in the United States, India, and Ireland, with Bangalore and Hyderabad health-tech clusters feeding module development pipelines. Cloud infrastructure dependencies draw from hyperscale data centers in Northern Virginia, Oregon, and Frankfurt, creating geographic concentration risk for SaaS availability. Distribution runs through direct vendor sales organizations and group purchasing organizations, with the latter consolidating negotiating leverage among multi-site physician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity for HL7 FHIR integration and ONC certification compliance reshapes competitive dynamics, favoring vendors with established regulatory affairs capabilities over pure-play technology developers.
For Market Incumbents: Fortify cloud migration toolkits against Oracle Cerner and Epic Systems' enterprise-scale deployments by accelerating serverless backend development for urgent care chains. Deepen interoperability certification investment to maintain federal incentive eligibility as ONC timeline compression filters smaller competitors. Anchor position in academic medical center affiliates where switching costs protect recurring revenue streams from SaaS challengers. For New Entrants and Emerging Players: Rural health clinic broadband infrastructure gaps present under-served deployment opportunities where cloud-native vendors struggle to penetrate. Target federally qualified health centers in Mississippi and Alabama with offline-capable hybrid architectures that synchronize intermittently. Pursue partnership-first go-to-market models with regional telecommunication providers to bundle connectivity with EHR subscriptions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS-native ambulatory platforms as containerization eliminates server maintenance overhead. Long-term viability favors acquisition targets with established ONC certification pipelines and specialty clinic module libraries rather than generalist primary care platforms. Monitor ONC version upgrade compliance rates as inflection indicator for vendor engineering resource adequacy.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Acceleration | Federal reimbursement eligibility hinges on standardized API compliance timelines. |
| Specialty Module Development | Dermatology and cardiology workflows command premium subscription positioning. |
| Cloud Migration Toolkit Investment | Serverless backends compress total cost of ownership for multi-site practices. |
| Interoperability Partnership | HL7 FHIR integration enables bidirectional hospital network connectivity. |
| Rural Infrastructure Penetration | Federally qualified health centers remain under-served by broadband-dependent vendors. |
Research Approach
Operator-level perspectives from ambulatory EHR product managers, hospital CIOs, GPO contracts managers, and ONC certification specialists anchored the qualitative base. Secondary validation drew from CMS Medicare reimbursement databases, ONC certified health IT product listings, hospital procurement contract disclosures, and hyperscaler healthcare vertical revenue filings. Bottom-up deployment estimates across physician practices, specialty clinics, and urgent care facilities triangulated against top-down vendor revenue segmentation.
Sensitivity analysis tested cloud adoption velocity assumptions and ONC compliance deadline shifts across the projection horizon. The analytical framework modeled segmentation across deployment architecture, therapy area, end-user facility type, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and interoperability mandate implementation schedules. Forecast inputs incorporated HL7 FHIR adoption rates and specialty clinic expansion patterns.
Underlying assumptions cover cloud infrastructure cost trajectories and federal incentive program continuity, with deviation risk concentrated in ONC certification timeline compression and GDPR data residency enforcement intensity. Revision becomes warranted when interoperability testing complexity triggers vendor exit rates exceeding modeled thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
EHR EMR Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Health IT Security Market
Health Informatics
Healthcare API Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Vocal Biomarkers Market