
 Global E-Health Market | 2026-2036
Global E-Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Health Market Foresight
Telemedicine distribution is rewriting how health systems reach patients outside traditional facilities. Epic Systems leverages its dominant position in electronic health records to anchor hospital-centric e-health networks across North America. Teladoc Health competes through employer and payer channels, sustaining virtual-first primary care models that bypass conventional referral structures. Koninklijke Philips differentiates via integrated remote patient monitoring hardware and software stacks that extend its cardiology and respiratory diagnostics footprint into home settings.
E-health encompasses digital technologies, information systems, and telecommunication infrastructure designed to deliver, manage, and exchange health services and medical data across distributed care environments. The field relies on HL7 FHIR interoperability standards, encrypted data transmission protocols, and cloud-native architectures to enable real-time clinical workflows and longitudinal patient record access. Telemedicine platforms and remote patient monitoring together command the largest addressable segments, with cloud-based deployment models capturing disproportionate growth as health systems abandon legacy on-premise infrastructure. Mobile health apps represent the fastest-expanding category, though margin pools remain concentrated in health information systems and clinical decision support tools sold to hospital end users.
FDA digital health pre-certification programs and EMA medical device regulation frameworks shape product development timelines and market entry pathways for software-as-medical-device offerings. HIPAA in the United States and GDPR in Europe impose data governance requirements that directly influence architecture decisions and cross-border service delivery models. Stakeholders must monitor evolving reimbursement codes from CMS and national health technology assessment bodies, as payment parity determinations between virtual and in-person care will dictate platform economics and provider adoption velocity.
Market Dynamics
Interoperability mandates from FDA and EMA are forcing health systems to replace fragmented electronic record architectures with unified data fabrics that enable real-time clinical decision-making across distributed care networks.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare's expanded coverage for remote patient monitoring creates direct revenue pathways for hospital systems deploying connected diagnostic devices in home settings.
- Germany's Digital Healthcare Act:Statutory health insurance funds now reimburse prescribed digital health applications, accelerating provider adoption of validated therapeutic software.
- HL7 FHIR Standardization:The interoperability framework enables seamless data exchange between disparate hospital information systems, reducing integration friction for new platform vendors.
Market Restraints
- GDPR Cross-Border Friction:European data localization requirements block cloud-based patient record hosting outside EU jurisdictions, fragmenting service delivery architectures for multinational health systems.
- Cybersecurity Insurance Costs:Ransomware attacks against hospital networks have tripled cyber liability premiums, consuming IT budgets that would otherwise fund platform modernization.
- Legacy EHR Lock-In:Proprietary data formats from dominant hospital information system vendors create switching costs that delay competitive platform adoption by five to seven years.
Strategic Opportunities
- India's Telemedicine Guidelines:The national framework legitimizing remote consultations opens addressable demand among 600 million rural residents lacking specialist access.
- AI-Augmented Triage:Machine learning integration with symptom checkers and clinical decision support creates new reimbursement categories for automated preliminary diagnosis.
- Direct-to-Employer Channels:Self-insured corporations are contracting virtual-first primary care directly, bypassing traditional payer intermediaries and capturing longitudinal patient relationships.
Industry Challenges
- Clinical Workflow Integration:Frontline physicians resist platforms that require duplicate data entry across EHR and telemedicine interfaces, eroding adoption rates despite administrative mandates.
- Interoperability Certification Delays:FDA pre-certification timelines for software-as-medical-device products extend 18-24 months, compressing commercialization windows before reimbursement codes update.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Health Market |
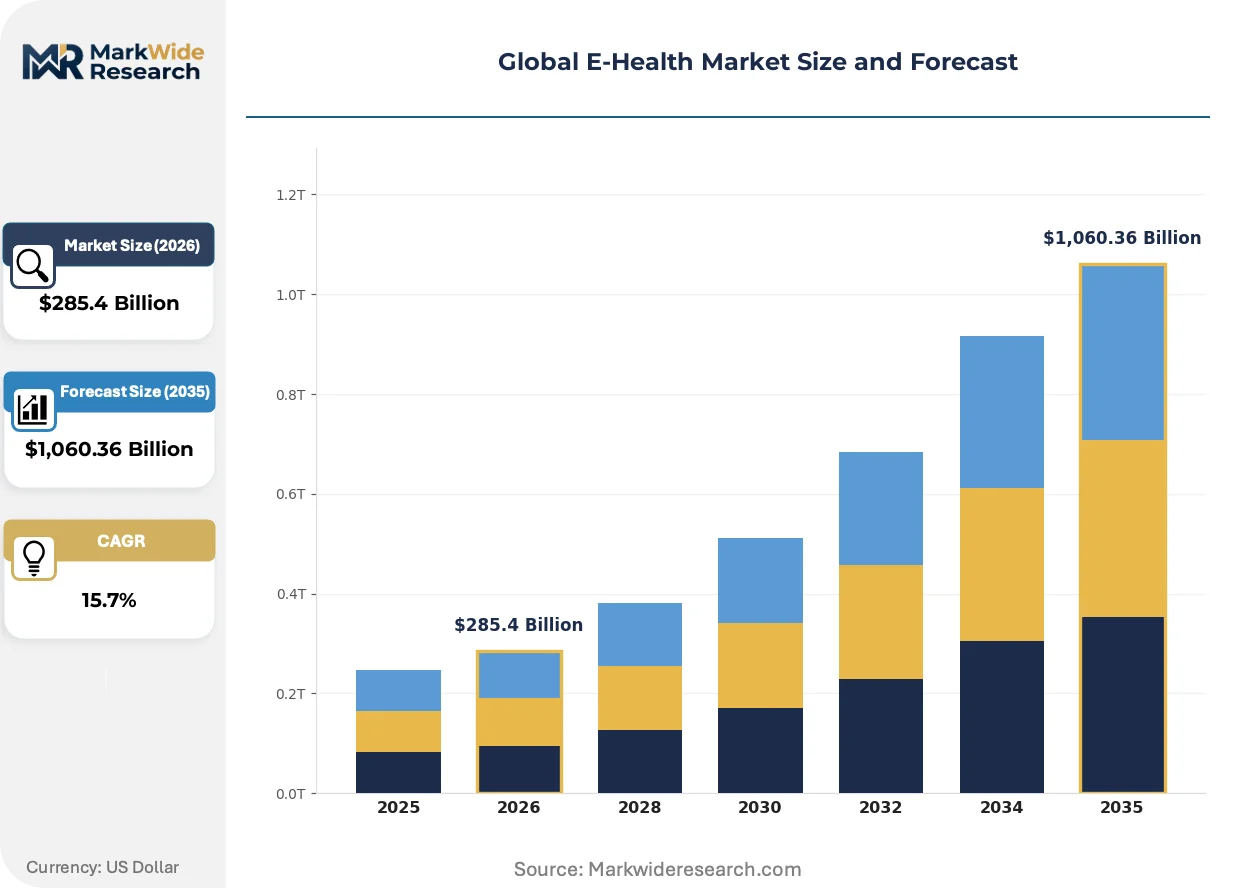
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $1,060.36 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Telemedicine Platforms, Remote Patient Monitoring, Health Information Systems, Mobile Health Apps, Clinical Decision Support, Electronic Health Records Application: Chronic Disease Management, Mental Health Management, Preventive Care, Wellness Programs, Medication Adherence, Postoperative Care End User: Hospitals, Ambulatory Centers, Diagnostic Laboratories, Home Care Providers, Pharmaceutical Companies, Health Insurance Firms Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Web-Based, Mobile-Based |
| Companies Covered | Teladoc Health, Epic Systems, Athenahealth, Oracle, Koninklijke Philips, Siemens Healthineers, GE Healthcare, Medtronic, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Health Market Shifts & Advancements
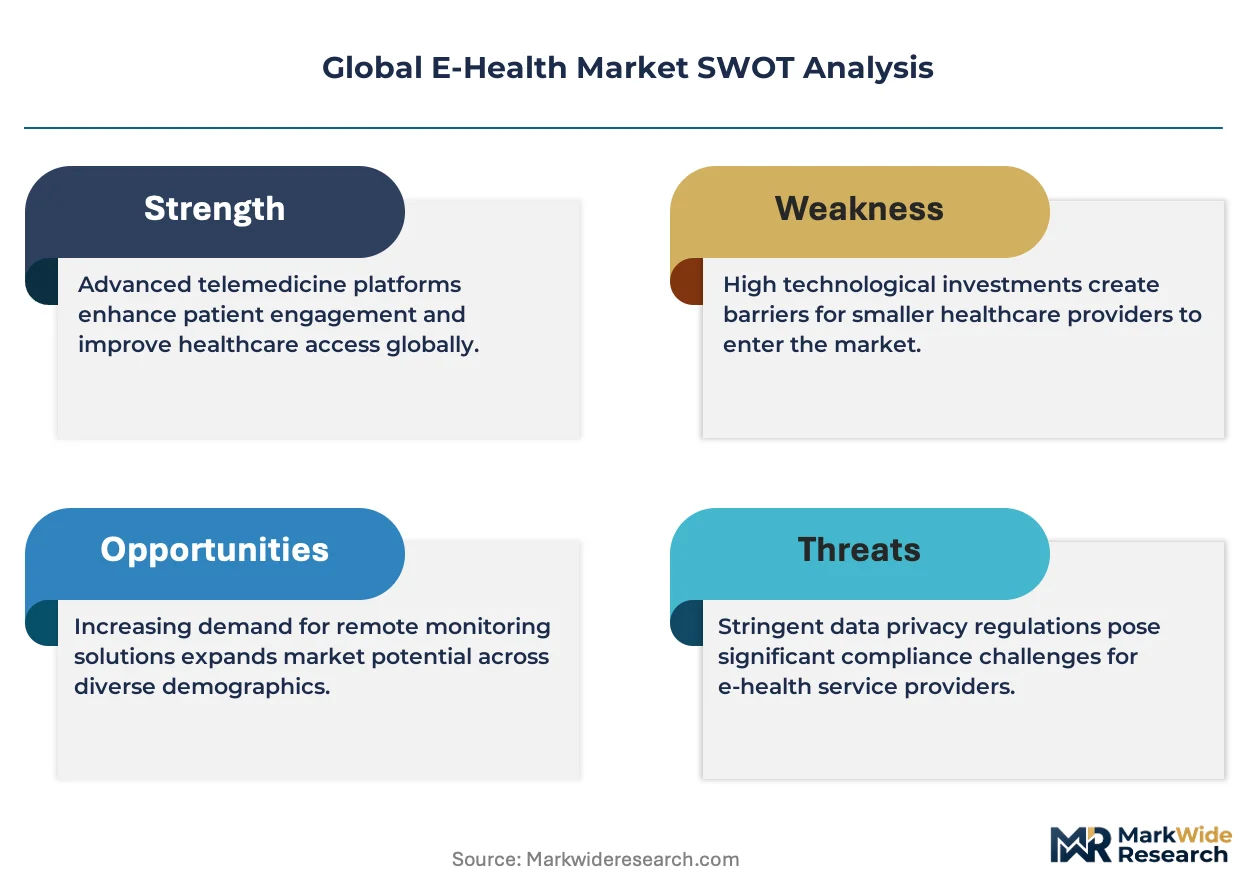
Artificial intelligence and ambient clinical intelligence are compressing documentation burden while regulatory pressure on algorithmic transparency is reshaping product development priorities across the sector.
Natural language processing is digitizing clinical encounter documentation by automatically generating structured encounter records from provider-patient conversations. Hospital systems in the United States are deploying ambient scribing tools across emergency departments and primary care clinics at scale. This technology is digitizing the cognitive load of administrative work, reallocating clinician hours from keyboards to direct patient contact.
EMA's Medical Device Regulation framework now classifies diagnostic algorithms as Class IIa or higher medical devices, requiring clinical evidence submissions and notified body review. Software vendors must maintain quality management systems and post-market surveillance comparable to hardware manufacturers. European health technology assessment bodies are withholding reimbursement for unvalidated AI diagnostic tools, accelerating consolidation toward vendors with regulatory infrastructure.
Employer-sponsored health benefits are unbundling virtual care from traditional medical plan structures. Large self-insured corporations in the United States are contracting directly with telemedicine platforms for primary care, mental health, and chronic disease management. This channel rotation is most visible among technology and financial services employers seeking to differentiate recruitment and reduce medical trend costs.
Global E-Health Market Segmentation
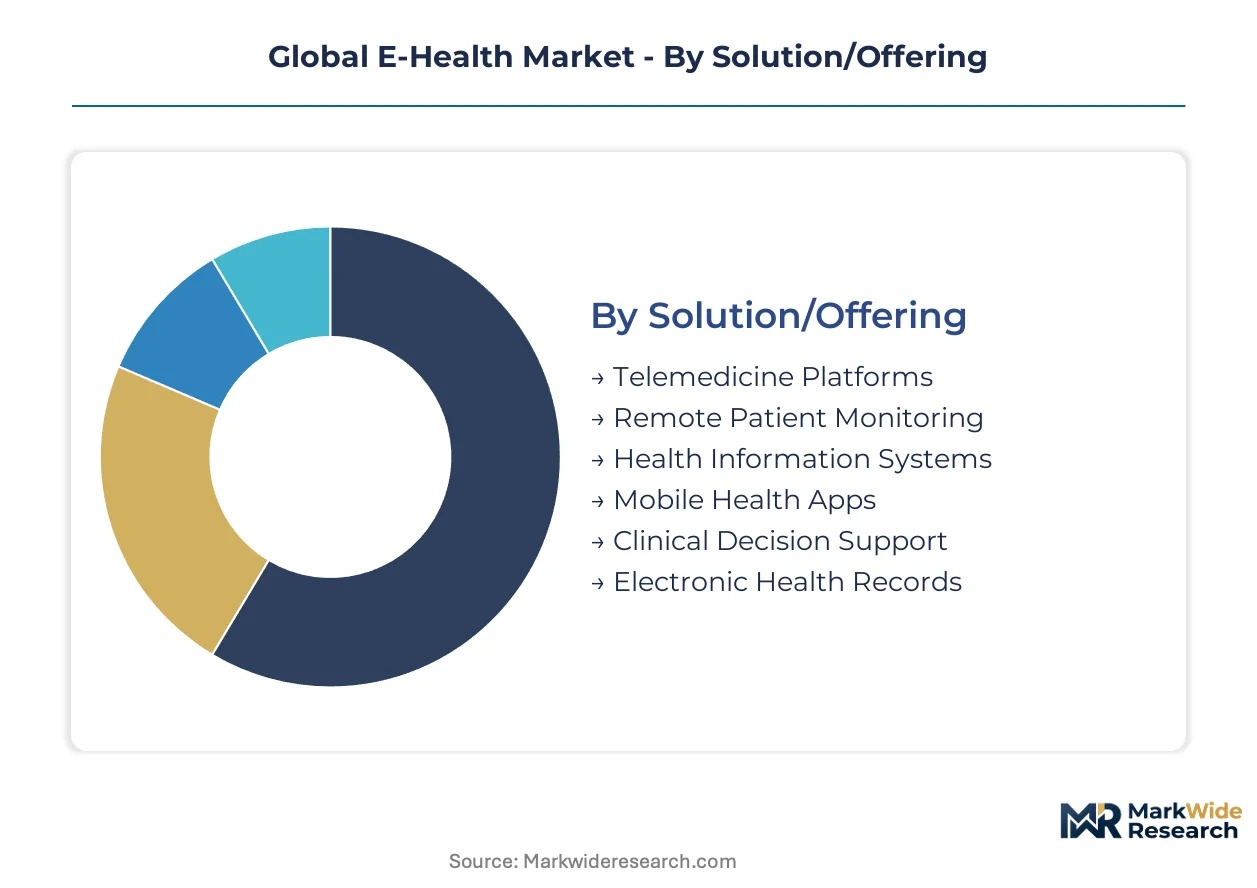
E-health market segmentation reveals distinct technology stacks, clinical workflows, and procurement patterns that determine vendor positioning and margin capture. Each dimension—solution type, application focus, end-user configuration, and deployment architecture—creates separate competitive arenas with unique regulatory requirements and integration challenges.
Solution/Offering:
Use-case spectrum spans acute intervention platforms through longitudinal record systems, with hardware-software integration intensity varying dramatically across categories.
- Telemedicine Platforms:Real-time video consultation infrastructure with embedded scheduling, billing, and prescription modules. Demand concentrates among rural hospital networks in the United States and India where CMS reimbursement expansion and national telemedicine guidelines respectively remove payment barriers for virtual encounters.
- Remote Patient Monitoring:Connected diagnostic devices transmitting biometric data to clinical dashboards for continuous oversight. Germany's Digital Healthcare Act reimbursement for prescribed monitoring applications is accelerating hospital deployment of cardiology and respiratory tracking systems in home settings.
- Health Information Systems:Administrative and operational platforms managing patient flow, resource allocation, and revenue cycle functions.
- Mobile Health Apps:Consumer-facing symptom trackers, medication reminders, and wellness tools operating on smartphone ecosystems.
- Clinical Decision Support:AI-augmented diagnostic assistance and treatment recommendation engines integrated at point-of-care.
- Electronic Health Records:Core longitudinal data repositories with interoperability mandates from FDA and EMA forcing architectural upgrades to HL7 FHIR standards.
The dominant share belongs to Electronic Health Records, while Mobile Health Apps is closing the gap fastest.
Application:
Cost tier differentiation separates high-acuity condition management from preventive engagement models, with reimbursement codes determining platform economics.
- Chronic Disease Management:Diabetes, hypertension, and heart failure programs combining remote monitoring with care coordination. United States self-insured employers are contracting directly for these services to reduce medical trend costs among covered populations.
- Mental Health Management:Virtual therapy, psychiatric consultation, and behavioral health coaching delivered through employer-sponsored benefits. European GDPR localization requirements create architectural friction for multinational corporations seeking unified mental health platforms across jurisdictions.
- Preventive Care:Screening reminders, risk assessment tools, and lifestyle intervention programs.
- Wellness Programs:Fitness tracking, nutrition coaching, and stress management for healthy population segments.
- Medication Adherence:Smart pill dispensers, refill automation, and compliance monitoring for polypharmacy patients.
- Postoperative Care:Surgical recovery tracking, wound monitoring, and rehabilitation coordination reducing readmission penalties.
Chronic Disease Management commands the largest addressable spend, though Mental Health Management is expanding most quickly as employer benefits unbundle from traditional medical plans.
End User:
Customer type determines procurement complexity, with hospital systems requiring enterprise integration versus home care providers prioritizing standalone usability.
- Hospitals:Integrated delivery networks requiring seamless EHR-telemedicine interoperability. Legacy EHR lock-in from dominant vendors creates five-to-seven-year switching costs that delay competitive platform adoption despite administrative mandates.
- Ambulatory Centers:Outpatient clinics and specialty practices seeking lightweight virtual care tools without enterprise IT overhead.
- Diagnostic Laboratories:Specimen processing facilities requiring results delivery and patient notification systems.
- Home Care Providers:Skilled nursing and personal care agencies deploying remote monitoring for dispersed patients.
- Pharmaceutical Companies:Drug manufacturers utilizing digital therapeutics and patient support programs for adherence and outcomes data.
- Health Insurance Firms:Payers building direct-to-member virtual primary care channels to capture longitudinal relationships.
Hospitals retain the dominant procurement volume, yet Health Insurance Firms are gaining share fastest as direct-to-employer contracting bypasses traditional intermediaries.
Deployment:
Maturity gradient separates legacy on-premise installations from cloud-native architectures, with hybrid models bridging transition phases.
- Cloud-Based:Fully managed SaaS infrastructure with automatic updates and elastic scaling. Health systems are abandoning legacy on-premise infrastructure disproportionately for this model as cybersecurity insurance costs consume modernization budgets.
- On-Premise:Self-hosted servers within institutional data centers retaining direct physical control over patient records.
- Hybrid:Split architectures keeping sensitive data local while leveraging cloud analytics and backup.
- SaaS:Subscription software licensing with vendor-managed maintenance and feature roadmaps.
- Web-Based:Browser-accessible platforms requiring no local installation for clinical users.
- Mobile-Based:Native smartphone and tablet applications for patient-facing engagement and provider point-of-care tools.
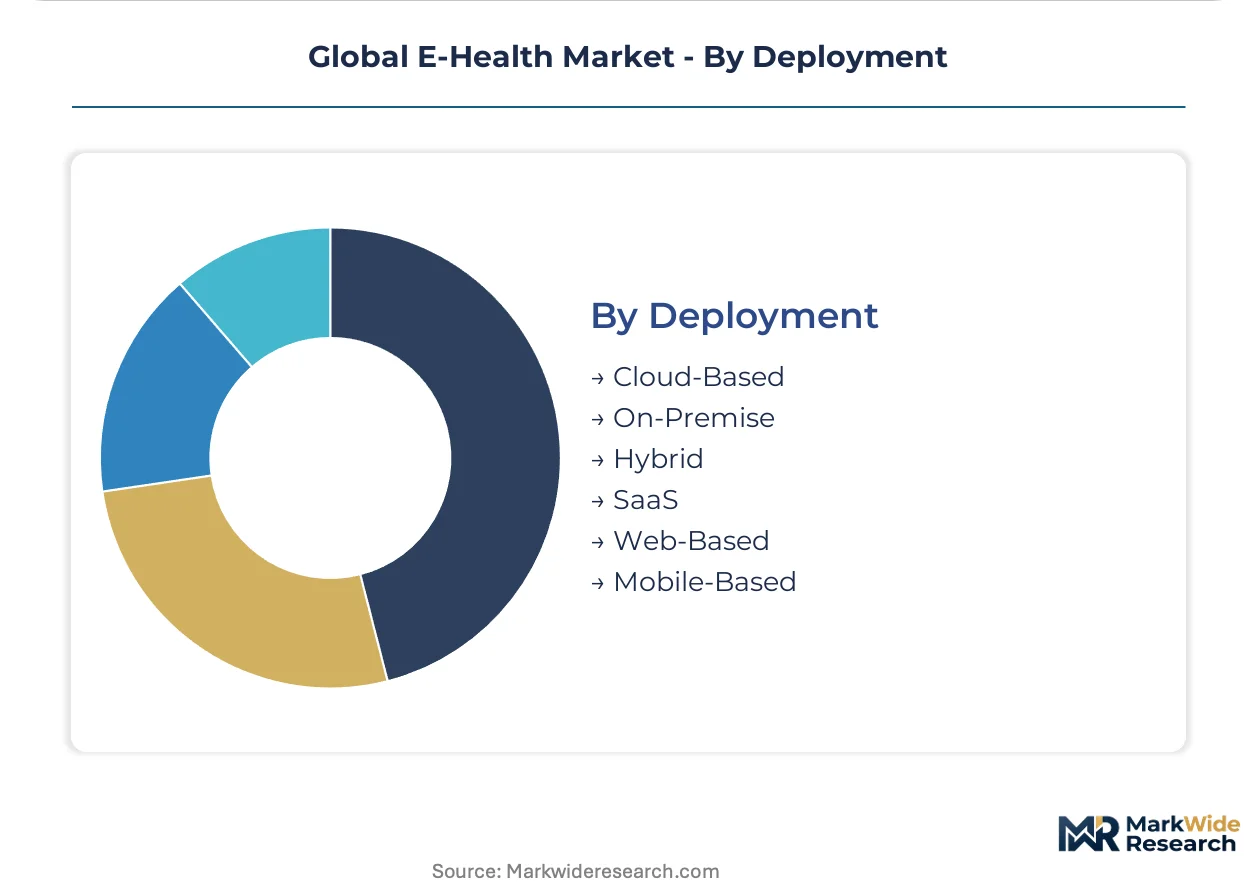
Cloud-Based deployment holds the dominant position, while Mobile-Based delivery is climbing the fastest as frontline physicians resist duplicate data entry across desktop and mobile interfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where reimbursement parity for digital health services commands premium platform economics, while India's cost-optimized telemedicine infrastructure operates on compressed margins serving volume-based rural demand.
United States
Medicare's expanded remote patient monitoring reimbursement creates direct revenue pathways for hospital systems deploying connected diagnostic devices. FDA digital health pre-certification programs shape 18-24 month commercialization timelines for software-as-medical-device offerings. The Greater Boston cluster anchors health IT development where Epic Systems and Athenahealth maintain dominant electronic health record positions.
Germany
Statutory health insurance funds now reimburse prescribed digital health applications under the Digital Healthcare Act, accelerating validated therapeutic software adoption. EMA medical device regulation frameworks classify diagnostic algorithms as Class IIa devices requiring notified body review. The Berlin-Brandenburg corridor concentrates telemedicine platform development serving statutory insurer contracts.
India
National telemedicine guidelines legitimize remote consultations for 600 million rural residents lacking specialist access. The country's central pharmaceutical regulator maintains oversight frameworks for digital therapeutic submissions. Karnataka's Bangalore cluster hosts health IT development centers serving domestic hospital networks and export markets.
United Kingdom
NHS England's digital-first primary care policies accelerate virtual consultation platform procurement across integrated care systems. GDPR localization requirements influence cloud architecture decisions for patient record hosting. London's health tech corridor concentrates AI-augmented diagnostic tool development subject to MHRA software medical device oversight.
Japan
PMDA's software-as-medical-device classification system creates structured pathways for AI diagnostic algorithm market entry. METI's healthcare digitization initiatives promote remote patient monitoring adoption among aging population segments. The Tokyo-Osaka corridor anchors health information system integration serving hospital network consolidation.
Global E-Health Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete modules for integration. The vendor base spans three tiers: dominant electronic health record incumbents with hospital network lock-in, telemedicine pure-plays capturing direct-to-employer channels, and diversified medical technology conglomerates extending hardware footprints into software services. Consolidation pressures favor acquisition of regulatory-ready software assets over de novo development. Strategic partnerships between cloud infrastructure providers and clinical workflow vendors accelerate deployment velocity.
Within the diversified medical technology tier, Koninklijke Philips and Siemens Healthineers exemplify hardware-software integration strategies extending cardiology and respiratory diagnostics into home monitoring settings. Epic Systems occupies a position representing electronic health record platform consolidation, anchoring hospital-centric networks across North American integrated delivery systems. Teladoc Health exemplifies the virtual-first primary care archetype, competing through employer and payer channels that bypass conventional referral structures.
| Leading Market Players |
|---|
| Teladoc Health |
| Epic Systems |
| Athenahealth |
| Oracle |
| Koninklijke Philips |
| Siemens Healthineers |
| GE Healthcare |
| Medtronic |
| Allscripts Healthcare Solutions |
| Others |
Supply & Pricing Matrix
Single-source dependency on cloud infrastructure hyperscalers determines both tiered pricing spreads and supply chain architecture across e-health platform delivery. HIPAA and GDPR cross-border friction forces vendors into jurisdiction-specific hosting configurations that fragment procurement and inflate compliance premiums.
Pricing Analysis
Configured-to-order pricing for HL7 FHIR-compliant enterprise deployments commands substantial premiums over standardized SaaS tiers for ambulatory clinics. Subscription models dominate hospital end users, with price differentiation driven by certification level (FDA pre-certification tier vs. standard health IT compliance) and customization depth for EHR interoperability. Pricing pressure stems from cybersecurity insurance cost absorption consuming IT budgets that would otherwise fund platform upgrades. Self-insured employers show lowest price sensitivity due to direct contracting for virtual-first primary care, while rural hospital networks face acute budget constraints.
Supply Chain Analysis
Supplier-financing through extended payment terms has become critical as hardware-software integration vendors manage working capital across FDA pre-certification timelines. Component manufacturing concentrates in the United States, Germany, and India, with cloud infrastructure drawing from hyperscaler data center networks in these jurisdictions. Raw material dependencies include semiconductor chips for connected diagnostic devices, specialized sensors for biometric monitoring, and encrypted transmission hardware. Single-source vulnerability in FDA-certified component suppliers creates regulatory chokepoint risk. Distribution runs through direct hospital system procurement and GPO contracts, with employer channels emerging as secondary pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-health incumbents face substitution defense against ambient clinical intelligence tools that bypass traditional platform architectures entirely. Generative documentation capabilities threaten to disintermediate established telemedicine workflows.
For Market Incumbents: Build data fabric moats through deep HL7 FHIR integration that locks hospital systems into longitudinal record architectures. Incumbents should acquire regulatory-ready AI diagnostic assets to compress 18-24 month FDA pre-certification windows before reimbursement codes shift. Vertical integration into cloud infrastructure through strategic hyperscaler partnerships reduces GDPR cross-border hosting fragmentation.
For New Entrants and Emerging Players: India's 600 million rural residents lacking specialist access represent the most penetrable geography for telemedicine platform deployment. New entrants should target employer-sponsored mental health channels where benefits unbundling from traditional medical plans creates procurement openness. A direct-to-employer go-to-market angle bypasses legacy EHR vendor lock-in that delays hospital adoption by five to seven years.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory infrastructure over pure technology plays. Long-term viability across the analysis window hinges on post-market surveillance capabilities comparable to hardware manufacturers under EMA Medical Device Regulation. Acquisition targets should demonstrate notified body relationships and quality management systems. The signal to watch is CMS reimbursement code expansion for AI-augmented triage categories.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates software-as-medical-device market entry before reimbursement parity shifts. |
| HL7 FHIR Platform Integration | Enables seamless data exchange between Epic Systems and emerging telemedicine vendors. |
| Hospital System Partnership | Captures procurement volume within integrated delivery networks requiring EHR interoperability. |
| Reimbursement Strategy Development | Positions platforms for CMS remote patient monitoring code expansion and payment parity. |
| Software Companion Development | Extends connected diagnostic hardware from Philips and Siemens into therapeutic algorithms. |
Research Methodology
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and telemedicine platform CTOs anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from FDA digital health pre-certification filings, EMA medical device regulation submissions, CMS reimbursement code databases, and hospital procurement records. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of demand estimates across deployment architectures and application categories.
Scenario-bracketing around regulatory timeline uncertainty and reimbursement parity evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include solution type, application focus, end-user configuration, and deployment architecture, with additional granularity on interoperability certification status. CAGRs were derived from patient encounter volume trajectories, platform adoption curves, and reimbursement expansion schedules. Forecast inputs incorporated FDA pre-certification pipeline data and statutory health insurance fund contracting patterns in Germany.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ambient clinical intelligence entrants or hyperscaler direct-to-hospital offerings would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
Global Health IT Security Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
IHE XDS.B Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market