
 United States Healthcare Fraud Detection Market | 2026-2036
United States Healthcare Fraud Detection Market Size, Share, and Industry Trends Forecast 2026-2036
United States Healthcare Fraud Detection Market Analytics
Real-time claims adjudication standards are collapsing the latency window between submission and fraud flagging. IBM leverages its Watson Health infrastructure to anchor predictive model deployment across federal payer contracts. Cotiviti Inc. specializes in pre-payment detection algorithms that dominate Medicare Advantage plan portfolios. Optum Inc. extends its vertical control from claims processing into fraud analytics, occupying a unique channel position that competitors struggle to replicate.
Healthcare fraud detection encompasses algorithmic systems that apply statistical pattern recognition, natural language processing of clinical documentation, and rule-based claims scoring to identify anomalous billing before or after payment. These platforms process structured claims data alongside unstructured physician notes, requiring sub-second throughput on millions of daily transactions to flag suspect encounters for investigator review. Machine learning segments now capture the fastest expansion as supervised models trained on historical enforcement outcomes outperform static rule sets in emerging fraud schemes. Predictive analytics retains the deepest margin pools due to recurring licensing structures and the high switching costs payers face when replacing core scoring engines. Government Agencies represent the most concentrated end-user segment, with CMS and state Medicaid programs driving standardization requirements that cascade into commercial payer procurement specifications.
FDA oversight of clinical decision support intersects with CMS reimbursement policy to shape how detection algorithms classify medically unnecessary services, while HIPAA mandates constrain data-sharing architectures between payers and law enforcement. The False Claims Act and Stark Law enforcement patterns directly influence model training priorities, as qui tam settlements provide labeled outcome data for supervised learning. Stakeholders must monitor how state Medicaid fraud control units adopt cloud-based platforms, as these procurement decisions will establish interoperability standards that ripple through commercial markets.
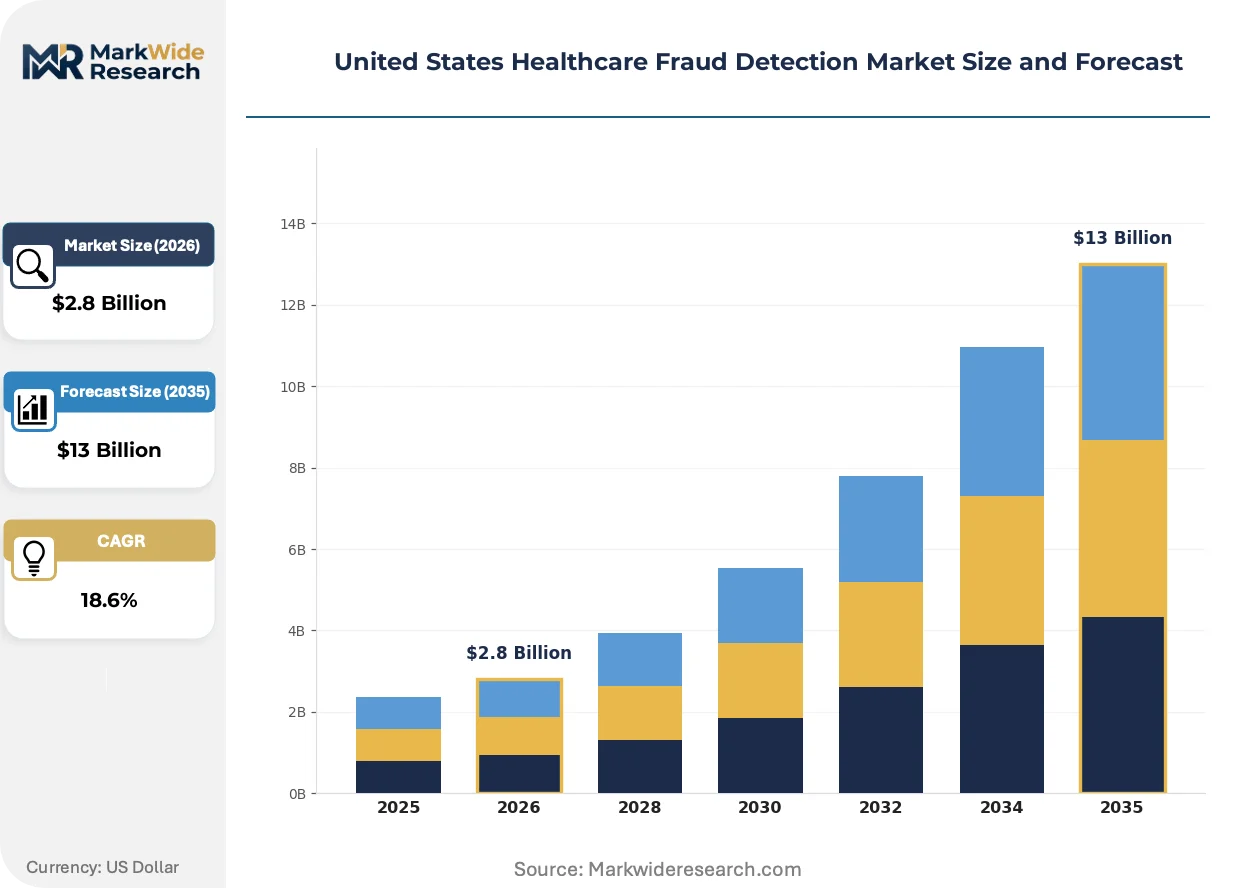
Market Dynamics
CMS risk-adjustment validation rules are compressing the fraud detection procurement cycle, forcing Medicare Advantage plans to replace retrospective audit systems with real-time pre-payment scoring engines that flag anomalies within milliseconds of claims submission.
Growth Catalysts
- HIPAA-compliant data architectures:Payers operating in Florida, California, and Texas are expanding secure data-sharing protocols with state Medicaid fraud control units, accelerating collaborative investigations.
- Machine learning model refinement:Supervised algorithms trained on historical False Claims Act settlement outcomes now identify emerging billing schemes faster than static rule-based systems.
- Pre-payment detection platforms:Commercial payers are prioritizing algorithmic scoring that intercepts suspect claims before funds disburse, reducing recovery costs.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers dominate secure healthcare data hosting, creating single-point-of-failure exposure for fraud detection platform uptime.
- Clinical documentation ambiguity:Natural language processing engines struggle with handwritten physician notes and non-standard abbreviations, generating false positive rates above investigator capacity.
- Interoperability friction:State Medicaid fraud control units operate on fragmented legacy systems that resist API integration with commercial payer analytics platforms.
Strategic Opportunities
- Behavioral health billing:Telehealth encounters and substance abuse treatment claims lack standardized coding, creating white space for anomaly detection algorithms trained on session-duration patterns.
- Stark Law safe harbor expansion:CMS guidance on value-based care arrangements is clarifying permissible physician compensation structures, enabling detection models to flag true outliers.
- Edge computing deployment:Federated learning architectures allow payers to train models on distributed datasets without centralizing protected health information, addressing HIPAA constraints.
Industry Challenges
- Data science talent scarcity:Payers compete with technology firms for machine learning engineers with healthcare domain expertise, inflating compensation packages and delaying model deployment timelines.
- Legacy claims system integration:Mainframe-based adjudication platforms from the 1990s resist real-time API connections, requiring expensive middleware development to enable sub-second fraud scoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Healthcare Fraud Detection Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Predictive Analytics, Natural Language Processing, Rule-Based Systems End User: Insurance Companies, Government Agencies, Healthcare Providers, Third-Party Administrators Service Type: Consulting, Software, Managed Services, Maintenance Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Conduent Inc., DXC Technology Company, EXL (Scio Health Analytics), International Business Machines Corporation (IBM), Mckesson, SAS Institute, Optum Inc., Cotiviti Inc., Northrop Grumman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Healthcare Fraud Detection Market Evolving Landscape
Algorithmic detection is migrating from batch retrospective analysis to streaming inference, with model architectures compressing inference latency while expanding the data types ingested beyond structured claims to unstructured clinical narratives.
Graph neural networks for provider relationship mapping is miniaturizing the detection window for collusion schemes, enabling Medicare Advantage plans to flag suspicious referral patterns within hours rather than months. These models ingest provider network topology, prescribing patterns, and geographic proximity to surface ring arrangements invisible to transaction-level scoring. The technology is compressing investigation cycle times and reducing the volume of cases requiring manual review.
CMS tightened risk-adjustment data validation protocols are forcing Medicare Advantage plans to deploy secondary documentation review algorithms that cross-reference diagnosis codes against clinical evidence in electronic health records. The policy is accelerating procurement of natural language processing engines that extract supporting conditions from physician notes. Plans operating in high-fraud states are prioritizing vendors with federal audit defense experience.
Real-time adjudication requirements are collapsing the traditional separation between claims processing and fraud detection functions. Large commercial payers are consolidating vendor relationships, selecting platforms that embed scoring directly within payment authorization workflows rather than operating as downstream audit layers. This pattern is most pronounced among regional Blues plans modernizing core administration systems.
United States Healthcare Fraud Detection Market Segmentation
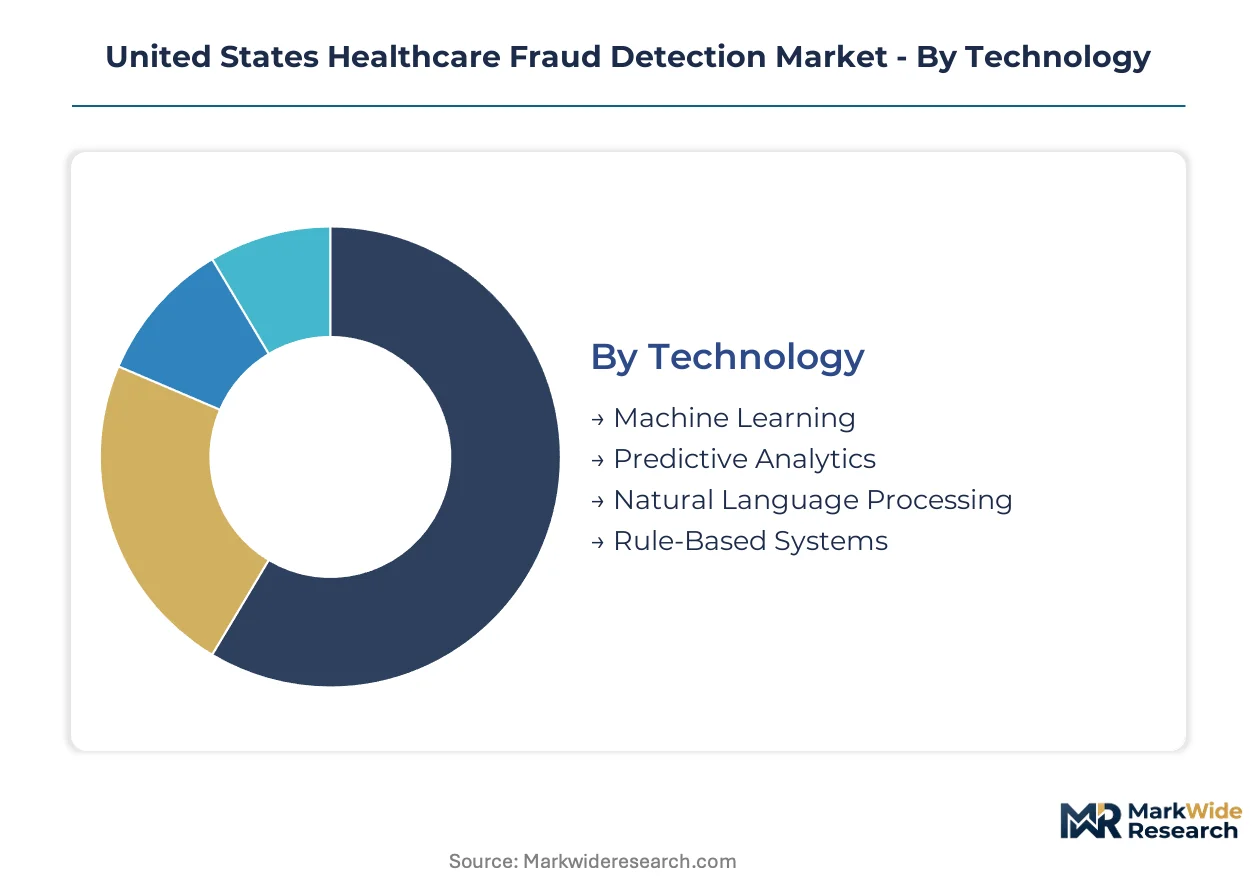
Technology heterogeneity in fraud detection creates distinct procurement patterns across payer types, with each segment demanding specialized integration architectures. Segmentation clarity enables vendors to align R&D spending with the highest-margin deployment pathways.
Technology:
Machine learning platforms face intensifying substitution pressure from next-generation graph neural networks and federated learning architectures that promise superior pattern recognition without centralized data exposure.
- Machine Learning:Supervised algorithms trained on historical enforcement outcomes now dominate Medicare Advantage procurement, with Florida and California plans prioritizing vendors offering sub-second inference latency. CMS risk-adjustment validation rules are compressing deployment timelines for these platforms.
- Predictive Analytics:Recurring licensing structures and high switching costs protect incumbent positions among large commercial payers, though cloud-native challengers are eroding margin pools through consumption-based pricing. Texas Blues plans represent the most concentrated demand concentration.
- Natural Language Processing:Extracts clinical evidence from physician notes to validate diagnosis codes against electronic health records.
- Rule-Based Systems:Static scoring engines retain footprint in state Medicaid fraud control units with limited modernization budgets.
Machine learning retains volume leadership; predictive analytics holds the steepest expansion curve.
End User:
Cost tier differentiation separates enterprise-grade deployments from mid-market solutions, with procurement authority fragmenting across technical and compliance functions.
- Insurance Companies:Large commercial payers in high-fraud states command the deepest technology budgets, consolidating vendor relationships around platforms embedding fraud scoring directly within claims authorization workflows. Real-time adjudication requirements are collapsing traditional separation between processing and detection functions.
- Government Agencies:CMS and state Medicaid programs drive standardization requirements that cascade into commercial payer specifications, creating compliance-driven demand concentration. Federal audit defense experience determines vendor selection.
- Healthcare Providers:Defensive fraud detection procurement accelerates as Stark Law enforcement patterns intensify documentation scrutiny.
- Third-Party Administrators:Price-sensitive demand concentrates among regional plans outsourcing core administrative functions.
Government agencies anchor volume leadership; insurance companies are climbing the fastest.
Service Type:
Application maturity varies sharply, with software platforms achieving production scale while managed services remain concentrated in legacy system environments.
- Software:Algorithmic platforms capturing the fastest expansion as payers replace retrospective audit systems with real-time pre-payment scoring engines. Medicare Advantage plans in Florida and California represent the most aggressive procurement profiles.
- Consulting:Specialized expertise in HIPAA-compliant data architecture and federal audit defense commands premium pricing from plans navigating CMS tightened protocols.
- Managed Services:Operational outsourcing appeals to mid-market payers lacking internal data science capabilities.
- Maintenance:Recurring revenue pools stabilize around legacy rule-based installations resistant to full platform replacement.
Software retains volume leadership; consulting holds the steepest expansion curve.
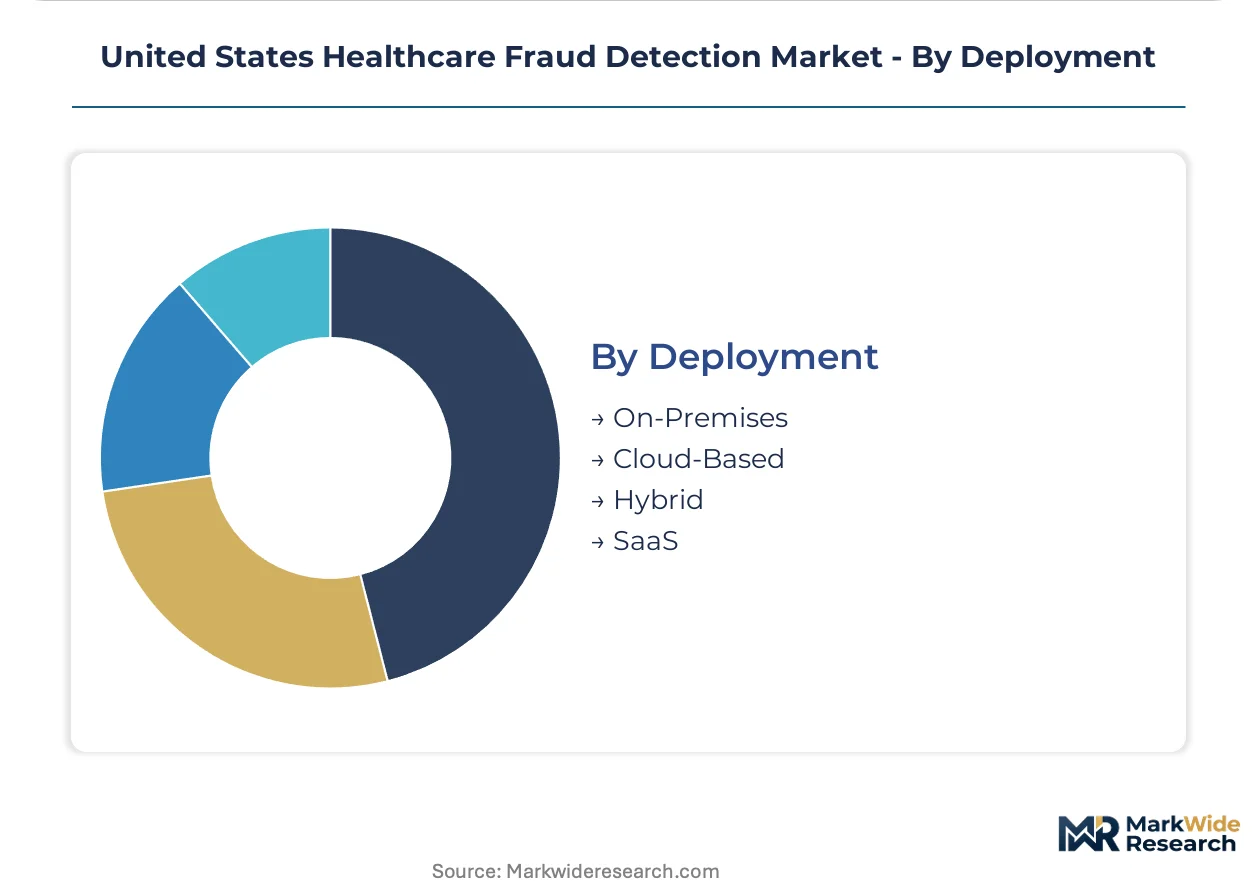
Deployment:
Customer type fragmentation separates hyperscale-ready enterprises from security-constrained organizations requiring air-gapped infrastructure.
- Cloud-Based:Three hyperscale providers dominate secure healthcare data hosting, creating concentration risk for platform uptime. Texas and California payers lead migration timelines, though Florida plans lag due to state-specific data residency requirements.
- SaaS:Consumption pricing models erode traditional perpetual license structures, appealing to regional Blues plans modernizing core administration systems without capital-intensive infrastructure commitments.
- On-Premises:Air-gapped installations persist among government agencies with stringent security classifications.
- Hybrid:Federated architectures allow sensitive claims processing on-premises while leveraging cloud analytics for model training.
Cloud-based retains volume leadership; SaaS is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Healthcare Fraud Detection Market operates as a closed domestic ecosystem with minimal cross-border trade, as fraud detection platforms process exclusively domestic claims data subject to HIPAA jurisdiction. Federal procurement by CMS and state Medicaid programs anchors demand concentration, while commercial payer investment clusters in high-fraud states with complex provider networks.
California
California's commercial payers command the deepest technology budgets for real-time fraud scoring, driven by dense provider networks in Los Angeles and San Francisco Bay Area metros. State Medicaid fraud control units under the Department of Health Care Services are accelerating cloud platform migration, establishing interoperability standards that cascade into commercial procurement specifications. Silicon Valley technology clusters supply machine learning engineering talent to payer analytics divisions, compressing model deployment timelines.
Texas
Texas Blues plans represent concentrated demand for predictive analytics platforms, with Houston and Dallas-Fort Worth metros generating claims volumes that expose billing anomalies at scale. The Texas Health and Human Services Commission operates fragmented legacy systems that resist API integration, creating procurement friction for vendors seeking unified state contracts. Austin's emerging health tech corridor attracts fraud detection startups targeting mid-market payer segments.
Florida
Florida's Medicare Advantage plans face intensified CMS risk-adjustment validation scrutiny, driving procurement of secondary documentation review algorithms that cross-reference diagnosis codes against electronic health records. Miami-Dade and Tampa Bay provider networks exhibit high exposure to billing anomalies, concentrating vendor sales activity. State-specific data residency requirements lag California and Texas cloud migration timelines, preserving on-premises installation footprints.
Illinois
Illinois Medicaid fraud control units under the Office of the Inspector General are adopting federated learning architectures to train models without centralizing protected health information. Chicago's healthcare administration sector anchors demand for consulting services in HIPAA-compliant data architecture. The state's provider network complexity in Cook County generates sufficient claims volume to justify enterprise-grade platform deployment by regional Blues plans.
New York
New York's commercial payers in the New York Metro area are consolidating vendor relationships around platforms embedding fraud scoring directly within claims authorization workflows. State Medicaid programs under the Department of Health are standardizing procurement specifications that influence commercial payer technology selection. Buffalo and Rochester provider networks generate secondary demand concentrations for mid-market fraud detection solutions.
United States Healthcare Fraud Detection Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized healthcare analytics firms that have secured federal payer contracts. The vendor base stratifies across three tiers: enterprise platforms serving CMS and national commercial payers, regional specialists targeting state Medicaid programs, and emerging cloud-native challengers eroding margin pools through consumption-based pricing. Strategic archetypes include vertical integrators extending from claims processing into analytics, pure-play algorithm vendors, and federal contractors leveraging security clearances. Dominant competitive moves encompass platform consolidation to embed scoring within real-time adjudication workflows, and federated learning partnerships that address HIPAA constraints without data centralization.
Within the enterprise platform tier, International Business Machines Corporation and Optum Inc. occupy positions that competitors struggle to replicate, with IBM leveraging Watson Health infrastructure for federal contract anchoring and Optum extending vertical control from claims processing into fraud analytics. Cotiviti Inc. exemplifies the specialized pre-payment detection archetype, dominating Medicare Advantage plan portfolios with algorithms that flag anomalies within milliseconds of claims submission. These three companies represent distinct strategic positions: technology infrastructure leverage, vertical integration depth, and clinical documentation specialization respectively.
| Leading Market Players |
|---|
| Conduent Inc. |
| DXC Technology Company |
| EXL (Scio Health Analytics) |
| International Business Machines Corporation (IBM) |
| Mckesson |
| SAS Institute |
| Optum Inc. |
| Cotiviti Inc. |
| Northrop Grumman |
| Others |
Value Network & Pricing Analysis
HIPAA certification tiers gate both vendor qualification and price differentiation simultaneously, as federal audit defense experience commands premium positioning while cloud-native challengers erode margins through consumption-based structures. Payers in Florida, California, and Texas face divergent procurement economics based on data residency requirements and legacy system integration burdens.
Pricing Analysis
Large commercial payers anchor subscription-based SaaS pricing for real-time fraud scoring platforms, with three-tier pricing structure across premium, standard, and economy levels separating federal contract holders from regional Blues plans and mid-market TPAs. Price differentiation stems from sub-second inference latency guarantees and CMS audit defense track records. Cost compression in the mid-market tier is intensifying because cloud-native vendors undercut perpetual license structures with usage-based models. Third-party administrators exhibit highest price sensitivity; Medicare Advantage plans with CMS risk-adjustment exposure show least.
Supply Chain Analysis
The United States anchors algorithm development and cloud infrastructure deployment for healthcare fraud detection platforms, with India and Eastern European hubs supplying machine learning engineering talent for model training pipelines. Software architectures draw from hyperscale compute services, proprietary clinical NLP engines, and labeled enforcement outcome datasets. Single-source vulnerability concentrates in three dominant cloud providers hosting PHI-compliant workloads. Distribution runs through direct enterprise sales to national payers and channel partnerships with core administration system vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning engineers with healthcare domain expertise command compensation premiums that compress vendor margins and delay deployment timelines, creating a talent scarcity bottleneck that shapes competitive outcomes.
For Market Incumbents: Shield federal contract positions by deepening clinical documentation specialization and accelerating federated learning partnerships that address HIPAA constraints without data centralization. Cloud-native challengers with consumption pricing threaten mid-market share; vertical integration into claims processing workflows secures channel control against disintermediation. For New Entrants and Emerging Players: Anchor in behavioral health billing white space, where telehealth encounter coding lacks standardization and session-duration pattern detection remains underdeveloped. Stark Law safe harbor expansion around value-based care arrangements creates penetrable entry points. Lead with edge computing deployment narratives that resonate with state Medicaid fraud control units facing PHI centralization restrictions. For Investors and Strategic Acquirers: CMS risk-adjustment validation protocol tightening reshapes the acquisition landscape toward vendors with secondary documentation review capabilities and federal audit defense experience. Long-term viability favors platforms embedding scoring within real-time adjudication workflows rather than downstream audit layers. Monitor state Medicaid fraud control unit cloud procurement decisions as interoperability standard inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | HIPAA-compliant model training without PHI centralization addresses payer data-sharing constraints. |
| Real-Time Adjudication Integration | Embedding fraud scoring within claims authorization workflows collapses detection latency windows. |
| Clinical NLP Engine Acquisition | Physician note extraction capabilities satisfy CMS tightened documentation validation requirements. |
| Graph Neural Network Capability Buildout | Provider relationship mapping compresses collusion scheme detection from months to hours. |
| State Medicaid Fraud Control Unit Partnership | Interoperability standard adoption cascades into commercial payer procurement specifications. |
Research Methodology
Cross-validation between payer analytics executives and federal enforcement officials anchors the qualitative findings, with primary interviews conducted across fraud detection vendor product managers, CMS program integrity officers, state Medicaid fraud control unit directors, and Medicare Advantage plan compliance leads. Secondary sources include CMS program guidance documents, False Claims Act settlement records, hospital GPO contract databases, and cloud provider healthcare compliance certifications. Bottom-up segment sizing triangulates against top-down federal procurement budget allocations.
Sensitivity analysis across deployment model adoption curves and cloud migration timelines shapes the analytical framework over the projection horizon. Segmentation dimensions encompass technology type, end-user category, service model, and deployment architecture, with state-level regulatory variation treated as a distinct modeling dimension. CAGRs derive from historical enforcement outcome labeling velocity and payer R&D spending allocation patterns. Model inputs incorporate CMS risk-adjustment validation rule implementation pace and state Medicaid fraud control unit modernization budgets.
Material uncertainties — regulatory enforcement pattern shifts, cloud infrastructure concentration disruptions, clinical documentation standardization advances — sit outside the modeled envelope. Forecasts reflect assumptions about labeled training data availability and investigator workforce capacity scaling. Recalibration cycles align with material shifts in CMS policy guidance and state procurement standard adoptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare API Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Allergy Care Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
North America Artificial Intelligence in Healthcare Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Global Health IT Security Market
Health Informatics
Global Healthcare EDI Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
Healthcare BI Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market