
 Asia-Pacific Yerba Mate Market | 2026-2036
Asia-Pacific Yerba Mate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Yerba Mate Market Outlook
Single-serve sachet bundling is repositioning buyer choice across the Asia-Pacific Yerba Mate Market, shifting volume from bulk loose-leaf toward trial-friendly formats in convenience channels. Guayaki Yerba Mate leverages its North American brand equity to anchor premium positioning in Japanese health stores. Taragüi sustains manufacturing scale through Argentine supply networks that dominate import corridors into Australia and New Zealand. Cruz de Malta differentiates via traditional preparation kits targeting experiential consumers in South Korean specialty retailers.
Yerba mate comprises dried leaves and twigs of Ilex paraguariensis, typically containing 1-2% caffeine by dry weight and processed through fire-drying or air-drying methods before aging; it serves primarily as a stimulant beverage with antioxidant properties in both traditional and functional drink applications. Organic product lines command margin premiums as Japanese and Australian consumers prioritize certified supply chains with traceable provenance. Online retail channels represent the fastest-expanding distribution vector, though supermarkets still occupy the largest volume share across Southeast Asian markets where impulse purchase behavior persists.
Australia's Food Standards Code and Japan's Consumer Affairs Agency labeling requirements shape product formulation and packaging disclosure obligations for imported botanical beverages. South Korea's Ministry of Food and Drug Safety enforces strict caffeine content thresholds that filter which SKUs gain market access. Stakeholders must monitor evolving organic certification reciprocity agreements between Mercosur source countries and Asia-Pacific import jurisdictions to secure sustained supply advantages.
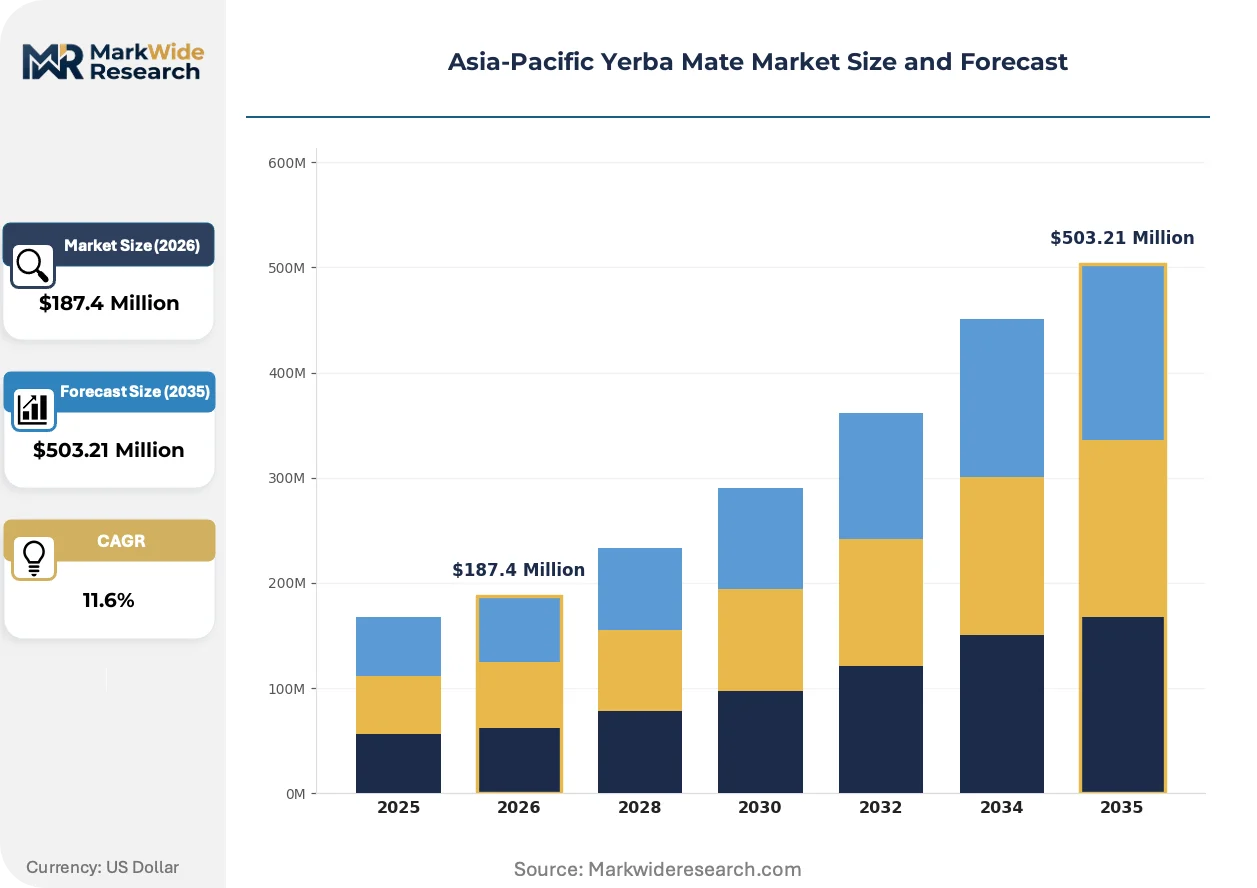
Market Dynamics
Single-serve packaging formats are compressing traditional bulk purchasing patterns across Asia-Pacific retail channels, forcing importers to reconfigure Argentine supply contracts toward smaller batch logistics.
Growth Catalysts
- Japan's Food Labeling Standards:Mandatory caffeine disclosure rules are filtering out non-compliant imports, creating shelf space for certified organic lines with transparent supply chains.
- Wellness-oriented retail chains:South Korean metropolitan retailers are dedicating premium shelf space to functional botanical beverages, accelerating trial adoption among urban professionals.
- Fire-drying to air-drying process migration:Cleaner processing methods are reducing smoke-taint complaints in Australian specialty cafes, expanding the addressable coffee-alternative customer base.
Market Restraints
- Argentine supply concentration:Over-reliance on Mercosur source regions exposes importers to peso volatility and harvest fluctuations that compress margin predictability.
- MFDS caffeine thresholds:South Korea's strict milligram-per-serving limits block high-caffeine traditional formulations from legal market entry.
- Green tea substitution:Established local caffeine traditions in Japan and China create habitual switching costs that slow yerba mate penetration.
Strategic Opportunities
- Vietnamese urban millennials:Ho Chi Minh City and Hanoi present underdeveloped demand pockets where coffee culture fatigue is opening trial windows for South American botanicals.
- Cross-category functional positioning:Blending yerba mate with adaptogenic ingredients targets the nootropic beverage segment expanding through Australian pharmacy channels.
- Organic certification reciprocity:Pending mutual recognition agreements between Argentine certifiers and Australia's Department of Agriculture would slash re-certification costs.
Industry Challenges
- Sensory training deficits:Specialty retailers in Seoul and Sydney lack staff capable of explaining traditional preparation methods, limiting experiential conversion rates.
- Cold-chain capex requirements:Preserving volatile antioxidant compounds through humidity-controlled warehousing demands infrastructure investments that strain mid-size importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Yerba Mate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Flavored, Organic, Instant Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Households, Cafes, Restaurants, Health Stores Packaging Type: Tea Bags, Loose Leaf, Cans, Bottles |
| Companies Covered | Canarias, Cruz de Malta, Guayaki Yerba Mate, Amanda, La Merced, Taragüi, Kraus Organic, Selecta, Rosamonte, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Yerba Mate Market Strategic Shifts
Product format experimentation and regulatory disclosure requirements are jointly reshaping how Argentine-sourced botanicals reach Asia-Pacific consumers. Packaging engineers and compliance officers now collaborate earlier in the NPD cycle.
Ready-to-drink aluminum canning technology is modularizing the traditional loose-leaf supply chain. Japanese convenience store buyers are adopting these formats at twice the pace of bulk alternatives. This compression is enabling direct-to-retailer contracts that bypass conventional import distributor layers.
Australia's Food Standards Code revisions are mandating clearer allergen and origin labeling for botanical stimulants. Reformulation costs are pushing smaller importers toward private-label partnerships with established Australian beverage manufacturers. Premium organic SKUs bear the heaviest compliance burden as traceability documentation requirements multiply.
Subscription-based replenishment models are displacing supermarket impulse purchases among Melbourne and Sydney wellness consumers. Direct-to-consumer platforms capture higher lifetime value through personalized brewing guidance. This channel shift concentrates most visibly among Australian consumers aged 25-40 seeking caffeine alternatives without abandonment rituals.
Asia-Pacific Yerba Mate Market Segmentation
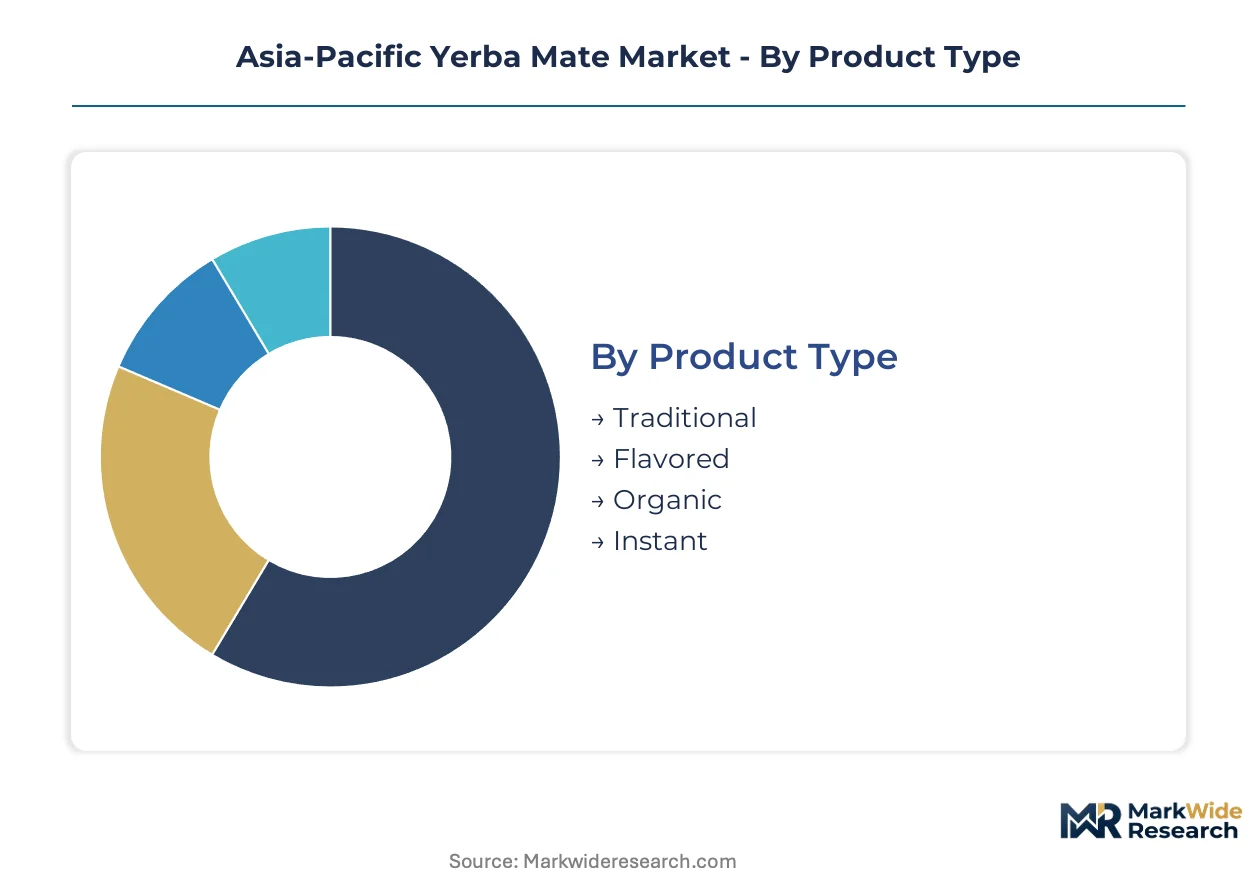
Yerba mate's Asia-Pacific expansion hinges on precise segment targeting. Product format, channel strategy, and end-user application each demand distinct commercial approaches across Australian wellness consumers, Japanese regulatory environments, and South Korean cafe culture.
Product Type:
Consumer priorities diverge sharply between heritage preparation seekers and convenience-oriented buyers across the region.
- Traditional:Fire-dried or air-dried leaf and twig blends containing 1-2% caffeine by dry weight, processed through aging cycles. Australian specialty cafes drive demand as baristas educate customers on gourd-and-bombilla rituals, though preparation complexity limits household penetration.
- Organic:Certified supply chains with Mercosur-origin traceability command shelf space in Japanese health stores where Consumer Affairs Agency disclosure requirements favor transparent provenance. Australia's Department of Agriculture reciprocity negotiations would reduce re-certification costs for Argentine organic lines.
- Flavored:Citrus, mint, and berry infusions target trial conversion among Vietnamese urban millennials in Ho Chi Minh City convenience channels.
- Instant:Soluble powder formats bypass traditional brewing barriers for office consumption in Seoul metropolitan area workplaces.
Volume sits with Traditional; growth tilts toward Organic.
Distribution Channel:
Channel economics reflect diverging customer acquisition costs and lifetime value calculations across metropolitan clusters.
- Online Retail:Direct-to-consumer platforms capture subscription replenishment from Melbourne and Sydney wellness consumers aged 25-40. Personalized brewing guidance and community content drive retention metrics superior to impulse channels.
- Supermarkets:Volume concentration persists across Southeast Asian markets where unplanned purchase behavior dominates. Shelf placement near coffee alternatives in Australian Coles and Woolworths locations determines trial rates.
- Specialty Stores:Japanese health store buyers stock Guayaki and premium Argentine lines; South Korean wellness chains dedicate experiential zones with preparation demonstrations.
- Direct Sales:Argentine exporter-direct contracts with Australian beverage manufacturers are expanding as private-label partnerships absorb compliance burdens from Food Standards Code revisions.
Supermarkets retain volume leadership; online channels gain share fastest through subscription mechanics.
End User:
Usage context determines caffeine disclosure obligations and preparation infrastructure requirements.
- Cafes:Australian specialty coffee houses position yerba mate as a functional alternative with antioxidant claims, though staff training gaps in Sydney and Seoul limit experiential conversion rates.
- Households:Japanese consumers prioritize single-serve sachets with clear METI-aligned labeling; bulk loose-leaf persists among Argentine expatriate communities.
- Health Stores:South Korean pharmacy channels stock adaptogenic blends targeting nootropic positioning; MFDS caffeine thresholds filter permissible SKUs.
- Restaurants:Limited penetration outside Buenos Aires-style steakhouses in Melbourne and Sydney; menu integration costs exceed beverage margin contribution.
Cafes anchor premium positioning; households drive volume scaling through format simplification.
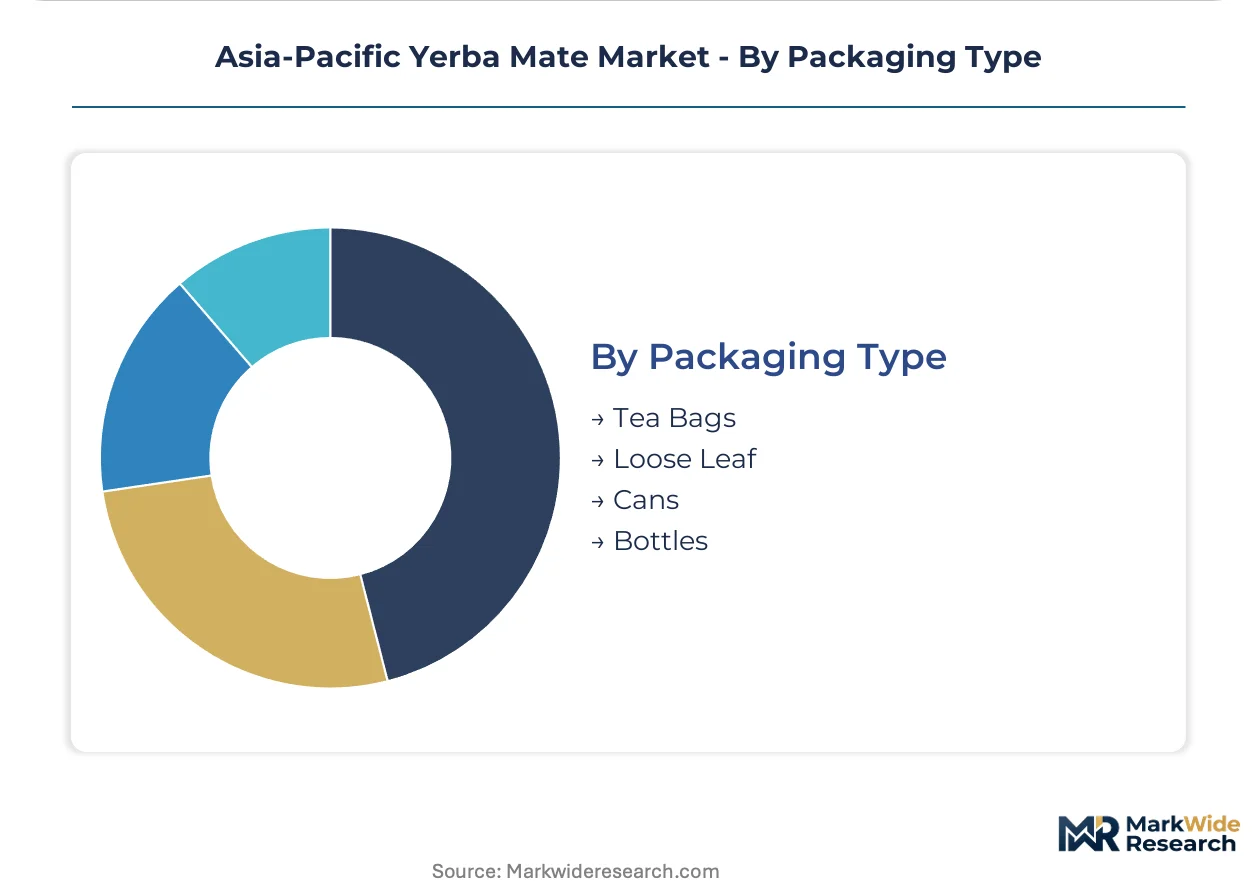
Packaging Type:
Packaging engineering decisions now precede regulatory compliance review in NPD cycles across import-dependent markets.
- Tea Bags:Single-serve sachet bundling compresses traditional bulk purchasing patterns, forcing Argentine supply contract reconfiguration toward smaller batch logistics. Japanese convenience store buyers adopt at twice the pace of bulk alternatives.
- Cans:Ready-to-drink aluminum canning technology enables direct-to-retailer contracts bypassing conventional import distributor layers. Humidity-controlled warehousing requirements strain mid-size importer capex.
- Loose Leaf:Heritage formats dominate Argentine-source traditionalists; peso volatility and harvest fluctuations compress margin predictability for bulk importers.
- Bottles:Cold-brew RTD lines target Australian pharmacy channel placement alongside functional beverage adjacencies.
Loose Leaf holds established volume; Tea Bags climb the fastest through trial-friendly positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina dominates global yerba mate production, yet Asia-Pacific consumption concentrates in import-dependent markets where regulatory frameworks and cafe culture shape demand patterns. The region's growth trajectory hinges on how Argentine supply networks adapt to Japanese labeling mandates, Australian organic certification requirements, and South Korean caffeine thresholds.
Australia
Specialty coffee houses in Melbourne and Sydney drive premium positioning as baristas educate consumers on traditional gourd preparation. Food Standards Code revisions mandate clearer allergen and origin labeling for botanical stimulants, pushing smaller importers toward private-label partnerships. New South Wales and Victoria anchor volume concentration through wellness-oriented retail chains and direct-to-consumer subscription platforms.
Japan
Health-conscious urban professionals seek certified organic lines with traceable Mercosur provenance in Tokyo and Osaka health stores. Consumer Affairs Agency labeling requirements favor transparent supply chains with clear caffeine disclosure, filtering out non-compliant imports. METI-aligned standards create shelf space for brands meeting stringent documentation protocols.
South Korea
Wellness retail chains in the Seoul metropolitan area dedicate premium shelf space to functional botanical beverages targeting urban professionals. Ministry of Food and Drug Safety caffeine thresholds block high-caffeine traditional formulations from legal market entry, forcing SKU curation. Experiential zones with preparation demonstrations attempt to overcome sensory training deficits among specialty retail staff.
Vietnam
Coffee culture fatigue among Ho Chi Minh City and Hanoi millennials opens trial windows for South American botanicals in convenience channels. Citrus and mint flavored infusions target format-friendly adoption among urban consumers unfamiliar with traditional preparation. Importers test single-serve sachet bundling to compress traditional bulk purchasing patterns.
Asia-Pacific Yerba Mate Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across import-dependent Asia-Pacific markets. Argentine supply networks dominate raw material flows, while regional distributors and private-label manufacturers absorb compliance burdens from evolving labeling requirements. Three archetypes define competitive positioning: heritage Argentine exporters with established Mercosur supply chains, North American brand equity players leveraging premium health store positioning, and regional private-label partners managing Food Standards Code and MFDS adaptation. Dominant competitive moves include direct-to-retailer contract compression bypassing conventional import distributor layers, and backward integration into humidity-controlled warehousing preserving volatile antioxidant compounds.
Among heritage Argentine exporters, Taragüi and Cruz de Malta exemplify scale-driven and experiential-positioning archetypes respectively. Taragüi's manufacturing scale sustains Argentine supply network dominance into Australia and New Zealand import corridors. Cruz de Malta anchors the traditional preparation kit segment targeting experiential consumers in South Korean specialty retailers. Guayaki Yerba Mate represents the North American brand equity vector, occupying premium positioning in Japanese health stores where consumer familiarity with its domestic market presence accelerates trial adoption.
| Leading Market Players |
|---|
| Canarias |
| Cruz de Malta |
| Guayaki Yerba Mate |
| Amanda |
| La Merced |
| Taragüi |
| Kraus Organic |
| Selecta |
| Rosamonte |
| Others |
Value Chain & Pricing Dynamics
Organic certification ladder bifurcation between Argentine heritage lines and private-label commodity tiers manifests in both margin capture and supply chain configuration, as Japanese Consumer Affairs Agency disclosure requirements and Australia's Food Standards Code revisions force divergent compliance investments that reshape procurement patterns across import corridors.
Pricing Analysis
Margin tightening in commodity loose-leaf tiers reflects peso volatility and harvest fluctuation exposure, while premium organic SKUs sustain markup power through traceable Mercosur provenance. Three-tier pricing structure across premium certified, standard conventional, and economy private-label levels stratifies buyer segments, with Australian wellness consumers aged 25-40 showing lowest price sensitivity through subscription channels and Vietnamese urban millennials in convenience segments exhibiting highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Melbourne, Sydney, and Tokyo anchor hub-and-spoke patterns that compress lead times for humidity-sensitive inventory. Argentine source regions supply dried Ilex paraguariensis leaf and twig inputs, with fire-drying and air-drying processing methods determining final antioxidant compound stability. Single-source vulnerability concentrates in Mercosur harvest corridors exposed to climate variability, while direct-to-retailer contracts bypass conventional import distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
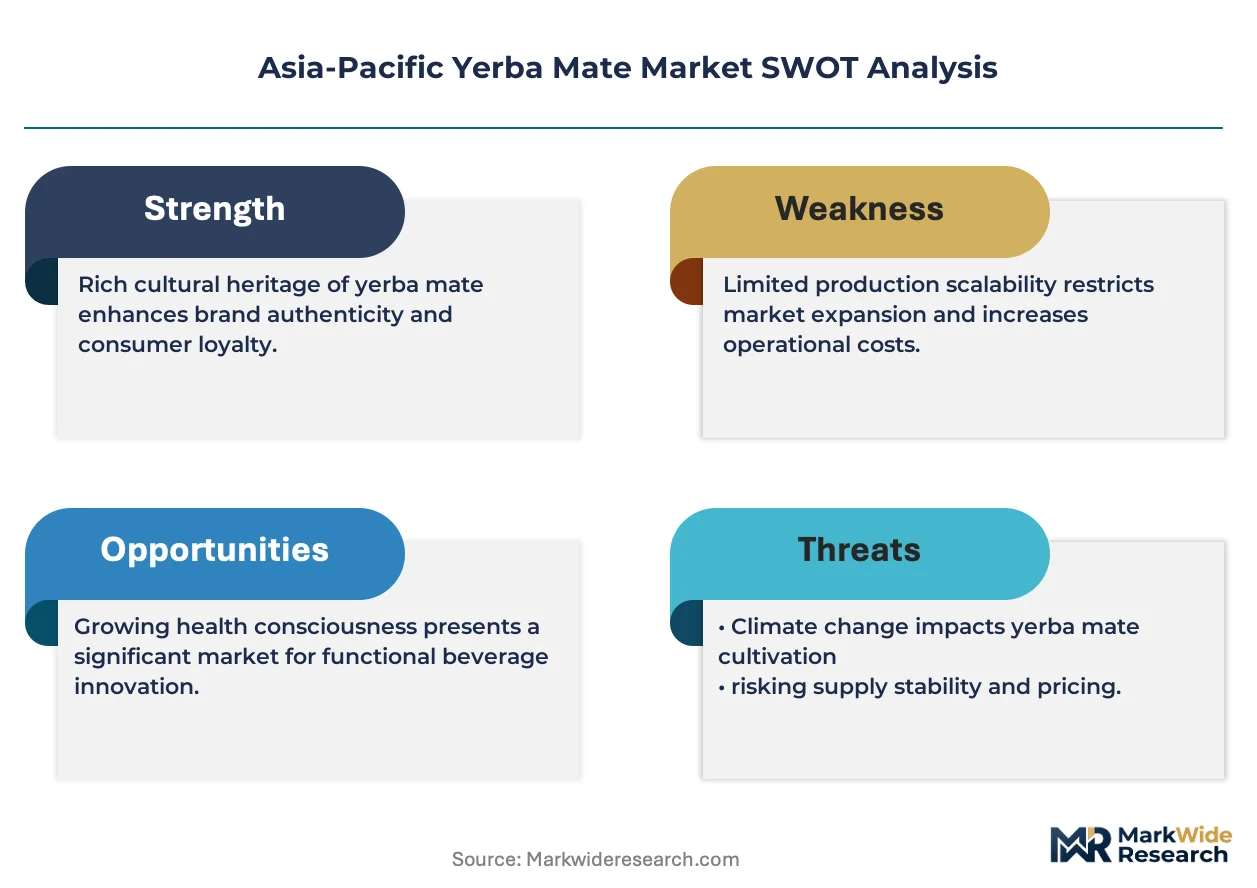
Asia-Pacific yerba mate market expansion functions as a cost-of-compliance story where Japan's Food Labeling Standards and South Korea's MFDS caffeine thresholds erect barrier-to-entry moats favoring players with documented supply chain transparency and reformulation capabilities.
For Market Incumbents: Deploy certification investment levers to deepen organic reciprocity advantages before Australia's Department of Agriculture finalizes Mercosur mutual recognition agreements. Anchor humidity-controlled warehousing capacity in Sydney and Melbourne to preserve volatile antioxidant compounds against green tea substitution threats. Absorb smaller importers through private-label partnerships that distribute Food Standards Code compliance burdens.
For New Entrants and Emerging Players: Cold-brew RTD canning technology offers a technology-first wedge into Australian pharmacy channels where functional beverage adjacencies remain underdeveloped. Target Ho Chi Minh City and Hanoi convenience networks with citrus and mint flavored sachet formats that bypass traditional preparation barriers. Pursue direct-to-retailer contracts with Japanese convenience store buyers adopting single-serve formats at accelerated pace.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-size Argentine exporters possessing established organic certification and direct Australian distribution relationships given pending reciprocity agreement catalysts. Monitor MFDS caffeine threshold enforcement patterns as inflection indicator for SKU viability expansion. Long-term viability hinges on backward integration into air-drying processing capacity that reduces smoke-taint liability.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Reciprocity Investment | Reduces re-certification costs for Argentine exporters entering Australian health store channels. |
| Cold-Chain Warehousing Expansion | Preserves antioxidant compound stability through humidity-controlled infrastructure in Sydney and Melbourne. |
| Direct-to-Retailer Contract Compression | Bypasses conventional import distributor layers for Japanese convenience store and Australian pharmacy placement. |
| Adaptogenic Blend Formulation | Targets nootropic beverage segment expanding through South Korean pharmacy and Australian wellness retail. |
| Single-Serve Sachet Format Migration | Captures trial conversion among Vietnamese urban millennials and Japanese office consumers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across import distributors, specialty retail buyers, Argentine exporter commercial directors, and Australian beverage manufacturer procurement leads. Bottom-up volume modeling triangulated against top-down category spend estimates derived from Nielsen retail audit data, Mercosur export statistics, and Japanese Consumer Affairs Agency import registration databases.
Segmentation granularity operated at product format, distribution channel, end-user application, and packaging type levels across the analysis window. CAGRs derived from trend extrapolation of historical trade flows adjusted for regulatory threshold changes and format adoption curves. Forecast inputs incorporated MFDS caffeine enforcement patterns, organic certification reciprocity negotiation timelines, and cold-brew RTD canning technology diffusion rates.
Several conditions sit outside the modeled scope, including abrupt Argentine peso devaluation, climate-induced harvest failures in Misiones province, and unilateral regulatory threshold adjustments by Australian or South Korean agencies. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Root Beer Market
Beverages
Nitro-Infused Beverages Market
Beverages
Coconut Milk Beverages Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Europe Bottled Water Processing Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Wellness Water Market
Beverages
Fruit Juice Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
India Bottled Water Market
Beverages
Europe Bottled Water Market
Beverages
Europe Beverage Market
Beverages
Sparkling Water Market
Beverages
South America Ready to Drink Beverages Market
Beverages
Sparkling Water Machine Market
Beverages
Health Drinks Market