
 Europe Yerba Mate Market | 2026-2036
Europe Yerba Mate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Yerba Mate Market Foresight
Single-source South American supply chains is restructuring as European importers diversify procurement across multiple Argentine and Brazilian cooperatives. Meta Mate leverages direct-trade relationships with smallholder growers to secure organic-certified harvests. Guayaki Sustainable Rainforest Products Inc. anchors its European presence through climate-neutral shipping programs and regenerative agriculture messaging. Taragüi competes on scale, operating large-volume drying and aging facilities that reduce per-unit costs for bulk buyers.
Yerba mate comprises dried leaves and stems of Ilex paraguariensis, a holly species native to subtropical South America, containing caffeine, theobromine, and polyphenol antioxidants in concentrations that vary by harvest season and processing method. The dried material serves primarily as a brewed stimulant beverage with established cultural use and emerging functional-food applications in energy and wellness products. Loose leaf formats dominate volume throughput in European wholesale channels, while ready-to-drink cans capture the fastest expansion in convenience retail and foodservice. Health stores and dedicated online retailers sustain the highest margin pools by targeting organic product seekers and millennials with premium single-origin positioning.
EFSA novel food assessments and EU organic certification standards govern import eligibility and on-label health claims for yerba mate products entering European distribution. REACH compliance and F-Gas Regulation requirements indirectly shape processing equipment sourcing and cold-chain logistics for ready-to-drink formats. Stakeholders must monitor evolving EFSA caffeine exposure guidelines and national caffeine labeling rules that could reshape product formulation and target consumer segments.
Market Dynamics
EFSA novel food assessments and EU organic certification standards are forcing European importers to restructure supply chains around documented provenance and laboratory-verified compound profiles, compressing margins for undocumented bulk suppliers while rewarding certified direct-trade networks.
Growth Catalysts
- EU Green Deal alignment:Climate-neutral shipping programs and regenerative agriculture messaging resonate with German and French wellness consumers seeking carbon-transparent stimulant alternatives.
- Specialty coffee shop expansion:Berlin and Hamburg cafés are integrating yerba mate into beverage menus, normalizing consumption among urban millennials previously unfamiliar with South American brewing traditions.
- Functional food formulation:Polyphenol antioxidant claims are penetrating energy drink and wellness shot applications, extending yerba mate beyond traditional loose-leaf formats into convenience retail.
Market Restraints
- Argentine-Brazilian supply concentration:Drought and currency volatility in Misiones Province and Paraná state create input cost instability for European wholesale buyers locked into annual contracts.
- EFSA novel food friction:Pre-market authorization timelines for new extraction methods or compound-standardized products delay product launches by 18-24 months.
- Energy drink substitution:Synthetic caffeine and guarana formulations maintain price advantages in mass-market convenience channels, limiting yerba mate penetration beyond premium positioning.
Strategic Opportunities
- Spanish market underpenetration:Madrid and Barcelona wellness retail remains dominated by kombucha and matcha, creating whitespace for single-origin yerba mate with Andalusian olive oil pairing narratives.
- Ready-to-drink can innovation:Nitrogen-chilled filling technology and aluminum recycling loops enable shelf-stable formats that bypass traditional gourd-brewing complexity.
- CSRD reporting integration:Supply chain transparency mandates are elevating cooperatives with blockchain-traceable harvest records above commodity traders in procurement evaluations.
Industry Challenges
- Organic certification latency:Conversion timelines for conventional Argentine estates seeking EU organic status extend 36 months, constraining certified volume growth.
- Cold-chain capex burden:Refrigerated warehousing for ready-to-drink inventory requires infrastructure investments that strain mid-size importer balance sheets.
- Flavor standardization complexity:Harvest-season variation in caffeine and theobromine concentrations complicates consistent product formulation for functional food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Yerba Mate Market |
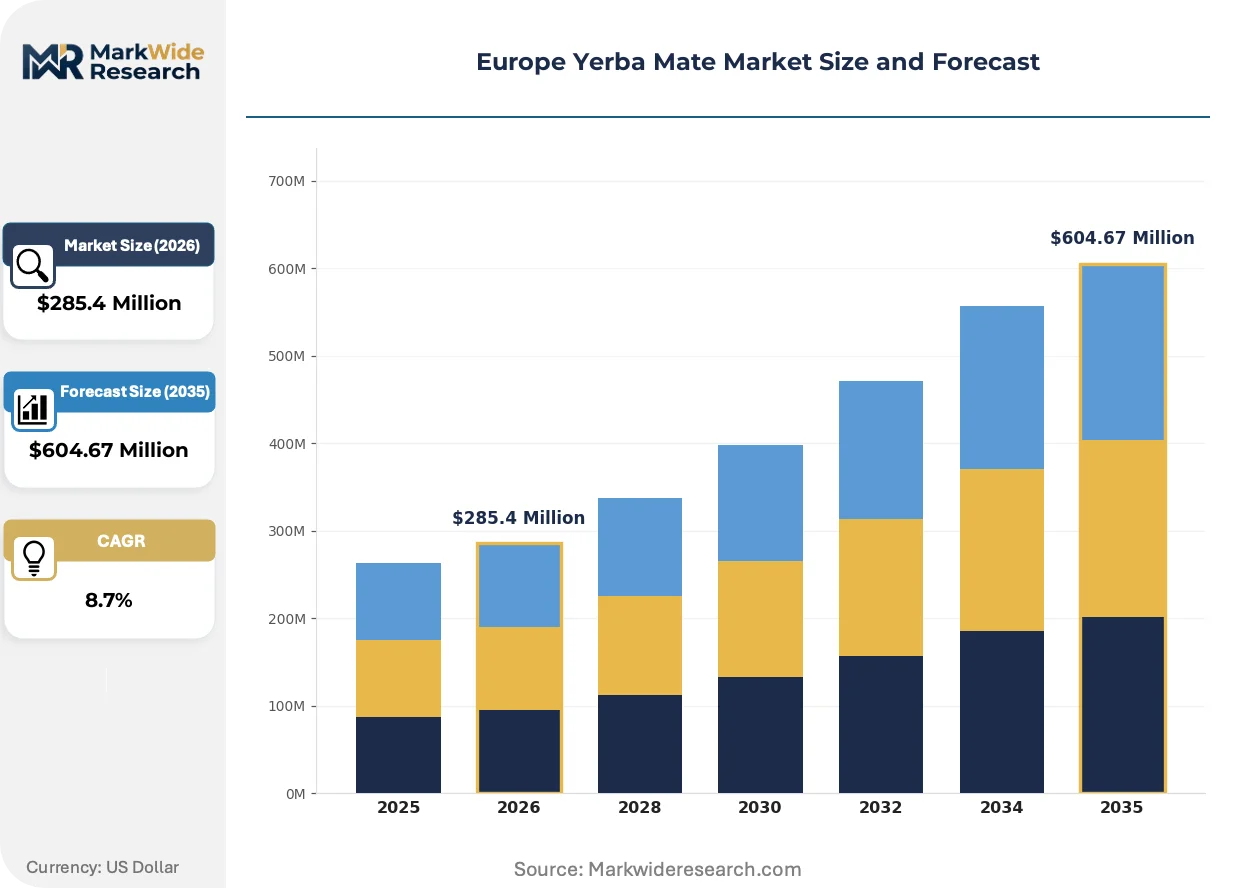
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Tea Bags, Ready-to-Drink, Extracts Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Customer Type: Health Conscious Consumers, Millennials, Traditionalists, Organic Product Seekers Packaging Type: Individual Packs, Bulk Packaging, Eco-friendly Containers, Cans |
| Companies Covered | Meta Mate, Taragüi, Guayaki Sustainable Rainforest Products Inc., Canarias, Rosamonte, ECOTEAS Organic Yerba Mate, Kraus, Pajarito, Yuyo Drinks Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Yerba Mate Market Shifts & Advancements
Processing technology and consumption format innovation are compressing the traditional gourd-brewing ritual into shelf-stable, on-the-go formats while regulatory transparency mandates reshape competitive differentiation around supply chain documentation.
Nitrogen-flush packaging and flash-chilled extraction systems are electrifying ready-to-drink development, enabling shelf-stable cans that preserve volatile aromatic compounds previously lost in heat-pasteurized formats. German beverage startups are adopting these systems at pilot scale, targeting convenience retail placement previously inaccessible to loose-leaf suppliers. The technology is compressing the format gap between traditional brewing and mass-market energy drinks.
REACH compliance and F-Gas Regulation requirements are tightening processing equipment specifications for European co-packers, favoring suppliers with capital reserves to retrofit drying and milling infrastructure. Cold-chain logistics providers face refrigerant phase-out timelines that favor CO2-based systems over hydrofluorocarbon-dependent fleets. Ready-to-drink manufacturers in France and the Netherlands are consolidating procurement around equipment vendors with documented ECHA registration portfolios.
Direct-to-subscription models are displacing health store wholesale as the primary channel for organic-certified loose-leaf, with Berlin and Hamburg consumers prioritizing harvest-date transparency over shelf availability. Specialty roasters and tea merchants are unbundling yerba mate from South American import bundles, creating single-origin SKUs with cooperative-specific provenance narratives. This channel rotation is most visible in German urban markets, where millennial buyers research harvest cooperatives before purchase.
Europe Yerba Mate Market Segmentation
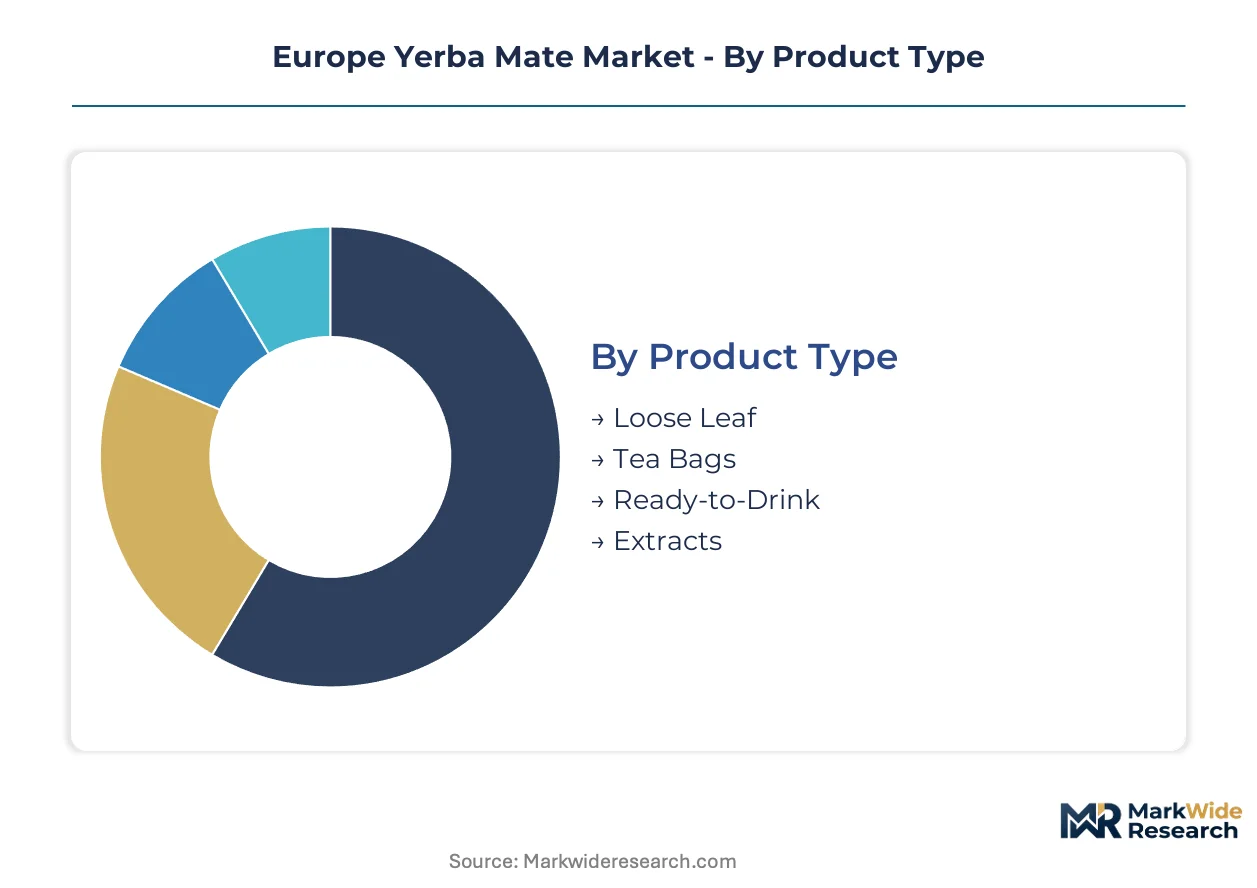
Segmentation in the Europe yerba mate market reveals divergent capital requirements across product formats and channel strategies. Drying, aging, and milling infrastructure demands separate commodity-grade suppliers from premium-positioned players, while cold-chain investments for ready-to-drink formats create distinct entry barriers.
Product Type:
Capital intensity varies sharply across processing stages, with extraction and ready-to-drink manufacturing requiring sterile filling lines and laboratory verification that loose-leaf operations bypass entirely.
- Loose Leaf:Sun-dried and aged Ilex paraguariensis leaves retain volatile aromatic compounds through minimal processing. German urban consumers in Berlin and Hamburg drive organic-certified purchases through direct-to-subscription channels that prioritize harvest-date transparency.
- Ready-to-Drink:Nitrogen-flush packaging and flash-chilled extraction systems preserve polyphenol integrity in shelf-stable aluminum cans. French and Dutch beverage startups are deploying pilot-scale filling lines to capture convenience retail placement previously inaccessible to traditional suppliers.
- Tea Bags:Mechanized sachet filling of cut-leaf material serves office and travel consumption occasions with lower per-unit margins.
- Extracts:Standardized caffeine and theobromine concentrates for functional food formulation require solvent extraction infrastructure and EFSA novel food authorization.
Loose leaf absorbs the bulk of installed capacity; ready-to-drink is expanding most quickly.
Distribution Channel:
Margin structures across channels reflect customer acquisition costs and inventory risk allocation, with health stores commanding premium positioning while supermarkets enforce volume guarantees.
- Online Retail:Direct-to-subscription platforms enable cooperative-specific provenance narratives and harvest-date transparency. Berlin-based merchants are unbundling yerba mate from South American import bundles, creating single-origin SKUs that bypass wholesale markups.
- Health Stores:Physical wellness retail in German and French urban centers sustains the highest margin pools through organic certification premiums and millennial-targeted education.
- Supermarkets:Mass-market placement demands pallet-scale volume commitments and standardized barcoding that favors established Argentine exporters with EU organic certification.
- Convenience Stores:Refrigerated shelving for ready-to-drink cans requires cold-chain logistics partnerships that strain mid-size importer balance sheets.
Online retail captures the steepest expansion trajectory; health stores defend the highest margin position.
Customer Type:
Targeting precision determines formulation complexity and certification burden, with organic seekers and traditionalists imposing divergent supply chain documentation requirements.
- Organic Product Seekers:EU organic certification mandates 36-month conversion timelines for Argentine estates and laboratory-verified compound profiles. Direct-trade networks with blockchain-traceable harvest records command procurement preference under CSRD transparency mandates.
- Millennials:Urban consumers aged 25-40 in Berlin, Hamburg, and Barcelona normalize yerba mate consumption through specialty coffee shop integration and carbon-transparent sourcing narratives.
- Health Conscious Consumers:Polyphenol antioxidant claims and natural caffeine positioning drive functional food applications in energy shots and wellness beverages.
- Traditionalists:Gourd-brewing ritual adherence concentrates among South American expatriate communities and cultural enthusiasts seeking unprocessed leaf grades.
Organic product seekers absorb the bulk of certified supply; millennials are climbing the fastest.
Packaging Type:
Material selection shapes regulatory compliance burden and end-of-life responsibility, with aluminum and biodegradable films facing divergent ECHA registration and recycling infrastructure requirements.
- Eco-friendly Containers:Compostable films and reusable vessel programs align with EU Green Deal carbon transparency expectations. German wellness cafés are piloting deposit-return schemes for ceramic gourd alternatives.
- Cans:Aluminum recycling loops and nitrogen-chilled filling technology enable shelf-stable ready-to-drink formats that bypass traditional brewing complexity. REACH compliance for coating materials favors suppliers with documented ECHA registration portfolios.
- Bulk Packaging:Multi-kilogram Kraft paper sacks serve foodservice and wholesale channels with minimal unit economics impact from packaging cost.
- Individual Packs:Single-serve sachets for hospitality and travel segments generate higher packaging waste ratios that face tightening extended producer responsibility frameworks.
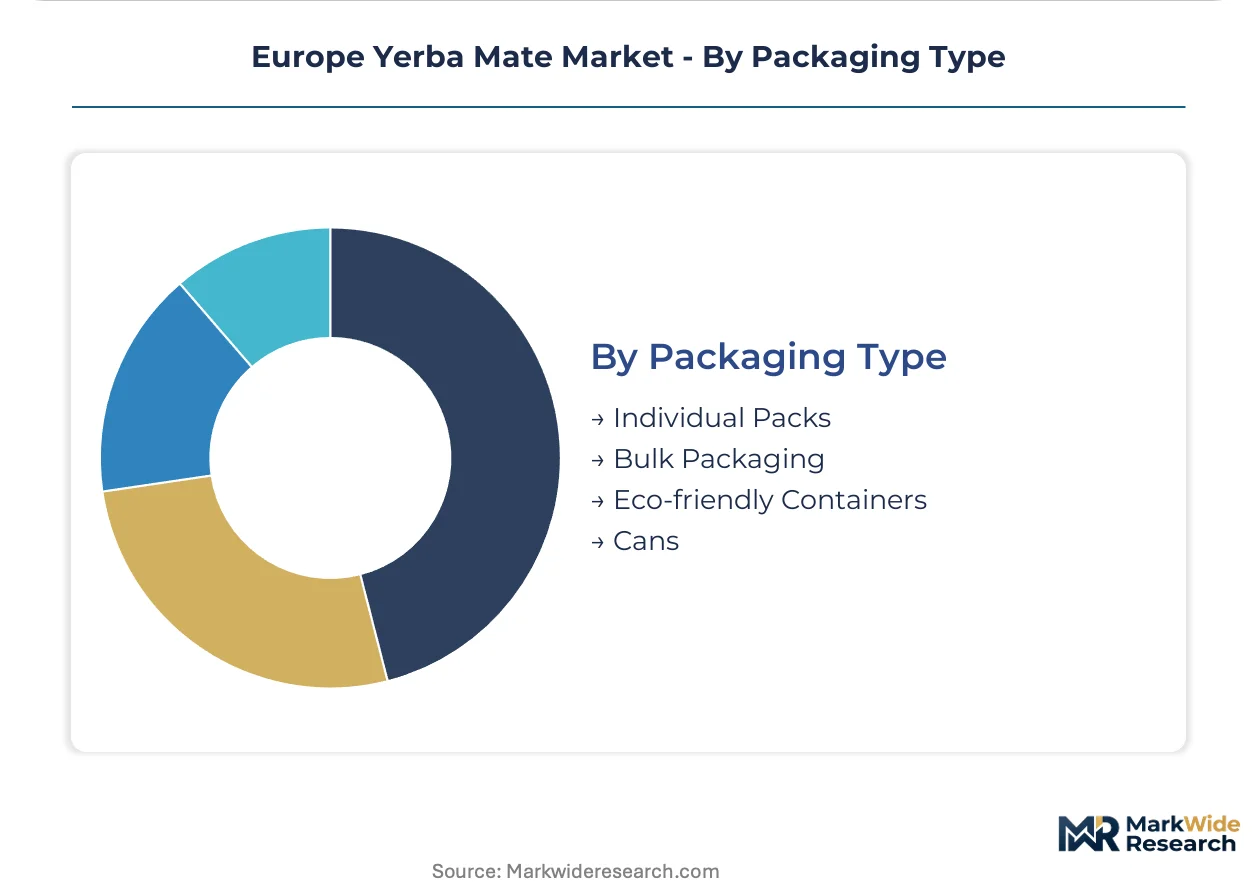
Eco-friendly containers absorb the bulk of sustainability-focused investment; cans are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban wellness consumers in Berlin, Hamburg, and Paris concentrate demand for organic-certified loose-leaf and ready-to-drink formats. EFSA novel food assessments and EU organic certification standards govern import eligibility across the region. Specialty coffee shop integration and carbon-transparent sourcing narratives are normalizing consumption among millennials previously unfamiliar with South American brewing traditions.
Germany
Berlin and Hamburg specialty coffee shops are expanding yerba mate menus as urban millennials seek natural energy alternatives. EFSA caffeine exposure guidelines and national caffeine labeling rules shape product formulation requirements. Hamburg importers operate direct-to-subscription platforms that prioritize harvest-date transparency and cooperative-specific provenance narratives.
France
Paris wellness cafés and Lyon health stores sustain premium margin pools through organic certification premiums. REACH compliance and F-Gas Regulation requirements tighten processing equipment specifications for French co-packers. Lyon beverage startups deploy pilot-scale nitrogen-chilled filling lines to capture convenience retail placement.
Spain
Madrid and Barcelona wellness retail remains underpenetrated relative to kombucha and matcha saturation. EU Green Deal alignment and climate-neutral shipping programs resonate with Spanish consumers seeking carbon-transparent stimulant alternatives. Barcelona specialty roasters are unbundling yerba mate from South American import bundles to create single-origin SKUs.
Netherlands
Amsterdam and Rotterdam convenience retail channels drive ready-to-drink can expansion through refrigerated shelving partnerships. CSRD reporting integration elevates cooperatives with blockchain-traceable harvest records above commodity traders in Dutch procurement evaluations. Rotterdam cold-chain logistics providers face refrigerant phase-out timelines favoring CO2-based systems.
Italy
Milan and Rome health-conscious consumers respond to polyphenol antioxidant claims in functional food applications. EU organic certification mandates 36-month conversion timelines for Argentine estates supplying Italian importers. Milan specialty beverage distributors are integrating yerba mate into energy shot and wellness beverage formulations.
Europe Yerba Mate Market Competitive Landscape
Strategic partnerships and direct-trade network expansion dominate the current landscape as importers restructure supply chains around documented provenance. The vendor base clusters around three archetypes: large-volume Argentine exporters with aging facility scale, European direct-trade specialists with organic certification focus, and ready-to-drink beverage startups with nitrogen-flush technology. M&A activity remains limited given the cooperative-heavy supply structure. Portfolio diversification into functional food extracts represents the secondary competitive move as manufacturers seek EFSA novel food authorization for compound-standardized products.
Among South American-origin suppliers, Taragüi exemplifies the scale-driven archetype through large-volume drying and aging infrastructure that reduces per-unit costs for bulk buyers. Meta Mate occupies the direct-trade specialist position, leveraging relationships with smallholder growers to secure organic-certified harvests. Guayaki Sustainable Rainforest Products Inc. anchors the sustainability-marketing tier, operating climate-neutral shipping programs and regenerative agriculture messaging that resonate with German and French wellness consumers.
| Leading Market Players |
|---|
| Meta Mate |
| Taragüi |
| Guayaki Sustainable Rainforest Products Inc. |
| Canarias |
| Rosamonte |
| ECOTEAS Organic Yerba Mate |
| Kraus |
| Pajarito |
| Yuyo Drinks Ltd |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU organic-certified and conventional commodity tiers manifests in divergent procurement economics and supply chain documentation burdens across European import channels. Premium single-origin positioning commands harvest-date transparency and blockchain-traceable cooperative records, while bulk conventional supply flows through undocumented trader networks vulnerable to EFSA novel food friction.
Pricing Analysis
Volume-mass versus margin-pool segmentation separates Argentine bulk exporters serving supermarket private-label programs from German direct-trade specialists capturing subscription-channel premiums. Three-tier pricing structure across premium organic, standard certified, and economy conventional levels reflects EU organic conversion timelines and laboratory verification costs. Pricing pressure stems from drought-driven input cost instability in Misiones Province harvests. Supermarket buyers exhibit highest price sensitivity; wellness café operators and direct-to-subscription platforms absorb premium positioning with lower elasticity.
Supply Chain Analysis
Workforce availability constraints in Argentine drying and aging facilities and Brazilian milling cooperatives limit processing capacity expansion for European contract volumes. Supply concentrates in Argentina, Brazil, and Paraguay as primary leaf sources, with secondary processing in Germany and France for ready-to-drink formulation. Raw material dependencies include Ilex paraguariensis leaf, nitrogen-flush packaging films, and aluminum can substrates. Single-source vulnerability runs through Misiones Province climate exposure. Distribution runs through Rotterdam and Hamburg port clusters into direct-to-subscription platforms, health store wholesale, and convenience retail cold-chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as importers pursue backward control over Argentine cooperative harvest records to secure EFSA-compliant documentation and compress novel food authorization timelines.
For Market Incumbents: Extend direct-trade network coverage into undercertified Argentine estates to capture 36-month organic conversion pipeline ahead of CSRD transparency mandates. Deepen cooperative-level blockchain traceability to defend margin position against commodity traders. EFSA caffeine exposure guideline revisions represent the named regulatory threat requiring formulation flexibility reserves. For New Entrants and Emerging Players: Launch via direct-to-subscription platforms targeting Madrid and Barcelona wellness retail whitespace currently dominated by kombucha and matcha. Spanish market underpenetration offers the most accessible geographic entry point. Nitrogen-chilled ready-to-drink formats bypass traditional gourd-brewing complexity barriers for millennial adoption. For Investors and Strategic Acquirers: Exit pathways concentrate in sustainability-marketing specialists with climate-neutral shipping programs and regenerative agriculture messaging that resonate with German and French wellness consumers. Long-term viability hinges on EFSA novel food authorization capabilities for compound-standardized extracts. Watch for EFSA caffeine exposure guideline finalization as inflection indicator for formulation-heavy portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Network Expansion | Secures organic-certified harvests with blockchain-traceable records for EFSA compliance. |
| Ready-to-Drink Format Innovation | Nitrogen-flush packaging preserves polyphenol integrity in shelf-stable aluminum cans. |
| CSRD Reporting Integration | Elevates cooperatives with documented provenance above commodity traders in procurement. |
| Functional Food Extract Development | Standardized caffeine concentrates require EFSA novel food authorization timelines. |
| Climate-Neutral Shipping Programs | Aligns with EU Green Deal carbon transparency for German and French consumers. |
Research Methodology
Multi-period observation of import volume flows, organic certification registrations, and EFSA novel food submission timelines anchored the trend analysis, supplemented by interviews with Argentine cooperative managers, German specialty beverage distributors, French health store category buyers, and Dutch cold-chain logistics operators. Secondary validation drew from EU organic certification databases, EFSA novel food registers, customs trade records, and CSRD implementation guidance documents. Bottom-up cooperative-level production estimates triangulated against top-down European import statistics.
Input-output matrix modeling connected Argentine and Brazilian harvest projections through processing capacity constraints to European channel placement volumes across the analysis window. Segmentation dimensions included product format, distribution channel, customer type, and packaging material. CAGRs derived from curve-fitting observed volume trajectories against EFSA regulatory timeline assumptions and specialty coffee shop expansion rates in Berlin, Hamburg, and Paris.
Drought severity in Misiones Province, EFSA novel food authorization delays, and refrigerant phase-out timelines for cold-chain fleets are the dominant revision risks that could compress or extend forecast outputs. Forecasts embed assumptions about cooperative conversion timelines and nitrogen-flush technology adoption rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Dairy Based Beverages Market
Beverages
Smart Home-Based Beverage Machine Market
Beverages
Hot Cocoa Mix Market
Beverages
Pineapple Juice Market
Beverages
Sparkling Juice Drinks Market
Beverages
Asia-Pacific Probiotic Drinks Market
Beverages
Tonic Water Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
Canned Beverages Market
Beverages
North America Kombucha Market
Beverages
Hydrogen Water Bottle Market
Beverages
Crystal Boba Market
Beverages
Cactus Water Market
Beverages
India Soy Beverages Market
Beverages
Craft Soda Market
Beverages
Rose Floral Water Market