
 Extra Virgin Olive Oil Market | 2026-2036
Extra Virgin Olive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Extra Virgin Olive Oil Market Analysis
Single-origin estate sourcing is rebalancing toward cooperative mill networks across Andalusia and Tuscany. Almazaras de La Subbética S.L. leverages its cooperative structure to secure Picual olive supply from over 4,000 member growers. Frantoio Franci anchors its market presence through heritage cultivar specialization in Montenero d'Orcia. Gallo Worldwide - Victor Guedes S.A. dominates Portuguese retail channels with vertically controlled groves in Alentejo.
Extra virgin olive oil denotes mechanically extracted olive juice with free acidity below 0.8% and peroxide value under 20 milliequivalents per kilogram, serving as the benchmark for unrefined culinary lipids. Organic product type commands margin premiums through certified grove management and traceable harvest documentation. Glass bottle packing type sustains shelf-life integrity for premium export segments despite higher logistics costs. Specialty store distribution channels concentrate per-unit profitability in urban gastronomy corridors.
EU EFSA health claim verification and IOC trade standards govern chemical parameter thresholds for cold-pressed classification. USDA organic certification and COOL labeling shape North American import access and retail placement. Stakeholders must monitor harvest yield volatility from Iberian drought cycles and calibrate inventory positions against Mediterranean basin climate projections.
Market Dynamics
EU EFSA health claim verification is compressing quality differentiation windows, forcing producers to document polyphenol retention through cold-extraction upgrades or surrender premium shelf positioning to certified competitors.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Approved cardiovascular benefit language enables premium pricing for oils meeting hydroxytyrosol thresholds, accelerating pharmacy and functional food channel placement.
- Cooperative Mill Networks:Andalusian almazara consolidation secures Picual supply volumes against Iberian drought volatility while reducing per-unit extraction costs for member growers.
- Foodservice Premiumization:Mediterranean culinary segments in urban gastronomy corridors specify origin-protected DOP/IGP oils for menu differentiation, pulling volume from commodity blends.
Market Restraints
- Iberian Climate Volatility:Andalusian and Alentejo harvest yield swings from irregular precipitation compress inventory planning horizons for bulk buyers.
- Input Cost Concentration:Glass bottle and tin packaging material costs track European energy pricing, squeezing margin structures for premium export-oriented bottlers.
- Substitution Pressure:High-oleic sunflower and avocado oils capture price-sensitive retail segments with comparable smoke-point performance at lower shelf prices.
Strategic Opportunities
- North American Organic Certification:USDA NOP and COOL labeling requirements create defensible positioning for estate producers with documented grove management and traceable harvest chains.
- Direct-to-Consumer Subscription Models:Quarterly harvest releases bypass conventional retail slotting fees while capturing lifetime value from enthusiast buyers seeking cultivar-specific freshness.
- Carbon Accounting Integration:EU Green Deal farm-to-fork reporting standards reward regenerative grove practices with preferential procurement terms from institutional foodservice buyers.
Industry Challenges
- Sensory Panel Calibration:IOC recognition requirements for official tasting panels create bottleneck capacity for new market entrants seeking export-grade certification.
- Legacy Equipment Retrofit Costs:Continuous extraction systems with temperature monitoring require capital outlays that strain cooperative balance sheets during low-yield harvest cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extra Virgin Olive Oil Market |
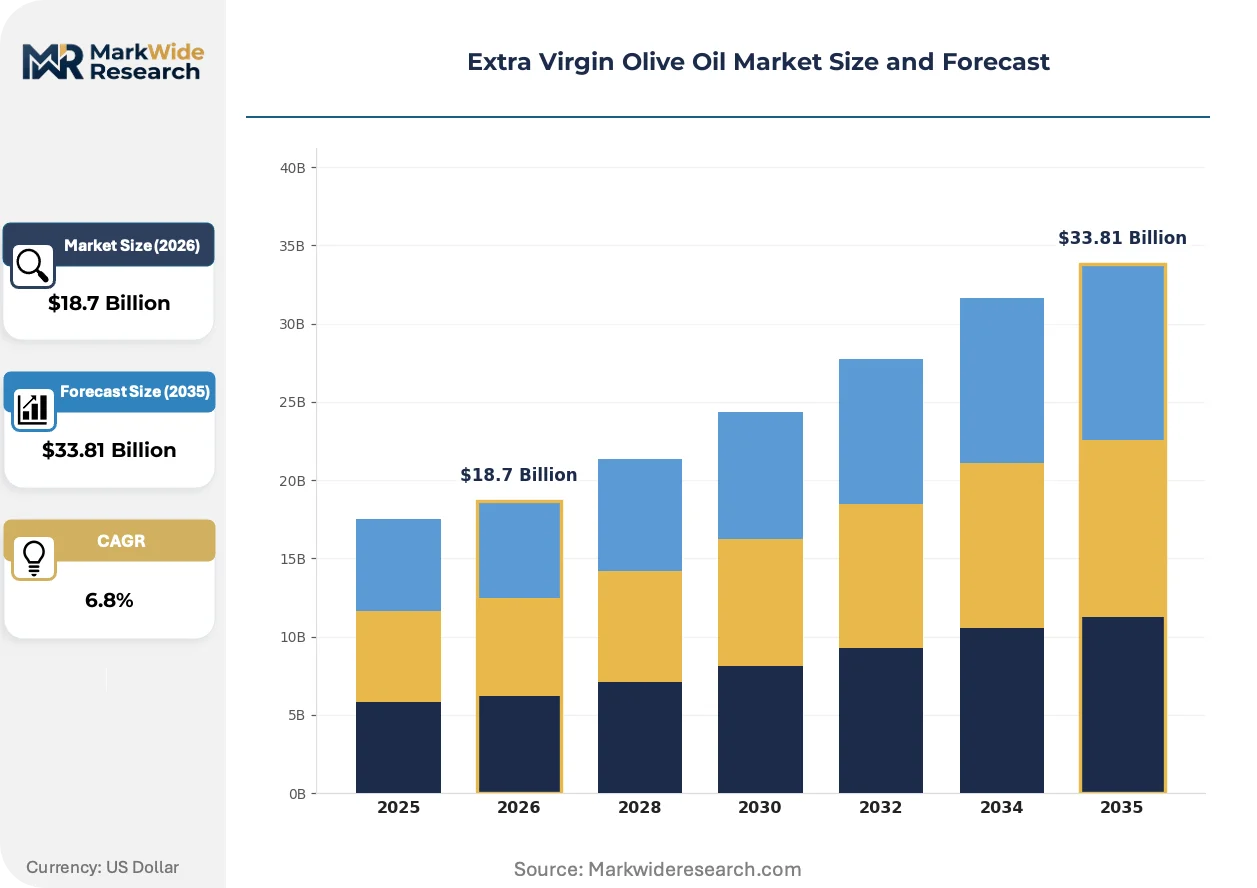
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Flavored, Infused Packing Type: Glass Bottles, Tin Cans, Plastic Bottles, Bulk Containers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Almazaras de La Subbética S.L., Fonte di Foiano, Nova Vera Gida ve Tarim San. Tic. A.S., Frantoio Bonamini, Comincioli, Gallo Worldwide - Victor Guedes S.A., Gaia Oliva Ltd. Sti., Frantoio Franci, Estância das Oliveiras Agroindustrial Ltda., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extra Virgin Olive Oil Market Emerging Trajectories
Traceability infrastructure and extraction automation are compressing information asymmetries between grove and consumer, while regulatory chemistry standards redefine what qualifies as cold-pressed.
Near-infrared spectroscopy coupled with blockchain harvest documentation is decentralizing quality verification away from centralized laboratory bottlenecks. Mid-sized Tuscan and Andalusian mills deploy portable NIR units for real-time free acidity and polyphenol screening at receiving stations. This compression of testing latency enables just-in-time blending decisions that optimize DOP compliance margins.
EU F-Gas Regulation phase-down schedules are accelerating mechanical harvesting adoption to compress fruit-to-mill transit windows. Traditional manual picking in steep-terrain groves faces labor availability constraints as refrigeration-dependent storage becomes cost-prohibitive. Producers in Greece's Peloponnese and Italy's Liguria are retrofitting straddle harvesters for super-high-density Arbequina and Koroneiki plantings.
Certification-driven preference rotation is displacing undifferentiated private-label volume in German and Benelux retail. Discounters now dedicate discrete shelf space to IOC-recognized extra virgin grades with harvest-date labeling, while conventional olive oil sections contract. This channel restructuring pressures Spanish and Portuguese bottlers to segregate export-grade lots from domestic commodity streams.
Extra Virgin Olive Oil Market Segmentation
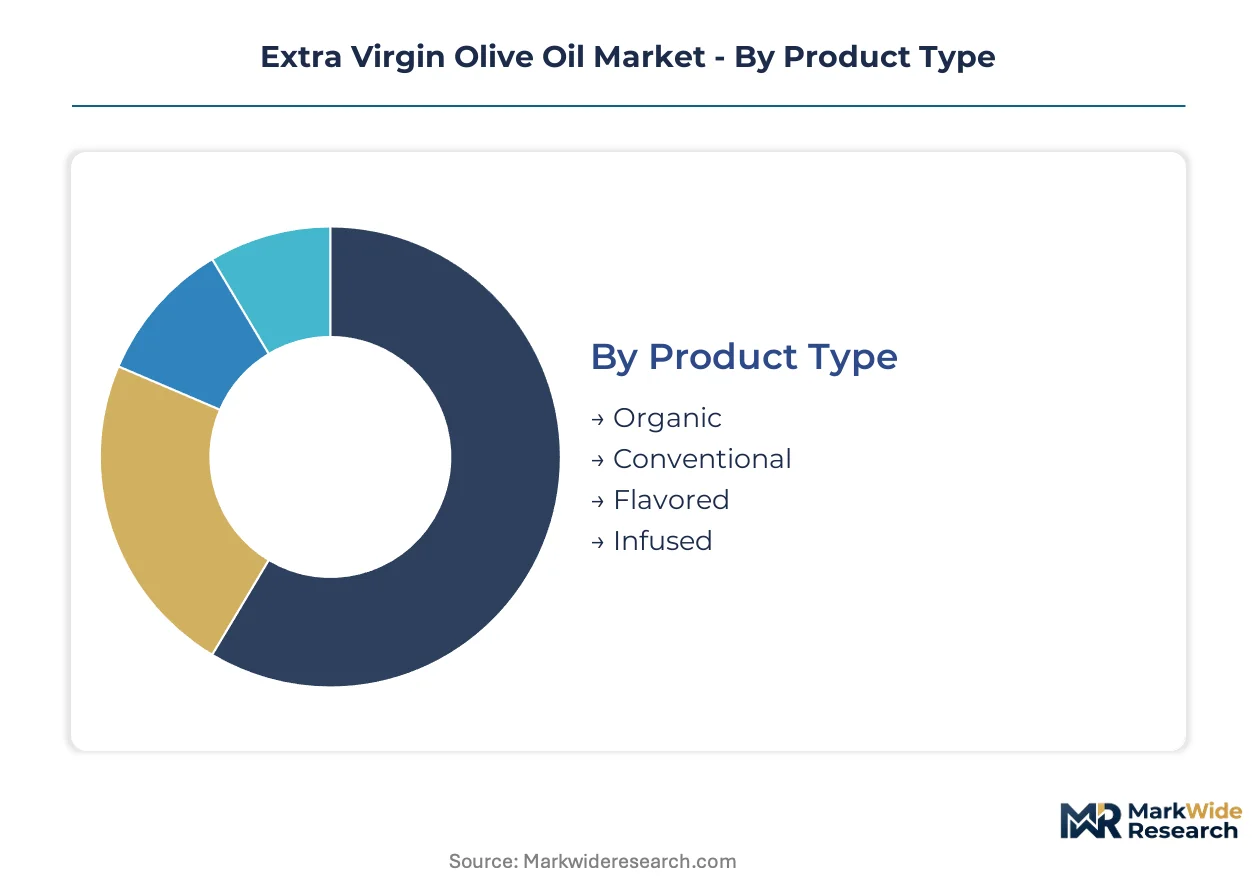
Segmentation in extra virgin olive oil separates commodity-grade volume from certified premium tiers. Cold-extraction documentation and origin-protected labeling create divergent margin structures across product and channel dimensions.
Product Type:
Consumer upgrade cycles from conventional to certified organic oils are shortening as EFSA health claim awareness spreads through pharmacy and functional food channels.
- Organic:Certified grove management with documented harvest chains commands retail premiums through USDA NOP and EU organic seals. Demand concentrates in German and Benelux supermarket channels where discounters now dedicate discrete shelf space to harvest-dated organic grades.
- Conventional:Mechanically extracted oils meeting IOC free acidity thresholds below 0.8% serve price-sensitive retail segments and bulk food manufacturing. Spanish and Portuguese bottlers segregate export-grade conventional lots from domestic commodity streams to defend margin positions.
- Flavored:Citrus and herb infusions target gift and gastronomy segments with limited-batch positioning.
- Infused:Chili and garlic variants capture ethnic cuisine adoption in North American urban corridors.
Volume placements concentrate in Conventional; the faster expansion belongs to Organic.
Packing Type:
Packaging cost tiers track European energy pricing, squeezing margin structures for export-oriented bottlers while shelf-life requirements dictate material selection.
- Glass Bottles:UV-protective dark glass sustains polyphenol integrity and flavor stability across extended supply chains. Premium export segments in Japanese and North American specialty stores absorb higher logistics costs for perceived quality signaling.
- Tin Cans:Light-impermeable metal packaging dominates Mediterranean foodservice procurement with lower unit costs than glass. Italian and Greek bulk exporters favor tin for institutional buyers prioritizing volume scale over retail presentation.
- Plastic Bottles:PET formats penetrate emerging market retail with cost advantages in last-mile distribution.
- Bulk Containers:Food manufacturers and catering services source flexitank and drum formats for blending operations.
Glass Bottles anchor premium positioning; Plastic Bottles are climbing the fastest in volume terms.
Distribution Channel:
Channel restructuring is displacing undifferentiated private-label volume as discounters segregate IOC-recognized grades from conventional olive oil sections.
- Supermarkets:Multi-brand retail chains in Spain and Italy consolidate shelf space around DOP-certified oils with harvest-date transparency. Centralized procurement teams now require cold-extraction documentation and sensory panel scores for premium placement.
- Specialty Stores:Urban gastronomy corridors in Paris, London, and New York concentrate per-unit profitability through cultivar-specific curation and tasting education. Direct importer relationships bypass conventional slotting fees.
- Online Retail:Subscription models capture enthusiast lifetime value with quarterly harvest releases.
- Wholesalers:Foodservice distributors aggregate volume for restaurant and catering procurement.
Supermarkets dominate volume throughput; Specialty Stores show the steepest expansion trajectory.
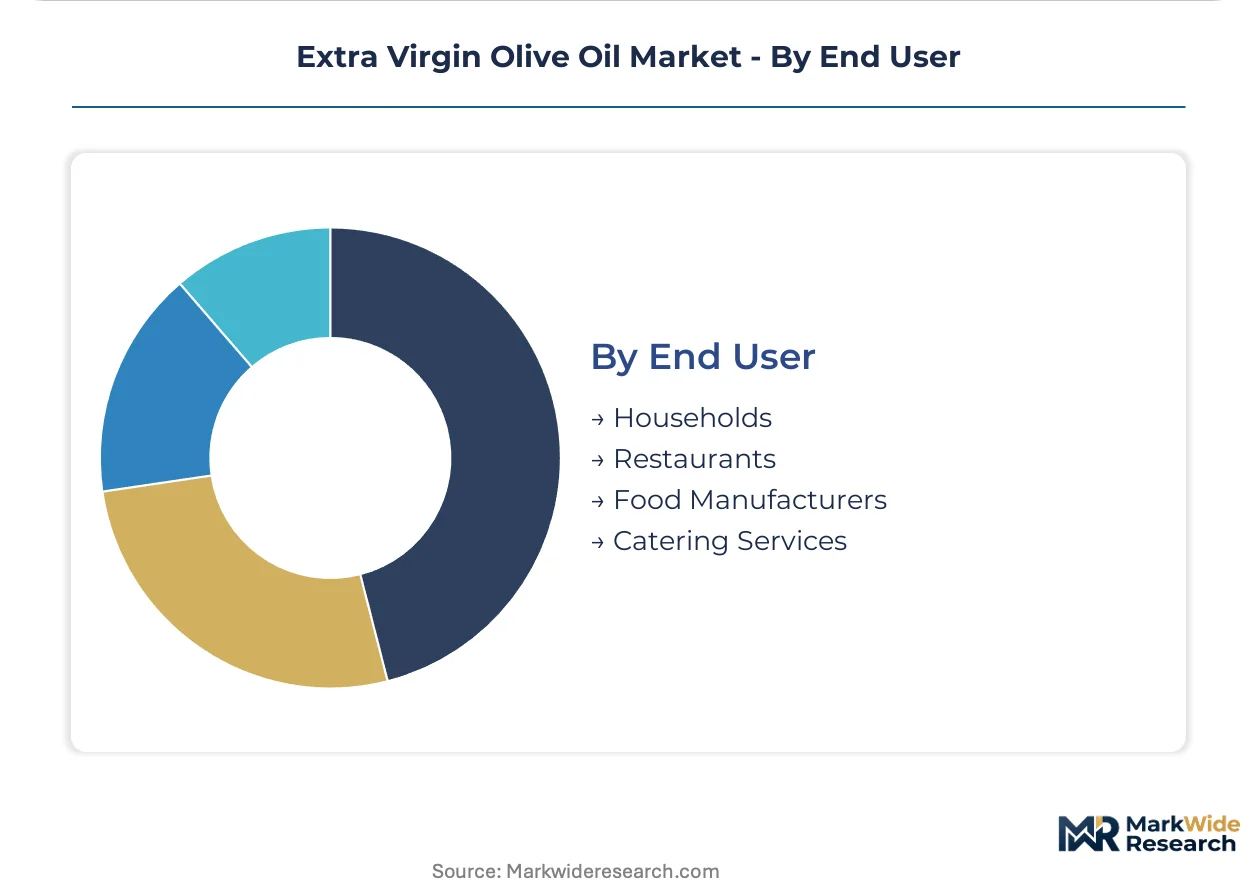
End User:
End-use concentration shapes extraction scale and certification requirements, with food manufacturing demanding bulk consistency against household preference for origin narrative.
- Households:Enthusiast buyers in North American and Japanese markets drive direct-to-consumer subscription growth with cultivar-specific freshness demands. EFSA cardiovascular benefit language accelerates pharmacy channel placement for polyphenol-rich oils.
- Restaurants:Mediterranean culinary segments specify origin-protected DOP/IGP oils for menu differentiation, pulling volume from commodity blends in Barcelona, Rome, and Lisbon gastronomy corridors.
- Food Manufacturers:Blending operations require consistent chemical parameters for processed food integration.
- Catering Services:Institutional procurement prioritizes cost-efficient bulk formats with basic IOC compliance.
Households represent the largest volume placement; Restaurants are gaining share fastest among end-use categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Picual olive groves across Andalusia supply the raw material base that anchors Mediterranean extra virgin olive oil production, with harvest volumes fluctuating around Iberian precipitation cycles.
Spain
Andalusian cooperative mills process Picual harvests from over 4,000 member growers, consolidating supply against drought-induced yield volatility. EFSA health claim verification requirements under EU Regulation 432/2012 pressure producers to document polyphenol retention through cold-extraction upgrades. Jaén province concentrates almazara infrastructure where continuous extraction systems with temperature monitoring are displacing legacy batch equipment.
Italy
Tuscan and Ligurian groves drive premium DOP/IGP certification demand through heritage cultivar specialization in Montenero d'Orcia. EU organic certification schemes shape export access to German and Benelux retail channels where discounters now segregate harvest-dated grades. Florence-Bologna gastronomy corridors pull volume from commodity blends as restaurants specify origin-protected oils for menu differentiation.
Greece
Peloponnese Koroneiki harvests supply bulk exporters prioritizing tin-can formats for institutional Mediterranean foodservice buyers. IOC trade standards govern chemical parameter thresholds for cold-pressed classification, with sensory panel recognition creating bottleneck capacity for new entrants. Kalamata sub-regions are retrofitting straddle harvesters for super-high-density plantings as F-Gas Regulation phase-downs compress fruit-to-mill transit windows.
United States
California Central Valley groves are expanding super-high-density Arbequina acreage to serve North American organic certification demand through USDA NOP and COOL labeling. FDA food safety oversight intersects with state-level agricultural inspection regimes for import-grade verification. Napa-Sonoma specialty store clusters concentrate per-unit profitability through cultivar-specific curation and direct-to-consumer subscription models.
Turkey
Aegean and Marmara basin groves supply conventional grades to Middle Eastern bulk food manufacturing and catering procurement channels. National agricultural ministry programs support mechanical harvesting adoption to reduce labor dependency in steep-terrain operations. Izmir-based mill networks are consolidating receiving capacity to meet IOC free acidity thresholds for export-grade certification.
Extra Virgin Olive Oil Market Vendor Landscape
Global majors compete with regional champions across extraction scale and origin-protected certification tiers, producing a market structure where cooperative networks and estate producers occupy distinct strategic positions. Consolidation pressures concentrate around cold-extraction documentation capabilities and sensory panel accreditation. Three archetypes dominate: vertically integrated estate specialists, cooperative mill aggregators, and retail-channel bottlers with captive grove access. Competitive moves center on almazara equipment upgrades for polyphenol retention verification and direct-to-consumer subscription infrastructure to bypass conventional retail slotting fees.
Among Iberian cooperative structures, Almazaras de La Subbética S.L. exemplifies the aggregator archetype through member-grower network scale, while Gallo Worldwide - Victor Guedes S.A. represents retail-channel verticalization with Alentejo grove control. Frantoio Franci occupies the heritage estate position within Tuscan DOP corridors.
| Leading Market Players |
|---|
| Almazaras de La Subbética S.L. |
| Fonte di Foiano |
| Nova Vera Gida ve Tarim San. Tic. A.S. |
| Frantoio Bonamini |
| Comincioli |
| Gallo Worldwide - Victor Guedes S.A. |
| Gaia Oliva Ltd. Sti. |
| Frantoio Franci |
| Estância das Oliveiras Agroindustrial Ltda. |
| Others |
Supply Flow & Price Mechanics
Skilled sensory panelists concentrated in Jaén province and Tuscany drive labor-cost differentials that widen pricing-tier spreads between commodity bulk oils and certified premium grades. EFSA health claim verification requirements and IOC tasting panel accreditation bottlenecks concentrate quality-assurance expertise in these regions, forcing bottlers to absorb premium labor costs or surrender shelf positioning.
Pricing Analysis
Harvest-date transparency and cold-extraction documentation bundled into premium SKUs separate certified organic grades from unbundled conventional bulk offerings. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and polyphenol retention verification. Pricing pressure stems from Iberian drought-induced yield volatility compressing margin structures for cooperative mills. Food manufacturers represent the most price-sensitive buyers, while Japanese specialty store purchasers show lowest sensitivity to per-unit premiums.
Supply Chain Analysis
EU Green Deal farm-to-fork reporting standards and domestic-content preferences for origin-protected DOP/IGP oils are reshaping sourcing toward traceable cooperative networks in Spain, Italy, and Greece. Raw material flows draw from Picual, Koroneiki, and heritage Tuscan cultivars with harvest timing compressed by F-Gas Regulation-driven mechanical adoption. Single-source vulnerability concentrates in Andalusian almazara infrastructure facing drought-induced volume swings. Distribution runs through cooperative mill aggregators supplying retail-channel bottlers with segregated export-grade lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around cold-extraction documentation capabilities, with EFSA health claim verification costs forcing sub-scale producers into cooperative structures or exit.
For Market Incumbents: Deepen sensory panel accreditation capacity to secure IOC export-grade certification bottlenecks that block new entrants. Expand backward integration into super-high-density Arbequina and Koroneiki plantings in Alentejo and Peloponnese to compress fruit-to-mill transit windows against F-Gas refrigeration cost pressures. For New Entrants and Emerging Players: Portable near-infrared spectroscopy units for real-time polyphenol screening offer a technology-first wedge into mid-sized Tuscan and Andalusian mill networks seeking just-in-time blending optimization. Target North American direct-to-consumer subscription channels with quarterly harvest releases bypassing conventional retail slotting fees. For Investors and Strategic Acquirers: Re-rating potential sits with cooperative mill aggregators possessing documented member-grower networks above 3,000 hectares given EU organic certification demand acceleration through German and Benelux discounter channels. Long-term viability favors estate producers with captive DOP/IGP positioning and traceable harvest chains. Watch IOC sensory panel recognition timelines as inflection indicators for export-grade capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Extraction Equipment Upgrade | EFSA health claim verification secures premium pharmacy and functional food channel placement against certified competitors. |
| Cooperative Mill Network Consolidation | Andalusian almazara aggregation secures Picual supply volumes against Iberian drought volatility while reducing per-unit extraction costs. |
| Direct-to-Consumer Subscription Launch | Quarterly harvest releases capture lifetime value from North American enthusiast buyers seeking cultivar-specific freshness. |
| USDA Organic Certification Investment | Documented grove management and traceable harvest chains create defensible positioning in COOL-labeled retail segments. |
| Carbon Accounting Integration | EU Green Deal regenerative grove practices unlock preferential procurement terms from institutional foodservice buyers. |
Methodological Framework
Independent corroboration across olive mill operations managers, cooperative board representatives, EFSA regulatory affairs specialists, and North American specialty store buyers underwrites the qualitative findings. Secondary validation draws from IOC trade standard filings, EU organic certification registries, USDA NOP compliance databases, and Mediterranean customs export records. Bottom-up volume estimates from almazara receiving station data triangulate against top-down consumption projections from retail audit channels.
Rate-of-change decomposition across the analysis window segments expansion by product type, packing format, distribution channel, and end-use application. CAGRs derive from harvest yield modeling, pricing elasticity by certification tier, and channel shift assumptions. Forecast inputs incorporate Iberian precipitation cycle projections and EU F-Gas Regulation phase-down schedules affecting mechanical harvesting adoption.
Several conditions sit outside the modeled scope, including extreme climate events beyond historical drought patterns, trade policy disruptions affecting olive oil tariffs, and breakthrough substitution technologies in high-oleic alternative oils. Forecasts reflect documented assumptions about cooperative consolidation trajectories and sensory panel capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Hydrogen Water Bottle Market
Beverages
Flavored Powder Drinks Market
Beverages
Europe Juices Market
Beverages
Collagen-Infused Water Market
Beverages
Asia Pacific Fruits and Vegetables Juice Market
Beverages
Italy Bottled Water Market
Beverages
Pineapple Juice Market
Beverages
Premium Water Market
Beverages
Drinking Water Market
Beverages
India Bottled Water Market
Beverages
Ginger Ale Market
Beverages
Europe Smoothies Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Asia-Pacific Vinegar Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Middle East and Africa Ready to Drink Beverages Market