
 Asia-Pacific Probiotic Drinks Market | 2026-2036
Asia-Pacific Probiotic Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Probiotic Drinks Market Analytics
The rising athlete segment is repositioning probiotic drinks from general wellness toward performance recovery positioning in the Asia-Pacific region. Yakult Honsha Co. Ltd leverages its century-long fermentation expertise to dominate daily-dose yogurt drink distribution across Japanese and Southeast Asian convenience networks. Amul anchors India's dairy-based probiotic portfolio through its extensive cooperative milk collection infrastructure, while Danone S.A. competes in premium plant-based fermented beverages targeting lactose-intolerant urban consumers.
Asia-Pacific probiotic drinks comprise live microbial cultures suspended in fermented liquid matrices, typically containing minimum colony-forming units per serving that must survive gastric transit to confer documented gastrointestinal benefits. Commercial production employs controlled-temperature fermentation of dairy, tea, or plant substrates followed by cold stabilization to preserve viable bacterial populations. Fermented milk maintains the largest volume position across the region, though kombucha registers the fastest growth trajectory driven by sugar-conscious younger demographics. Online retailers capture expanding margin pools as direct-to-consumer subscription models bypass traditional supermarket slotting fees in markets like South Korea and Australia.
Japan's Ministry of Health, Labour and Welfare enforces FOSHU certification requirements that mandate clinical evidence for all health claims on probiotic labels, creating a compliance barrier that filters smaller regional entrants. China's National Health Commission and SAMR jointly administer new food raw material approvals, including novel probiotic strains not listed in the national food safety standards. Australia's TGA and FSANZ coordinate on complementary medicine classification boundaries that determine whether probiotic drinks carry therapeutic claims or standard food labeling. Stakeholders must monitor evolving strain-specific approval pathways as each Asia-Pacific jurisdiction develops distinct evidence requirements for live culture efficacy substantiation.
Market Dynamics
Cold-chain infrastructure expansion across China's tier-one cities is eliminating the historical distribution barrier that constrained refrigerated probiotic shelf life, enabling live-culture beverages to reach convenience stores at viable bacterial counts for the first time.
Growth Catalysts
- FOSHU Certification Framework:Japan's Ministry of Health, Labour and Welfare validates clinical efficacy standards for digestive health claims, creating consumer trust premiums that regional brands leverage for export credibility.
- Plant-Based Fermentation:Advances in oat and coconut substrate processing enable dairy-free probiotic matrices targeting lactose-intolerant urban populations in metropolitan India and Southeast Asia.
- Athlete Segment Positioning:Sports nutrition channels in Australia and South Korea reposition probiotic drinks toward performance recovery, expanding addressable occasions beyond general wellness.
Market Restraints
- Strain Approval Bottlenecks:China's National Health Commission and SAMR require novel probiotic strain registration through new food raw material pathways, extending product development timelines by 18-36 months.
- Refrigerated Distribution Costs:Cold-chain energy expenses and last-mile refrigeration requirements compress margins in Indonesia and Philippines where ambient-temperature logistics dominate beverage distribution.
- Clinical Evidence Burden:Australia's TGA and FSANZ coordinate on therapeutic claim boundaries that force brands to choose between costly clinical trials or restricted food-label positioning.
Strategic Opportunities
- Tier-Two City Penetration:China's cold-chain networks now reach Chengdu, Xi'an, and Wuhan, opening distribution white space beyond saturated Beijing-Shanghai-Guangzhou corridors.
- Direct-to-Consumer Subscriptions:South Korean and Australian online retailers bypass supermarket slotting fees through refrigerated home-delivery models, capturing margin pools previously lost to retail intermediaries.
- Sugar-Conscious Formulation:Kombucha and water kefir variants with reduced glycemic loads address younger demographic preferences in Japan and Taiwan, differentiating from traditional sweetened yogurt drinks.
Industry Challenges
- Viability Testing Expertise:Colony-forming unit verification through gastric transit simulation requires specialized microbiology talent scarce across Southeast Asian quality control laboratories.
- Legacy Dairy Infrastructure:India's cooperative milk collection networks optimize for volume throughput rather than temperature-controlled probiotic preservation, necessitating parallel cold-chain construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Probiotic Drinks Market |
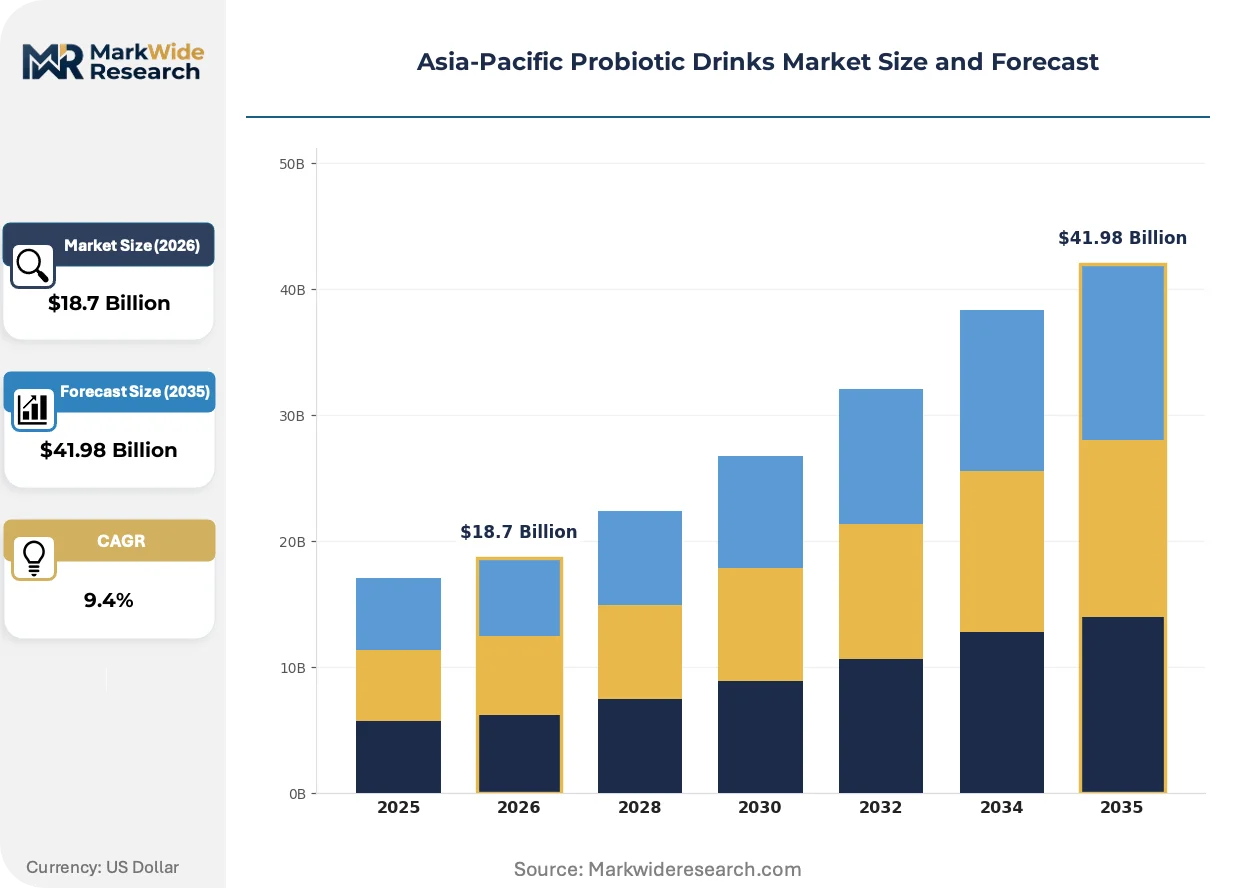
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermented Milk, Kefir, Kombucha, Plant-Based Drinks Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores End User: Health-Conscious Consumers, Athletes, Lactose-Intolerant Individuals, General Population Flavor Profile: Fruit-Flavored, Herbal, Plain, Exotic Blends |
| Companies Covered | PepsiCo, Inc., Amul, Yakult Honsha Co. Ltd, Kerry Group PLC, General Mills, Inc., Nestle S.A., Fonterra Co-operative Group Limited, Lifeway Foods, Inc., Danone S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Probiotic Drinks Market Evolving Landscape
Live-culture stabilization technologies and regulatory evidence frameworks are converging to transform how probiotic beverages demonstrate efficacy and maintain viability through distribution.
Microencapsulation technology is integrating protective lipid or protein coatings around bacterial cells to extend shelf stability without continuous refrigeration. Japanese and Australian manufacturers adopt this approach for ambient-distribution products targeting convenience channels. The technology is compressing the historical trade-off between bacterial survival rates and distribution reach.
Japan's FOSHU system is tightening clinical evidence requirements for gastrointestinal benefit claims, mandating human intervention studies for new probiotic strain approvals. This regulatory compression filters smaller entrants lacking research budgets while rewarding established players with existing trial portfolios. Australian brands seeking export positioning into Japanese channels now pre-emptively commission FOSHU-aligned studies.
Subscription-based replenishment models are displacing traditional retail procurement for daily-consumption probiotic regimens. South Korean consumers increasingly purchase monthly Yakult or kombucha deliveries through platform apps, bypassing convenience store intermediaries. This channel shift concentrates in metropolitan Seoul and Busan where delivery density supports refrigerated last-mile economics.
Asia-Pacific Probiotic Drinks Market Segmentation
Segmentation in Asia-Pacific probiotic drinks reveals how formulation choices, channel access, and consumer physiology intersect to determine purchasing patterns. Buyers select products based on digestive tolerance, performance goals, and cold-chain availability rather than price alone.
Product Type:
Buyers prioritize substrate compatibility with their metabolic constraints and daily consumption rituals.
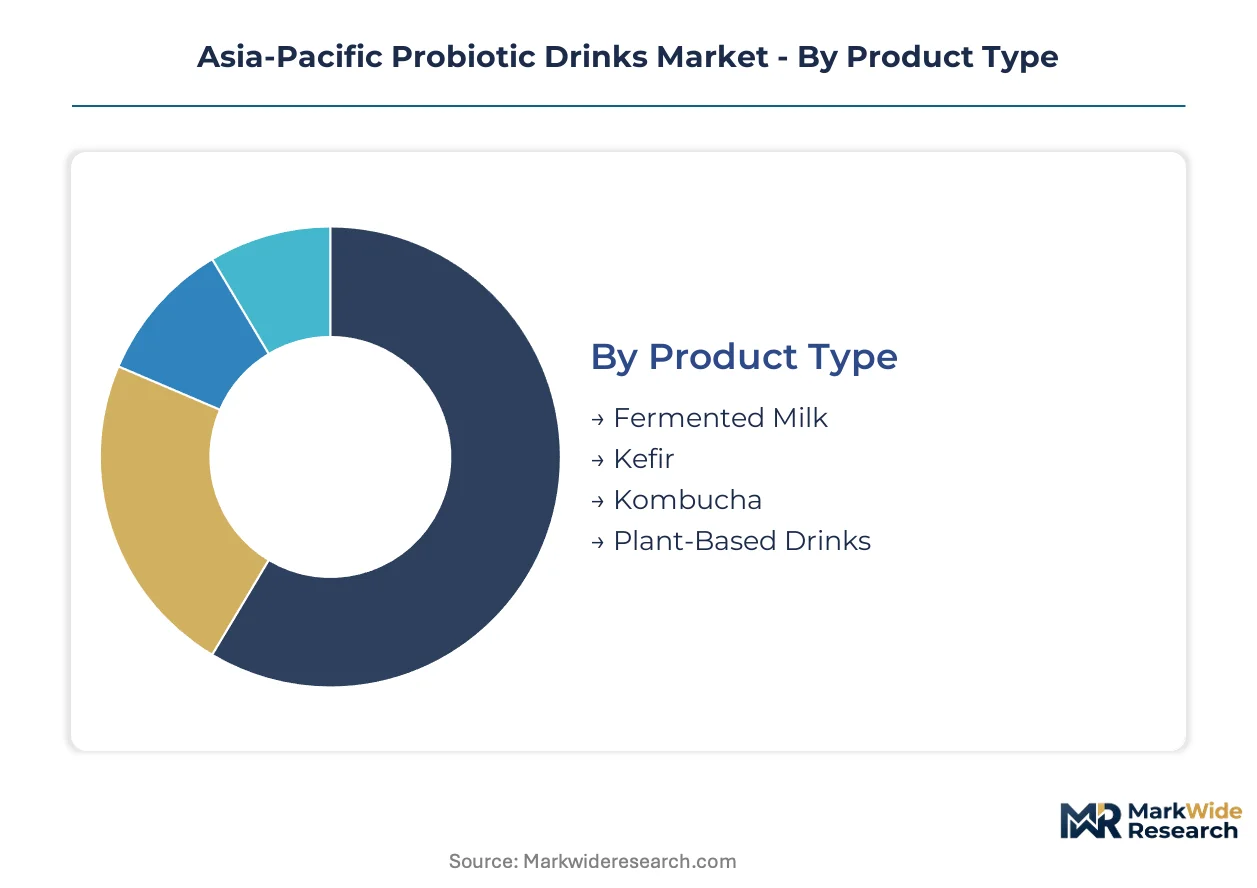
- Fermented Milk:Traditional dairy matrices containing Lactobacillus and Bifidobacterium strains dominate Japanese and Indian household consumption. Volume concentrates in Japan's convenience store networks and India's cooperative dairy channels where daily-dose formats anchor repeat purchase behavior.
- Kombucha:Tea-based fermentation with acetic acid bacteria and yeast cultures appeals to sugar-conscious younger demographics in Australia and South Korea. Demand clusters in Seoul and Sydney where wellness-focused retail chains stock refrigerated variants with reduced glycemic loads.
- Kefir:Fermented milk drink with diverse microbial consortium including lactobacilli, yeasts, and acetic acid bacteria targets Eastern European heritage communities and emerging adopters in China's tier-one cities.
- Plant-Based Drinks:Oat, coconut, and soy substrates processed with proprietary probiotic strains serve lactose-intolerant urban populations across metropolitan India and Southeast Asia.
Volume sits with Fermented Milk; growth tilts toward Kombucha.
Distribution Channel:
Channel selection reflects cold-chain maturity and consumer replenishment cadence across the region.
- Supermarkets:Multi-brand refrigerated aisles in Australia's Coles and Woolworths, Japan's AEON, and China's Hema Fresh anchor weekly stock-up purchasing for family households with established probiotic routines.
- Online Retailers:Direct-to-consumer subscription platforms in South Korea and Australia bypass slotting fees and capture margin pools through refrigerated home delivery.
- Health Stores:Specialist retailers in Japan and Taiwan stock premium functional beverages with FOSHU-certified claims, targeting consumers seeking clinical validation.
- Convenience Stores:7-Eleven and Lawson networks across Thailand and Philippines struggle with ambient-temperature logistics, limiting viable bacterial counts despite high foot traffic.
Revenue concentrates in Supermarkets; expansion accelerates through Online Retailers.
End User:
User physiology and performance objectives drive strain-specific formulation requirements.
- Health-Conscious Consumers:Preventive wellness seekers in Japan and Taiwan purchase daily-dose fermented milk for digestive maintenance, responding to FOSHU-certified efficacy claims.
- Athletes:Sports nutrition channels in Australia and South Korea stock probiotic recovery beverages targeting gut permeability reduction post-exertion.
- Lactose-Intolerant Individuals:Dairy-free substrates in plant-based and kombucha formats serve Southeast Asian and Indian urban populations with high lactase non-persistence rates.
- General Population:Mass-market adoption in China's tier-two cities depends on cold-chain infrastructure reaching Chengdu and Wuhan with viable live-culture products.
Health-Conscious Consumers anchor current volume; Athletes represent the steepest expansion trajectory.
Flavor Profile:
Palatability preferences vary by market maturity and local ingredient familiarity.
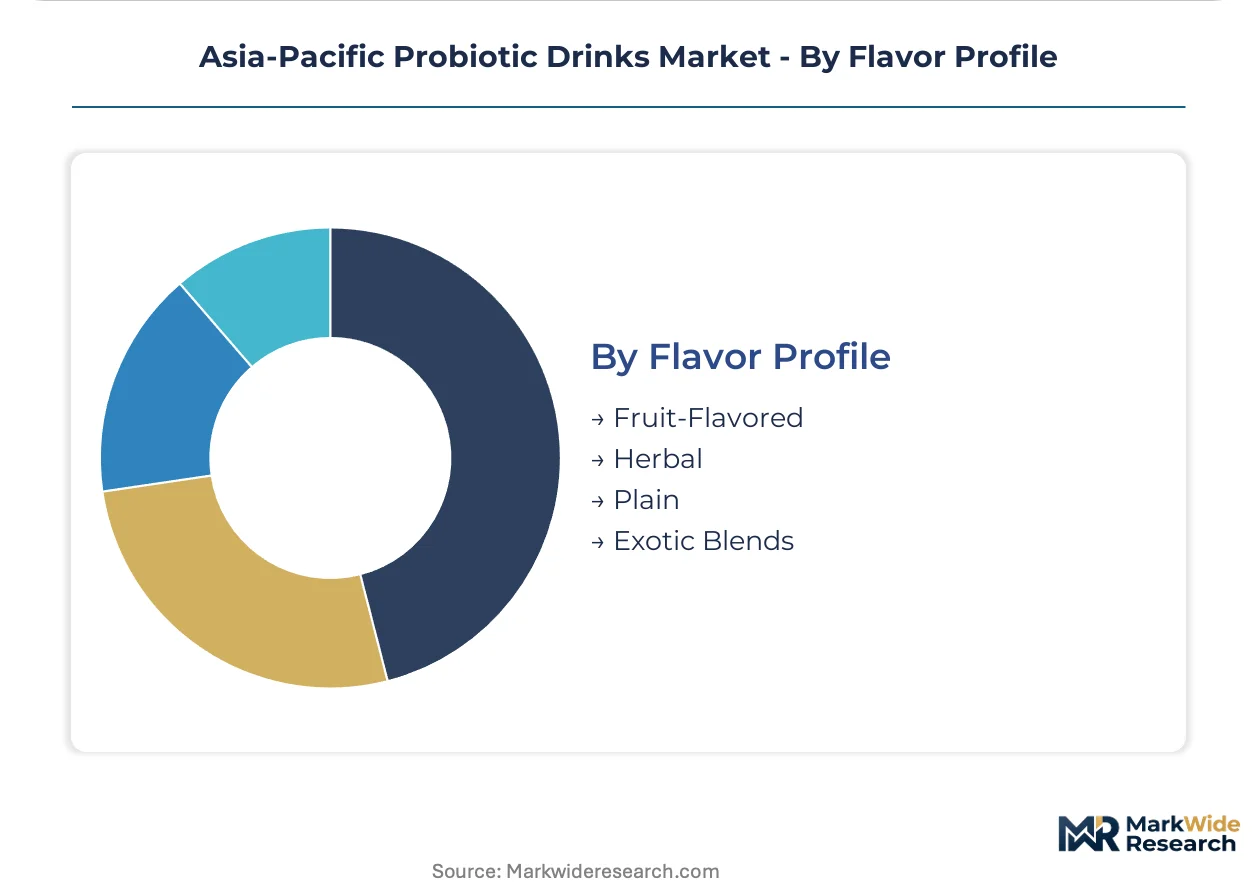
- Fruit-Flavored:Mango, lychee, and passionfruit variants dominate Southeast Asian markets where sweetness masks fermentation acidity for new adopters.
- Plain:Unsweetened traditional formats retain loyal following among Japanese elderly consumers with decades of Yakult consumption history.
- Herbal:Ginger, turmeric, and ginseng infusions target functional positioning in South Korea and Taiwan, aligning with traditional medicine associations.
- Exotic Blends:Yuzu, calamansi, and jackfruit combinations test niche appeal in premium Australian and Japanese specialty channels.
Fruit-Flavored variants capture mainstream volume; Herbal profiles gain share fastest in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates probiotic drink production through century-old fermentation infrastructure, while consumption spreads across China's expanding cold-chain corridors and India's dairy cooperative networks. The production-consumption divide creates distinct competitive dynamics in each national market.
Japan
Daily-dose fermented milk consumption anchors household purchasing patterns, with FOSHU certification from the Ministry of Health, Labour and Welfare validating clinical efficacy claims. Tokyo and Osaka metropolitan areas concentrate convenience store distribution networks that sustain high-frequency replenishment models. Nagoya's industrial corridor hosts specialized fermentation equipment manufacturing that supplies regional bottling facilities.
China
Tier-one cities drive refrigerated probiotic adoption as cold-chain infrastructure reaches Chengdu, Xi'an, and Wuhan with viable bacterial counts. SAMR and the National Health Commission jointly administer novel strain approvals through new food raw material pathways. Shanghai's Yangpu District clusters dairy processing plants with direct port access for imported culture strains.
India
Metropolitan professionals in Mumbai and Delhi purchase functional beverages with digestive health positioning, while Amul's cooperative infrastructure anchors dairy-based probiotic distribution. FSSAI regulates functional food claims under the Food Safety and Standards Act. Gujarat's Anand district concentrates cooperative milk collection networks that feed regional processing capacity.
South Korea
Subscription-based replenishment models displace convenience store purchasing in Seoul and Busan, with platform apps capturing recurring revenue streams. MFDS oversees health functional food certification requirements for probiotic efficacy claims. Gyeonggi Province's logistics corridors enable refrigerated last-mile delivery density that sustains direct-to-consumer economics.
Australia
Sports nutrition channels reposition probiotic drinks toward athlete recovery applications, expanding addressable occasions beyond general wellness. TGA and FSANZ coordinate on therapeutic claim boundaries that determine labeling classification. Sydney and Melbourne metropolitan areas concentrate specialty health retailers stocking premium functional beverages with clinical validation.
Asia-Pacific Probiotic Drinks Market Competitive Landscape
Top-tier vendors anchor daily-dose distribution through convenience networks, while mid-tier challengers compete on plant-based substrates and direct-to-consumer channels. The vendor base stratifies across fermentation specialists, dairy cooperatives, and diversified beverage conglomerates with functional food portfolios. Three archetypes dominate: heritage fermentation houses with century-long strain libraries, dairy cooperatives leveraging raw milk access, and multinational CPG players with cross-category R&D budgets. Competitive moves concentrate on cold-chain partnerships for ambient-distribution viability and clinical evidence investments for regulatory certification.
Within the heritage fermentation tier, Yakult Honsha Co. Ltd exemplifies century-long expertise in controlled bacterial culture propagation. Among diversified CPG conglomerates, PepsiCo, Inc. and Nestle S.A. occupy positions spanning beverage portfolios with functional health extensions. Danone S.A. represents the dairy-centric multinational archetype with investments in plant-based fermentation alternatives. These three companies illustrate distinct strategic postures without exhausting the competitive field.
| Leading Market Players |
|---|
| PepsiCo, Inc. |
| Amul |
| Yakult Honsha Co. Ltd |
| Kerry Group PLC |
| General Mills, Inc. |
| Nestle S.A. |
| Fonterra Co-operative Group Limited |
| Lifeway Foods, Inc. |
| Danone S.A. |
| Others |
Value Network & Pricing Analysis
Milk powder futures and cold-chain diesel indices cascade through Asia-Pacific probiotic manufacturing into three-tier pricing structures across premium, standard, and economy levels. Japanese FOSHU-certified products command certification premiums while Indonesian ambient-distribution variants absorb logistics compression.
Pricing Analysis
Margin tightening in economy-tier ambient products reflects diesel cost pass-through and last-mile refrigeration gaps. Pricing stratifies across premium, standard, and economy tiers: FOSHU-certified Japanese imports carry clinical-evidence premiums, cooperative dairy brands leverage raw milk access for standard-tier positioning, and Southeast Asian ambient formats compete on accessibility. Cost compression in Indonesian and Philippine distribution accelerates because ambient logistics dominate beverage channels. Health-conscious consumers in Japan and Taiwan demonstrate lowest price sensitivity; general population buyers in China's tier-two cities exhibit highest elasticity.
Supply Chain Analysis
China's SAMR strain-approval mandates reshape sourcing toward domestic culture-bank partnerships and registered-supplier lists. Concentration sits with Japan, Australia, and China: Japanese heritage houses anchor strain libraries, Australian sports-nutrition specialists control athlete-segment formulations, Chinese processors dominate volume manufacturing. Raw material dependencies center on dairy substrates, tea cultures, and specialized probiotic strains. Single-source vulnerability runs through Japanese culture-bank dependencies for FOSHU-aligned strains. Distribution runs through refrigerated supermarket networks in Australia and Japan, subscription platforms in South Korea, and cooperative dairy channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific probiotic drinks have become a vertical-integration race as players pursue backward integration into strain-bank ownership to bypass approval bottlenecks and secure proprietary culture access.
For Market Incumbents: Deepen cold-chain partnerships in China's tier-two corridors to preempt emerging cooperative dairy entrants. Acquire or license proprietary strain libraries to defend against plant-based fermentation disruptors targeting lactose-intolerant segments. Lock in FOSHU-aligned clinical trial portfolios before Japan's Ministry of Health, Labour and Welfare tightens evidence requirements. For New Entrants and Emerging Players: Begin with direct-to-consumer subscription models in South Korea and Australia where platform density supports refrigerated last-mile economics. Target kombucha and water kefir white space in sugar-conscious younger demographics. Pursue athlete-segment positioning through sports nutrition channels to bypass saturated general wellness competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier plant-based fermentation specialists in Southeast Asia facing ambient-distribution margin compression. Five-to-ten year viability hinges on regulatory navigation capability across China's SAMR and Japan's FOSHU frameworks. Watch MFDS certification timelines in South Korea as inflection indicator for subscription-model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Refrigerated distribution networks in Chengdu and Wuhan unlock tier-two penetration for live-culture viability. |
| FOSHU-Aligned Clinical Investment | Human intervention studies satisfy Japan's Ministry of Health, Labour and Welfare tightening efficacy standards. |
| Strain-Bank Acquisition | Proprietary culture libraries bypass China's SAMR new food raw material approval bottlenecks. |
| Direct-to-Consumer Platform Launch | Subscription apps in Seoul and Busan capture margin pools from convenience store intermediaries. |
| Plant-Based Substrate Expansion | Oat and coconut fermentation matrices target lactose-intolerant urban populations in metropolitan India. |
Research Methodology
Independent corroboration across fermentation technology suppliers, cold-chain logistics operators, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews engaged brand managers at heritage Japanese houses, category buyers at Australian supermarket chains, supply planners at Indian dairy cooperatives, and platform engineers at South Korean delivery apps. Secondary validation drew from FOSHU certification registries, SAMR new food raw material approvals, MFDS health functional food databases, and customs records of culture strain imports. Bottom-up volume modeling triangulated against top-down category spend estimates.
Comparable historical reference periods anchored the projection horizon to observed cold-chain expansion trajectories and regulatory approval cycle durations. Segmentation dimensions modeled include product substrate, distribution channel, end-user physiology, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to penetration rates across tier-one and tier-two city corridors. Industry-specific inputs incorporated FOSHU certification velocity, strain-approval queue lengths, and refrigerated logistics cost indices.
Strain-approval delays, cold-chain infrastructure buildout pace, and consumer willingness-to-pay for clinical validation are the dominant revision risks. Forecasts reflect assumptions on regulatory pathway efficiency and ambient-distribution technology maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverages Market
Beverages
Packaged Milkshake Market
Beverages
Whole Grain Drinks Market
Beverages
BBQ Charcoal Market
Beverages
Collagen-Infused Water Market
Beverages
Foaming Creamer Market
Beverages
Smoothies Market
Beverages
Bottled Air Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Superfood Infused Beverages Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Water Bottle Market
Beverages
Victorian Jars Market
Beverages
Europe Bottled Water Market
Beverages
Wine Cooler and Chest Freezer Market
Beverages
Citrus Water Market