
 Stack and Nest Containers Market | 2026-2036
Stack and Nest Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Stack and Nest Containers Market Analytics
Direct-to-manufacturer distribution is rewriting procurement patterns for reusable transport packaging. ORBIS Corporation leverages captive resin production to control material costs across its North American molding network. SSI SCHAEFER sustains engineering intensity through dedicated tooling centers in Germany and the Czech Republic. Schoeller Allibert Services anchors European market presence through pooled container management contracts with major grocery retailers.
Stack and nest containers are interlocking material handling vessels designed for vertical stacking when loaded and nested nesting when empty, typically molded from high-density polyethylene or polypropylene with load ratings from 15 to 50 kilograms and standardized footprint dimensions compatible with ISO pallets. Their primary purpose centers on protecting goods through distribution cycles while minimizing empty return freight volume. Plastic dominates type-level value capture due to durability multiples over cardboard and weight advantages against metal, though metal variants retain position in high-temperature and heavy-load industrial storage applications. Logistics application growth outpaces retail packaging as e-commerce fulfillment networks expand hub-and-spoke container pooling systems. Medium-size containers concentrate margin pools by balancing cube efficiency across the broadest cross-section of automotive and food service use cases.
FDA food contact regulations and EU REACH chemical compliance frameworks govern material composition for containers serving food service and pharmaceutical distribution channels, with migration testing protocols adding certification cost layers that favor established suppliers over import entrants. OSHA ergonomic guidelines influence handle design and weight limits, indirectly shaping product development roadmaps for manual handling segments. Stakeholders must monitor how California's SB 54 extended producer responsibility rules and pending EU Packaging and Packaging Waste Regulation amendments reshape total cost of ownership calculations for single-use versus reusable packaging systems.
Market Dynamics
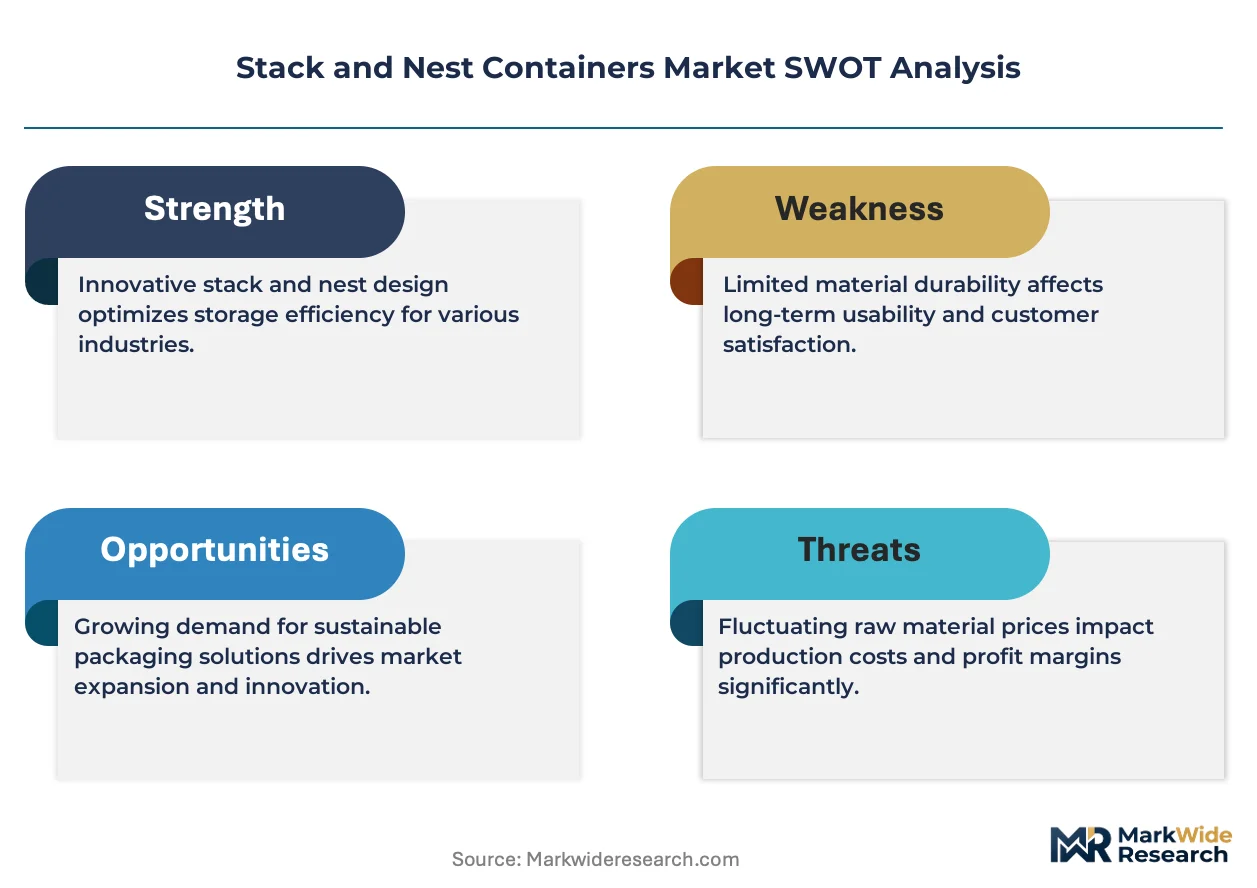
The EU Packaging and Packaging Waste Regulation is forcing automotive parts manufacturers and food distributors to accelerate container reuse programs, compressing payback periods for pooling investments and redrawing supplier selection criteria toward circularity-certified vendors.
Growth Catalysts
- EU REACH chemical compliance:Migration testing protocols for food contact materials favor established molders with in-house certification labs, locking out import entrants and consolidating margin pools among compliant suppliers.
- Automotive closed-loop programs:Tier-1 suppliers in Germany's manufacturing corridor are mandating reusable packaging for component deliveries, creating anchored demand for standardized footprint containers.
- Hub-and-spoke pooling networks:E-commerce fulfillment operators are expanding container circulation systems between regional distribution centers, reducing empty return freight volume by nesting ratios exceeding 70 percent.
Market Restraints
- HDPE resin price volatility:Feedstock cost swings tied to crude oil benchmarks compress molding margins and deter long-term fixed-price contracts with logistics operators.
- Tooling concentration in Germany and Czech Republic:SSI SCHAEFER and Schoeller Allibert Services control critical injection mold fabrication capacity, creating bottleneck risk for new market entrants seeking custom container geometries.
- Cardboard substitution in low-rotation lanes:Single-use corrugated retains cost advantage in irregular shipping patterns where container return logistics prove uneconomical.
Strategic Opportunities
- California SB 54 extended producer responsibility:Plastic packaging waste fees create arbitrage opportunity for reusable container pooling services against single-use alternatives in West Coast distribution corridors.
- Pharmaceutical cold chain convergence:Insulated stack and nest variants combining passive thermal materials with standard footprints address temperature-sensitive biologics distribution gaps.
- Direct-to-manufacturer distribution:Bypassing distributor markups through captive sales forces captures margin previously surrendered to packaging intermediaries in North American automotive supply chains.
Industry Challenges
- FDA food contact certification timelines:Migration testing protocols for new polymer formulations extend product launch cycles by 12-18 months, delaying revenue recognition for material innovations.
- Retrofit integration with legacy warehouse management systems:Container tracking RFID and barcode protocols require middleware development to synchronize with existing inventory platforms at grocery retail distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stack and Nest Containers Market |
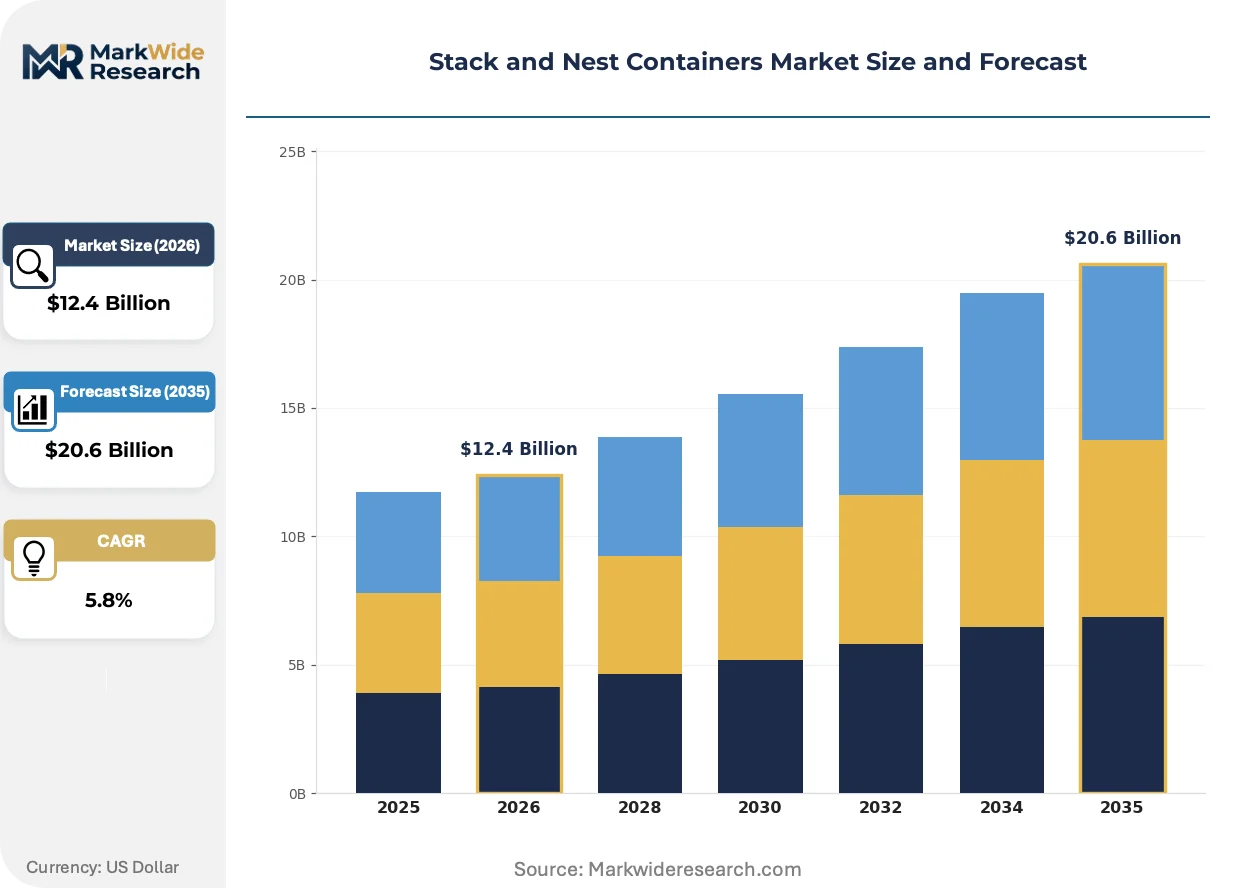
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plastic, Metal, Wood, Cardboard Application: Industrial Storage, Retail Packaging, Food Service, Logistics Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Schoeller Allibert Services, ORBIS Corporation, SSI SCHAEFER, Greif, Polymer Logistics, Monoflo International, Rehrig Pacific Company, Myers Industries, IFCO Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stack and Nest Containers Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape container specifications, with durability standards and traceability requirements now embedded in procurement specifications rather than treated as aftermarket features.
Post-consumer recycled HDPE is migrating from niche sustainability branding to baseline procurement requirements. Automotive OEMs in Stuttgart and Wolfsburg now specify minimum 30 percent recycled content for transport packaging. This shift is compressing virgin resin demand among Tier-2 molders lacking certified recycling supply chains.
REACH SVHC candidate list expansions are restricting certain plasticizers and colorants previously standard in industrial container production. ECHA screening assessments on phthalate alternatives are forcing reformulation of high-impact polypropylene grades used in heavy-load applications. Food service distributors serving EU markets are responding by consolidating supplier bases toward REACH-registered compounders with documented substance dossiers.
Leasing models are displacing outright purchase in capital-constrained logistics operations. Third-party pooling operators now finance container fleets through per-trip fees rather than asset sales, transferring utilization risk from end-users to service providers. This pattern is most visible in German grocery retail, where Schoeller Allibert Services manages circulation for major supermarket chains through multi-year fleet management contracts.
Stack and Nest Containers Market Segmentation
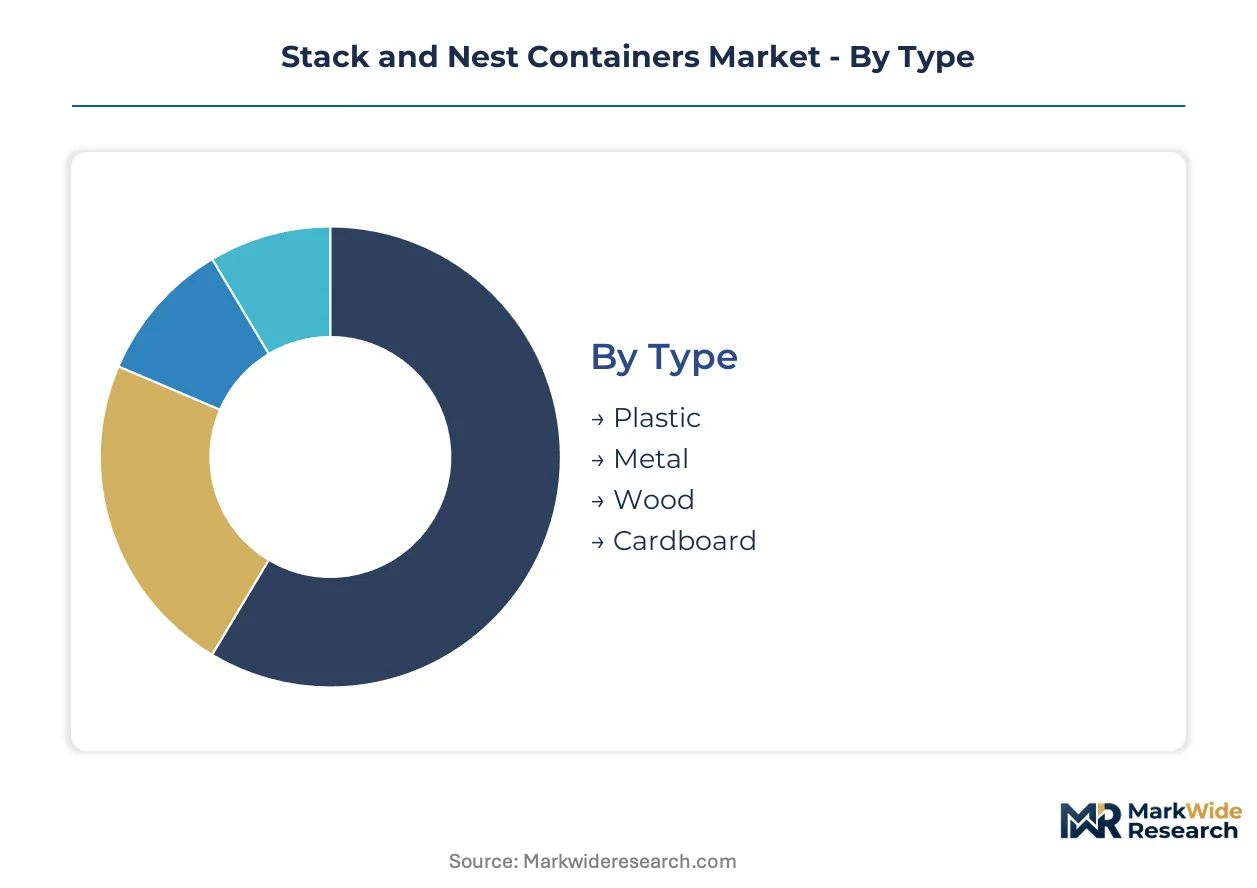
Stack and nest container procurement splits across material durability requirements, operational use cases, and fulfillment network configurations. Understanding these segment boundaries clarifies where pooling economics outperform single-use alternatives and which specifications command premium positioning.
Type:
Mature resin-based solutions coexist with emerging sustainable formulations as compliance frameworks tighten chemical disclosure requirements.
- Plastic:High-density polyethylene and polypropylene variants dominate automotive closed-loop programs through nesting ratios exceeding 70 percent and load ratings between 15-50 kilograms. German OEMs in Stuttgart and Wolfsburg now mandate minimum 30 percent post-consumer recycled content, compressing virgin resin demand among uncertified molders.
- Metal:Steel and aluminum constructions retain fixed position in high-temperature industrial storage and heavy-load applications exceeding 50 kilograms, though weight penalties limit adoption in air freight corridors. REACH SVHC restrictions on certain coatings are forcing reformulation among European fabricators.
- Wood:Pallet-based wooden containers serve niche agricultural bulk transport with lower capital requirements but face hygiene limitations in food service channels regulated by FDA food contact standards.
- Cardboard:Single-use corrugated retains cost advantage in irregular shipping patterns where return logistics prove uneconomical, particularly in low-rotation e-commerce lanes.
Plastic handles the majority of throughput; Metal is the fastest mover on share as thermal performance specifications tighten.
Application:
Cost tier stratification separates capital-intensive pooling networks from depreciated asset deployments in manual handling environments.
- Industrial Storage:Heavy-load variants with reinforced bases and sidewalls serve manufacturing floor staging and work-in-process inventory, with OSHA ergonomic guidelines influencing handle placement and weight limits.
- Retail Packaging:Consumer-facing containers with color-coded identification and tamper-evident features support in-store replenishment cycles for grocery chains, though RFID tracking integration requires middleware investment.
- Food Service:FDA-compliant HDPE grades with migration testing documentation address temperature-controlled distribution for prepared meals and ingredients, locking out import entrants lacking certified compounder relationships.
- Logistics:Hub-and-spoke pooling systems between regional distribution centers are expanding fastest, with third-party operators financing fleets through per-trip fees rather than asset sales.
Logistics is expanding most quickly as e-commerce fulfillment networks scale; Industrial Storage retains the largest installed base.
Size:
Volume concentration patterns reflect cube efficiency optimization across the broadest cross-section of automotive and food service use cases.
- Small:Under 25-liter capacity serves pharmaceutical component kits and electronics subassemblies where part segregation prevents damage.
- Medium:25-60 liter footprints balance manual handling ergonomics with pallet cube utilization, anchoring procurement specifications for Tier-1 automotive suppliers in Germany's manufacturing corridor.
- Large:60-120 liter variants address bulk ingredient handling in food processing plants with forklift-compatible base designs.
- Extra Large:Exceeding 120 liters, these containers serve agricultural harvest collection and retail distribution center inbound receiving, though nesting efficiency degrades above standard ISO pallet footprints.
Medium containers command the densest margin pools; Extra Large is gaining share fastest in agricultural bulk transport.
Distribution Channel:
Customer type fragmentation separates specification-heavy direct relationships from transactional spot purchasing.
- Online Retailers:Digital procurement platforms aggregate small-lot orders from regional molders, compressing lead times for standardized footprints but limiting customization access.
- Wholesale Distributors:Inventory-holding intermediaries serve capital-constrained logistics operators with immediate availability, capturing markup spreads on emergency replenishment.
- Direct Sales:Captive sales forces bypass distributor margins in North American automotive supply chains, with ORBIS Corporation and SSI SCHAEFER deploying dedicated account teams for OEM specifications.
- Specialty Stores:Local material handling dealers provide last-mile service for replacement parts and small fleet expansions in fragmented industrial markets.
Direct Sales is climbing the fastest as procurement centralizes; Wholesale Distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive manufacturing corridor, where standardized container specifications command premium positioning against fragmented North American spot markets shaped by resin cost volatility.
United States
California's SB 54 extended producer responsibility rules impose plastic packaging waste fees that accelerate reusable container pooling adoption across West Coast distribution networks. FDA food contact certification requirements lock out import entrants lacking migration testing documentation. Detroit's automotive supply base anchors demand for medium-footprint containers serving Tier-1 component deliveries.
Germany
Stuttgart and Wolfsburg OEMs mandate minimum 30 percent post-consumer recycled content for transport packaging, compressing virgin resin demand among uncertified molders. EU REACH SVHC candidate list expansions restrict plasticizers and colorants in industrial container production. Bavaria's tooling centers control critical injection mold fabrication capacity for custom container geometries.
China
Dual carbon goals and national plastic restriction policies drive substitution toward durable reusable systems in e-commerce fulfillment networks. GB standards govern food contact materials with testing protocols favoring domestic compounders with certified recycling supply chains. Yangtze River Delta manufacturing clusters generate concentrated demand for small-format containers serving electronics subassemblies.
India
BIS certification requirements for food contact materials create compliance barriers for unregistered import suppliers. PLI scheme incentives for domestic manufacturing attract captive molding investments from logistics operators seeking backward integration. Maharashtra's automotive component corridors in Pune and Chakan anchor procurement specifications for standardized footprint containers.
Japan
METI circular economy roadmaps promote container reuse systems in retail distribution networks. JIS standards for material handling equipment ensure interoperability with automated warehouse systems. Kansai manufacturing clusters in Osaka and Kyoto sustain demand for precision-engineered nesting ratios optimizing empty return freight volume.
Stack and Nest Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin compounding and mold fabrication. The vendor base organizes around three archetypes: captive resin producers controlling material costs, pooling operators financing fleets through per-trip fees, and tooling houses concentrating fabrication capacity in Central Europe. Consolidation pressure intensifies as automotive OEMs consolidate supplier bases toward REACH-registered compounders. Geographic expansion and strategic partnerships dominate competitive moves as players seek certified recycling supply chains.
Among established pooling operators, Schoeller Allibert Services exemplifies the service-based archetype through European fleet management contracts, while ORBIS Corporation represents North American captive production models with backward integration into resin supply. SSI SCHAEFER occupies a position bridging tooling concentration and system integration, anchoring engineering intensity through dedicated fabrication centers.
| Leading Market Players |
|---|
| Schoeller Allibert Services |
| ORBIS Corporation |
| SSI SCHAEFER |
| Greif |
| Polymer Logistics |
| Monoflo International |
| Rehrig Pacific Company |
| Myers Industries |
| IFCO Systems |
| Others |
Value Network & Pricing Analysis
Tooling undercapacity in Bavaria and the Czech Republic concentrates mold fabrication capacity among SSI SCHAEFER and Schoeller Allibert Services, driving premium pricing for custom container geometries while standard footprints face commoditization pressure from Asian import competition.
Pricing Analysis
The customization-premium spread separates configured-to-order containers from standard footprints by 40-60 percent, with automotive OEM specifications commanding the upper tier through REACH-registered compounder requirements and migration testing documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and recycled content thresholds, with virgin HDPE variants facing cost compression from resin price volatility tied to crude benchmarks. Price erosion runs through standard footprints as online retail platforms aggregate spot demand, while food service distributors show lowest price sensitivity due to FDA compliance lock-in. Contract-based long-term offtake dominates pooling operator relationships, insulating fleet managers from spot volatility.
Supply Chain Analysis
Contract manufacturing concentration rests with SSI SCHAEFER's tooling centers in Germany and the Czech Republic, alongside ORBIS Corporation's captive molding network across North American facilities. Geographic supply concentrates in Germany, China, and the United States, with HDPE resin compounding anchored in Gulf Coast petrochemical corridors and Yangtze River Delta processing clusters. Raw material dependencies draw from crude oil derivatives, post-consumer recycled feedstock, and REACH-compliant colorant formulations. Single-source vulnerability sits with Bavaria's injection mold fabrication capacity for custom geometries. Distribution runs through direct sales forces for automotive OEMs, wholesale distributors for emergency replenishment, and third-party pooling operators financing per-trip circulation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity justified by container pooling and fleet management fees expanding faster than hardware sales as logistics operators transfer utilization risk to third-party operators.
For Market Incumbents: Insulate margin pools by deepening captive resin production and certifying recycling supply chains ahead of EU Packaging and Packaging Waste Regulation tightening. Prioritize REACH-registered compounder status to lock out import entrants lacking migration testing infrastructure. Defend against cardboard substitution in low-rotation lanes through per-trip pricing models that neutralize capital expenditure barriers for capital-constrained operators. For New Entrants and Emerging Players: Build out pharmaceutical cold chain convergence as the most penetrable white-space, combining passive thermal materials with standard footprints for temperature-sensitive biologics distribution. Target West Coast US distribution corridors where California SB 54 extended producer responsibility fees create arbitrage opportunity against single-use alternatives. Pursue direct-to-manufacturer distribution bypassing wholesale markups through dedicated account teams for mid-tier automotive suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pooling operations as per-trip financing models displace asset-heavy fleet ownership, compressing balance sheet requirements for scaled operators. Long-term viability favors platform integrators with certified recycling supply chains and multi-year grocery retail contracts over component molders exposed to resin volatility. Monitor EU REACH SVHC candidate list expansions as the inflection signal—substance restrictions will consolidate supplier bases toward registered compounders with documented dossiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | ORBIS Corporation's captive HDPE production insulates margin pools from crude price volatility. |
| REACH Certification Investment | Registered compounder status locks out Asian import entrants lacking migration testing infrastructure. |
| Per-Trip Pooling Model Expansion | Schoeller Allibert Services transfers utilization risk from grocery retailers to fleet operators. |
| Pharmaceutical Cold Chain Development | Insulated stack and nest variants address temperature-sensitive biologics distribution gaps. |
| Direct Sales Force Deployment | Captive account teams capture margin previously surrendered to packaging intermediaries. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including logistics procurement directors at Tier-1 automotive suppliers, pooling fleet managers at grocery retail chains, FDA compliance officers at food service distributors, and resin compounding technical leads. Secondary validation drew from EU ECHA substance dossiers, FDA food contact guidance documents, SEC 10-K filings of listed packaging manufacturers, and customs trade data for HDPE container imports. Bottom-up container shipment estimates triangulated against top-down automotive production and e-commerce fulfillment network expansion metrics.
Calibration anchored volume projections to automotive OEM container specification changes and e-commerce hub-and-spoke network buildouts across the analysis window. Segmentation dimensions modeled include material type, application use case, container size tier, and distribution channel structure. CAGRs derived from logistic curve adoption patterns for reusable packaging systems, cross-referenced with regulatory compliance cost trajectories and resin price elasticity assumptions. Industry-specific inputs incorporated EU Packaging and Packaging Waste Regulation amendment timelines and California SB 54 fee implementation schedules.
Practitioners should monitor EU REACH SVHC candidate list expansions and post-consumer recycled content mandate thresholds for early signals of supplier base consolidation. Forecasts reflect assumptions regarding regulatory enforcement consistency and resin price volatility ranges. Quarterly review of automotive OEM specification changes and pooling operator contract renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Clear Hinged Container Market
Containers
Tottle Containers Market
Containers
Container Stacking Machine Market
Containers
Spout Containers Market
Containers
Vials Market
Containers
PUR Containers Packaging Market
Containers
Essential Oil Containers Market
Containers
Disposable Lids Market
Containers
Takeaway Containers Market
Containers
Canisters Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
APAC Container Technology Market
Containers
Algeria Container Glass Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Chest-Style Insulated Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market