
 Lever Lid Cans Market | 2026-2036
Lever Lid Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Lever Lid Cans Market Foresight
REACH is hardening the cost-of-entry calculus for lever lid can manufacturers serving European food production and chemical packaging buyers. Pirlo GmbH leverages its German manufacturing footprint to sustain compliance with evolving ECHA substance restrictions. Kian Joo Group anchors volume production across Southeast Asian markets with integrated tinplate sourcing. Ball Corporation differentiates through aluminum alloy technology leadership and beverage-to-industrial cross-application expertise.
A lever lid can is a cylindrical metal container featuring a mechanically retained lid that pivots on a fixed hinge or lever mechanism, typically fabricated from tinplate, aluminum, or steel with internal epoxy-phenolic coatings for corrosion resistance. The design permits repeated opening and resealing without tool deformation, serving primary commercial purposes in food preservation, chemical storage, and automotive fluid containment. Tinplate variants dominate food and beverages applications due to solderability and printability, while aluminum grades capture personal care and premium retail segments where weight reduction and recyclability command margin premiums. Steel constructions retain structural share in chemicals and automotive end uses where impact resistance and stack-load capacity outweigh material cost differentials.
FDA food contact substance notifications and EPA chemical container standards govern North American product specifications, while EU F-Gas Regulation and MDR indirect pressures affect coating chemistry selections for pharmaceutical-adjacent personal care applications. BIS certification requirements in India and GB standards in China create divergent testing protocols that fragment qualification timelines for multinational suppliers. Stakeholders must monitor regulatory harmonization progress between ISO container standards and emerging national extended producer responsibility frameworks to anticipate retooling investments and geographic qualification sequencing.
Market Dynamics
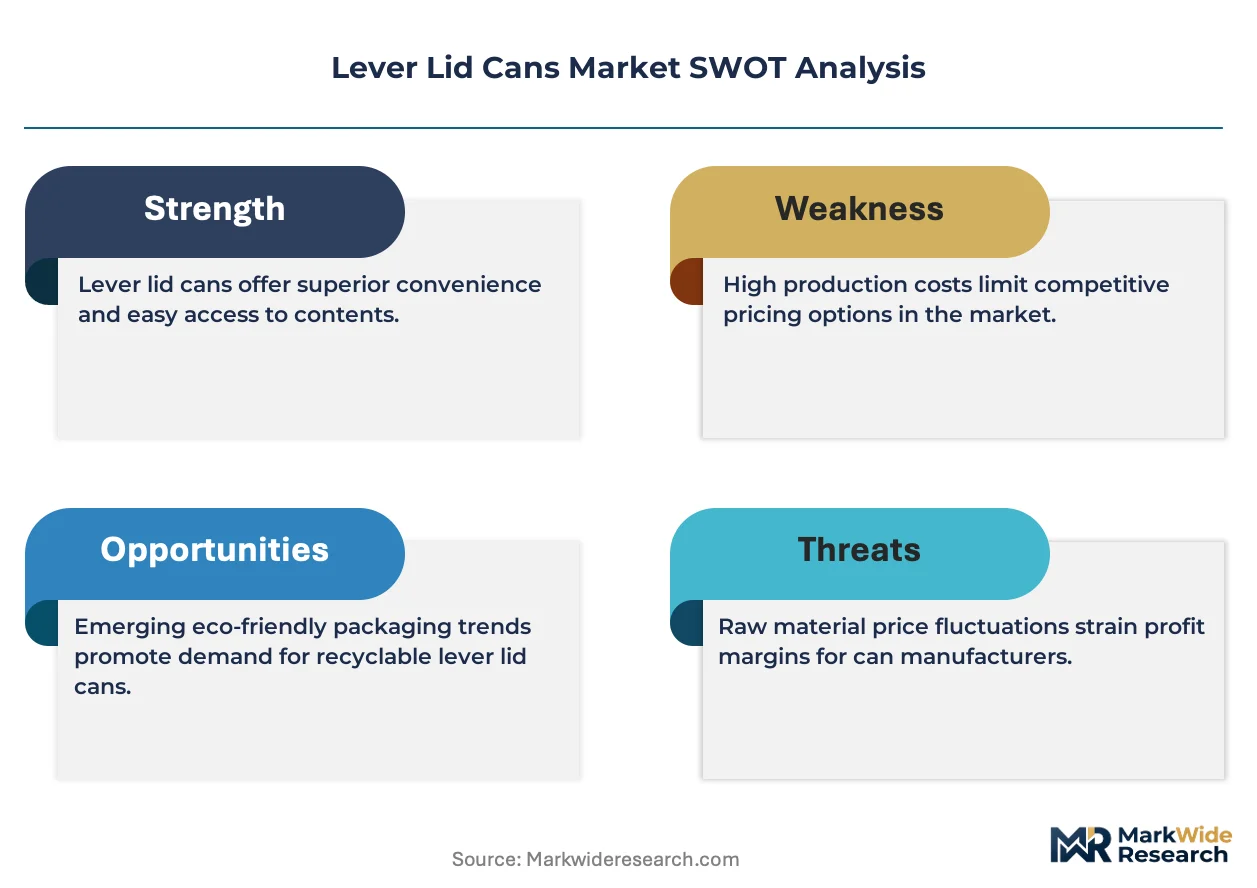
REACH substance restrictions are hardening material specifications across European food production and chemical packaging applications, forcing retooling investments and geographic qualification sequencing for lever lid can manufacturers.
Growth Catalysts
- REACH compliance differentiation:Food producers in Germany and France are consolidating procurement around suppliers with verified ECHA substance documentation, creating pull for compliant tinplate and coating systems.
- Aluminum alloy substitution:Personal care brands are specifying aluminum lever lid cans to meet EU Green Deal recyclability mandates and reduce transport emissions.
- Localization incentives:Manufacturers are relocating production to the United States and China to shorten supply chains for automotive fluid and chemical storage end uses.
Market Restraints
- Tinplate cost volatility:Raw material exposure to steel and tin commodity swings compresses margin stability for food-grade can producers.
- Coating chemistry limitations:BPA-free epoxy-phenolic alternatives face performance gaps in high-acid food contact applications.
- Substitution by flexible pouches:Retort pouch technology captures share in premium pet food and ready-meal segments where resealability is less critical.
Strategic Opportunities
- Indian FSSAI expansion:Processed food sector growth under BIS certification harmonization creates white space for tinplate lever lid formats in spice and ghee packaging.
- Refill retail channel emergence:Zero-waste stores in Germany and the Netherlands are piloting bulk dispensing systems using durable lever lid can returns.
- Dual carbon alignment in China:GB standards evolution and MEE enforcement are accelerating aluminum can adoption for carbon-conscious personal care brands.
Industry Challenges
- Coating formulation expertise gap:Food contact substance notification requirements under FDA and EFSA demand specialized toxicology and migration testing capabilities that smaller manufacturers lack.
- Multi-jurisdiction certification timelines:Sequential BIS, GB, and ISO qualification protocols delay product launches by 18-24 months for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lever Lid Cans Market |
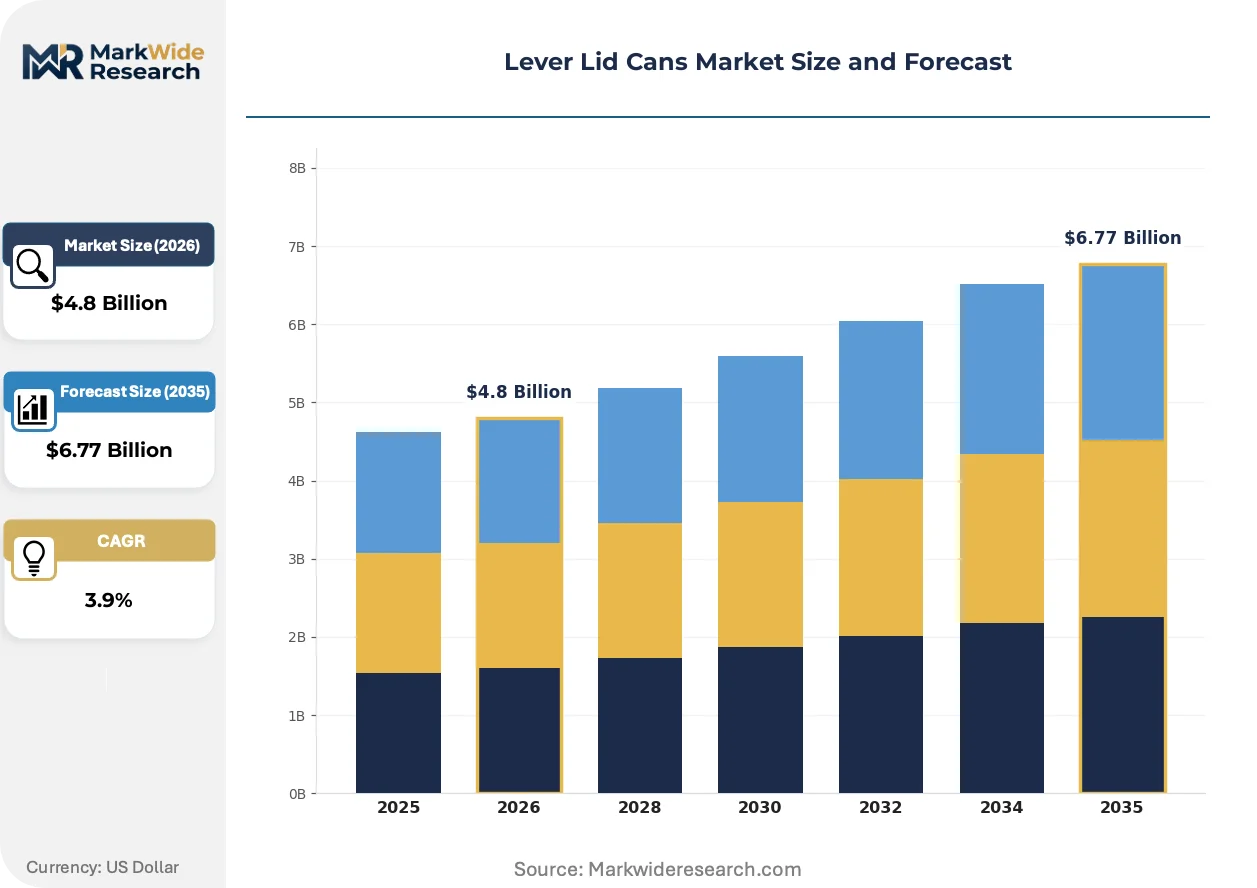
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aluminum, Steel, Plastic, Tinplate Application: Food & Beverages, Chemicals, Personal Care, Automotive End User: Retail, Manufacturing, Food Production, Distribution Size: Standard, Mini, Large, Custom |
| Companies Covered | Pirlo GmbH, Kian Joo Group, RLM Packaging, Quitmann O'Neill Packaging, Central Tin Containers, HUBER Packaging Group GmbH, Ball Corporation, P. Wilkinson Containers, Taylor Davis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lever Lid Cans Market Shifts & Advancements
Digital printing and smart packaging integration are reshaping how lever lid cans communicate traceability and freshness to end users, while coating chemistry advances address regulatory pressure on legacy substances.
Water-based digital inkjet decoration is decentralizing brand packaging workflows by enabling short-run customization without plate costs. Regional food producers in Italy and Spain are adopting this for seasonal and private-label SKUs. The technology is decentralizing volume concentration away from large-format offset printing houses toward in-house or local contract decoration facilities.
EU F-Gas Regulation phase-down schedules are forcing reformulation of polyurethane foam blowing agents used in insulated can jacketing for temperature-sensitive chemicals. Coatings suppliers are accelerating HFO and natural refrigerant alternatives. Pharmaceutical-adjacent personal care applications face the steepest compliance ramps, with German and French buyers now specifying F-gas-free supply chain documentation.
Direct-to-manufacturer procurement platforms are compressing distributor margins in industrial chemical packaging. Automotive fluid blenders in the United States and China are negotiating lever lid can supply through digital marketplaces that bypass traditional regional distributors. The shift is most visible in bulk lubricant and antifreeze segments where specification standardization reduces technical selling requirements.
Lever Lid Cans Market Segmentation
Lever lid can procurement decisions hinge on material compatibility with contents, regulatory compliance burden, and reseal frequency requirements. Buyers across food production and chemical storage segments prioritize coating integrity and hinge durability over unit cost when specifying formats.
Type:
Material selection drives total cost of ownership calculations for food producers and chemical blenders.
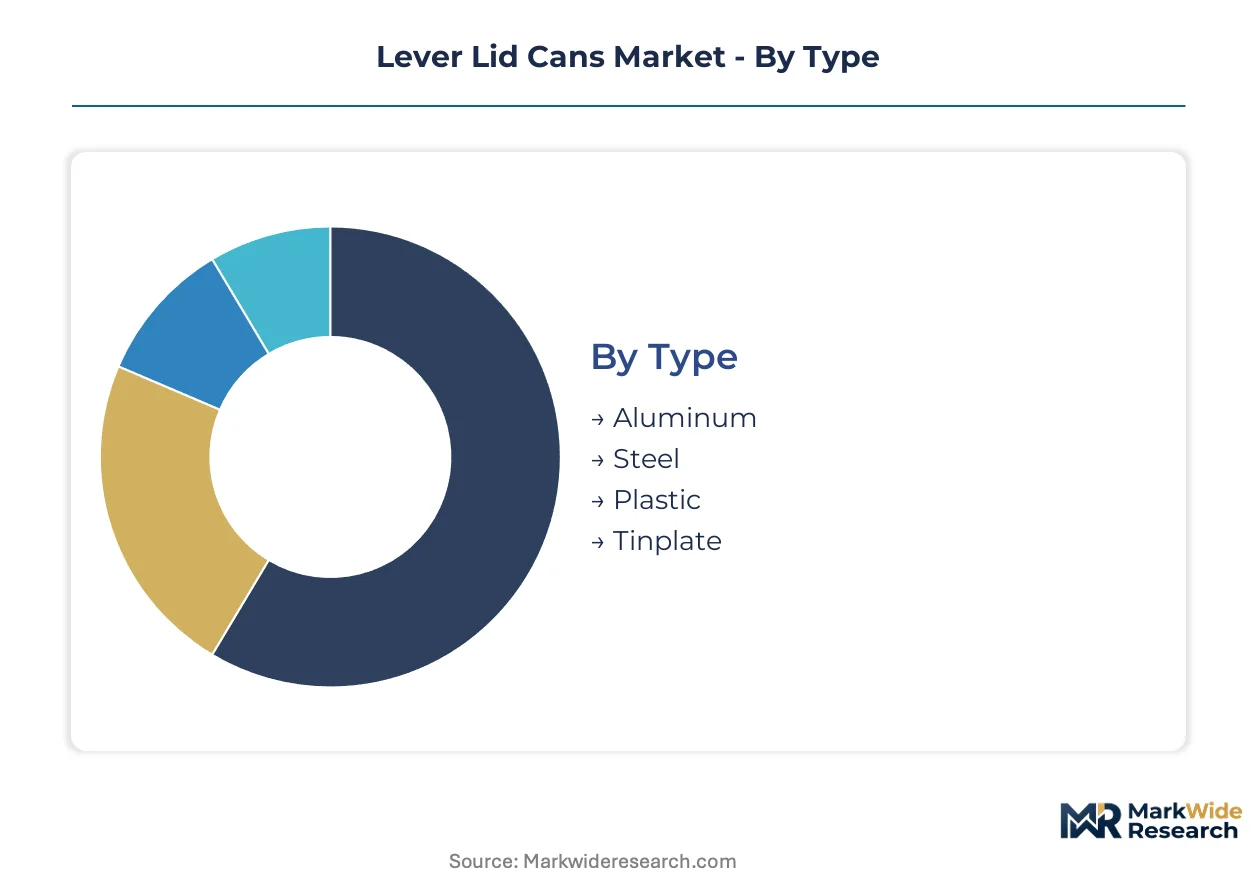
- Tinplate:Solderable steel substrate with tin coating enables high-resolution lithographic printing and corrosion resistance in acidic food contact. German and French food producers specify tinplate for premium preserves and specialty condiments where shelf appeal and EFSA coating compliance are non-negotiable.
- Aluminum:Lightweight alloy construction reduces transport emissions and satisfies EU Green Deal recyclability mandates. Personal care brands in the Netherlands and Germany specify aluminum lever lid cans for carbon-conscious positioning in refill retail channels.
- Steel:High-impact structural grade retains stack-load capacity for chemical and automotive fluid storage where mechanical stress exceeds material cost sensitivity.
- Plastic:Polymer variants serve cost-constrained applications where metal corrosion resistance is unnecessary and single-use disposal is acceptable.
Volume sits with tinplate; growth tilts toward aluminum.
Application:
End-use chemistry and regulatory exposure determine coating specification intensity and certification depth.
- Food & Beverages:Acidic and high-fat contents demand epoxy-phenolic internal coatings with FDA and EFSA substance notifications. Italian and Spanish regional producers adopt digital-printed tinplate formats for seasonal SKU flexibility.
- Chemicals:Solvent compatibility and UN transport certification requirements favor steel constructions with specialized barrier coatings. Automotive fluid blenders in the United States negotiate direct procurement to bypass distributor margins.
- Personal Care:EU F-Gas Regulation compliance and MDR-adjacent documentation pressure favor aluminum formats with F-gas-free supply chain verification for German and French buyers.
- Automotive:Impact resistance and stack-load specifications prioritize steel lever lid cans for bulk lubricant and antifreeze containment in United States and Chinese manufacturing clusters.
Food & Beverages commands installed base; Personal Care climbs the fastest on sustainability specification.
End User:
Procurement scale and technical selling requirements fragment channel economics.
- Food Production:Industrial-scale buyers consolidate procurement around REACH-verified suppliers with documented ECHA substance compliance, compressing vendor lists in Germany and France.
- Retail:Zero-waste store formats in Germany and the Netherlands pilot durable lever lid can return systems for bulk spice and ghee dispensing.
- Manufacturing:Chemical and automotive fluid blenders leverage digital marketplaces to compress distributor margins through specification-standardized direct sourcing.
- Distribution:Traditional channel intermediaries face margin pressure as procurement platforms disintermediate regional stocking roles.
Food Production anchors volume concentration; Retail gains share fastest on circular economy pilots.
Size:
Format dimensions align with handling automation, shelf space constraints, and consumption velocity patterns.
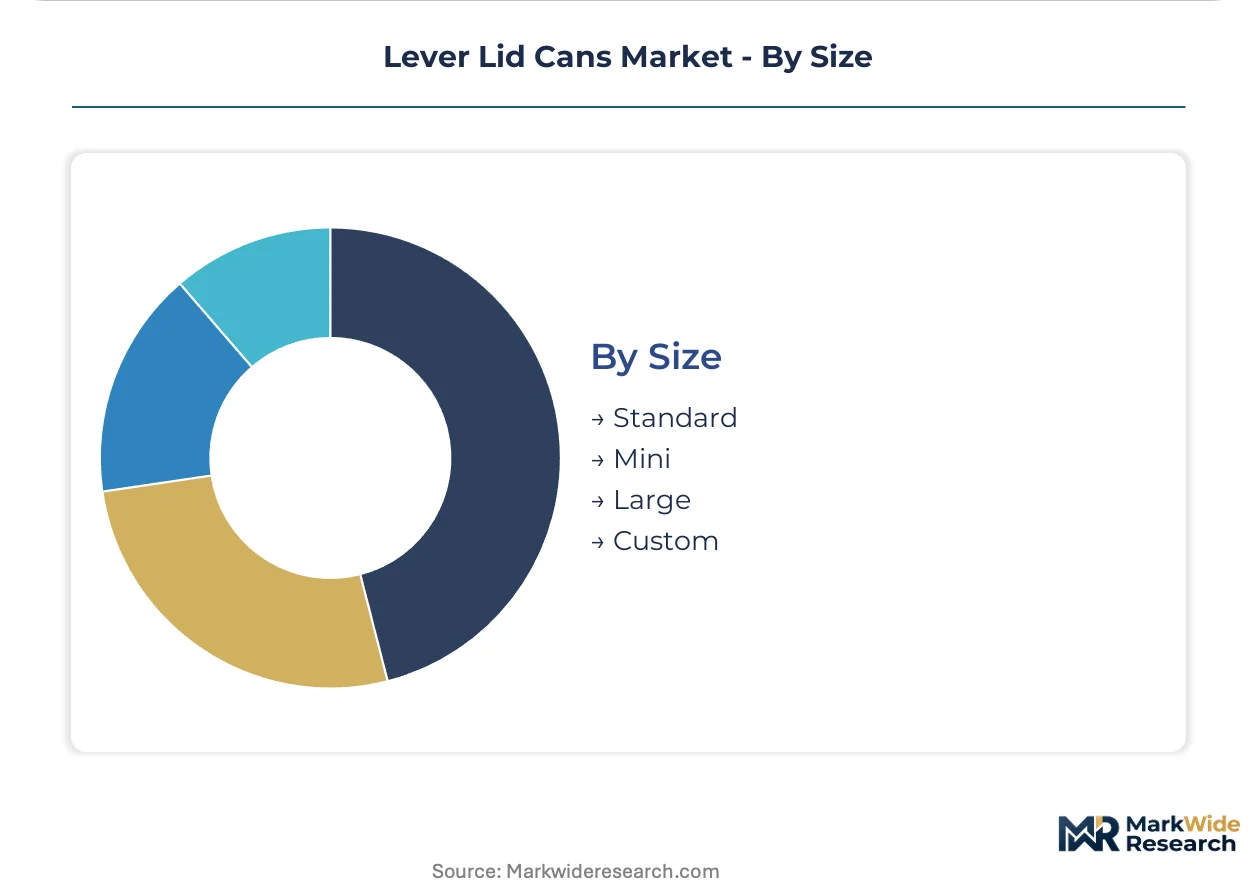
- Standard:Mid-capacity formats balance automation compatibility across European and North American filling lines with household consumption rates for preserves and condiments.
- Mini:Single-serve and sample formats capture travel retail and hospitality segments where portion control outweighs per-unit cost premiums.
- Large:Industrial and food service bulk formats optimize logistics for high-velocity manufacturing and institutional procurement.
- Custom:Bespoke dimensions serve specialty chemical and pharmaceutical-adjacent applications where standard formats fail compatibility requirements.
Standard formats dominate throughput economics; Custom specifications expand most quickly in pharmaceutical-adjacent personal care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Guangdong Province and the Yangtze River Delta anchor Asia-Pacific production concentration for lever lid can exports. German industrial clusters leverage REACH compliance infrastructure to capture premium food packaging procurement. United States automotive fluid demand drives regional capacity localization.
Germany
Premium preserves and specialty condiment producers in Baden-Württemberg specify tinplate formats with EFSA-compliant epoxy-phenolic coatings. REACH substance restrictions under ECHA enforcement harden material documentation requirements for chemical packaging applications. The Stuttgart industrial corridor hosts coating formulation specialists serving pharmaceutical-adjacent personal care buyers.
China
Personal care brands in Shanghai and Guangzhou specify aluminum lever lid cans to satisfy dual carbon goals under MEE enforcement. GB standards evolution accelerates domestic qualification timelines for food-grade tinplate imports. The Pearl River Delta concentrates digital printing integration for seasonal SKU flexibility in condiment exports.
United States
Automotive fluid blenders in Michigan and Ohio negotiate direct procurement through digital marketplaces for bulk lubricant containment. EPA chemical container standards govern UN transport certification for steel lever lid formats. The Great Lakes manufacturing belt sustains stack-load capacity specifications for antifreeze distribution.
India
Processed food sector expansion under FSSAI harmonization creates demand for spice and ghee packaging in Maharashtra and Gujarat. BIS certification requirements fragment qualification timelines for multinational tinplate suppliers. The Mumbai-Pune industrial corridor pilots durable can return systems for zero-waste retail channels.
Netherlands
Refill retail formats in Amsterdam and Rotterdam pilot aluminum lever lid can returns for bulk dispensing applications. EU Green Deal recyclability mandates drive specification shifts away from tinplate in carbon-conscious personal care segments. The Randstad logistics hub enables circular economy pilot scaling across Benelux markets.
Lever Lid Cans Market Competitive Landscape
German producers anchor one tier; Southeast Asian specialists hold volume manufacturing positions. The vendor base spans integrated metal packaging conglomerates and regional fabrication specialists serving niche chemical and food preservation applications. Three archetypes dominate: REACH-verified European suppliers, aluminum technology leaders, and integrated tinplate sourcers. Competitive moves concentrate on geographic qualification sequencing and coating chemistry partnerships with regulatory-compliant resin formulators.
Within the European compliance tier, Pirlo GmbH and HUBER Packaging Group GmbH exemplify German manufacturing footprint strategies. Kian Joo Group represents integrated tinplate sourcing across Southeast Asian markets. Ball Corporation occupies a position at the aluminum technology vector. These three anchors illustrate how geographic specialization and material technology differentiation structure competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| Pirlo GmbH |
| Kian Joo Group |
| RLM Packaging |
| Quitmann O'Neill Packaging |
| Central Tin Containers |
| HUBER Packaging Group GmbH |
| Ball Corporation |
| P. Wilkinson Containers |
| Taylor Davis |
| Others |
Supply & Pricing Matrix
Digital printing decentralization is compressing decoration economics while fragmenting volume concentration across regional European and North American facilities, simultaneously eroding large-format offset house pricing power and enabling shorter-run premium positioning for compliant tinplate suppliers.
Pricing Analysis
Lead-time-driven pricing stratification separates premium-compliant tinplate formats with documented ECHA substance verification from economy-grade spot inventory carrying coating chemistry gaps. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and coating integrity specifications. Cost compression in economy tinplate is intensifying because raw material exposure to steel and tin commodity swings compresses margin stability for undifferentiated producers. Food production buyers in Germany and France demonstrate lowest price sensitivity where REACH documentation is non-negotiable; retail channel distributors face highest sensitivity as procurement platforms disintermediate regional stocking roles.
Supply Chain Analysis
Tinplate supply rests on integrated steel-tin sourcing from China, Germany, and South Korea with coating resin dependencies from specialized epoxy-phenolic formulators in the United States and Europe. Raw material feeds draw from steel substrate mills, tin electrolytic deposition facilities, and barrier coating chemical specialists. Single-source vulnerability concentrates in REACH-compliant resin supply where ECHA substance restriction evolution forces reformulation cycles. Distribution runs through direct-to-manufacturer procurement platforms for automotive fluid blenders and chemical storage buyers, while food-grade formats retain traditional distributor networks for technical selling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance hardening functions as a structural barrier-to-entry moat, concentrating procurement power among ECHA-verified European suppliers while elevating retooling costs for non-compliant manufacturers attempting geographic qualification sequencing.
For Market Incumbents: Lock in coating formulation partnerships with regulatory-compliant resin suppliers to sustain EFSA and FDA food contact substance notification advantages against emerging aluminum substitution threats. Anchor capacity positions in Germany and China to capture localization incentives for automotive fluid and chemical storage end uses while defending margin position through documented ECHA substance compliance that smaller manufacturers cannot replicate. For New Entrants and Emerging Players: The price-point gap between premium REACH-verified tinplate and economy-grade uncoated steel creates white-space entry at mid-tier certification levels for Indian FSSAI expansion and Chinese GB standards harmonization. Target processed food sector growth in Maharashtra and Gujarat where BIS certification fragments multinational timelines. Pilot durable can return systems for zero-waste retail channels in the Netherlands as a differentiated circular economy go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap coating specialists with documented FDA and EFSA toxicology capabilities rather than commodity fabrication assets. Long-term viability favors vertically integrated tinplate sourcers with captive steel-tin supply and regional qualification depth across three or more jurisdictions. Watch ECHA substance restriction expansion velocity as the inflection indicator for accelerated consolidation among undercapitalized European specialists lacking migration testing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Sourcing | Captive steel-tin supply secures margin stability against commodity volatility for food-grade producers. |
| Coating Chemistry Partnership with Resin Formulators | EFSA-compliant epoxy-phenolic access creates REACH differentiation moats in premium preserves segments. |
| Digital Printing Capability Expansion | In-house decoration enables short-run SKU flexibility for Italian and Spanish seasonal condiment producers. |
| Direct Procurement Platform Integration | Bypassing distributor margins captures automotive fluid blender volume in Michigan and Ohio clusters. |
| Zero-Waste Retail Channel Pilot Programs | Durable can return systems align with EU Green Deal mandates in Amsterdam and Rotterdam markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with coating formulation specialists, food production procurement directors, chemical storage logistics managers, and automotive fluid blender supply chain leads validated demand-side assumptions. ECHA substance restriction databases, FDA food contact substance notifications, BIS certification registries, and GB standards documentation supplied regulatory boundary conditions. Bottom-up volume triangulation across material type, application segment, and end-user channel converged with top-down macroeconomic anchoring.
Segment-level modeling tracked tinplate, aluminum, steel, and plastic material types across food and beverages, chemicals, personal care, and automotive applications with end-user granularity spanning food production, retail, manufacturing, and distribution channels. CAGRs were derived from regression-based projection incorporating REACH compliance cost trajectories, aluminum alloy substitution elasticities, and localization incentive intensity. Coating chemistry reformulation timelines and digital printing adoption curves supplied industry-specific forecast inputs across the projection horizon.
Inputs from ECHA enforcement bulletins and FDA notification databases were available through the study window; gaps in real-time BIS qualification completion rates introduce uncertainty bands for Indian market penetration assumptions. Forecasts reflect documented regulatory trajectories and primary fieldwork synthesis; coating performance gaps in BPA-free alternatives and retort pouch substitution velocity represent specific revision triggers. A small set of named triggers—ECHA substance restriction expansion, MEE dual carbon enforcement intensity, and FSSAI harmonization completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Americas Container Technology Market
Containers
Stackable Plastic Trays Market
Containers
Container Market
Containers
PVC Container Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Wooden Barrels Market
Containers
Chest-Style Insulated Containers Market
Containers
Vacuum Formed Tray Market
Containers
Corrugated Open-Head Drums Market
Containers
PUR Containers Packaging Market
Containers
Metal Crates Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Laminated Bulk Bins Market
Containers
Container Liner Market
Containers
Jug Shipper Market