
 Electrical Conduit Pipe Market | 2026-2036
Electrical Conduit Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Conduit Pipe Market Foresight
High-density polyethylene is rebalancing cost-performance tradeoffs across underground infrastructure applications. Atkore leverages integrated resin-to-conduit manufacturing to control input costs across volatile polymer markets. Wheatland Tube anchors domestic steel conduit supply through electric resistance welding capacity in the Midwest. Electri-Flex specializes in liquid-tight flexible metal systems for industrial machinery and robotics installations.
Electrical conduit pipe comprises rigid or flexible tubing systems fabricated from PVC, steel, aluminum, or HDPE, engineered to protect and route electrical wiring in buildings, infrastructure, and industrial facilities. Wall thickness, corrosion resistance, and flame-retardant properties determine suitability for exposed, concealed, or buried installations per NEC and UL standards. Rigid PVC dominates residential and light commercial segments due to light weight and chemical inertness, while flexible steel captures industrial maintenance and retrofit applications where vibration tolerance and tight bending radius prove essential. EMT maintains strong position in commercial construction where cost-efficient electromagnetic shielding meets code requirements without threaded coupling labor.
FCC infrastructure rules indirectly shape conduit demand through broadband deployment mandates requiring underground utility coordination. EPA stormwater regulations and state-level PFAS restrictions are accelerating HDPE substitution for legacy PVC in environmentally sensitive installations. OSHA electrical safety standards enforce conduit integrity in hazardous location classifications across manufacturing plants. Stakeholders must weigh resin price volatility against multi-decade infrastructure replacement cycles when committing to material platforms and manufacturing footprints.
Market Dynamics
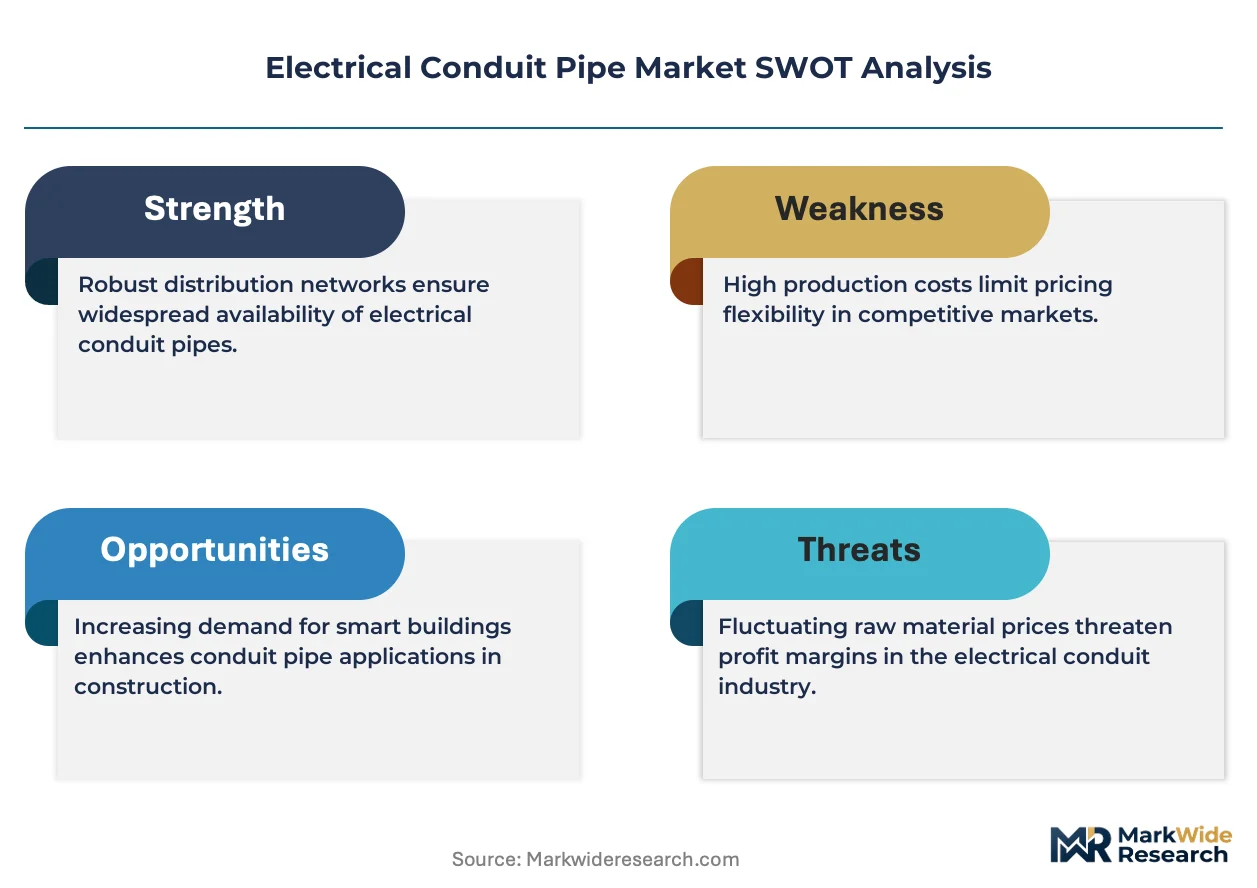
HDPE conduit is absorbing underground infrastructure share as resin price volatility and environmental compliance reshape material selection criteria across utility-scale projects.
Growth Catalysts
- NFPA 70 NEC updates:Stricter fire-resistance ratings for commercial installations in the United States are forcing retrofit cycles and new-build specification upgrades across retail, healthcare, and education verticals.
- Data center construction:Hyperscale facility builds require extensive underground conduit networks for redundant power distribution, with liquid-tight flexible metal systems capturing critical path routing in server hall environments.
- Gulf Coast corridor:Petrochemical and LNG facility expansions across Texas and Louisiana are driving demand for corrosion-resistant HDPE and coated steel conduit in hazardous location classifications.
Market Restraints
- Resin input volatility:Polyethylene and PVC feedstock prices fluctuate with crude oil and natural gas liquids, compressing margin predictability for integrated and non-integrated manufacturers alike.
- Steel supply concentration:Electric resistance welding capacity clusters in the US Midwest, creating geographic vulnerability to logistics disruptions and regional labor actions.
- Technical substitution ceiling:Rigid PVC cannot achieve the bending radius or vibration tolerance required for industrial robotics installations, capping its addressable market in automated manufacturing environments.
Strategic Opportunities
- Utility-scale solar:Photovoltaic farm construction across the southwestern United States requires miles of underground collector circuits, with HDPE conduit specified for UV resistance and trenching efficiency.
- FCC broadband mandates:Underground utility coordination rules for fiber deployment create bundled procurement opportunities for conduit-electrical-cable packages in municipal infrastructure.
- EPA stormwater alignment:State-level PFAS restrictions and green infrastructure incentives are accelerating HDPE specification for environmentally sensitive installations near wetlands and watersheds.
Industry Challenges
- Skilled electrician scarcity:Threaded rigid metal conduit installation requires certified trades labor that is aging out of the workforce faster than apprenticeship programs replenish supply.
- Multi-certification burden:UL listing, NEC compliance, and state-level electrical inspector approvals create timeline friction for new product introductions and material platform switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Conduit Pipe Market |
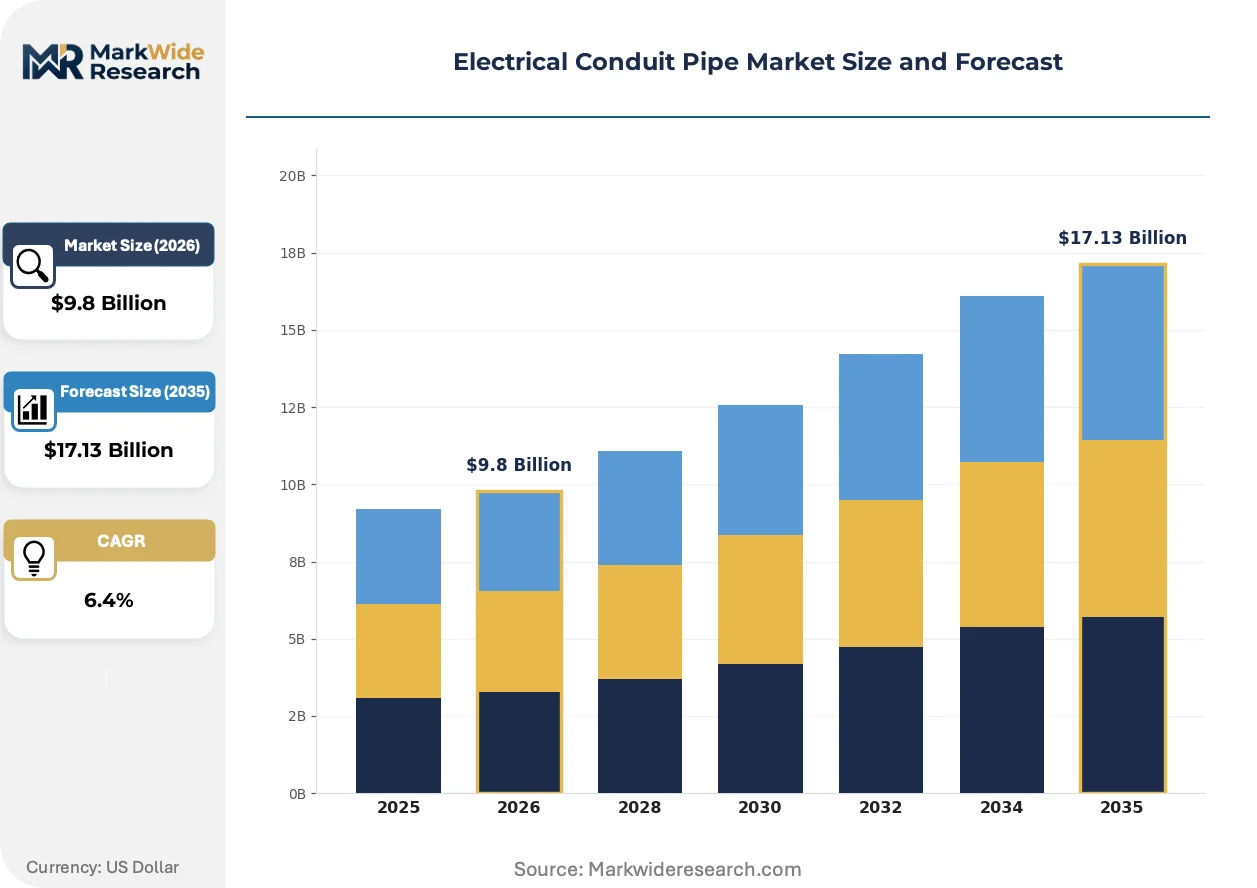
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, EMT, IMC, Flexible Steel Installation Method: Concealed, Exposed, Buried, Surface-mounted End User: Residential, Commercial, Industrial, Infrastructure Size: 1 inch, 2 inch, 3 inch, 4 inch |
| Companies Covered | Hubbell, Electri-Flex, Atkore, Prime Conduit, National Pipe & Plastics, Cantex, Wheatland Tube, Nucor Tubular Products, Aliaxis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Conduit Pipe Market Shifts & Advancements
Material science advances and regulatory tightening are converging to redefine performance benchmarks across rigid and flexible conduit categories.
Co-extruded HDPE conduit with integrated conductive layers is absorbing market share in cathodic protection applications. Oil and gas pipeline operators specify these systems for impressed current anode bed installations where corrosion monitoring requires electrical continuity. The technology compresses installation labor by eliminating separate tracer wire pulling.
REACH restrictions on halogenated flame retardants are forcing PVC compound reformulation across European supply chains. Manufacturers are shifting to metal hydroxide and phosphorus-based alternatives that maintain UL 94 V-0 ratings while satisfying ECHA substance authorization requirements. Commercial construction specifications in Germany and France now prioritize these reformulated compounds for public building projects.
Direct-to-contractor digital procurement platforms are fragmenting traditional distribution channels. Electrical contractors in the United States increasingly source EMT and fittings through specialized e-commerce portals that bypass regional distributor markups. This behavior concentrates in residential and light commercial segments where specification authority rests with individual electricians rather than engineering firms.
Electrical Conduit Pipe Market Segmentation
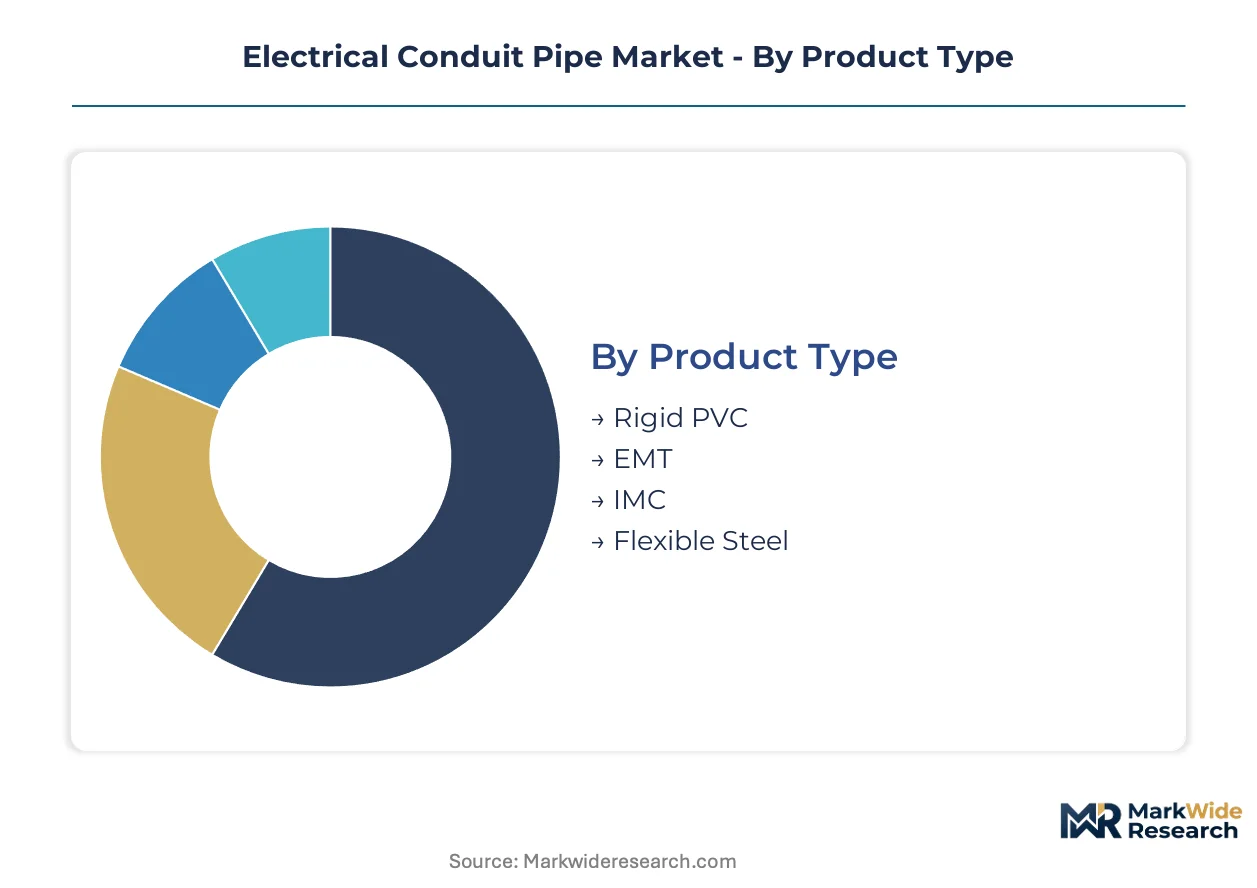
Material selection and installation environment dictate specification logic across the electrical conduit pipe market. Contractors weigh code compliance against labor efficiency and lifecycle durability when matching product categories to project requirements.
Product Type:
Cost-performance positioning separates buyers seeking economy from those prioritizing mechanical resilience or corrosion immunity.
- Rigid PVC:Thermoplastic construction delivers chemical inertness and light weight for residential and light commercial wiring protection. Demand concentrates in single-family housing across the southeastern United States where termite resistance and moisture immunity override metal alternatives.
- EMT:Thin-wall steel tubing provides cost-efficient electromagnetic shielding without threaded coupling labor. Commercial construction in Texas and California specifies EMT for retail and office builds where NEC fire-resistance requirements meet budget constraints.
- IMC:Intermediate metal conduit offers heavier wall thickness than EMT for enhanced physical protection in industrial environments.
- Flexible Steel:Spiral-wound construction accommodates tight bending radius and vibration tolerance for machinery and robotics installations.
Rigid PVC leads volumes today; flexible steel is gaining share fastest.
Installation Method:
Project phase and accessibility constraints determine whether conduit runs through finished spaces or remains serviceable.
- Concealed:Embedded within walls, ceilings, or concrete slabs for aesthetic finish in occupied buildings. Residential developers in Florida and Arizona specify concealed PVC runs to preserve interior design integrity while meeting NEC outlet spacing mandates.
- Exposed:Surface-visible routing for industrial facilities and retrofit applications where future access trumps appearance. Manufacturing plants across Ohio and Michigan deploy exposed EMT for maintenance accessibility in production floor electrical distribution.
- Buried:Direct earth placement for underground feeder circuits and utility interconnections. HDPE dominates this method for solar farm collector circuits in Nevada and Arizona where UV resistance and trenching efficiency reduce installed cost.
- Surface-mounted:External attachment to existing structures for expansion and temporary power in commercial renovation.
Concealed installation commands the largest project count; buried methods are climbing the fastest.
End User:
Specification authority and procurement scale vary dramatically across customer types.
- Residential:Single-family and multifamily construction driven by housing starts and electrical code adoption. Builders in the US Sun Belt specify PVC conduit for new home electrical rough-in where cost control and installation speed matter.
- Commercial:Retail, healthcare, and education facilities requiring fire-rated systems and inspection documentation. Hospital construction in California and New York demands EMT and IMC for emergency circuit integrity per NFPA 99.
- Industrial:Manufacturing, petrochemical, and food processing plants with hazardous location classifications. Gulf Coast LNG facilities specify coated steel and HDPE for corrosion resistance in salt-air environments.
- Infrastructure:Transportation, broadband, and utility projects with extended design lives and public funding cycles.
Commercial end users generate the highest revenue per project; infrastructure is expanding most quickly.
Size:
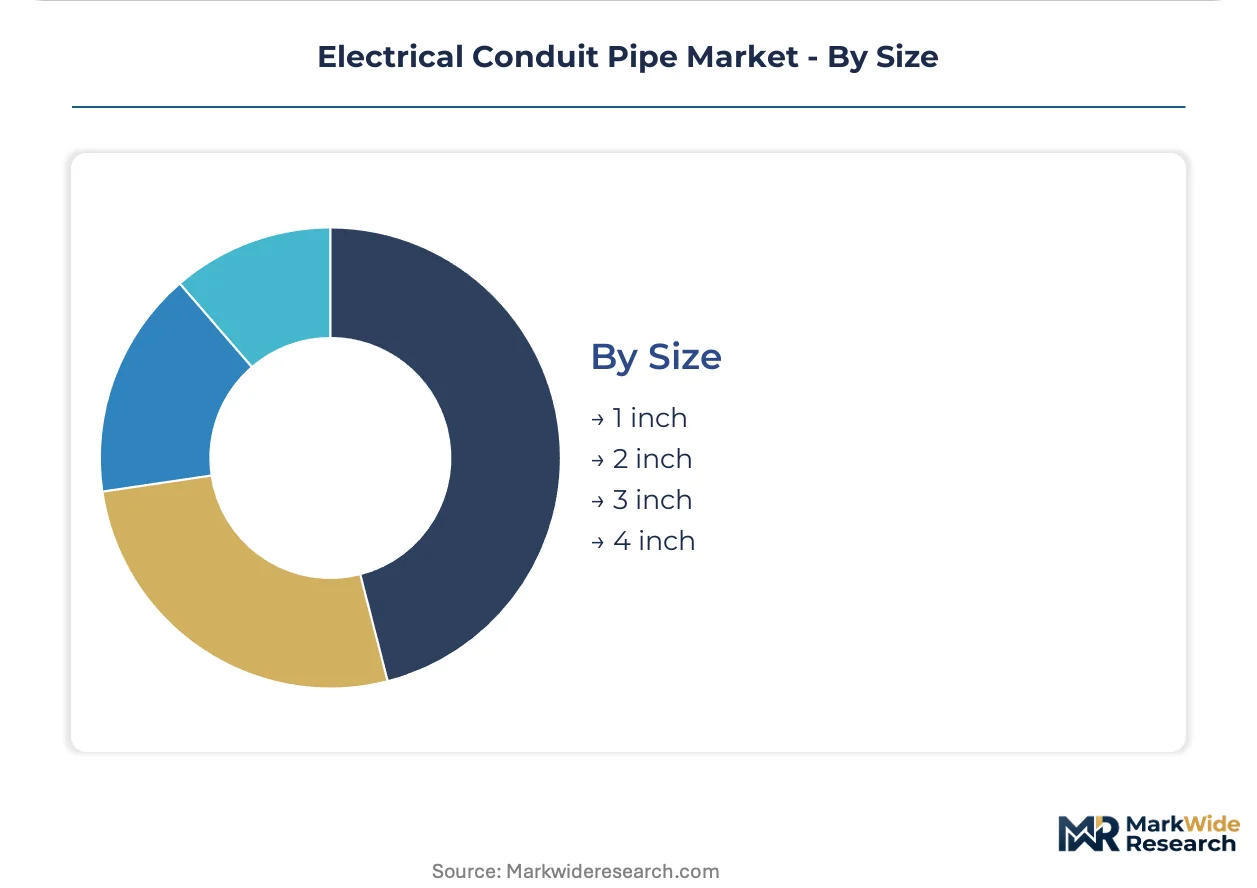
Conduit diameter scales with circuit ampacity and wire fill requirements per NEC Chapter 9 tables.
- 1 inch:Standard residential branch circuit capacity for 15-20A lighting and receptacle loads.
- 2 inch:Commercial feeder circuits and panelboard connections requiring higher conductor counts.
- 3 inch:Main distribution runs in industrial facilities and large commercial buildings.
- 4 inch:Primary service entrances and utility-scale interconnections for data centers and solar farms.
1 inch and 2 inch diameters dominate unit volumes; 4 inch specifications are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast corridor concentrates petrochemical and LNG facility expansions driving corrosion-resistant conduit demand across Texas and Louisiana. Data center construction clusters in Northern Virginia and Dallas-Fort Worth absorb miles of underground feeder circuits. Utility-scale solar farms spread across Nevada and Arizona specify HDPE for trenching efficiency.
United States
Hyperscale data centers in Northern Virginia and Dallas-Fort Worth require extensive underground conduit networks for redundant power distribution. NFPA 70 NEC updates mandate stricter fire-resistance ratings for commercial installations across retail, healthcare, and education verticals. The Gulf Coast petrochemical corridor spanning Texas and Louisiana drives demand for coated steel and HDPE conduit in hazardous location classifications.
Germany
REACH restrictions on halogenated flame retardants force PVC compound reformulation across European supply chains. ECHA substance authorization requirements accelerate metal hydroxide and phosphorus-based alternatives in commercial construction specifications. Industrial manufacturing clusters in Bavaria and North Rhine-Westphalia specify flexible metal systems for automated production environments.
China
Dual carbon goals and renewable energy buildouts accelerate utility-scale solar farm construction requiring underground collector circuits. GB standards and MIIT regulations shape electrical infrastructure material specifications for data center and manufacturing facility construction. Yangtze River Delta manufacturing hubs absorb flexible conduit for robotics and industrial machinery installations.
India
PLI scheme incentives for electronics manufacturing and data center infrastructure drive conduit demand across industrial corridors. CEA regulations and state electrical inspector approvals create multi-layer compliance requirements for commercial and infrastructure projects. Maharashtra and Gujarat industrial zones specify rigid PVC and EMT for manufacturing facility electrical distribution systems.
Japan
METI energy efficiency mandates and infrastructure modernization programs shape commercial building electrical specifications. JIS standards govern conduit performance requirements for industrial and residential applications. Kanto and Kansai manufacturing belts maintain demand for liquid-tight flexible metal systems in precision machinery and automotive production facilities.
Electrical Conduit Pipe Market Competitive Landscape
Global majors compete with regional champions across resin-to-conduit manufacturing integration and distribution reach. The market structures around three tiers: integrated polymer producers with captive conduit operations, specialized metal fabricators with electric resistance welding capacity, and regional thermoplastic extruders serving municipal infrastructure. Strategic moves center on backward integration into resin supply and geographic expansion through distributor partnerships.
Among North American fabricators, Atkore, Wheatland Tube, and Electri-Flex occupy distinct positioning vectors. Atkore exemplifies the integrated archetype with resin-to-conduit manufacturing control. Wheatland Tube anchors domestic steel conduit supply through Midwest-based electric resistance welding capacity. Electri-Flex represents specialization in liquid-tight flexible metal systems for industrial machinery applications.
| Leading Market Players |
|---|
| Hubbell |
| Electri-Flex |
| Atkore |
| Prime Conduit |
| National Pipe & Plastics |
| Cantex |
| Wheatland Tube |
| Nucor Tubular Products |
| Aliaxis |
| Others |
Supply & Pricing Matrix
NFPA 70 NEC fire-resistance mandates are forcing commercial contractors toward premium-grade EMT and IMC specifications, compelling distributors to restructure procurement tiers and compress margin spreads on standard-grade inventory.
Pricing Analysis
Resin cost pass-through dominates pricing dynamics across thermoplastic conduit categories. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed fire-rated products from commodity PVC grades, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-grade PVC is intensifying because of polyethylene feedstock volatility linked to natural gas liquids pricing. Residential contractors exhibit highest price sensitivity, while data center developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content preferences in US infrastructure procurement are reshaping sourcing patterns for federally funded broadband and solar projects. Manufacturing concentrates in the United States, China, and Germany, with raw material dependencies spanning polyethylene resin, steel coil, and aluminum billet. Supply chain risk centers on single-source vulnerability in electric resistance welding capacity clustered in the US Midwest. Distribution runs through electrical wholesalers and direct-to-contractor digital platforms, with the latter gaining share in residential and light commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as code compliance tightens and project specifications migrate toward corrosion-resistant, fire-rated systems that command durable margin premiums.
For Market Incumbents: Extend resin-to-conduit manufacturing control to buffer margin volatility from polymer feedstock swings. Deepen captive supply of HDPE compounds to defend against integrated competitors and secure specification wins in Gulf Coast petrochemical projects. Invest in UL-listed fire-rated product certification to capture NEC-driven retrofit demand across healthcare and education verticals. For New Entrants and Emerging Players: Specialty distributors serving data center contractors represent the most accessible channel for market entry. Target liquid-tight flexible metal conduit for industrial robotics applications where incumbent coverage remains thin. Pursue municipal broadband bundling opportunities created by FCC underground utility coordination mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with regional thermoplastic extruders possessing Gulf Coast geographic positioning and resin backward integration. Long-term viability hinges on exposure to utility-scale solar and data center construction cycles rather than residential housing volatility. Monitor HDPE resin price spreads as an inflection indicator for margin compression risk across non-integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene production insulates Atkore from feedstock volatility in utility-scale solar procurement. |
| Fire-Rated Product Certification Investment | UL 94 V-0 listings capture NEC-mandated retrofit cycles across California hospital construction. |
| Digital Procurement Platform Partnership | Direct-to-contractor channels bypass distributor markups in Texas residential electrical markets. |
| Geographic Expansion to Gulf Coast Corridor | Texas and Louisiana proximity reduces logistics costs for petrochemical facility conduit specifications. |
| Co-Extruded HDPE Technology Development | Integrated conductive layers eliminate tracer wire labor in oil and gas cathodic protection applications. |
Research Methodology
Multiple input streams — structured interviews with electrical contractors and distributors, resin procurement data from polymer markets, and NEC code adoption tracking — were reconciled to build segment-level demand estimates. Primary fieldwork engaged plant managers at conduit extrusion facilities, procurement leads at data center developers, electrical inspectors in Texas and California, and channel partners serving municipal infrastructure. Secondary validation drew from NFPA code revision records, UL certification databases, EIA energy construction data, and SEC filings of publicly traded electrical product manufacturers. Bottom-up project pipeline analysis and top-down construction spending triangulation anchored volume forecasts.
Historical installation patterns were cross-referenced against panel input from specification engineers and contractor bidding behavior to construct the analytical framework. Segmentation modeling spanned material type, installation method, end-user vertical, and conduit diameter across the projection horizon. CAGRs were derived from trend extrapolation adjusted for code-cycle timing and infrastructure funding disbursement patterns. Forecast inputs incorporated solar farm development pipelines, data center power density requirements, and resin price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal infrastructure appropriation delays, state-level PFAS regulatory expansion, and electrician apprenticeship graduation rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Glass Curtain Wall Market
Construction and Engineering
Gas Connectors and Gas Hoses Market
Construction and Engineering
Horizontal Directional Drilling Market
Construction and Engineering
Trim Press Market
Construction and Engineering
Underground Mining Diamond Drilling Market
Construction and Engineering
Bulldozer Market
Construction and Engineering
France Prefab Wood Building Market
Construction and Engineering
Industrial Condensing Units Market
Construction and Engineering
East Africa Wall Putty Market
Construction and Engineering
Wet Scrubber Market
Construction and Engineering
Light Gauge Framing System Market
Construction and Engineering
Blowing Torch Market
Construction and Engineering
East Africa White Cement Market
Construction and Engineering
Elevator Door-Motor Market
Construction and Engineering
Qatar Facade Market
Construction and Engineering
Welded Steel Tanks Market