
 Antiozonant Market | 2026-2036
Antiozonant Market Size, Share, and Industry Trends Forecast 2026-2036
Antiozonant Market Analysis
Automotive OEMs and tier-one tire suppliers is bifurcating demand between commodity-grade and performance-specification antiozonant buyers. LANXESS anchors its position through backward integration into key aromatic amine intermediates. Eastman Chemical Company differentiates via liquid antiozonant concentrates that reduce mixing-cycle times for high-volume tire plants. SI Group, Inc. competes on R&D intensity in non-staining antiozonant variants for white sidewall and aesthetic rubber applications.
Antiozonants are chemical additives, predominantly para-phenylenediamine derivatives and wax-based systems, that inhibit ozone-induced cracking in unsaturated elastomers by scavenging free radicals and forming protective surface films. These compounds function at loadings of 1–3 phr in rubber formulations to extend flex-fatigue life in dynamic applications such as tires, conveyor belts, and engine mounts. The rubber application segment dominates volume consumption given tire industry scale, while specialty-grade liquid concentrates command margin premiums in precision-calendered industrial goods. The automotive end-user channel leads absolute demand but industrial maintenance, repair, and operations procurement is expanding faster as infrastructure replacement cycles compress.
REACH registration requirements and the EU F-Gas Regulation constrain certain traditional antiozonant chemistries in Europe, while EPA Toxic Substances Control Act reporting shapes product stewardship obligations in the United States. China's GB standards on rubber chemical emissions and India's BIS certification for tire-grade additives create divergent compliance thresholds that fragment formulation strategies across manufacturing geographies. Stakeholders must monitor regulatory pre-announcements in target jurisdictions to anticipate reformulation timelines and avoid stranded inventory positions.
Market Dynamics
Electric vehicle tire specifications are forcing reformulation of antiozonant loadings and chemistries as higher torque and weight profiles accelerate rubber degradation. Tire OEMs now specify differentiated additive packages for EV versus internal combustion platforms.
Growth Catalysts
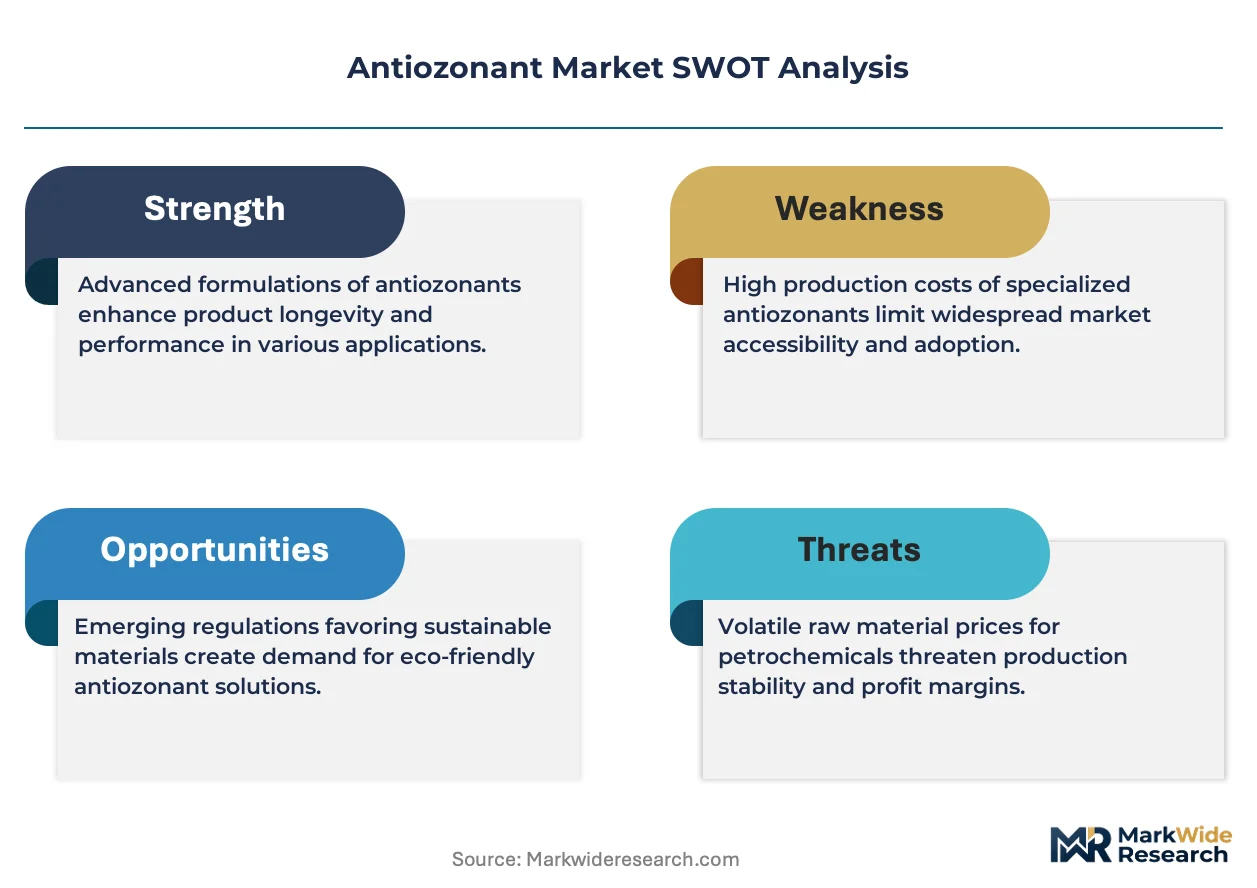
- REACH Phase-Out Pressure:ECHA restrictions on certain para-phenylenediamine derivatives are redirecting R&D budgets toward compliant alternatives, expanding the addressable market for bio-based antiozonant suppliers.
- China Tire Production Scale:Domestic tire manufacturing capacity expansion under GB standards compliance is sustaining chemical additive procurement volumes despite export market softness.
- Wax-Blend Concentrate Technology:Liquid delivery systems that reduce Banbury mixing cycle times by 15-20% are capturing share in high-throughput tire plants seeking line efficiency gains.
Market Restraints
- Aniline Feedstock Volatility:Crude oil-linked benzene and nitrobenzene pricing swings compress margin predictability for aromatic amine-based antiozonant producers.
- China Supply Concentration:60-70% of rubber chemical intermediate capacity resides in Shandong and Jiangsu provinces, creating geographic risk exposure for global formulators.
- Performance Trade-Offs:Non-staining antiozonant variants for white sidewall applications deliver inferior ozone protection versus traditional PPD chemistries, limiting adoption in severe-service tire segments.
Strategic Opportunities
- India BIS Certification Pathway:Tire-grade additive standardization under Bureau of Indian Standards creates first-mover positioning for compliant suppliers as domestic tire production scales.
- Conveyor Belt Remanufacturing:Industrial MRO channel expansion for mining and bulk material handling equipment creates demand for specialty-grade antiozonants in retreading compounds.
- EU Green Deal Procurement Mandates:Public sector vehicle fleet purchasing rules favoring sustainable tire specifications are pulling bio-based antiozonant adoption in European OEM supply chains.
Industry Challenges
- Reformulation Timeline Compression:REACH sunset dates for restricted chemistries leave insufficient lead time for full qualification cycles with tier-one tire manufacturers.
- Cross-Contamination Control:Multi-product rubber chemical plants face capital-intensive equipment segregation requirements to prevent staining antiozonant carryover into non-staining product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiozonant Market |
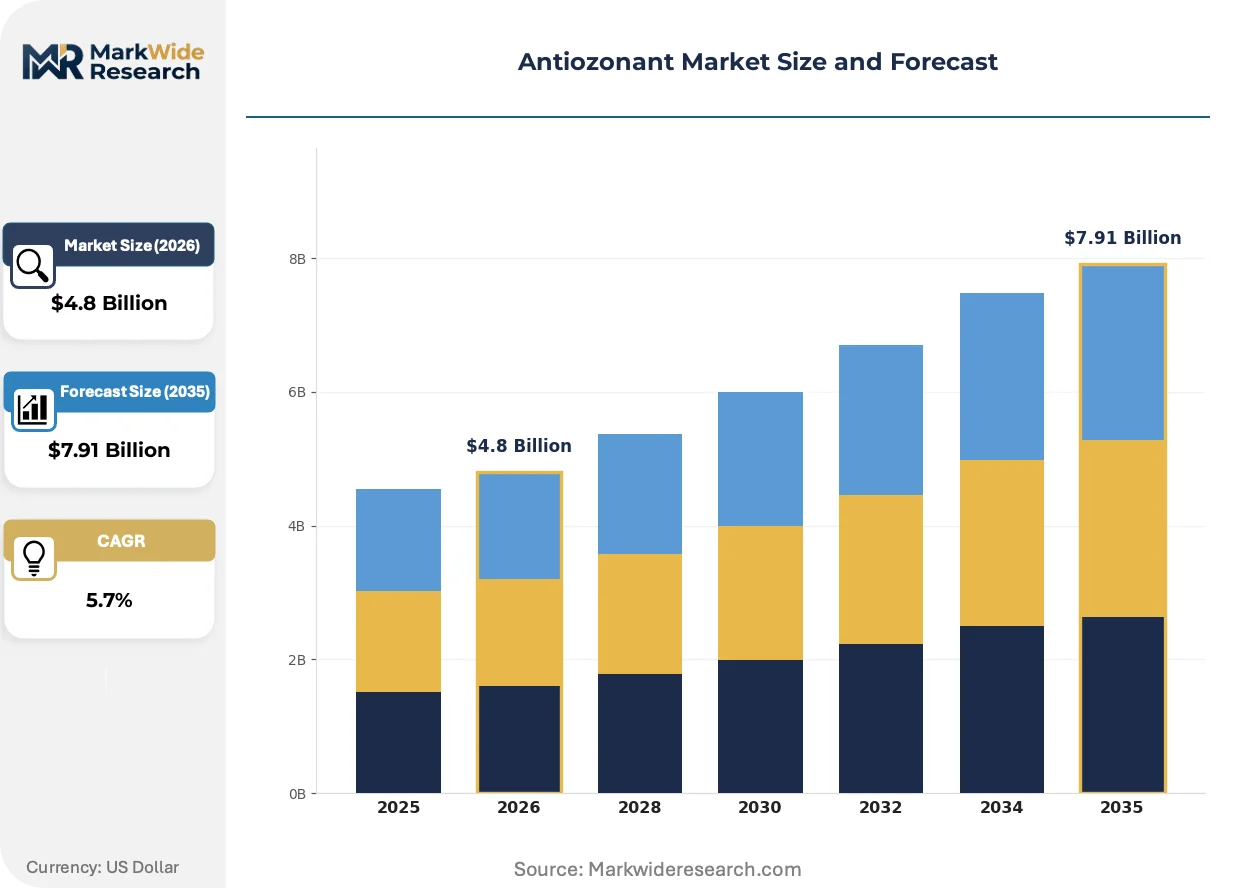
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Rubber, Plastics, Coatings, Textiles Form: Granules, Liquids, Powders, Concentrates End User: Automotive, Industrial, Consumer Goods, Aerospace Type: Primary, Secondary, Tertiary, Specialty |
| Companies Covered | LANXESS, Eastman Chemical Company, SI Group, Inc., NOCIL LIMITED, PMC Group, Inc, DOG Chemie, Alpine Chemie, SASOL, Repsol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiozonant Market Emerging Trajectories
Formulation science is splitting along performance-versus-sustainability axes as tire OEMs face divergent customer specifications and regulatory timelines. The technology frontier now spans molecular design, delivery systems, and end-of-life compatibility.
Microencapsulated antiozonant delivery systems are bifurcating the compounding equipment market. These systems protect active ingredients from premature thermal degradation during mixing while enabling controlled release during tire service life. High-performance tire manufacturers in Germany and Japan are qualifying these systems for ultra-high-performance summer tire lines. The technology is compressing demand for conventional dry powder handling infrastructure and favoring liquid dosing equipment suppliers.
ECHA's restriction roadmap for certain PPD derivatives is compressing the viable chemistry set for European tire production. The industrial consequence is accelerated migration toward para-phenylenediamine alternatives and wax-based protective systems that meet hazard classification thresholds. Specialty tire producers serving agricultural and off-road segments face the steepest reformulation curves given their reliance on maximum-protection chemistries.
Direct compounder procurement of antiozonant masterbatches is displacing traditional distributor channels in high-volume tire manufacturing regions. Tier-one tire plants in Thailand and Vietnam are negotiating direct supply agreements with additive houses to secure volume commitments and technical service access. This channel compression is most visible in Southeast Asia, where greenfield tire capacity is concentrating and established distribution networks remain underdeveloped relative to production scale.
Antiozonant Market Segmentation
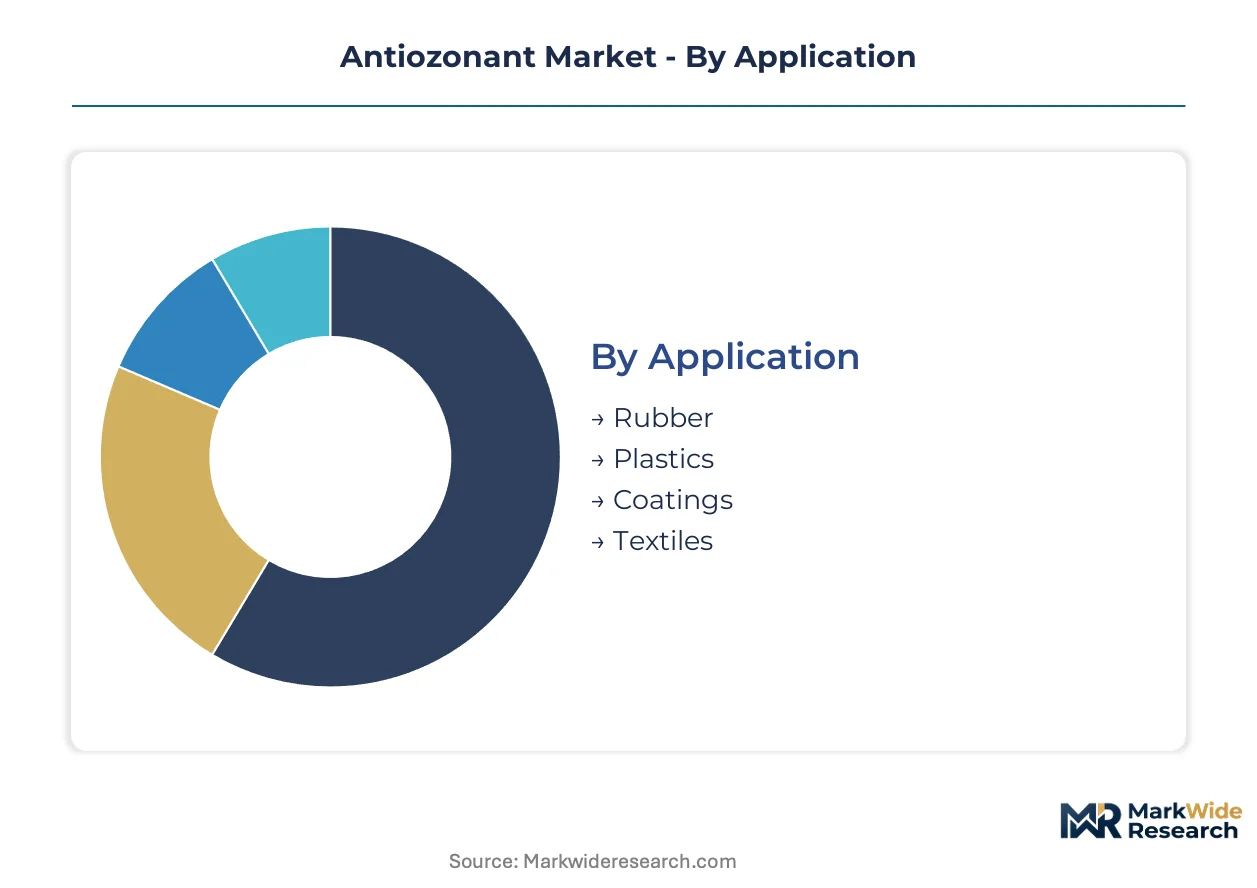
Antiozonant procurement patterns diverge sharply across application chemistries and delivery formats. Tire manufacturers drive volume concentration in rubber-grade formulations, while regulatory pressure on para-phenylenediamine derivatives fragments the specialty segment into compliant alternatives.
Application:
Margin pools concentrate in rubber formulations serving dynamic flex-fatigue environments, where ozone protection commands specification premiums over commodity plastics compounding.
- Rubber:Para-phenylenediamine derivatives and wax-based systems protect unsaturated elastomers in tires, conveyor belts, and engine mounts. Tire OEMs in China specify differentiated additive packages for electric vehicle versus internal combustion platforms, with higher torque and weight profiles accelerating rubber degradation. The dominant share belongs to Rubber, while Plastics is closing the gap fastest.
- Plastics:Polymer stabilization applications in outdoor construction materials and agricultural films require lower loadings than rubber formulations. Demand concentrates in weatherable PVC and polyolefin compounds for infrastructure replacement cycles in North American and European markets.
- Coatings:Protective film-forming additives for exterior automotive and industrial coatings.
- Textiles:Fiber stabilization in outdoor upholstery and technical fabrics exposed to ozone and UV degradation.
Rubber applications absorb the majority of antiozonant volume, though plastics compounding is expanding most quickly as construction polymer specifications tighten.
Form:
Delivery format selection hinges on mixing equipment infrastructure and Banbury cycle efficiency targets rather than active chemistry alone.
- Liquids:Concentrated delivery systems reduce mixing-cycle times by 15-20% in high-throughput tire plants. Southeast Asian greenfield capacity favors liquid dosing equipment over conventional dry powder handling infrastructure. Liquids capture the steepest expansion trajectory as direct compounder procurement displaces distributor channels.
- Concentrates:Pre-dispersed masterbatches secure volume commitments through direct supply agreements between additive houses and tier-one tire manufacturers. Thai and Vietnamese plants negotiate these arrangements to guarantee technical service access.
- Granules:Dust-free handling format for multi-product rubber chemical plants requiring contamination control.
- Powders:Legacy dry format facing displacement as microencapsulated systems compress demand for conventional handling infrastructure.
Liquid formats lead technology investment, while concentrates are gaining share fastest through channel restructuring.
End User:
Automotive procurement specifications cascade through tier-one tire suppliers, while industrial MRO channels expand on compressed infrastructure replacement cycles.
- Automotive:OEM specifications now bifurcate between commodity-grade and performance-specification buyers. Electric vehicle platforms require higher-durability rubber formulations with reformulated antiozonant loadings. The automotive channel commands absolute demand leadership.
- Industrial:Mining and bulk material handling equipment drives conveyor belt remanufacturing demand. Retreading compounds for industrial rubber goods require specialty-grade antiozonants with precise calendering compatibility.
- Consumer Goods:White sidewall and aesthetic rubber applications specify non-staining antiozonant variants despite inferior ozone protection versus traditional PPD chemistries.
- Aerospace:Extreme-service elastomer specifications for engine mounts and sealing systems.
Automotive end-use dominates procurement volume, though industrial MRO is climbing the fastest as maintenance cycles compress.
Type:
Functional classification separates scavenging mechanisms and protective film formation, with regulatory pressure reshaping the viable chemistry set.
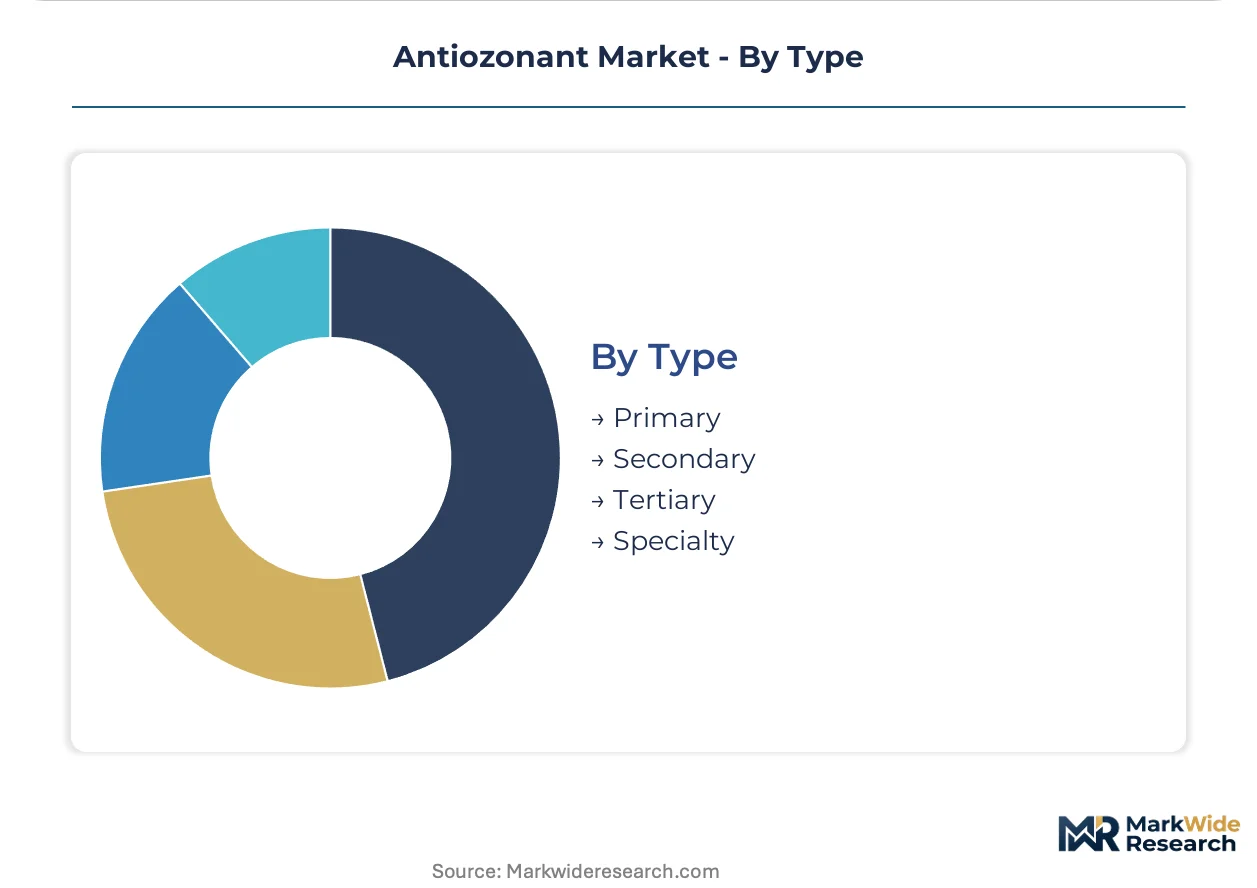
- Primary:Para-phenylenediamine derivatives function at 1-3 phr loadings by scavenging free radicals before ozone attack. ECHA restrictions on certain PPD derivatives are compressing the viable chemistry set for European tire production, accelerating migration toward compliant alternatives.
- Specialty:Bio-based and low-toxicity alternatives capture reformulation investment as REACH sunset dates force qualification cycles with tier-one manufacturers. Agricultural and off-road tire segments face the steepest reformulation curves given their historical reliance on maximum-protection chemistries.
- Secondary:Synergistic blends enhancing primary antiozonant performance in severe-service applications.
- Tertiary:Protective wax-based systems forming surface films without radical scavenging activity.
Primary antiozonants retain specification dominance, while specialty variants are expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port rubber chemical terminal anchors China's role as the dominant procurement hub for tire-grade additives, processing aromatic amine intermediates from Shandong province refineries before distribution to domestic tire plants and Southeast Asian manufacturing zones.
China
Domestic tire production under GB standards compliance sustains chemical additive procurement volumes despite export softness. MEE emissions regulations on rubber chemical manufacturing concentrate compliance investment in Jiangsu and Shandong provinces. The Yangtze River Delta cluster around Nanjing hosts backward-integrated aromatic amine producers supplying antiozonant formulators.
Germany
Ultra-high-performance tire manufacturers in Baden-Württemberg qualify microencapsulated delivery systems for summer tire lines. ECHA restrictions on para-phenylenediamine derivatives compress viable chemistry sets for European production. The KBA collaborates with tire OEMs on EV-specific rubber formulation standards requiring reformulated antiozonant loadings.
United States
EPA Toxic Substances Control Act reporting shapes product stewardship obligations for aromatic amine-based producers. The Gulf Coast petrochemical corridor supplies benzene and nitrobenzene feedstocks to antiozonant manufacturers. Tennessee and Texas host liquid concentrate blending facilities serving high-throughput tire plants.
India
BIS certification for tire-grade additives creates first-mover positioning as domestic tire production scales. The PLI scheme for automotive components indirectly supports rubber chemical demand through tire manufacturing expansion. Gujarat and Maharashtra industrial corridors concentrate new tire plant capacity requiring qualified additive supply chains.
Thailand
Greenfield tire capacity concentrates procurement power for direct compounder negotiations with additive houses. Thai industrial estates attract Japanese and Korean tire OEMs specifying differentiated EV platform formulations. The Eastern Economic Corridor hosts masterbatch blending facilities bypassing traditional distributor channels.
Antiozonant Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and R&D commitment dimensions. The vendor base splits between backward-integrated chemical conglomerates and focused additive houses. Three archetypes dominate: aromatic amine producers with captive intermediate supply, liquid concentrate specialists emphasizing mixing efficiency, and regional compounders serving distributor channels. Capacity expansion and direct procurement agreements represent the dominant competitive moves as tire plants consolidate supplier relationships.
Within the integrated chemical tier, LANXESS anchors its position through in-house production of key aromatic amine intermediates. Eastman Chemical Company exemplifies the liquid delivery format specialists reducing Banbury cycle times for high-volume manufacturers. SI Group, Inc. occupies a position among R&D-intensive houses developing non-staining variants for aesthetic rubber applications. These three represent distinct strategic postures rather than overlapping competitive territory.
| Leading Market Players |
|---|
| LANXESS |
| Eastman Chemical Company |
| SI Group, Inc. |
| NOCIL LIMITED |
| PMC Group, Inc |
| DOG Chemie |
| Alpine Chemie |
| SASOL |
| Repsol |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day aromatic amine intermediate lead times tether pricing power to Shandong and Jiangsu province inventory positions, compressing margin buffers for formulators when benzene-nitrobenzene spreads widen.
Pricing Analysis
Three-tier pricing structure across performance-grade, standard rubber-grade, and commodity wax-blend levels separates tire OEM specifications. Price differentiation hinges on REACH compliance certification and volume scale commitments. Pricing pressure stems from aniline feedstock volatility as crude-linked benzene costs swing unpredictably. Commodity-grade buyers exhibit highest price sensitivity, while performance-specification tire manufacturers absorb premiums for EV-platform qualified additives.
Supply Chain Analysis
Inventory positions at Qingdao Port rubber chemical terminals signal supply tightness before price movements transmit to Southeast Asian tire plants. Manufacturing concentrates in China, Germany, and the United States. Production draws from benzene, nitrobenzene, and para-phenylenediamine intermediates. Single-source vulnerability pervades Shandong province aromatic amine capacity. Distribution runs through direct compounder agreements displacing traditional distributor channels in Thai and Vietnamese greenfield capacity zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH sunset dates for restricted para-phenylenediamine derivatives compress reformulation timelines, forcing simultaneous chemistry migration and qualification cycles that favor agile suppliers with compliant alternative pipelines.
For Market Incumbents: Fortify backward integration into key aromatic amine intermediates to offset feedstock volatility exposure. Expand liquid concentrate blending capacity in Tennessee and Texas to capture high-throughput tire plant demand. ECHA restriction roadmaps threaten stranded inventory positions for PPD-dependent formulators.
For New Entrants and Emerging Players: BIS certification fast-track for tire-grade additives opens positioning as Indian domestic tire production scales under PLI scheme support. Target conveyor belt remanufacturing MRO channels with specialty-grade liquid concentrates. Pursue direct technical service partnerships with tier-one compounders bypassing distributor layers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming rubber additive divisions. Long-term viability centers on bio-based antiozonant platforms aligned with EU Green Deal procurement mandates. Monitor ECHA pre-announcements for restriction timeline accelerations signaling chemistry set displacement inflections.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Amines | Captive nitrobenzene supply shields LANXESS from benzene price volatility at Ludwigshafen. |
| Liquid Concentrate Capacity Expansion | Banbury cycle reduction of 15-20% locks in high-volume tire plant procurement commitments. |
| REACH-Compliant Alternative R&D | Bio-based antiozonant qualification with tier-one OEMs secures European market access post-sunset dates. |
| Direct Compounder Supply Agreements | Masterbatch contracts with Thai and Vietnamese plants displace distributor channel economics. |
| Microencapsulated Delivery System Qualification | German ultra-high-performance tire manufacturers specify controlled-release technology for summer lines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with tire OEM procurement directors, rubber chemical plant managers, and ECHA regulatory affairs specialists; and secondary validation against customs trade data, SEC 10-K chemical segment disclosures, and GB standards documentation. Bottom-up segment sizing triangulated with top-down industry value-chain assessments.
Across the analysis window, forecasts modeled rubber versus plastics application splits, liquid versus powder delivery formats, and automotive versus industrial end-use channels. CAGRs derived from regression analysis of historical aromatic amine consumption patterns and projected EV tire production ramp rates. Benzene-nitrobenzene spread assumptions and REACH compliance cost curves fed sensitivity scenarios.
The analysis sits within stated boundaries; outcomes outside sustained China tire production scale or accelerated ECHA restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding feedstock cost trajectories and regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Calcium Carbide Market
Chemicals
N-Propanol Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
CHPTAC Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Asia-Pacific Methanol Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Acetic Ether Market
Chemicals
China Amines Market
Chemicals
Inorganic Chemicals Market