
 Global Boron Trifluoride Market | 2026-2036
Global Boron Trifluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boron Trifluoride Market Foresight
REACH compliance is decoupling small-scale traders from the European boron trifluoride supply chain, raising the cost-of-entry calculus for new participants. BASF SE leverages its integrated fluorochemistry platform to sustain captive feedstock security across German and Belgian production nodes. Honeywell International Inc. anchors North American supply through its specialty materials division, while Arkema S.A. competes via differentiated boron trifluoride etherate grades for pharmaceutical synthesis.
Boron trifluoride is a pungent, corrosive gas with molecular formula BF3 and boiling point of −100.3°C, manufactured primarily through fluorination of boron oxide or thermal decomposition of fluoroborates for use as a strong Lewis acid catalyst. The gaseous form dominates volume flows into semiconductor manufacturing, where ultra-high purity specifications command premium positioning. Liquid boron trifluoride and boron trifluoride complexes occupy expanding niches in petrochemical polymerization, while drum container packaging for etherate derivatives captures margin pools in pharmaceutical contract manufacturing.
EPA fluorinated gas reporting requirements, EU REACH substance authorization, and South Korean K-REACH parallel registration are tightening product stewardship obligations across all major demand centers. Semiconductor fabs now require documented supply chain transparency from boron trifluoride vendors, shifting procurement criteria beyond price toward regulatory certification depth. Stakeholders must monitor evolving fluorinated gas phase-down schedules and assess backward integration into boron raw material sources as a risk mitigation priority.
Market Dynamics
Semiconductor ion implantation specifications are tightening faster than incumbent purification capacity can expand, compressing qualified supplier lists and amplifying contract security premiums for remaining vendors.
Growth Catalysts
- Advanced node semiconductor fabrication:South Korean memory manufacturers in Pyeongtaek and Yongin are expanding boron trifluoride consumption for sub-7nm doping processes. This application now commands the highest purity grades.
- EU F-Gas Regulation phase-down schedules:Controlled substance frameworks are redirecting investment toward boron trifluoride as a lower-GWP alternative for certain fluorinated gas applications in industrial processes.
- Petrochemical polymerization catalyst demand:Boron trifluoride etherate complexes are displacing conventional aluminum chloride systems in polyisobutylene production for lubricant additives.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in China and Mexico, exposing boron trifluoride producers to export quota volatility and input cost spikes.
- Ultra-high purity technical barriers:Semiconductor-grade specifications below 1 ppb metallic impurity thresholds require specialized distillation infrastructure unavailable to mid-scale manufacturers.
- EU REACH authorization timelines:Substance authorization procedures for boron trifluoride derivatives extend 18-24 months, freezing formulation development cycles for European pharmaceutical contract manufacturers.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDMO capacity growth in Hyderabad and Ahmedabad is creating demand for boron trifluoride etherate in active pharmaceutical ingredient synthesis.
- Solid-state storage and delivery systems:Adsorbed gas technologies are enabling safer transport modalities for remote semiconductor fabs lacking on-site gas handling infrastructure.
- US CHIPS Act fabrication subsidies:Domestic semiconductor manufacturing incentives in Arizona and Texas are attracting boron trifluoride distribution infrastructure investments.
Industry Challenges
- Specialized fluorochemistry talent scarcity:Experienced process engineers capable of managing corrosive Lewis acid production safely command premium compensation and extended recruitment cycles.
- Multi-jurisdiction product stewardship synchronization:Simultaneous compliance with EPA fluorinated gas reporting, EU REACH, and South Korean K-REACH requires dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boron Trifluoride Market |
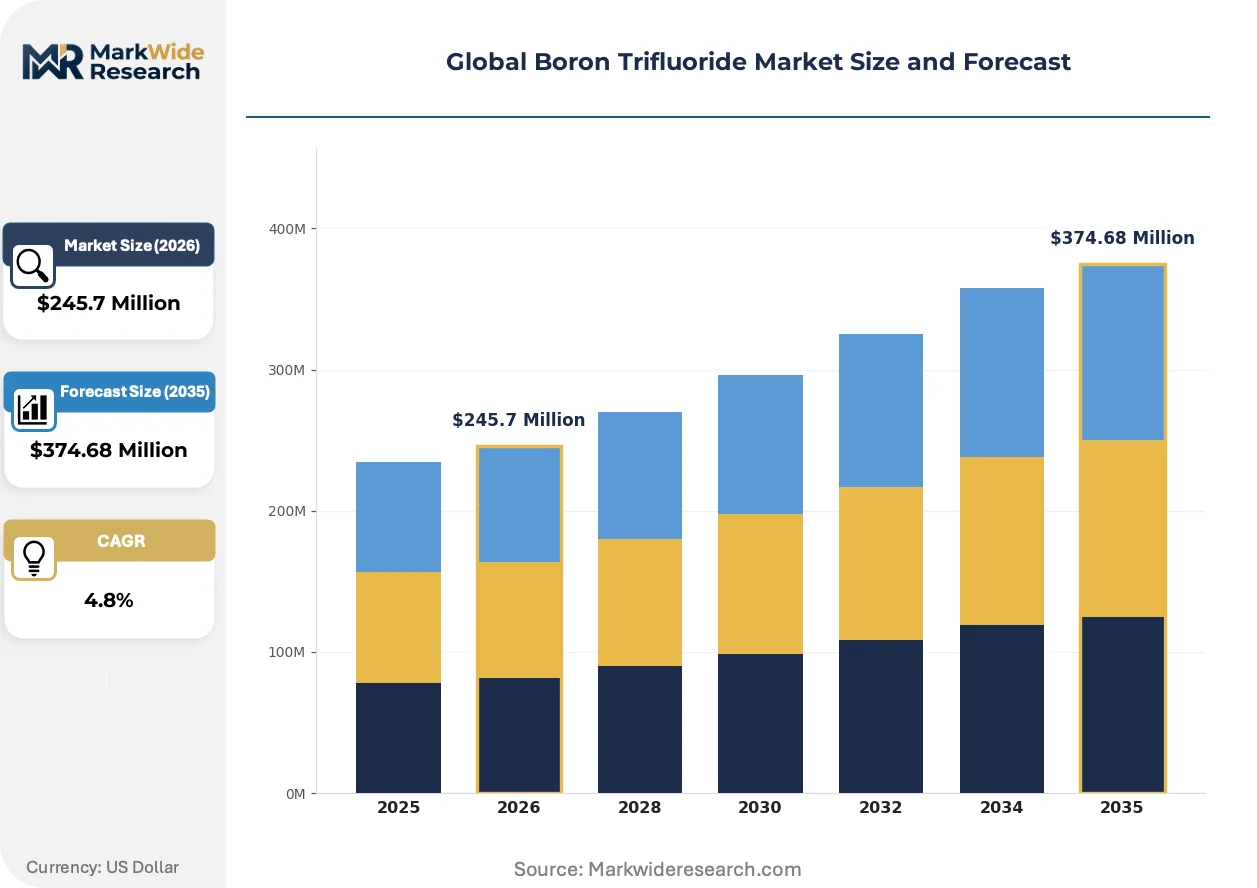
| Market Size in 2026 | $245.7 Million |
| Market Size in 2035 | $374.68 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaseous Boron Trifluoride, Liquid Boron Trifluoride, Boron Trifluoride Complexes, Boron Trifluoride Etherate Application: Polymerization Catalyst, Semiconductor Manufacturing, Chemical Synthesis, Metal Recovery, Laboratory Reagent End Use Industry: Electronics Fabricators, Petrochemical Plants, Pharmaceutical Manufacturers, Agricultural Chemical Producers Packaging Type: Steel Cylinders, High-Pressure Tanks, Drum Containers, Glass Bottles |
| Companies Covered | BASF SE, Honeywell International Inc., Arkema S.A., Tanfac Industries Ltd., Gulbrandsen Chemicals, Praxair Technology Inc., Navin Fluorine International Limited, Stella Chemifa Corporation, Voltaix LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boron Trifluoride Market Shifts & Advancements
Containerized delivery modalities and purification technologies are compressing the traditional gap between commodity chemical supply and semiconductor-grade service expectations.
Point-of-use purification skids are overtaking centralized bulk gas distribution in advanced semiconductor fabs. These modular systems strip residual moisture and particulates from boron trifluoride streams immediately before ion implantation chambers. Samsung and SK Hynix facilities in South Korea are deploying this architecture to reduce contamination risk. The shift is compressing demand for traditional bulk trailer delivery contracts.
EU F-Gas Regulation 2024 amendments are accelerating refrigerant sector displacement schedules. Industrial process exemptions for boron trifluoride are narrowing, forcing chemical manufacturers to document alternative feedstock pathways. German and Belgian production nodes face the most immediate compliance recertification burdens.
Specification-driven vendor consolidation is visible across East Asian procurement offices. Semiconductor fabs are reducing qualified supplier lists from six to three vendors per site, prioritizing those with integrated boron raw material sourcing. South Korean memory manufacturers are leading this consolidation, demanding documented supply chain transparency down to boron ore origins.
Global Boron Trifluoride Market Segmentation
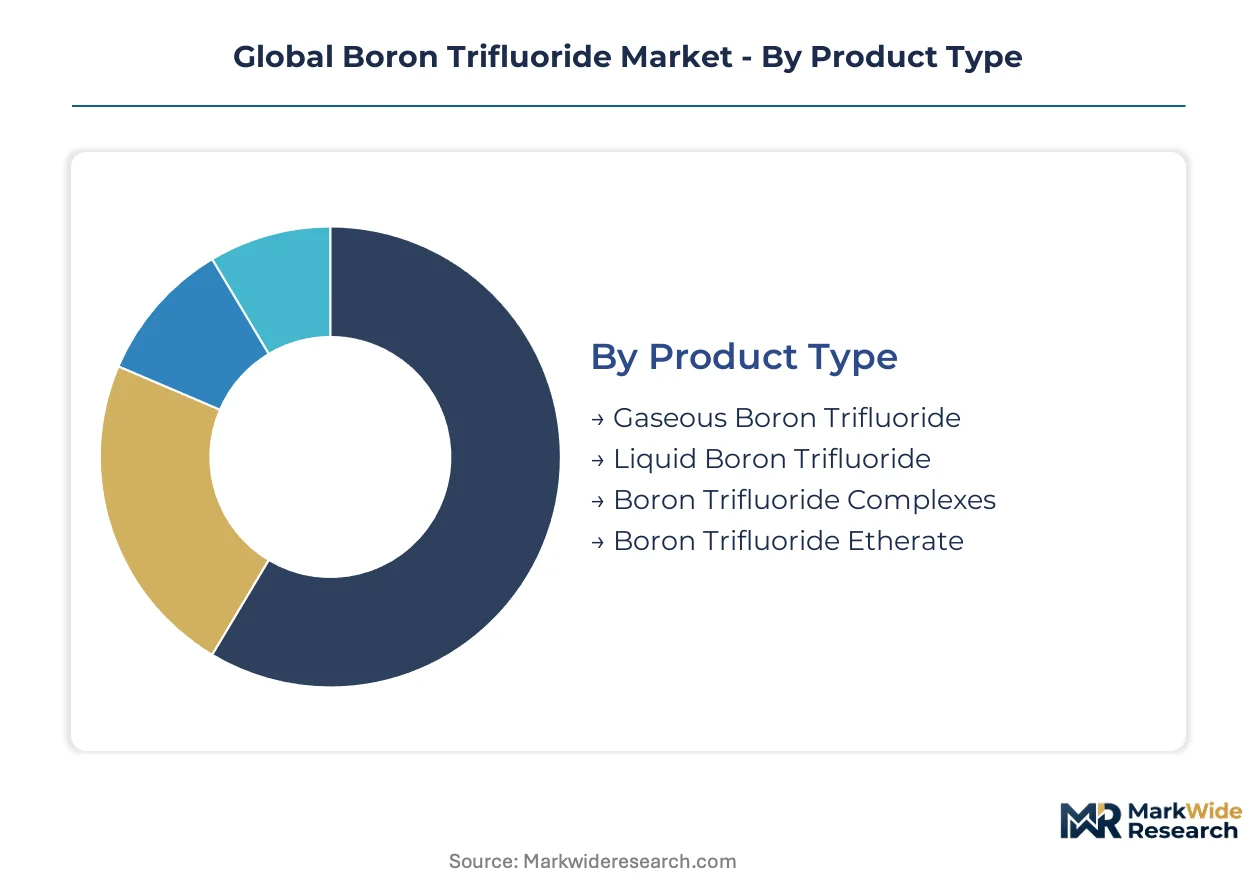
Segmentation in boron trifluoride markets reveals how regulatory burden concentrates differently across physical forms and end-use specifications. Certification requirements fragment competitive dynamics, with semiconductor-grade products demanding documentation depths unavailable to commodity suppliers.
Product Type:
Certification obligations escalate sharply from gaseous to complexed forms, with semiconductor fabs demanding ppb-traceability documentation that etherate producers supplying pharmaceutical synthesis rarely encounter.
- Gaseous Boron Trifluoride:Ultra-high purity gas delivered at 99.999%+ specifications dominates ion implantation doping in South Korean memory fabrication. Pyeongtaek-based fabs require documented supply chain transparency down to boron ore origins, compressing qualified vendor lists to integrated fluorochemistry platforms.
- Boron Trifluoride Etherate:The diethyl ether complex serves as a bench-stable Lewis acid catalyst for pharmaceutical acylation reactions and polyisobutylene polymerization. Hyderabad CDMO expansion is accelerating drum-container procurement for API synthesis, though EU REACH authorization timelines extend 18-24 months for new formulations.
- Liquid Boron Trifluoride:Condensed-phase storage enables safer transport logistics for remote petrochemical facilities lacking on-site gas handling infrastructure.
- Boron Trifluoride Complexes:Amine and phenol adducts provide handling convenience for agricultural chemical synthesis where absolute purity thresholds are relaxed.
Leading the category by volume: Gaseous Boron Trifluoride. Growing fastest: Boron Trifluoride Etherate.
Application:
Application selection determines whether buyers face EPA fluorinated gas reporting, EU F-Gas Regulation phase-down compliance, or K-REACH parallel registration.
- Semiconductor Manufacturing:Ion implantation doping for sub-7nm nodes commands the most stringent metallic impurity thresholds below 1 ppb. Samsung and SK Hynix facilities are deploying point-of-use purification skids that strip residual moisture immediately before process chambers, reducing reliance on bulk trailer contracts.
- Polymerization Catalyst:Boron trifluoride etherate displaces aluminum chloride systems in polyisobutylene production for lubricant additives, with petrochemical plants in Texas and Louisiana expanding consumption.
- Chemical Synthesis:Friedel-Crafts alkylation and acylation reactions in fine chemical production utilize etherate complexes where handling safety trumps absolute purity.
- Metal Recovery:Hydrometallurgical extraction applications for rare earth separation employ technical-grade material with relaxed certification requirements.
- Laboratory Reagent:Analytical and research-scale consumption represents fragmented demand across academic and industrial R&D facilities.
Dominant by revenue concentration: Semiconductor Manufacturing. Steepest expansion trajectory: Polymerization Catalyst.
End Use Industry:
Industry selection maps directly to jurisdiction-specific stewardship obligations, with electronics fabricators navigating the most multi-layered compliance environment.
- Electronics Fabricators:Memory and logic chip manufacturers in South Korea's Yongin corridor and Arizona's Phoenix metro are consolidating qualified supplier lists from six to three vendors per site. US CHIPS Act subsidies are attracting distribution infrastructure investments to serve domestic fabrication expansion.
- Petrochemical Plants:Polyisobutylene and synthetic rubber producers in the US Gulf Coast and Rotterdam-Antwerp cluster consume etherate complexes for continuous polymerization processes.
- Pharmaceutical Manufacturers:CDMO capacity growth in Ahmedabad and Hyderabad is creating demand for drum-container etherate deliveries, though Indian pharmaceutical manufacturers face evolving national chemical inventory notification requirements.
- Agricultural Chemical Producers:Pesticide and herbicide synthesis applications utilize technical-grade complexes where cost efficiency outweighs traceability documentation.
Highest certification burden: Electronics Fabricators. Fastest demand growth: Pharmaceutical Manufacturers.
Packaging Type:
Packaging selection reflects transport distance, consumption scale, and safety infrastructure availability at destination facilities.
- Steel Cylinders:Standard high-pressure containment for gaseous product serves semiconductor fabs with established gas handling infrastructure and trained personnel.
- High-Pressure Tanks:Bulk trailer delivery to large-volume consumers in petrochemical corridors enables economies of scale in continuous polymerization operations.
- Drum Containers:Etherate liquid handling dominates pharmaceutical contract manufacturing where batch-scale consumption matches container throughput.
- Glass Bottles:Laboratory-scale reagent packaging serves analytical and R&D applications with minimal volume requirements.
Largest volume throughput: High-Pressure Tanks. Emerging modality: Drum Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's semiconductor special economic zone concentrates memory fabrication investment, drawing boron trifluoride distribution infrastructure toward South Korea's western coast. Tax incentives for advanced node production in Arizona and Texas are reshaping North American supply chain geography. REACH compliance costs in Germany and Belgium filter trader participation across European procurement networks.
United States
CHIPS Act subsidies attract domestic fabrication capacity to Arizona and Texas, expanding ion implantation gas demand. EPA fluorinated gas reporting requirements impose documentation burdens on semiconductor fabs and chemical distributors alike. Phoenix metro fabrication clusters now require supply chain transparency down to boron ore origins.
Germany
Integrated fluorochemistry platforms in Ludwigshafen and Antwerp anchor European boron trifluoride supply security. EU REACH substance authorization procedures extend 18-24 months for derivative formulations, freezing development cycles for pharmaceutical contract manufacturers. The Rhine-Ruhr chemical corridor maintains captive feedstock integration for process reliability.
South Korea
Samsung and SK Hynix facilities in Yongin and Pyeongtaek deploy point-of-use purification skids for sub-7nm doping processes. K-REACH parallel registration requirements add regulatory layers beyond EU and US obligations. Memory chip fabrication corridors consolidate qualified supplier lists from six to three vendors per site.
India
CDMO capacity expansion in Hyderabad and Ahmedabad accelerates drum-container etherate procurement for API synthesis. BIS certification and evolving national chemical inventory notification requirements complicate import logistics. Pharmaceutical manufacturing clusters prioritize handling safety over absolute purity thresholds.
Japan
Specialty materials divisions in Osaka and Tokyo metropolitan areas sustain precision gas purification capabilities. METI industrial policy supports domestic semiconductor supply chain resilience through designated critical material status. Stella Chemifa Corporation exemplifies focused fluorochemistry specialization serving East Asian electronics fabricators.
Global Boron Trifluoride Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification requirements. The vendor base compresses around integrated fluorochemistry platforms capable of documenting boron ore provenance and metallic impurity thresholds below 1 ppb. Three archetypes dominate: captive feedstock integrators, purification technology licensors, and regional distribution specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as fabs consolidate qualified supplier lists.
Among diversified chemical conglomerates, BASF SE anchors European supply through integrated production nodes in Germany and Belgium. Honeywell International Inc. occupies a position in North American specialty materials distribution. Arkema S.A. exemplifies differentiation through etherate complex grades for pharmaceutical synthesis applications. These three represent distinct strategic postures: feedstock security, geographic anchoring, and product form specialization.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell International Inc. |
| Arkema S.A. |
| Tanfac Industries Ltd. |
| Gulbrandsen Chemicals |
| Praxair Technology Inc. |
| Navin Fluorine International Limited |
| Stella Chemifa Corporation |
| Voltaix LLC |
| Others |
Supply & Pricing Matrix
Point-of-use purification skid deployment in South Korean fabs simultaneously compresses bulk gas premiums and concentrates procurement leverage among integrated suppliers capable of documenting boron ore provenance. This technology shift rewards vendors with captive feedstock security while penalizing traders lacking backward integration into acid-grade fluorspar sourcing.
Pricing Analysis
Lead-time premiums for spot semiconductor-grade deliveries now exceed contract baselines by substantial margins, while accumulated etherate inventory in Indian pharmaceutical corridors trades at discounts. Three-tier pricing structure across semiconductor-grade, technical-grade, and reagent-grade levels reflects certification depth and metallic impurity thresholds. Cost compression in etherate complexes is intensifying because Hyderabad CDMOs are consolidating drum-container procurement volumes. Pharmaceutical contract manufacturers exhibit highest price sensitivity; sub-7nm fabs prioritize supply security over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese acid-grade fluorspar export quotas, which expose boron trifluoride producers to input cost spikes without alternative sourcing. Manufacturing concentrates in Germany, Belgium, and South Korea, with purification capabilities clustering around Ludwigshafen and Pyeongtaek. Production draws from boron oxide feedstock, diethyl ether complexing agents, and specialized corrosion-resistant alloys. Tariff exposure on Chinese fluorspar concentrates threatens margin stability for non-integrated processors. Distribution runs through integrated fluorochemistry platforms with captive logistics rather than merchant chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-high purity distillation capacity scarcity props pricing power for qualified vendors, creating durable returns for incumbents with documented ore-to-gas traceability while erecting barriers for aspirants lacking certification infrastructure.
For Market Incumbents: Deploy captive boron raw material sourcing to defend against trader disintermediation under REACH compliance tightening. Expand point-of-use purification service offerings to capture value migrating from bulk gas deliveries. Consolidate qualified supplier list positions in Yongin and Pyeongtaek corridors before CHIPS Act infrastructure matures in Arizona. For New Entrants and Emerging Players: Solid-state adsorbed gas storage technologies offer entry pathways into remote semiconductor fabs lacking on-site handling infrastructure. Target Indian pharmaceutical CDMO expansion in Ahmedabad with drum-container etherate logistics capabilities. Differentiate through K-REACH registration completion ahead of EU authorization timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated fluorochemistry platforms with documented sub-1 ppb purification capabilities and captive boron sourcing. Five-to-ten-year viability favors specialists over diversified conglomerates lacking feedstock integration. Monitor EU F-Gas Regulation amendment schedules as inflection indicators for refrigerant displacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Boron Feedstock | BASF's Ludwigshafen captive sourcing insulates against Chinese fluorspar quota volatility. |
| Point-of-Use Purification Service Expansion | Samsung Pyeongtaek deployment reduces contamination risk while compressing bulk trailer contracts. |
| K-REACH Parallel Registration Completion | Early compliance accelerates vendor qualification for SK Hynix Yongin expansion programs. |
| Solid-State Adsorbed Gas Technology Deployment | Enables safer transport to Arizona fabs lacking established gas handling infrastructure. |
| Drum-Container Etherate Logistics Investment | Hyderabad CDMO growth creates batch-scale procurement matching container throughput economics. |
Research Methodology
Independent corroboration across semiconductor fab procurement directors, fluorochemistry plant managers, and pharmaceutical CDMO supply chain leads underwrites the qualitative findings. Primary fieldwork engaged technical R&D directors at etherate complex manufacturers, distribution channel partners in the Rhine-Ruhr corridor, and regulatory affairs specialists navigating REACH authorization timelines. Secondary validation drew from customs trade data, SEC 10-K specialty materials disclosures, ECHA substance registration databases, and K-REACH notification records. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable historical periods anchored the projection framework against semiconductor capital expenditure cycles and fluorinated gas regulatory phase-down schedules. Segmentation modeling spanned physical form tiers, end-use industry applications, packaging modalities, and regional production hub clusters. CAGRs derive from slope-log analysis of demand drivers and capacity expansion announcements. Forecast inputs incorporated ion implantation specification tightening trajectories and EU F-Gas Regulation exemption narrowing assumptions.
Several conditions sit outside the modeled scope, including unforeseen fluorspar export quota suspensions, breakthrough alternative doping technologies displacing boron trifluoride in sub-5nm nodes, and geopolitical disruptions affecting East Asian semiconductor corridor logistics. Forecasts reflect documented assumptions about purification capacity commissioning schedules and regulatory authorization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Detergent Alcohols Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Aromatic Polyamine Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Potassium Hydrogen Fluoride Market
Chemicals
Trimethylamine Market
Chemicals
Chromium Trioxide Market
Chemicals
Global Amines Market
Chemicals
Etching Chemicals Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
South America Construction Chemicals Market
Chemicals
Coagulant Market
Chemicals
Indonesia Nitric Acid Market