
 Uranyl Carbonate Market | 2026-2036
Uranyl Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Uranyl Carbonate Market Analysis
Multi-source procurement among conversion facilities is decoupling from the vertically integrated supply chains that historically dominated uranium feedstock markets. Cameco Corporation leverages its Saskatchewan mining base to sustain long-term supply agreements with downstream processors. Kazatomprom anchors Central Asian production capacity through state-controlled extraction and tolling arrangements. Orano competes in European conversion services by extending its La Hague reprocessing capabilities into specialized carbonate purification.
Uranyl carbonate is a uranium(VI) coordination compound with the formula UO2CO3, typically precipitated from alkaline leach solutions and valued for its solubility profile in carbonate-based uranium recovery circuits. The powder segment dominates commercial transactions due to its direct feed compatibility with ammonium uranyl carbonate conversion lines. Nuclear energy applications lead volume consumption, while radiopharmaceuticals represent the fastest-growing demand pocket as cyclotron operators seek high-specific-activity precursors. Research institutions occupy a stable niche with predictable procurement cycles tied to grant funding.
The US Nuclear Regulatory Commission enforces strict source material licensing under 10 CFR Part 40, shaping how domestic processors qualify international suppliers. France's ASN and Canada's CNSC maintain parallel certification regimes for uranium compound handling, creating overlapping compliance obligations for cross-border traders. Kazakhstan's Ministry of Energy implements export quota frameworks that directly constrain available spot market volumes. Stakeholders must monitor regulatory divergence between national nuclear authorities and emerging environmental disclosure standards for radioactive material transport.
Market Dynamics
Conversion facilities are fragmenting procurement across multiple uranium compound suppliers, breaking the vertically integrated supply chains that historically locked feedstock to single-source processors.
Growth Catalysts
- 10 CFR Part 40 licensing:The US Nuclear Regulatory Commission's source material framework creates predictable qualification pathways for domestic processors seeking international supply partnerships.
- Radiopharmaceutical cyclotron networks:Cyclotron operators in North America and Europe are expanding high-specific-activity precursor programs that require refined uranyl carbonate feedstock.
- Carbonate-based alkaline leaching:Mining jurisdictions with established conversion infrastructure in Canada and Australia are scaling in-situ recovery circuits that precipitate uranyl carbonate directly.
Market Restraints
- Export quota frameworks:Kazakhstan's Ministry of Energy constrains spot market availability through state-controlled extraction and tolling arrangements.
- Radiation handling certification costs:France's ASN and Canada's CNSC impose overlapping compliance obligations that extend supplier qualification timelines.
- Ammonium uranyl carbonate conversion economics:Downstream processors face input cost volatility from sulfuric acid and ammonia feedstock pricing.
Strategic Opportunities
- Research institution grant cycles:Predictable procurement patterns from university and national laboratory funding streams create stable demand pockets outside nuclear fuel cycles.
- Environmental disclosure standards:Emerging radioactive material transport reporting frameworks favor suppliers with established chain-of-custody documentation systems.
- European conversion service specialization:La Hague reprocessing capabilities extension into carbonate purification creates technical differentiation in a concentrated supplier base.
Industry Challenges
- Radiation safety officer certification scarcity:Qualified personnel shortages constrain expansion timelines for conversion facilities seeking to add carbonate purification lines.
- Cross-border licensing synchronization:Divergent national nuclear authority requirements between the US, France, and Canada create compliance friction for multi-jurisdictional traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uranyl Carbonate Market |
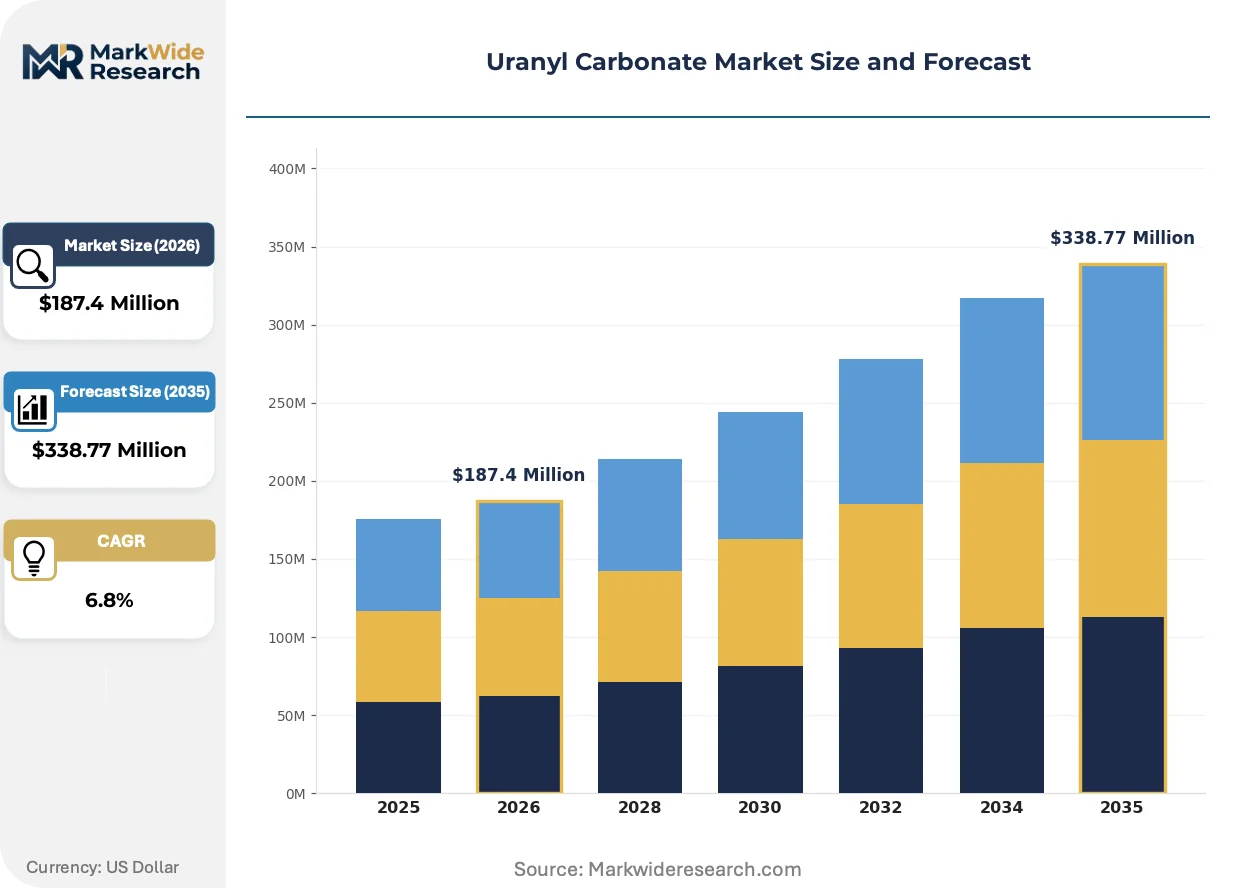
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Solutions, Crystals Application: Nuclear Energy, Chemical Reagent, Research, Radiopharmaceuticals End User: Energy Sector, Research Institutions, Pharmaceutical Companies, Nuclear Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Cameco Corporation, Kazatomprom, Orano, Energy Fuels Inc., Uranium One Inc., Paladin Energy Ltd., Ur-Energy Inc., Denison Mines Corp., American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uranyl Carbonate Market Emerging Trajectories
Digital chain-of-custody tracking and advanced purification chemistries are compressing qualification timelines while raising the technical threshold for supplier entry.
Membrane-based carbonate recovery systems are rewriting purification economics by reducing solvent extraction stages. Conversion facilities in Saskatchewan and Kazakhstan are piloting these units to shorten tolling turnaround. The technology is compressing capital requirements for mid-scale processors seeking to enter the refined uranium compound market.
France's ASN has tightened radiation worker exposure limits for uranium compound handling operations. The revised framework extends mandatory monitoring intervals and documentation retention periods. European conversion services are responding by retrofitting automated handling systems to reduce personnel contact hours.
Long-term offtake contracting is displacing spot market purchasing among nuclear fuel cycle operators. Utilities and downstream processors are locking multi-year supply agreements directly with mining jurisdictions possessing established conversion infrastructure. This pattern is most visible in Canadian and Australian supply corridors where transportation and certification costs favor volume commitments over transactional procurement.
Uranyl Carbonate Market Segmentation
Uranyl carbonate segmentation reveals how procurement priorities diverge across conversion economics, regulatory compliance burdens, and end-use purity requirements. Buyers select product formats and supply channels based on downstream process compatibility and certification timelines rather than commodity pricing alone.
Product Type:
Powder and granule buyers prioritize direct feed compatibility with ammonium uranyl carbonate conversion lines, while solution and crystal purchasers emphasize solubility control and specific surface area for specialized applications.
- Powder:Fine particulate precipitated from alkaline leach circuits delivers direct feed compatibility with downstream conversion infrastructure. Saskatchewan and Kazakh processors favor this format for tolling efficiency, though sulfuric acid cost volatility squeezes conversion margins.
- Granules:Compacted spherical particles reduce dust exposure during automated handling and improve flow characteristics in bulk transport systems. European conversion services at La Hague specify granule feedstock to minimize personnel contact hours under tightened ASN exposure protocols.
- Solutions:Aqueous carbonate complexes enable precise concentration control for research-scale synthesis and radiopharmaceutical precursor preparation.
- Crystals:Macroscopic single-crystal or polycrystalline forms serve analytical standards and specialized neutron scattering research requiring structural uniformity.
Volume sits with Powder; growth tilts toward Solutions.
Application:
Application segmentation tracks how purity specifications and regulatory pathways diverge between bulk fuel cycle consumption and specialized high-value uses.
- Nuclear Energy:Fuel cycle operators consume refined uranium compounds for conversion to uranium hexafluoride and subsequent enrichment. Canadian and Australian mining jurisdictions with established infrastructure dominate procurement through long-term offtake contracting that displaces spot purchasing.
- Radiopharmaceuticals:Cyclotron operators in North America and Europe require high-specific-activity precursors for medical isotope production. This application climbs the fastest as diagnostic imaging networks expand precursor programs.
- Chemical Reagent:Laboratory and industrial synthesis applications demand consistent stoichiometry for uranium coordination chemistry and catalysis research.
- Research:University and national laboratory grant cycles create predictable demand outside commercial fuel markets, with procurement tied to funding award timelines.
Nuclear Energy commands installed volume; Radiopharmaceuticals drives expansion.
End User:
End user categories reflect distinct procurement authority structures, from state-controlled energy entities to principal-investigator-driven academic purchasing.
- Energy Sector:State-owned utilities and independent power producers secure multi-year supply agreements directly with conversion-capable mining jurisdictions. Procurement concentrates in French and Kazakh nuclear fuel cycle operators expanding refined uranium compound sourcing.
- Nuclear Facilities:Conversion and enrichment plants specify feedstock purity thresholds that determine supplier qualification under 10 CFR Part 40, ASN, and CNSC parallel regimes.
- Research Institutions:Universities and national laboratories operate within grant-funded procurement cycles with documented chain-of-custody requirements for radioactive material handling.
- Pharmaceutical Companies:Radiopharmaceutical manufacturers seek GMP-compatible uranium compound supply for cyclotron-produced isotope precursors.
Energy Sector anchors procurement scale; Pharmaceutical Companies gain share.
Distribution Channel:
Channel selection reflects security classification, shipment size, and the complexity of cross-border licensing synchronization.
- Direct Sales:Long-term offtake agreements between mining jurisdictions and conversion facilities bypass intermediary margins. Kazakhstan's state-controlled tolling arrangements and Cameco's Saskatchewan-based supply contracts exemplify this channel's dominance for volume transactions.
- Distributors:Specialized nuclear material traders manage overlapping compliance obligations across US, French, and Canadian regulatory regimes for mid-scale processors lacking in-house licensing expertise.
- Online Retail:Research-grade quantities in exempted activity thresholds move through compliant e-commerce platforms serving university procurement offices.
- Specialty Stores:Regional suppliers with established radiation handling certification serve local research and industrial accounts requiring rapid fulfillment.
Direct Sales carries throughput; Distributors capture complexity premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Conversion-capable mining jurisdictions in Canada and Australia concentrate procurement authority for refined uranium compounds. French and Kazakh nuclear fuel cycle operators are expanding refined uranium compound sourcing through state-controlled tolling arrangements. Long-term offtake contracting is displacing spot market purchasing across all major demand centers.
Canada
Saskatchewan's uranium mining base sustains direct supply agreements with downstream processors. The Canadian Nuclear Safety Commission maintains parallel certification regimes for uranium compound handling that shape cross-border trade. Cameco Corporation leverages its Saskatchewan operations to anchor North American conversion feedstock supply.
Kazakhstan
State-controlled extraction and tolling arrangements constrain available spot market volumes. The Ministry of Energy implements export quota frameworks that directly limit international supply availability. Kazatomprom anchors Central Asian production capacity through integrated extraction and processing infrastructure.
France
Nuclear fuel cycle operators expand procurement of refined uranium compounds for conversion services. The Autorité de Sûreté Nucléaire tightened radiation worker exposure limits for uranium compound handling operations. Orano extends its La Hague reprocessing capabilities into specialized carbonate purification for European markets.
United States
Cyclotron operators in North America expand high-specific-activity precursor programs requiring refined uranyl carbonate feedstock. The Nuclear Regulatory Commission enforces source material licensing under 10 CFR Part 40 for domestic processors. Conversion facilities fragment procurement across multiple uranium compound suppliers, breaking historically integrated supply chains.
Australia
Mining jurisdictions with established conversion infrastructure scale in-situ recovery circuits that precipitate uranyl carbonate directly. The Australian Radiation Protection and Nuclear Safety Agency maintains certification requirements for radioactive material transport and handling. Paladin Energy and other operators concentrate production in jurisdictions with direct feed compatibility to ammonium uranyl carbonate conversion lines.
Uranyl Carbonate Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as utilities and downstream processors lock multi-year supply agreements directly with mining jurisdictions. The supplier base concentrates around state-controlled entities and vertically integrated mining-conversion operators. Two strategic archetypes prevail: sovereign-backed producers with captive tolling capacity, and independent miners securing direct processor relationships. Capacity expansion in carbonate purification lines and backward integration into conversion services represent the dominant competitive moves.
Among North American operators, Cameco Corporation and Energy Fuels Inc. exemplify the integrated mining-conversion archetype, while Kazatomprom represents the state-controlled production model with centralized tolling arrangements. Orano occupies a position within the European conversion specialization tier, extending reprocessing capabilities into refined compound purification. These three entities anchor the concentrated supplier base that shapes procurement patterns across nuclear fuel cycle and radiopharmaceutical demand segments.
| Leading Market Players |
|---|
| Cameco Corporation |
| Kazatomprom |
| Orano |
| Energy Fuels Inc. |
| Uranium One Inc. |
| Paladin Energy Ltd. |
| Ur-Energy Inc. |
| Denison Mines Corp. |
| American Elements |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between research-exempt quantities and fuel-cycle feedstock creates distinct procurement economics that separate spot-market spot purchases from multi-year offtake premiums. Buyers in the radiopharmaceutical segment absorb elevated unit costs for GMP-compatible documentation, while nuclear utilities leverage volume commitments to compress tolling fees at Saskatchewan and Kazakh conversion facilities.
Pricing Analysis
Volume transactions through direct sales channels sacrifice margin for throughput security, while specialty distributors capture complexity premiums for cross-border compliance management. Price differentiation rests on radiation handling certification tiers—10 CFR Part 40 licensing for US processors, ASN protocols for French operators, CNSC frameworks for Canadian facilities—rather than intrinsic material quality. Cost compression in powder-grade carbonate conversion is intensifying as sulfuric acid and ammonia input volatility squeezes processor margins. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, whereas state-backed energy utilities demonstrate lowest sensitivity through captive tolling arrangements.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale demand from French and Kazakh nuclear fuel cycle operators, while specialized distributors manage mid-scale procurement for North American cyclotron networks. Geographic supply concentration centers on Canada, Kazakhstan, and Australia, with Saskatchewan and Central Asian mining jurisdictions anchoring extraction capacity. Raw material dependencies include sulfuric acid for leach circuits, ammonia for ammonium uranyl carbonate conversion, and specialized membrane systems for purification stage efficiency. Single-source vulnerability pervades the supplier base, as state-controlled tolling arrangements and vertically integrated mining-conversion operators limit alternative sourcing pathways. Distribution runs through long-term offtake agreements that displace spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints from radiation safety officer certification scarcity prop pricing premiums across carbonate purification capacity. Expansion timelines for conversion facilities face qualified personnel bottlenecks that reinforce incumbent positioning.
For Market Incumbents: Cement long-term offtake relationships with radiopharmaceutical cyclotron operators before membrane-based recovery systems democratize purification technology. Extend La Hague-style reprocessing capabilities into specialized carbonate streams to defend against emerging European conversion entrants. Prioritize automated handling retrofits that reduce personnel contact hours under tightened ASN exposure protocols. For New Entrants and Emerging Players: E-commerce platforms serving research-grade exempted quantities offer the most penetrable entry vector for university procurement offices seeking rapid fulfillment. Target radiopharmaceutical precursor programs in North American cyclotron networks where GMP-compatible supply remains concentrated among established distributors. Pursue tolling partnerships with mid-scale Canadian processors lacking in-house carbonate purification lines. For Investors and Strategic Acquirers: Re-rating potential sits with conversion-capable mining operators given membrane technology compression of capital requirements for purification stage entry. Five-to-ten year viability favors entities with backward integration into Saskatchewan or Central Asian extraction infrastructure. Monitor Kazakhstan's Ministry of Energy export quota adjustments as the primary inflection signal for spot market availability.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane System Deployment | Purification stage compression reduces solvent extraction costs at Saskatchewan conversion facilities. |
| Automated Handling Retrofit | Personnel contact reduction aligns with ASN tightened exposure limits for European operators. |
| Long-term Supply Agreement | Volume commitments displace spot purchasing among French nuclear fuel cycle utilities. |
| GMP Documentation Investment | Cyclotron operator qualification enables radiopharmaceutical precursor market penetration. |
| Radiation Safety Certification Pipeline | Qualified officer scarcity constrains competitor expansion timelines across purification capacity. |
Methodological Framework
Document review covered regulatory filings from the US Nuclear Regulatory Commission, ASN, and CNSC, complemented by interviews with conversion facility procurement managers, cyclotron operator supply chain leads, and university radiation safety officers. Secondary validation drew from customs trade data, uranium market price reporting services, and national laboratory procurement databases. Bottom-up demand modeling across radiopharmaceutical, nuclear energy, and research application segments was triangulated against top-down supply capacity assessments from mining jurisdiction production disclosures.
Historical volume trajectories were cross-referenced against expert panel inputs from fuel cycle operators and tolling facility managers. The analytical framework segmented demand by product format, application purity requirements, end-user procurement authority structures, and distribution channel complexity across the projection horizon. CAGRs were derived from installed conversion capacity expansion schedules, grant funding cycle patterns for research institutions, and cyclotron network buildout timelines for medical isotope production.
The model holds under stable regulatory licensing pathways; deviation in export quota enforcement, radiation worker exposure limit revisions, or membrane technology adoption curves would shift capacity utilization assumptions. Forecasts reflect documented base conditions for sulfuric acid and ammonia input cost structures, tolling arrangement renewal patterns, and cross-border certification synchronization efficiency. Periodic stress-testing of base assumptions against Kazakhstan Ministry of Energy policy announcements and ASN protocol amendments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Glyoxal Market
Chemicals
Coagulant Market
Chemicals
Coal Tar Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Aluminum Chemicals Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Phenothiazine Market
Chemicals
Methylamines Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Triethanolamine Market
Chemicals
Barbituric Acid Market
Chemicals
Chlorosilane Market
Chemicals
Antiozonant Market