
 Methyldiisopropanolamine Market | 2026-2036
Methyldiisopropanolamine Market Size, Share, and Industry Trends Forecast 2026-2036
Methyldiisopropanolamine Market Analytics
Technical service contracts for formulation support and custom blending is restructuring how methyldiisopropanolamine suppliers capture value downstream. Huntsman Corporation leverages its integrated amine production network to sustain cost advantages across specialty surfactant supply chains. BASF SE anchors European demand through controlled distribution of high-purity grades to pharmaceutical and coatings manufacturers. Dow Chemical Company competes on manufacturing scale in North American industrial markets.
Methyldiisopropanolamine is a tertiary alkanolamine with the molecular formula C7H17NO2, manufactured through the reaction of methylamine with propylene oxide and valued for its emulsifying, neutralizing, and pH-buffering properties in surfactant systems. The liquid form dominates commercial transactions due to ease of handling in continuous-process manufacturing, while powder and gel variants occupy niche positions in personal care formulations requiring controlled release. Industrial grade material leads volume consumption across coatings and adhesives applications, though pharmaceutical grade commands premium positioning as regulatory scrutiny intensifies.
REACH registration requirements in the European Union, EPA chemical substance evaluations in the United States, and China's GB standards administered by SAMR collectively elevate compliance costs for cross-border suppliers. These frameworks shape product specifications, testing protocols, and market access timelines for new entrants. Stakeholders must monitor evolving purity mandates and regional notification requirements to align capacity investments with compliant output.
Market Dynamics
REACH compliance deadlines and China's evolving GB standards are compressing formulation timelines for methyldiisopropanolamine suppliers, forcing simultaneous purity upgrades across multiple production sites while specialty chemical buyers consolidate vendor lists.
Growth Catalysts
- Coatings sector expansion:Industrial coatings manufacturers in India and Vietnam are scaling waterborne formulation capacity, pulling methyldiisopropanolamine demand for pH control and emulsification in high-solids systems.
- REACH registration maturity:Completed substance dossiers under ECHA guidelines have streamlined market access for compliant EU suppliers, reducing competitive friction from unregistered imports.
- Propylene oxide supply diversification:New merchant capacity in the Middle East is easing feedstock concentration risk, improving cost predictability for tertiary alkanolamine producers.
Market Restraints
- Methylamine price volatility:Ammonia and methanol cost swings transmit directly into methyldiisopropanolamine production economics, compressing margin stability for non-integrated manufacturers.
- Pharmaceutical-grade purity thresholds:SAMR's tightening impurity limits under revised GB standards extend batch testing cycles and disqualify legacy production assets from high-margin segments.
- MEA and DEA substitution:Primary and secondary alkanolamines retain cost advantages in basic neutralization applications, capping methyldiisopropanolamine penetration in commodity surfactant markets.
Strategic Opportunities
- Personal care grade white space:Controlled-release gel formulations for premium skincare in South Korea and Japan offer premium positioning beyond standard liquid grades.
- Carbon capture solvent adaptation:Tertiary alkanolamine chemistry is converging with post-combustion capture process development, opening pilot-scale offtake from power sector engineering firms.
- Direct technical service models:Custom blending and formulation support contracts bypass traditional distributor margins, capturing value from mid-sized coatings compounders in Poland and Czechia.
Industry Challenges
- Cross-functional regulatory expertise:Simultaneous compliance with REACH, EPA TSCA, and SAMR notification requirements demands specialized toxicology and dossier management capabilities that outpace generalist chemical regulatory staffing.
- Legacy asset retrofit costs:Pharmaceutical-grade purification investments for existing propylene oxide addition reactors require capital deployment that conflicts with short-cycle specialty chemical return benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyldiisopropanolamine Market |
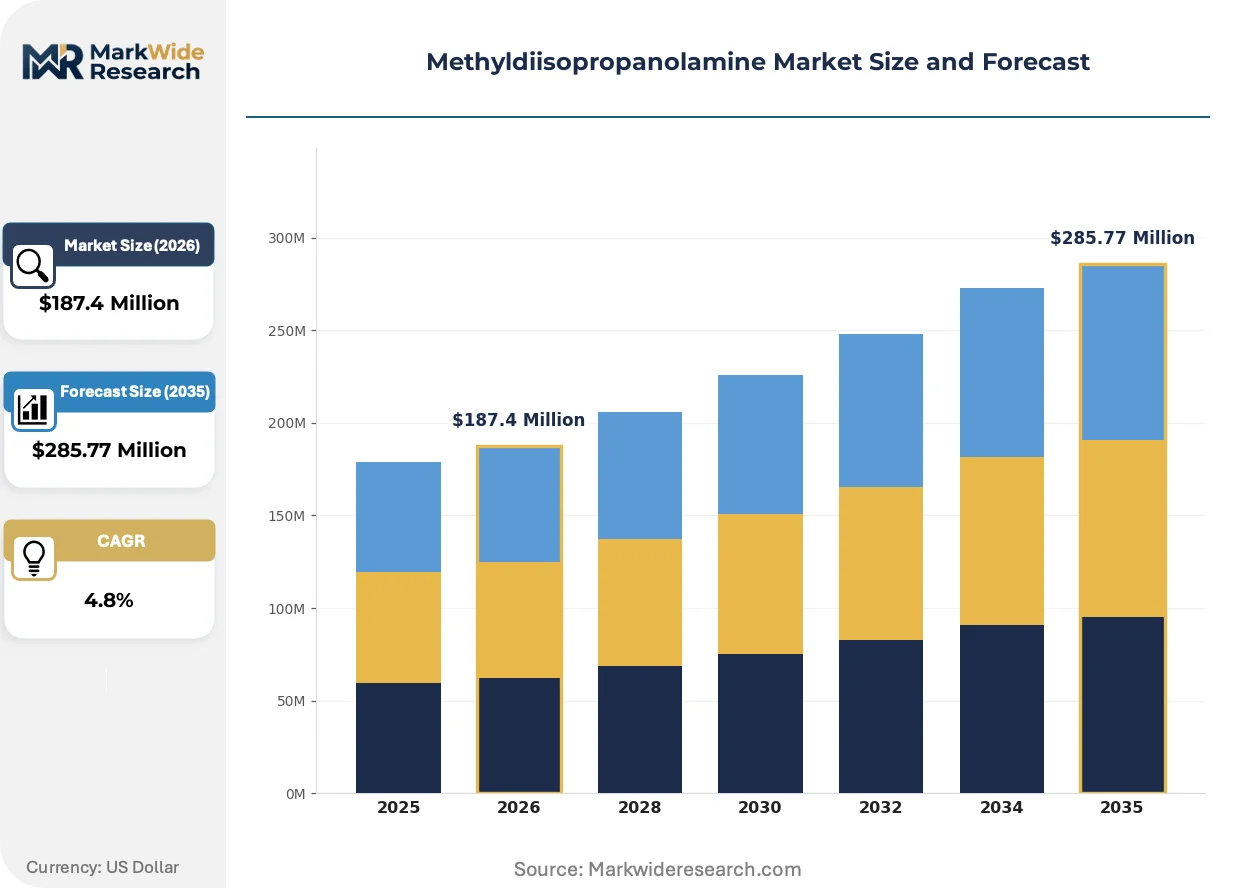
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Personal Care, Coatings, Adhesives, Textile Form: Liquid, Powder, Paste, Gel End User: Manufacturers, Distributors, Retailers, Enterprises Grade: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Specialty Grade |
| Companies Covered | Huntsman Corporation, Aurora Fine Chemicals, BASF SE, HangZhou Yuhao Chemical Technology, Jigs Chemical, Dow Chemical Company, LANXESS, Akos GmbH, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyldiisopropanolamine Market Evolving Landscape
Continuous-process manufacturing upgrades and digital quality control systems are compressing batch-to-batch variability, enabling real-time specification adjustments that align output with tightening pharmaceutical-grade mandates.
Membrane filtration technology for residual amine removal is consolidating quality assurance workflows for high-purity methyldiisopropanolamine production. Specialty surfactant manufacturers in Germany and Switzerland are adopting in-line filtration to replace offline distillation cycles. This consolidation is reducing testing lead times from days to hours, compressing working capital requirements for certified grade inventory.
REACH authorization list expansions under ECHA review are redirecting formulation R&D toward alternative neutralizing agents with favorable toxicological profiles. Coatings compounders are preemptively reformulating to exclude substances under regulatory scrutiny. The adhesives segment in France and Italy is most affected, with technical service teams accelerating substitution timelines ahead of sunset date announcements.
Consolidated procurement through integrated chemical distributors is displacing fragmented spot purchasing for industrial-grade material. Large coatings manufacturers in India are mandating vendor-managed inventory programs with monthly consumption guarantees. This concentration is most visible in the Mumbai-Pune industrial corridor, where compounders are reducing qualified supplier lists from twelve to three core partners.
Methyldiisopropanolamine Market Segmentation
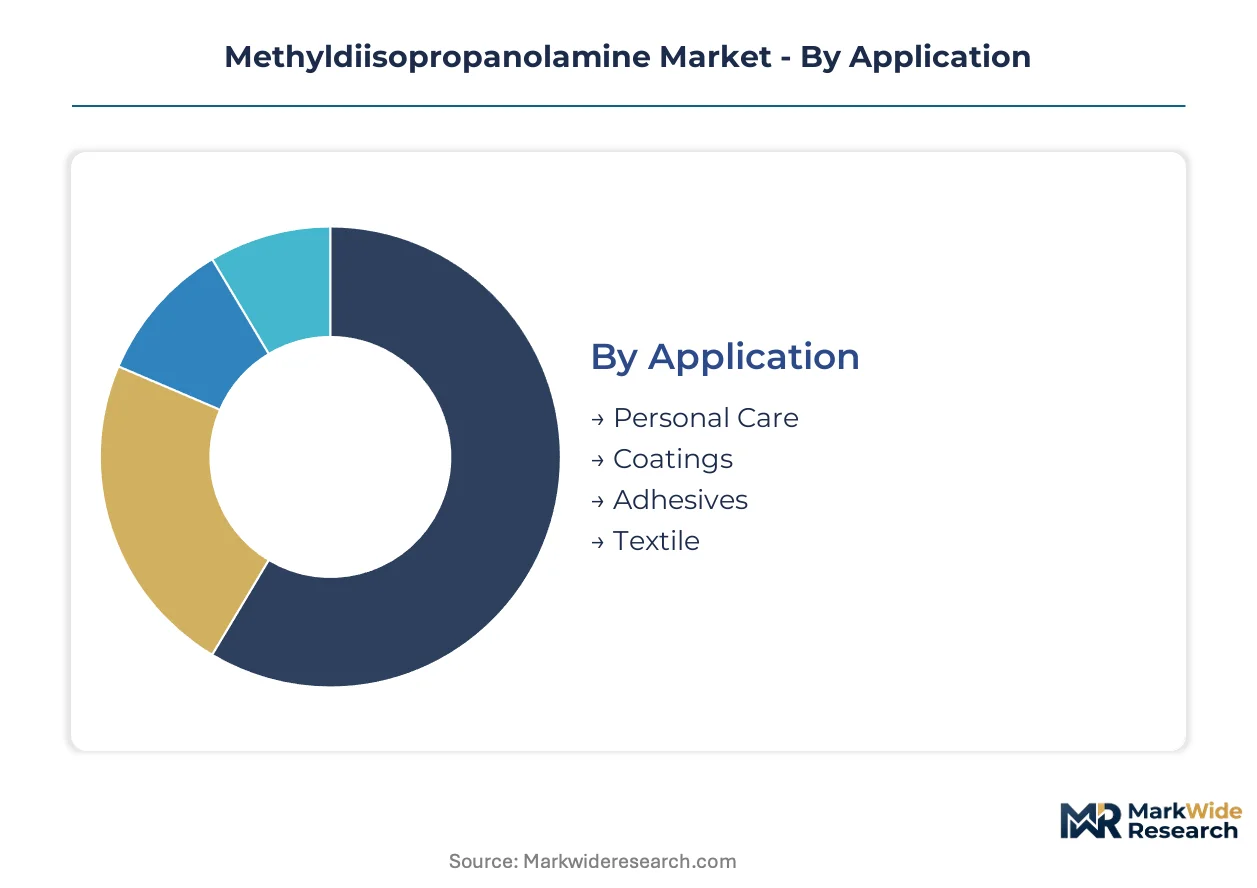
Methyldiisopropanolamine serves distinct performance requirements across personal care emulsification and industrial pH control. Segmentation reveals how purity thresholds, handling properties, and procurement models reshape supplier-buyer relationships.
Application:
Buyers differentiate by formulation complexity and regulatory exposure in their end markets.
- Personal Care:Tertiary alkanolamine chemistry enables mild neutralization in premium skincare and haircare formulations. South Korean and Japanese cosmetics manufacturers specify low-odor, low-color grades for sensitive-skin product lines.
- Coatings:Waterborne industrial coatings in India and Vietnam leverage methyldiisopropanolamine for pH buffering in high-solids acrylic and polyurethane systems. Demand concentrates where VOC regulations are tightening fastest.
- Adhesives:Pressure-sensitive and structural adhesive compounders in France and Italy use the amine for controlled neutralization of tackifier resins.
- Textile:Fiber processing and dye-fixing applications in Bangladesh and Vietnam industrial zones employ industrial-grade material for pH adjustment in continuous dyeing lines.
Volume sits with Coatings; growth tilts toward Personal Care.
Form:
Handling economics and process integration determine procurement preferences across manufacturing setups.
- Liquid:Dominates commercial transactions due to pumpable handling in continuous-process reactors and bulk storage compatibility. German coatings manufacturers specify ISO-tank delivery for just-in-time formulation lines.
- Powder:Solid-state stability supports dry-blend surfactant premixes and powder detergent formulations. Southeast Asian toll manufacturers favor this form for containerized export logistics.
- Paste:Intermediate viscosity suits small-batch cosmetic compounding where metering precision matters more than throughput speed.
- Gel:Controlled-release properties enable premium skincare applications in South Korea where sustained active delivery commands formulation premiums.
Throughput favors Liquid; margin expansion concentrates in Gel.
End User:
Procurement scale and technical service requirements split the buyer base into distinct contracting patterns.
- Manufacturers:Integrated surfactant and coatings producers in Germany and China negotiate direct supply agreements with volume commitments and technical service riders.
- Distributors:Pan-European chemical distributors consolidate fragmented industrial-grade demand from mid-sized compounders in Poland and Czechia, capturing value through inventory pooling.
- Retailers:Specialty chemical retailers serve small-scale personal care formulators and research laboratories with packaged quantities and certificate-of-analysis documentation.
- Enterprises:Multinational coatings and adhesives corporations centralize procurement through global supply agreements with qualified supplier lists reduced to three core partners.
Transaction volume concentrates with Manufacturers; contract complexity expands fastest among Enterprises.
Grade:
Purity specifications and certification requirements create tiered pricing structures that filter market access.
- Industrial Grade:Standard purity suffices for coatings, adhesives, and textile processing where functional performance outweighs trace impurity constraints. Indian and Vietnamese industrial clusters absorb the largest volumes.
- Pharmaceutical Grade:Tightened impurity limits under SAMR's revised GB standards and REACH registration requirements elevate testing protocols. German and Swiss pharmaceutical excipient manufacturers qualify suppliers through extended audit cycles.
- Cosmetic Grade:Intermediate purity with enhanced color and odor specifications serves premium personal care formulators in Japan and South Korea seeking regulatory pre-approval for export markets.
- Specialty Grade:Custom-specified variants for carbon capture solvent pilots and niche surfactant R&D command project-based pricing from engineering firms and research consortia.
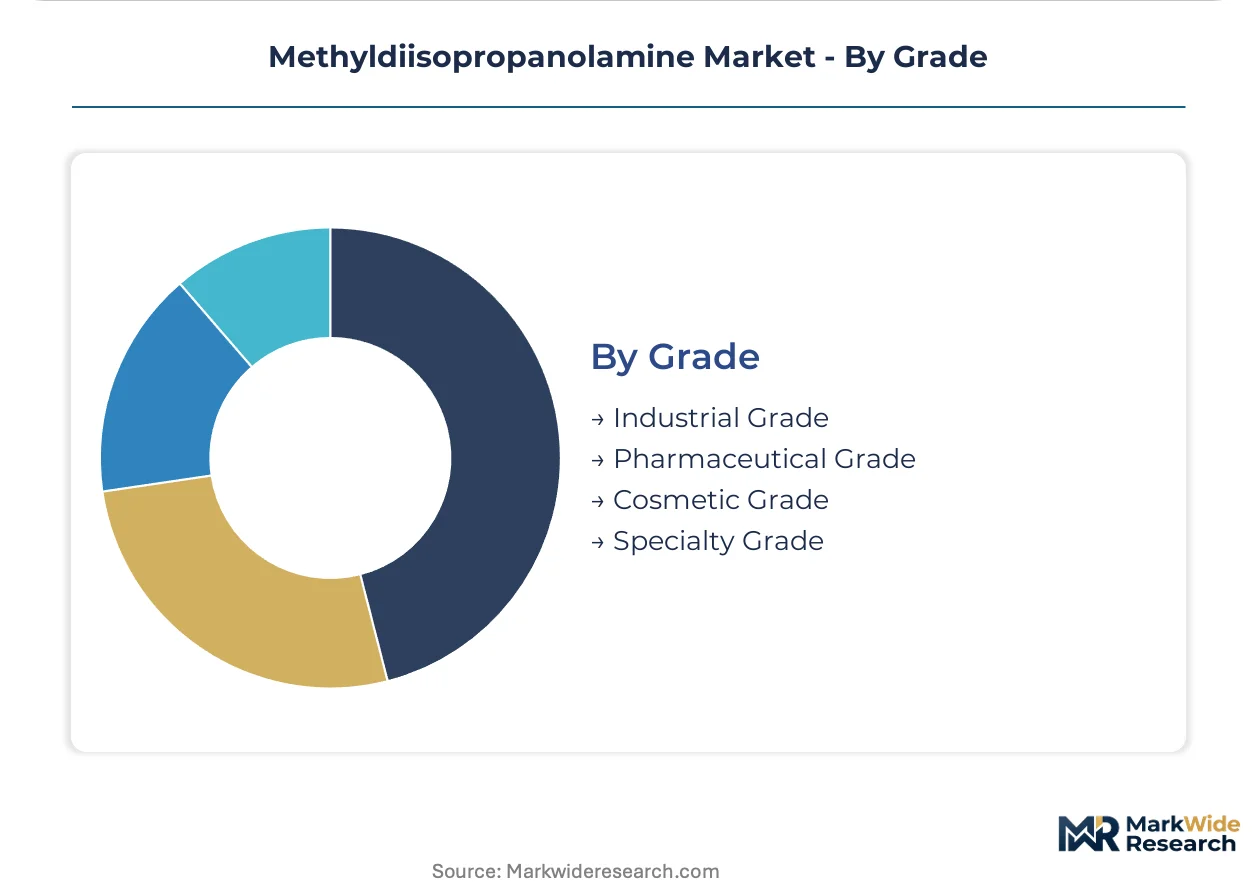
Industrial Grade anchors volume; Pharmaceutical Grade claims the steepest expansion trajectory as regulatory thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and China while consumption gravity shifts toward industrial clusters in India and Vietnam. This geographic split creates arbitrage opportunities for integrated suppliers with cross-border logistics capabilities. Regulatory divergence between REACH-compliant European markets and China's evolving GB standards compounds complexity for multinational procurement strategies.
Germany
Pharmaceutical-grade demand from Swiss and domestic excipient manufacturers pulls high-purity material through BASF SE's controlled distribution network. ECHA REACH registration requirements filter market access, disqualifying unregistered third-country imports from premium segments. The Ludwigshafen chemical complex anchors tertiary alkanolamine production with backward integration into captive propylene oxide supply.
China
HangZhou Yuhao Chemical Technology and domestic specialty manufacturers scale pharmaceutical-grade output as SAMR tightens impurity limits under revised GB standards. The Yangtze River Delta coatings cluster absorbs industrial-grade volumes for waterborne acrylic systems. Dual carbon goals from MEE accelerate process efficiency investments at legacy propylene oxide addition reactors.
India
Waterborne coatings expansion in the Mumbai-Pune industrial corridor drives pH control chemical consumption from consolidated three-partner supplier lists. BIS certification requirements for imported chemical intermediates extend qualification timelines for new vendors. Gujarat-based surfactant compounders negotiate vendor-managed inventory programs with monthly volume guarantees.
United States
Dow Chemical Company's manufacturing scale serves North American industrial markets with ISO-tank delivery infrastructure for just-in-time coatings lines. EPA TSCA chemical substance evaluations elevate compliance documentation burdens for cross-border shipments. The Gulf Coast petrochemical corridor provides feedstock cost advantages through proximity to merchant methylamine and propylene oxide supply.
Vietnam
Textile processing clusters in Ho Chi Minh City and Binh Duong province employ industrial-grade material for continuous dyeing line pH adjustment. Rapid waterborne coatings capacity expansion pulls tertiary alkanolamine imports through consolidated distributor networks. Local compounders lack pharmaceutical-grade purification assets, creating import dependency for certified cosmetic applications.
Methyldiisopropanolamine Market Competitive Landscape
Capital-heavy integrated producers compete with asset-light specialty distributors for formulation value capture. The market structure tilts toward consolidation as REACH compliance costs and pharmaceutical-grade purity investments filter marginal participants. Three archetypes dominate: integrated petrochemical majors with captive feedstock, regional specialty distributors with technical service capabilities, and toll manufacturers serving niche personal care grades. Competitive moves center on backward integration into propylene oxide supply and direct technical service contracting that bypasses traditional distributor margins.
Among integrated petrochemical majors, Huntsman Corporation, BASF SE, and Dow Chemical Company occupy positions that exemplify scale-driven and geography-anchored competitive strategies. Huntsman leverages its amine production network across multiple sites. BASF SE anchors European pharmaceutical-grade positioning through controlled distribution. Dow Chemical Company represents North American manufacturing scale with Gulf Coast feedstock access. These three names from the raw data illustrate how feedstock integration and regulatory compliance capabilities separate tier-one suppliers from fragmented regional competitors.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Aurora Fine Chemicals |
| BASF SE |
| HangZhou Yuhao Chemical Technology |
| Jigs Chemical |
| Dow Chemical Company |
| LANXESS |
| Akos GmbH |
| Eastman Chemical Company |
| Others |
Value Network & Pricing Analysis
Large coatings manufacturers in India and Vietnam anchor procurement through vendor-managed inventory programs, forcing contract-based long-term offtake pricing with monthly volume guarantees rather than spot-market flexibility.
Pricing Analysis
Cost compression in pharmaceutical-grade tiers accelerates because SAMR's tightening impurity limits under revised GB standards extend batch testing cycles and disqualify legacy assets. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates certified excipient manufacturers from commodity coatings compounders. Pricing pressure intensifies in industrial-grade segments as methylamine and propylene oxide cost swings transmit directly into production economics. Coatings manufacturers in India demonstrate highest price sensitivity through consolidated three-partner supplier lists, while Swiss pharmaceutical excipient buyers accept premium positioning for REACH-registered material.
Supply Chain Analysis
Chemical engineering talent shortages in Germany and the US Gulf Coast constrain continuous-process manufacturing upgrades at legacy propylene oxide addition reactors. Supply concentrates in China, Germany, and the United States, with the Yangtze River Delta and Ludwigshafen chemical complex anchoring tertiary alkanolamine output. Feedstock dependencies center on merchant methylamine, propylene oxide, and ammonia sourced from integrated petrochemical corridors. Single-source vulnerability persists for pharmaceutical-grade purification assets in Europe, where ECHA REACH registration filters market access. Distribution runs through integrated chemical distributors in Europe, direct technical service contracts in North America, and consolidated distributor networks in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH compliance costs and pharmaceutical-grade purity investments that filter marginal participants lacking integrated feedstock positions.
For Market Incumbents: Acquire captive propylene oxide supply assets to insulate margin stability from merchant feedstock volatility. BASF SE's controlled distribution model in Europe exemplifies channel control that locks out unregistered imports. Huntsman Corporation's multi-site amine production network demonstrates how backward integration defends against methylamine price swings. Prioritize membrane filtration technology investments to compress batch-to-batch variability for SAMR-compliant output. For New Entrants and Emerging Players: Technical service distributors in Poland and Czechia represent the most accessible channel partners for bypassing established supplier lists. White-space concentrates in personal care gel formulations for South Korean premium skincare, where controlled-release properties command formulation premiums. Carbon capture solvent pilots offer project-based entry without competing on industrial-grade volume scale. Direct formulation support contracts with mid-sized coatings compounders capture value that traditional distributors currently extract. For Investors and Strategic Acquirers: The window for entry favors asset-light specialty distributors with technical service capabilities over capital-heavy production builds. Long-term viability hinges on regulatory compliance infrastructure that outpaces generalist chemical staffing. Target acquisition archetypes include regional distributors with established SAMR audit relationships and toll manufacturers serving niche cosmetic grades. Watch ECHA authorization list expansions as the inflection signal for substitution-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Huntsman Corporation's captive feedstock insulates margin stability from merchant price volatility. |
| Membrane Filtration Technology Deployment | German and Swiss manufacturers compress testing lead times from days to hours for SAMR compliance. |
| Direct Technical Service Contracting | Bypassing distributor margins captures value from mid-sized coatings compounders in Poland and Czechia. |
| Pharmaceutical-Grade Certification Investment | REACH registration and SAMR audit cycles filter unregistered competitors from premium segments. |
| Carbon Capture Solvent Pilot Partnerships | Post-combustion capture process development opens pilot-scale offtake from power sector engineering firms. |
Research Methodology
Independent corroboration across primary interviews with plant managers, procurement leads at coatings manufacturers, distribution channel partners, and technical R&D directors, combined with secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings, underwrites the qualitative findings. Bottom-up demand modeling across application segments and top-down supply validation from production capacity disclosures enable triangulation of market size estimates.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by grade tier, end-use industry, form factor, and regional production hub. CAGRs derive from regression analysis of historical consumption patterns against forecast inputs including coatings sector capacity expansion timelines, REACH authorization list review schedules, and propylene oxide supply diversification milestones. Segment-specific growth differentials reflect pharmaceutical-grade purity threshold tightening and waterborne formulation adoption curves.
Several conditions sit outside the modeled scope, including unannounced regulatory sunset dates, force majeure disruptions in propylene oxide supply corridors, and abrupt reformulation shifts away from tertiary alkanolamine chemistry. Forecasts reflect documented assumptions about continued methylamine supply availability and stable trade policy environments. Material deviation in SAMR enforcement intensity or ECHA authorization timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
China Methanol Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Ferric Oxide Market
Chemicals
Desalination Chemicals Market
Chemicals
Ammonia Market
Chemicals
Methanol to Gasoline Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
1, 4 Butanediol Market
Chemicals
India Methanol Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Formalin Vials Market