
 Tanning Agents Market | 2026-2036
Tanning Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Tanning Agents Market Outlook
India is tilting toward expanded vegetable tannin extraction capacity to serve footwear export demand. LANXESS sustains synthetic tannin leadership through backward integration into phenolic chemistry. Silvateam anchors Mediterranean supply with chestnut and quebracho extract dominance. BASF SE competes on aldehyde tanning systems for automotive-grade leather.
Tanning agents are chemical compounds that permanently alter collagen structure in animal hides, with vegetable tannins typically comprising 30-70% polyphenolic content by dry weight and synthetic variants using sulfonated phenol-formaldehyde condensates to achieve uniform penetration rates. Their primary purpose is to convert perishable raw hides into durable, flexible leather resistant to microbial decay and thermal degradation. Synthetic tannins command the largest volume share due to consistent batch performance and shorter processing cycles, while vegetable tannins retain premium positioning in saddlery and luxury goods where patina development matters. Powder formulations lead industrial uptake for storage stability and precise dosing, though liquid concentrates gain share in continuous-processing tanneries.
REACH regulates chromium(VI) limits in finished leather at 3 mg/kg, forcing tanneries toward zirconium, titanium, and vegetable alternatives. ECHA's restriction proposals on glutaraldehyde are reshaping aldehyde tannin R&D priorities. BIS certification requirements for leather chemicals in India affect export market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence between EU hazard-based frameworks and India's process-standard approach when allocating formulation development budgets.
Market Dynamics
REACH's chromium(VI) limit of 3 mg/kg in finished leather is forcing a wholesale reformulation pivot across European tanneries, compressing chrome-tanning's dominance while accelerating zirconium, titanium, and vegetable tannin substitution curves.
Growth Catalysts
- Automotive Interior Mandates:OEM specifications for chrome-free leather upholstery are pulling synthetic and aldehyde tanning systems into high-volume production lines.
- REACH Restriction Cascade:The 3 mg/kg chromium(VI) ceiling in finished leather is redirecting formulation R&D budgets toward compliant alternatives.
- Quebracho Extraction Expansion:Mediterranean chestnut and South American quebracho extract capacity is scaling to serve footwear export demand from Italian and Indian clusters.
Market Restraints
- Phenolic Input Volatility:Synthetic tannin production depends on sulfonated phenol-formaldehyde condensates exposed to petrochemical price swings.
- Arzignano Supply Concentration:Italy's Veneto tanning cluster controls disproportionate vegetable tannin refining capacity, creating geographic chokepoint risk.
- Glutaraldehyde Regulatory Friction:ECHA restriction proposals on aldehyde-based agents are compressing R&D timelines for automotive-grade leather applications.
Strategic Opportunities
- Indian Footwear Export Corridor:Vegetable tannin extraction capacity expansion in Tamil Nadu and Uttar Pradesh can capture share of EU-bound finished leather demand.
- Biobased Synthetics Convergence:Phenolic chemistry from lignin feedstocks is converging with conventional synthetic tannin production routes.
- PLI Scheme Tailwinds:India's production-linked incentive scheme for leather chemicals is lowering capital barriers for domestic formulation scale-up.
Industry Challenges
- Collagen Chemistry Expertise Gap:Tanneries lack sufficient technicians trained in zirconium and titanium tanning kinetics versus legacy chrome processes.
- BIS Certification Timelines:India's Bureau of Indian Standards approval cycles for new leather chemical formulations delay export market access by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanning Agents Market |
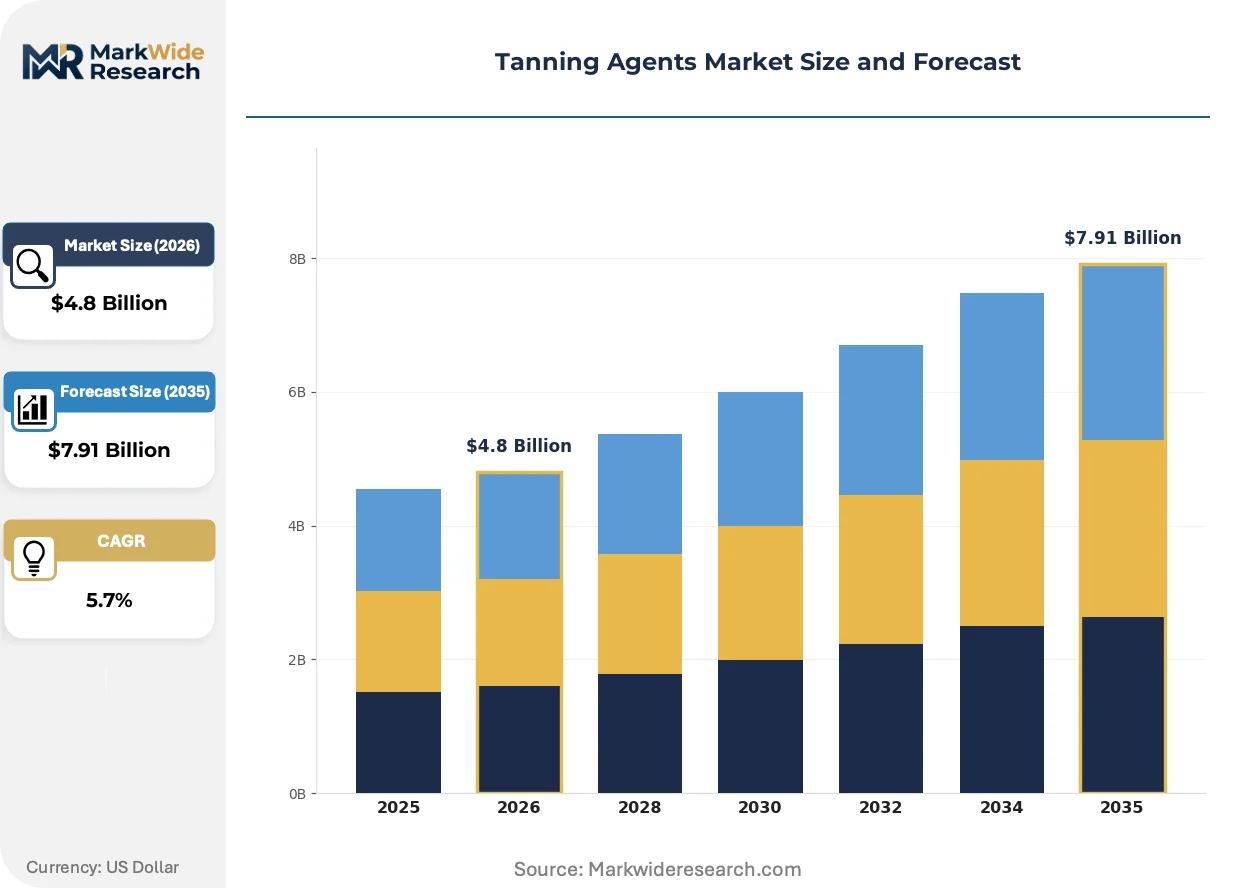
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Tannins, Synthetic Tannins, Mineral Tannins, Aldehyde Tannins Application: Leather Goods, Footwear, Upholstery, Automotive Interiors End User: Textile Industry, Automotive Sector, Furniture Manufacturers, Aerospace Form: Liquid, Powder, Granule, Paste |
| Companies Covered | Chemtan Company, Merck KGaA, LANXESS, Silvateam, SCHILL+SEILACHER GMBH, BASF SE, ANGUS Chemical Company, TRUMPLER GmbH & Co. KG, Clariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanning Agents Market Strategic Shifts
Digital process control systems and biobased feedstock substitution are compressing traditional tanning cycles while rewriting compliance architectures across European and Asian production bases.
Enzymatic bating and degreasing systems are virtualizing conventional lime-sulfide processing sequences in continuous-processing tanneries. Italian and Spanish mid-cap tanneries are adopting these systems at accelerating rates to meet wastewater discharge limits. This virtualization is compressing chemical inventory requirements and enabling real-time bath chemistry adjustment through sensor feedback loops.
ECHA's proposed glutaraldehyde restrictions are forcing aldehyde tannin suppliers to validate glyoxal and oxazolidine alternatives for automotive interior certification. The industrial consequence is a bifurcation between premium automotive-grade formulations and commodity leather applications. Italian automotive leather suppliers are responding by accelerating zirconium-titanium hybrid system qualification with German OEM technical centers.
Specification-driven procurement is consolidating tannery supplier panels around REACH-compliant, ISO-certified chemical houses with dedicated technical service teams. Small-batch Italian luxury goods tanneries are displacing spot-market chemical purchasing with multi-year formulation partnership contracts. This consolidation is most visible in Veneto and Tuscany, where patina-critical applications demand consistent batch-to-batch vegetable tannin performance.
Tanning Agents Market Segmentation
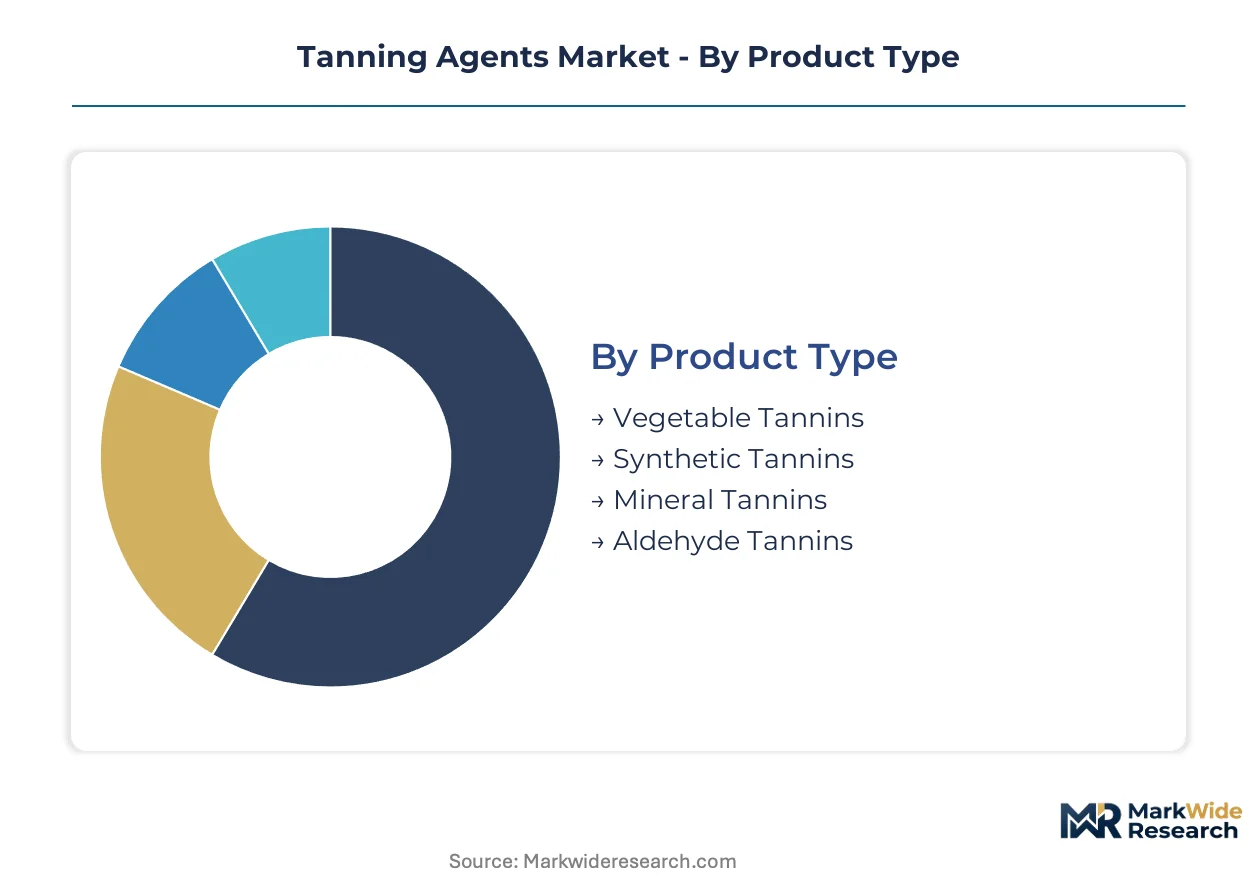
Tanning agent selection hinges on collagen modification kinetics, end-use durability requirements, and regulatory compliance thresholds. Formulation choices cascade through supply chain configurations, from Arzignano's vegetable tannin refineries to Tamil Nadu's synthetic production lines.
Product Type:
Cost tier stratification separates legacy mineral systems from premium vegetable extracts and mid-market synthetic alternatives.
- Vegetable Tannins:Polyphenolic extracts from chestnut, quebracho, and mimosa bark comprise 30-70% tannin content by dry weight. Italian luxury saddlery and patina-critical leather goods in Tuscany drive specification. REACH chromium(VI) restrictions are accelerating substitution from chrome-tanned substrates.
- Synthetic Tannins:Sulfonated phenol-formaldehyde condensates deliver uniform penetration rates and shortened processing cycles. High-volume automotive upholstery lines in Germany and continuous-processing tanneries in India's Kanpur cluster specify these for batch consistency.
- Mineral Tannins:Chromium(III) salts historically dominated volume, though ECHA's 3 mg/kg chromium(VI) ceiling in finished leather is compressing share. Basque Country tanneries retain chrome systems for specific heavy leather applications.
- Aldehyde Tannins:Glutaraldehyde and emerging glyoxal variants serve automotive-grade leather requiring chrome-free certification. ECHA restriction proposals on glutaraldehyde are compressing R&D timelines for alternative oxazolidine systems.
Synthetic tannins command the established base. The steepest expansion runs through vegetable tannin alternatives.
Application:
Application segmentation tracks durability specifications, aesthetic requirements, and automotive OEM compliance mandates across end-use categories.
- Leather Goods:Handbags, wallets, and small accessories demand vegetable-tanned substrates for patina development and natural aging characteristics. Italian artisan tanneries in Florence and Milan anchor demand for chestnut-extract formulations.
- Footwear:Athletic and formal shoe leather requires consistent flex resistance and color fastness. Tamil Nadu and Uttar Pradesh tanning clusters in India are scaling vegetable tannin extraction to serve EU-bound export demand.
- Upholstery:Residential and commercial furniture leather balances cost with abrasion resistance. Powder-form synthetic tannins dominate for storage stability and precise dosing in batch processing.
- Automotive Interiors:OEM specifications mandate chrome-free leather upholstery across German, Italian, and US vehicle programs. Zirconium-titanium hybrid systems are qualifying with technical centers in Stuttgart and Munich.
Footwear applications hold the volume base. Automotive interiors are climbing the fastest on specification-driven reformulation.
End User:
Customer type segmentation reflects divergent procurement patterns between specification-driven OEMs and cost-optimized commodity buyers.
- Textile Industry:Leather apparel and accessory manufacturers source tanning agents through chemical distributors with technical service support.
- Automotive Sector:Tier-1 seating suppliers and OEM direct sourcing teams enforce REACH compliance, ISO certification, and dedicated formulation partnerships.
- Furniture Manufacturers:Residential upholstery producers prioritize powder formulations for inventory stability and dosing precision.
- Aerospace:Aircraft seating and interior panel applications demand fire-retardant leather substrates with traceable chemical certification.
Automotive sector procurement commands premium positioning. Textile industry uptake represents the broadest volume foundation.
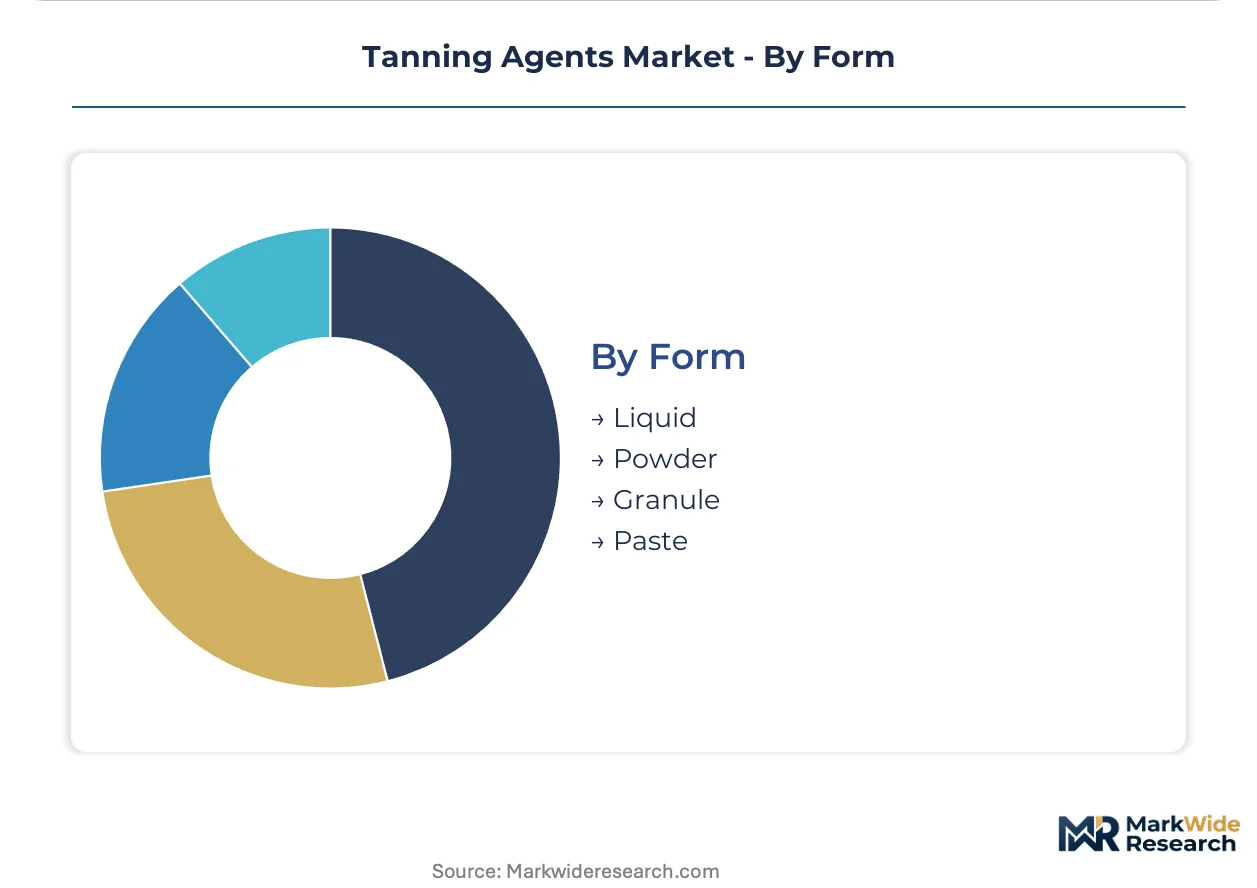
Form:
Physical form selection maps to processing infrastructure, from continuous liquid dosing systems to batch powder handling.
- Liquid:Concentrates enable real-time bath chemistry adjustment through sensor feedback loops in continuous-processing tanneries.
- Powder:Dominates industrial uptake for storage stability, extended shelf life, and precise gravimetric dosing in batch operations.
- Granule:Reduced dust generation improves handling safety in high-volume tanneries with mechanical mixing equipment.
- Paste:Pre-dispersed formulations eliminate dissolution steps for small-batch luxury goods producers.
Powder formulations anchor the installed base. Liquid concentrates are gaining share fastest in continuous-processing installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arzignano's Veneto tanning cluster refines disproportionate vegetable tannin capacity, while India's Kanpur and Tamil Nadu belts scale synthetic production for footwear export corridors. REACH chromium(VI) ceilings and BIS certification requirements are diverging regulatory compliance architectures across these production bases.
Italy
Luxury leather goods and automotive upholstery specifications drive vegetable tannin demand from Tuscan patina-critical tanneries. REACH's 3 mg/kg chromium(VI) limit redirects formulation strategies toward zirconium-titanium hybrid systems. Arzignano's Veneto cluster concentrates chestnut and quebracho extract refining capacity for saddlery and premium goods.
Germany
OEM technical centers in Stuttgart and Munich qualify chrome-free leather for vehicle interior programs. ECHA restriction proposals on glutaraldehyde compress R&D timelines for aldehyde tanning alternatives. BASF SE anchors aldehyde system supply from Ludwigshafen for automotive-grade certification.
India
Tamil Nadu and Uttar Pradesh clusters expand vegetable tannin extraction to serve EU-bound footwear leather demand. BIS certification requirements for leather chemicals delay export market access by 12-18 months for non-compliant suppliers. The PLI scheme for leather chemicals lowers capital barriers for domestic formulation scale-up in Kanpur.
United States
Automotive seating suppliers enforce chrome-free specifications across German, Italian, and US vehicle programs. EPA and OSHA frameworks govern phenolic chemical handling in synthetic tannin production. Michigan and Ohio-based Tier-1 suppliers consolidate procurement around REACH-compliant chemical houses.
Spain
Mid-cap tanneries in Catalonia and the Basque Country adopt enzymatic bating systems to meet wastewater discharge limits. ECHA glutaraldehyde proposals force validation of glyoxal alternatives for automotive applications. Spanish tanneries retain chrome systems for specific heavy leather segments despite REACH compression.
Tanning Agents Market Competitive Environment
Backward-integrated chemical majors and regional extractive specialists split the market between consistent batch performance and polyphenolic authenticity. Synthetic tannin supply concentrates around phenolic chemistry control, while vegetable tannin players anchor Mediterranean and South American bark supply chains. Two archetypes dominate: petrochemical-integrated formulators achieving uniform penetration rates, and botanical extractors leveraging quebracho and chestnut sourcing relationships. Competitive moves center on captive phenol supply security and multi-year formulation partnerships with luxury tanneries.
Among German chemical majors, LANXESS and BASF SE exemplify the petrochemical-integrated archetype through in-house phenolic chemistry production. Silvateam anchors the botanical extractor position with Mediterranean chestnut and South American quebracho dominance. These three represent the strategic poles—synthetic consistency versus polyphenolic heritage—around which procurement panels consolidate.
| Leading Market Players |
|---|
| Chemtan Company |
| Merck KGaA |
| LANXESS |
| Silvateam |
| SCHILL+SEILACHER GMBH |
| BASF SE |
| ANGUS Chemical Company |
| TRUMPLER GmbH & Co. KG |
| Clariant |
| Others |
Value Chain & Pricing Dynamics
Arzignano's Veneto tanning cluster concentrates chestnut and quebracho extract refining capacity, granting Italian botanical extractors disproportionate leverage over premium vegetable tannin pricing while compressing margins for downstream formulators dependent on Mediterranean polyphenolic supply.
Pricing Analysis
REACH's chromium(VI) ceiling dictates the pricing tier structure across European tanneries, separating chrome-free certified formulations at premium levels from legacy mineral systems facing compliance-driven obsolescence. Price differentiation hinges on certification grade and captive phenol supply security, with LANXESS and BASF SE commanding stability through backward integration while spot-market buyers absorb petrochemical volatility. Cost compression in synthetic tannin tiers is intensifying as sulfonated phenol-formaldehyde condensates track benzene derivative swings. Automotive OEM procurement teams show least price sensitivity given specification mandates, whereas Indian footwear exporters operate at highest sensitivity due to thin export margins.
Supply Chain Analysis
Export-control regimes on phenolic chemical precursors limit synthetic tannin production equipment flows to certain jurisdictions, constraining capacity buildout in emerging production bases. Geographic supply concentration centers on Germany, Italy, and India for formulated tanning agents, with Mediterranean chestnut and South American quebracho bark anchoring vegetable tannin feedstocks. Raw material dependencies rest on petrochemical phenol, formaldehyde, and bark extract supply chains. Single-source vulnerability from Arzignano's vegetable tannin dominance creates chokepoint exposure. Distribution runs through chemical distributor networks with technical service capabilities, consolidating around REACH-compliant, ISO-certified houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where REACH compliance architectures and automotive OEM specification networks are creating winner-take-most dynamics around certified formulation partnerships.
For Market Incumbents: Harden supply security through captive phenol production or long-term quebracho extraction agreements, as ECHA's glutaraldehyde restriction timeline compresses alternative certification windows. Deepen technical service presence in Stuttgart and Munich OEM technical centers to lock in zirconium-titanium hybrid system qualifications before competitor validation cycles complete. For New Entrants and Emerging Players: Tamil Nadu's expanding vegetable tannin extraction base represents the most penetrable entry point for EU-bound footwear leather supply, given BIS certification backlogs delaying established competitor export approvals. A formulation partnership model with mid-cap Italian luxury tanneries bypasses direct Arzignano cluster competition while building patina-critical performance credentials. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because REACH-architected markets reward formulation R&D depth over commodity scale. Acquisition targets should display backward integration into phenolic chemistry or Mediterranean/South American bark supply relationships. The signal to watch is ECHA's final glutaraldehyde restriction determination, which would force accelerated alternative system adoption and compress valuation multiples for non-compliant specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Chemistry | LANXESS's captive sulfonated phenol-formaldehyde production insulates batch consistency from petrochemical volatility. |
| Long-term Formulation Partnership Contracts | Italian luxury tanneries in Tuscany displace spot-market purchasing with multi-year vegetable tannin supply agreements. |
| Zirconium-Titanium Hybrid System Qualification | German OEM technical centers in Stuttgart certify chrome-free alternatives for automotive interior programs. |
| Quebracho Extraction Capacity Expansion | Tamil Nadu and Uttar Pradesh clusters scale South American bark processing to capture EU footwear export demand. |
| Enzymatic Bating System Adoption | Spanish mid-cap tanneries virtualize lime-sulfide sequences to meet Catalan wastewater discharge limits. |
Study Parameters
A spread of perspectives from tanning plant managers, automotive Tier-1 procurement leads, leather chemical distribution partners, and technical R&D directors converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from customs and trade data, REACH regulatory filings, SEC 10-K disclosures from listed chemical majors, and Italian tannery association production statistics enabled bottom-up and top-down triangulation across the value chain.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across tanning agent chemistry type, end-use application tier, physical formulation format, and regional production hub cluster. CAGRs derived from installed capacity trajectories, OEM specification adoption curves, and regulatory compliance timeline assumptions. Key inputs included automotive interior content per vehicle forecasts and footwear leather export volume projections from Indian customs data.
Macroeconomic conditions sit as an overlay; deviation in benzene derivative pricing, euro-rupee exchange rates, or EU automotive production schedules would shift the trajectory. Material shifts in ECHA's final glutaraldehyde restriction determination or BIS certification timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Mining Flotation Chemicals Market
Chemicals
White Phosphorus Market
Chemicals
Mercuric Chloride Market
Chemicals
Sodium Ethylate Market
Chemicals
Whitening Ingredients Market
Chemicals
Egypt Acidulants Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Global Thiophene Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Tin Chemicals Market
Chemicals
Inorganic Chemicals Market
Chemicals
Global Methyl Cellulose Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Trimethylamine Market
Chemicals
Bakers Ammonia Market