
 Lead Tetracetate Market | 2026-2036
Lead Tetracetate Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Tetracetate Market Analytics
REACH authorization protocols for lead compounds are restructuring the cost-of-entry calculus for European suppliers, forcing smaller distributors to consolidate or exit. Thermo Fisher Scientific leverages its analytical-grade certification infrastructure to sustain premium positioning across regulated jurisdictions. Noah Technologies Corporation anchors its competitive stance through specialized reagent packaging for North American laboratories. Spectrum Chemical differentiates via dual-source procurement networks that navigate raw material volatility without compromising batch consistency.
Lead tetracetate is a lead(IV) coordination compound with the formula Pb(C₂H₃O₂)₄, synthesized through electrochemical oxidation of lead(II) acetate in glacial acetic acid with ammonium persulfate or peracetic acid, yielding a moisture-sensitive crystalline solid that serves primarily as a selective oxidizing agent in organic synthesis. The powder segment dominates current volume flows due to its compatibility with standard laboratory dispensing equipment and extended shelf stability under inert atmosphere. Pharmaceutical companies represent the fastest-growing end-user category, driven by expanded contract research organization spending on carbon-carbon bond formation protocols. The reagents application commands the widest margin pool, reflecting the compound's irreplaceable role in specific oxidative decarboxylation and glycol cleavage reactions where alternative oxidants fail.
The EPA regulates lead compound handling under TSCA Section 8(d) reporting requirements, while OSHA enforces permissible exposure limits that shape workplace handling protocols and protective equipment specifications. India's Central Pollution Control Board imposes hazardous waste tracking mandates on lead chemical processors, adding documentation burdens that favor larger manufacturers with dedicated compliance departments. Stakeholders must monitor evolving substitution pressures from organocatalytic methods while preserving technical service capabilities that justify premium positioning for irreplaceable synthetic applications.
Market Dynamics
REACH authorization protocols are compressing the European supplier base while Indian specialty chemical producers expand acetylation catalyst output for export markets, creating a bifurcated supply structure.
Growth Catalysts
- Pharmaceutical Pipeline Expansion:Contract research organizations deepen spending on carbon-carbon bond formation protocols that require lead-mediated oxidative decarboxylation.
- REACH Authorization Requirements:Compliance costs force consolidation among European distributors, concentrating volume with certified bulk suppliers who capture margin from exiting smaller players.
- India's Hazardous Waste Tracking Mandates:Documentation burdens favor larger manufacturers with dedicated compliance departments, accelerating formalization of the domestic specialty chemical sector.
Market Restraints
- Lead Compound Exposure Limits:OSHA permissible exposure limits shape workplace handling protocols and protective equipment specifications, elevating operational costs for laboratory-scale users.
- Organocatalytic Substitution Pressure:Emerging metal-free oxidative methods threaten demand in routine synthetic applications where reaction selectivity requirements permit alternatives.
- Moisture Sensitivity:The compound's reactivity with atmospheric moisture necessitates inert atmosphere packaging and storage, adding logistics complexity and shelf-life risk.
Strategic Opportunities
- North American Laboratory Services:Specialized reagent packaging and technical service capabilities justify premium positioning for irreplaceable synthetic applications in academic and industrial research settings.
- Dual-Source Procurement Networks:Raw material volatility navigation without batch consistency compromise creates differentiation for distributors with diversified supply bases.
- Analytical-Grade Certification Infrastructure:Premium positioning across regulated jurisdictions rewards investment in quality systems that satisfy pharmaceutical and fine chemical buyer requirements.
Industry Challenges
- Electrochemical Synthesis Scale-Up:The oxidation of lead(II) acetate in glacial acetic acid requires specialized equipment and process control expertise that constrains capacity expansion timelines.
- TSCA Section 8(d) Reporting Burden:EPA documentation requirements for lead compound handling create administrative overhead that disproportionately affects smaller volume handlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Tetracetate Market |
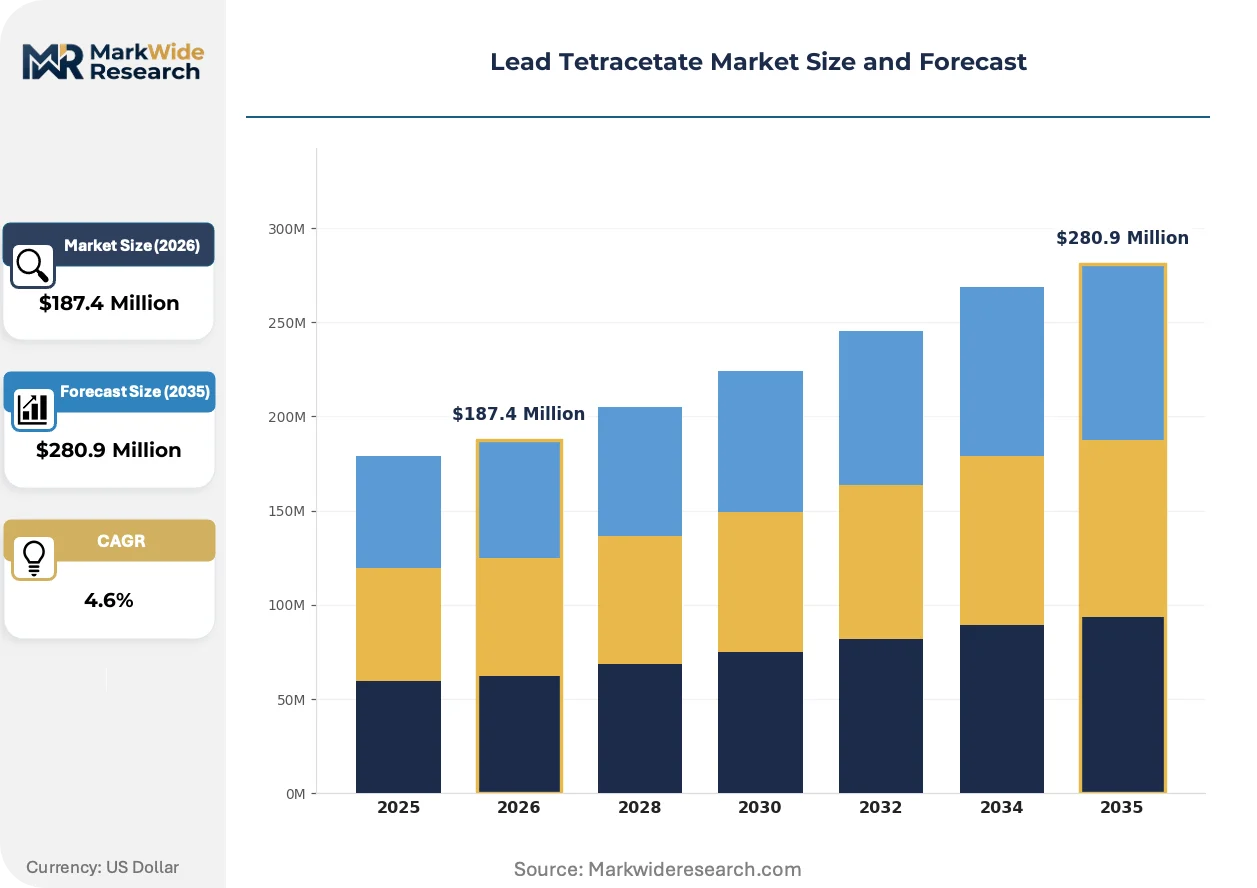
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
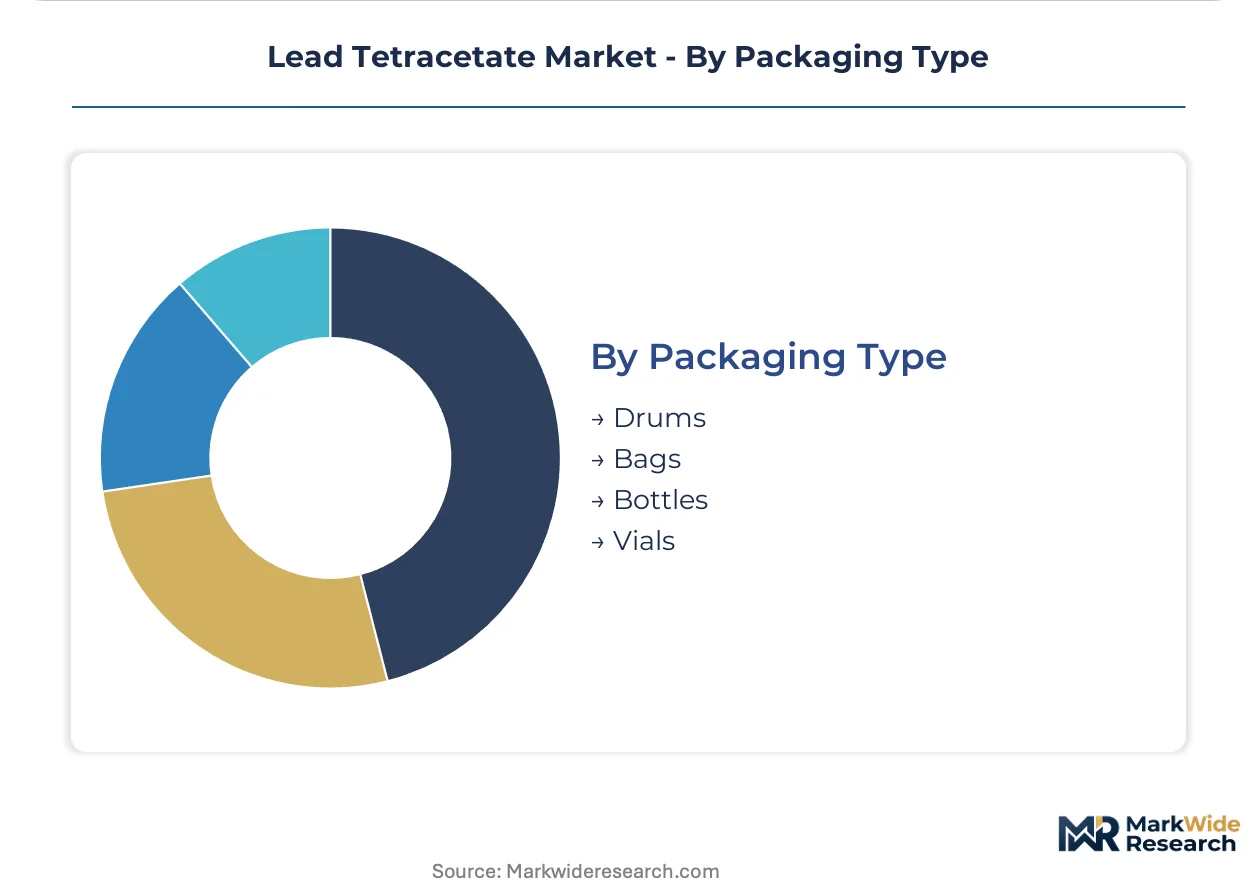
| Segmentation | Product Type: Granular, Powder, Liquid, Crystals End User: Chemical Manufacturers, Pharmaceutical Companies, Laboratories, Academic Institutions Application: Reagents, Catalysts, Organic Synthesis, Analytical Chemistry Packaging Type: Drums, Bags, Bottles, Vials |
| Companies Covered | Thermo Fisher Scientific, Sisco Research Laboratories, Spectrum Chemical, Noah Technologies Corporation, Hummel Croton, Aerocell, AVA Chemicals, Baerlocher, Chloral Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Tetracetate Market Evolving Landscape
Process intensification and regulatory compliance automation are reshaping how lead tetracetate is manufactured, distributed, and consumed across pharmaceutical and fine chemical value chains.
Continuous electrochemical oxidation systems are absorbing capital investment from batch reactor infrastructure as manufacturers seek tighter process control over the lead(II) acetate conversion step. Specialty chemical producers in India and Germany adopt these systems to reduce solvent waste and improve current efficiency. The technology is absorbing smaller batch producers who cannot amortize the capital expenditure or technical expertise required for continuous operation.
ECHA's tightening REACH authorization timelines for lead compounds are compressing the window for downstream user notification and supply chain restructuring. European distributors face accelerated compliance deadlines that favor pre-registered bulk suppliers with established authorization dossiers. The pharmaceutical reagent segment is responding by consolidating procurement relationships with REACH-authorized manufacturers and reducing supplier counts.
Specification-driven procurement is displacing price-first purchasing in pharmaceutical applications where batch consistency and certificate of analysis reliability determine synthetic success. Contract research organizations now require dual-source qualification with identical analytical profiles, extending vendor onboarding cycles. This pattern is most visible in North American and European CRO networks serving late-stage drug development programs.
Lead Tetracetate Market Segmentation
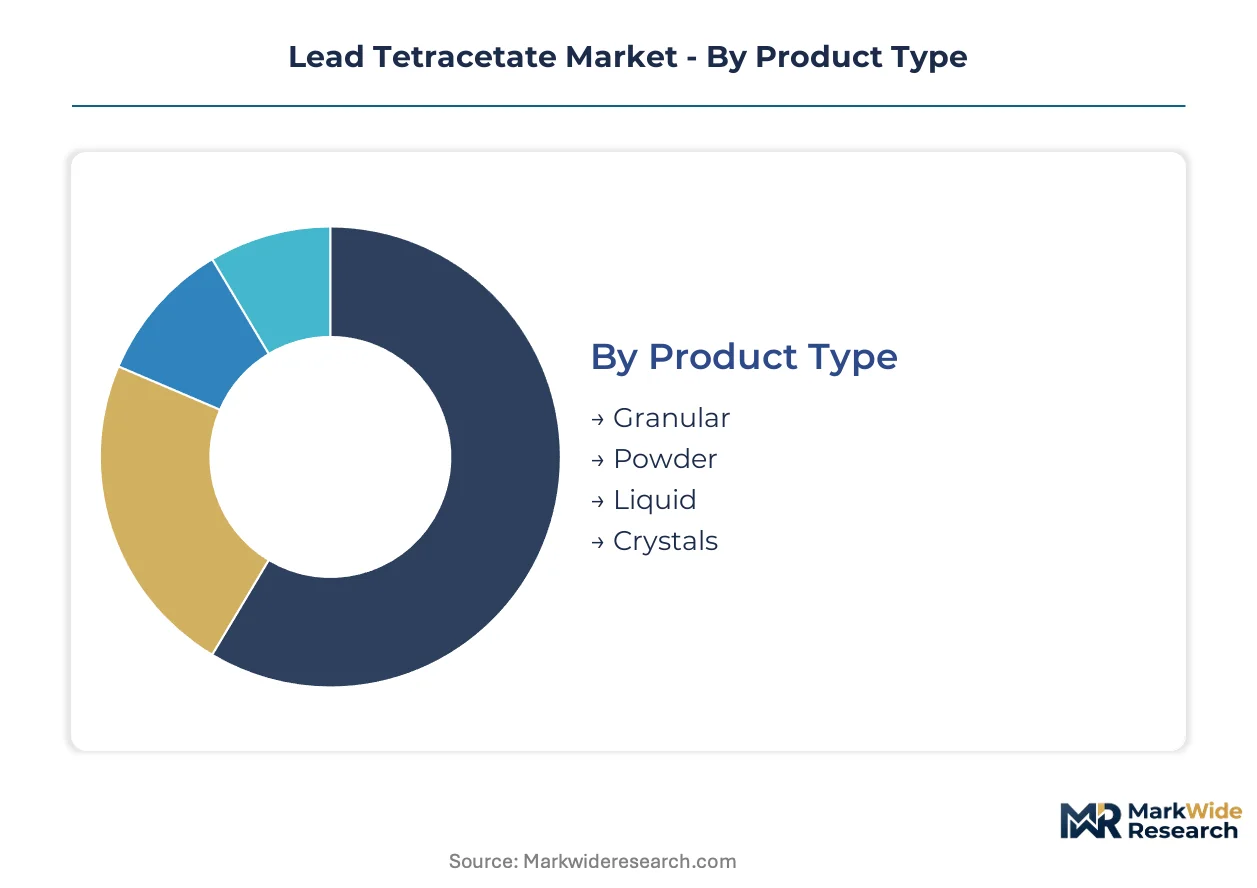
Lead tetracetate procurement patterns diverge sharply across product specifications and end-use requirements. Pharmaceutical buyers prioritize analytical-grade consistency while industrial users optimize for bulk handling efficiency. Understanding these segment-level trade-offs reveals where margin pools concentrate and which specifications command sustainable premiums.
Product Type:
Upgrade cycles in laboratory infrastructure favor formats compatible with automated dispensing and inert atmosphere storage systems.
- Powder:Crystalline solid form with extended shelf stability under argon or nitrogen atmosphere. Demand concentrates in contract research organizations running high-throughput oxidative decarboxylation protocols where precise gravimetric dosing determines reaction yields.
- Liquid:Solution formulations in glacial acetic acid or compatible solvents eliminate atmospheric moisture exposure during transfer. Academic institutions in India and Germany favor this format for undergraduate organic synthesis instruction where handling safety protocols must accommodate less experienced users.
- Granular:Coarse particle size reduces dust generation during bulk transfer operations. Chemical manufacturers in specialty acetylation catalyst production specify this grade for reactor charging efficiency.
- Crystals:Large crystalline morphology suits visual purity verification and single-batch traceability requirements. Analytical chemistry laboratories specify this form for reference standard preparation.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
End User:
Customer sophistication tiers separate specification-driven procurement from price-sensitive commodity purchasing.
- Pharmaceutical Companies:Late-stage drug development programs require certificate of analysis reliability and dual-source qualification with identical analytical profiles. REACH authorization compliance and batch consistency documentation justify premium positioning.
- Chemical Manufacturers:Organic synthesis operations in India's specialty chemical sector scale acetylation catalyst output for export markets. Central Pollution Control Board hazardous waste tracking mandates favor larger producers with dedicated compliance infrastructure.
- Laboratories:Industrial and academic research facilities prioritize moisture-sensitive packaging and technical service support for irreplaceable synthetic applications.
- Academic Institutions:Teaching laboratories balance material cost against handling safety protocols, driving demand for liquid formulations and smaller package sizes.
Pharmaceutical Companies capture the dominant procurement value; Chemical Manufacturers are climbing the fastest as India's export-oriented specialty chemical sector formalizes.
Application:
Functional performance requirements determine whether lead tetracetate remains irreplaceable or faces substitution pressure from organocatalytic alternatives.
- Reagents:Selective oxidizing agent for oxidative decarboxylation, glycol cleavage, and carbon-carbon bond formation where alternative oxidants fail to achieve required selectivity. Contract research organizations deepen spending on these protocols.
- Catalysts:Acetylation and related transformations in fine chemical production. Indian specialty chemical producers expand output for export markets.
- Organic Synthesis:General synthetic utility across pharmaceutical intermediates and agrochemical building blocks.
- Analytical Chemistry:Reference standard preparation and method development applications requiring high-purity crystalline material.
Reagents command the widest margin pool; Catalysts are gaining share fastest with India's manufacturing expansion.
Packaging Type:
Handling logistics and contamination risk shape format selection across volume tiers and end-use environments.
- Bottles:Amber glass or fluoropolymer containers with septum closures for laboratory-scale dispensing under inert atmosphere. Standard equipment compatibility drives specification.
- Vials:Single-use or limited-quantity packaging for analytical chemistry reference standards and method validation batches.
- Drums:Stainless steel or lined steel containers for bulk chemical manufacturer procurement with dedicated material handling systems.
- Bags:Multi-layer barrier bags with nitrogen flush for intermediate quantities in specialty chemical production.
Bottles dominate laboratory procurement volumes; Drums are expanding most quickly with chemical manufacturer scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Visakhapatnam Special Economic Zone and Gujarat's Dahej PCPIR concentrate Indian lead tetracetate manufacturing capacity through tax holidays and duty exemptions on imported electrochemical equipment. These zones attract multinational fine chemical producers seeking REACH-authorized export platforms.
India
Domestic specialty chemical producers scale acetylation catalyst output for European and North American export markets. The Central Pollution Control Board's hazardous waste tracking mandates favor larger manufacturers with dedicated compliance departments in Ankleshwar and Vapi industrial corridors. Mumbai-Pune chemical clusters absorb consolidation pressure from smaller unorganized sector exits.
Germany
ECHA's tightening REACH authorization timelines compress the supplier base for downstream pharmaceutical users. The Leverkusen-Düsseldorf chemical belt hosts electrochemical oxidation specialists serving contract research organizations with dual-source qualification requirements. Bavarian fine chemical producers invest in continuous flow systems to reduce solvent waste.
United States
EPA TSCA Section 8(d) reporting requirements elevate administrative overhead for laboratory-scale handlers. Greater Boston and San Diego biotech corridors deepen procurement from REACH-authorized manufacturers to secure late-stage drug development supply chains. OSHA permissible exposure limits shape protective equipment specifications across industrial research facilities.
China
Jiangsu and Zhejiang province chemical parks absorb capacity expansion from batch-to-continuous process upgrades. The Ministry of Ecology and Environment's dual carbon goals accelerate electrochemical efficiency investments in Yangtze River Delta production bases. Shanghai-based distributors navigate raw material volatility through diversified lead acetate sourcing.
Switzerland
Basel's pharmaceutical reagent specialists leverage Swissmedic quality frameworks to sustain premium positioning across regulated jurisdictions. The country's analytical-grade certification infrastructure attracts procurement consolidation from global contract research organizations. Geneva-based trading houses manage dual-source networks for moisture-sensitive compound logistics.
Lead Tetracetate Market Competitive Landscape
Indian producers anchor the volume tier through SEZ-enabled export platforms; German and Swiss specialists hold premium positions via REACH authorization dossiers. The supplier base compresses into two concentration layers: bulk manufacturers with electrochemical scale and certified reagent houses with analytical-grade infrastructure. Three archetypes dominate—continuous-process specialists, dual-source procurement managers, and technical service providers. Consolidation accelerates through REACH-driven distributor exits and SEZ-attracted capacity expansion.
Among laboratory reagent specialists, Thermo Fisher Scientific exemplifies the analytical-grade certification archetype, while Noah Technologies Corporation occupies a position within North American technical service providers. Spectrum Chemical represents the dual-source procurement management tier. These three entities anchor the competitive structure without exhausting its variation—AVA Chemicals and Baerlocher sit within distinct geographic and scale segments, and the full player set includes Sisco Research Laboratories, Hummel Croton, Aerocell, and Chloral Chemicals alongside regional specialists captured in the "Others" category.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sisco Research Laboratories |
| Spectrum Chemical |
| Noah Technologies Corporation |
| Hummel Croton |
| Aerocell |
| AVA Chemicals |
| Baerlocher |
| Chloral Chemicals |
| Others |
Value Network & Pricing Analysis
REACH certification bifurcation separates authorized bulk suppliers from commodity distributors, concentrating pricing power with German and Swiss electrochemical specialists while Indian SEZ producers capture volume through tax-advantaged export platforms. This tier divergence manifests in procurement contracts where pharmaceutical buyers pay substantial premiums for dual-source qualification documentation that smaller distributors cannot furnish, while chemical manufacturers optimize for landed cost efficiency through Visakhapatnam and Dahej production bases.
Pricing Analysis
Expedited lead-time premiums reward REACH-authorized manufacturers with established dossiers, while spot-market discounts attract price-sensitive academic buyers willing to accept single-source risk. Three-tier pricing structure across analytical-grade, reagent-grade, and technical-grade levels reflects certification investment recovery and batch consistency documentation costs. Pricing pressure stems from organocatalytic substitution in routine oxidative applications where selectivity requirements permit metal-free alternatives. Academic institutions exhibit highest price sensitivity, prioritizing liquid formulations and smaller package sizes over certificate reliability.
Supply Chain Analysis
Regional distribution centers in Mumbai-Pune and Leverkusen-Düsseldorf chemical belts manage moisture-sensitive inventory through nitrogen-flushed warehousing and controlled-atmosphere transfer protocols. Manufacturing concentrates in India, Germany, and Switzerland, with electrochemical oxidation capacity anchored in Visakhapatnam SEZ and Bavarian fine chemical corridors. Raw material flows draw from lead acetate suppliers, glacial acetic acid producers, and ammonium persulfate manufacturers across Yangtze River Delta and Gujarat industrial zones. Single-source vulnerability persists in analytical-grade certification infrastructure where Swissmedic and ECHA authorization timelines extend eighteen to thirty-six months. Distribution runs through specialty chemical distributors with dedicated reagent logistics capabilities serving North American and European laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization deadlines compress the supplier base into two sustainable tiers, forcing smaller distributors without certification dossiers toward exit or acquisition. Consolidation accelerates through electrochemical scale requirements that absorb capital beyond unorganized sector reach.
For Market Incumbents: Cement dual-source qualification relationships with contract research organizations by investing in continuous electrochemical oxidation systems that guarantee batch consistency documentation. Backward integration into lead acetate supply secures raw material margin control against Yangtze River Delta price volatility. Organocatalytic substitution in routine synthetic applications threatens volume in commodity-grade segments; defend through technical service capabilities for irreplaceable oxidative decarboxylation protocols.
For New Entrants and Emerging Players: Begin with liquid formulation packaging for Indian academic institutions where handling safety protocols favor solution-based dispensing over moisture-sensitive powder transfer. White-space concentration sits in North American laboratory services where specialized reagent packaging and inert atmosphere logistics justify premium positioning. Target procurement managers at mid-tier contract research organizations seeking REACH-authorized alternatives to incumbent pricing power.
For Investors and Strategic Acquirers: Re-rating potential sits with electrochemical scale specialists given ECHA authorization timeline compression and pharmaceutical buyer consolidation toward pre-registered suppliers. Long-term viability hinges on five-to-ten year substitution risk management as organocatalytic methods advance. Acquisition targets include Indian SEZ-based producers with export platform infrastructure and German continuous-process specialists with established authorization dossiers. Signal to monitor: contract research organization procurement consolidation announcements indicating supplier count reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Electrochemical Scale-Up | Absorbs batch producers unable to amortize capital expenditure for oxidation efficiency gains. |
| REACH Authorization Dossier Investment | Captures margin from exiting distributors across European pharmaceutical procurement networks. |
| Dual-Source Procurement Qualification | Secures late-stage drug development supply relationships with certificate reliability requirements. |
| Liquid Formulation Development | Addresses academic safety protocols while reducing atmospheric moisture exposure during transfer. |
| SEZ-Based Export Platform Expansion | Leverages Visakhapatnam tax holidays for duty-exempt electrochemical equipment import. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrochemical plant managers, pharmaceutical procurement leads, specialty chemical distribution channel partners, and technical R&D directors at contract research organizations. Cefic chemical industry reports, ECHA authorization databases, SEC 10-K filings, and Indian Central Pollution Control Board hazardous waste tracking records provided demand-side validation. Bottom-up volume estimates from product-type and end-user segmentation reconciled against top-down market sizing from regional production capacity assessments.
Data-stream reconciliation across supply-side capacity utilization, demand-side procurement surveys, and trade-flow customs documentation established analytical coherence. Segmentation dimensions modeled include product format tier, end-use industry sophistication, packaging specification, and regional regulatory cluster across the projection horizon. CAGRs derived from regression analysis of historical volume trajectories adjusted for REACH authorization timeline impacts and organocatalytic substitution elasticity. Industry-specific forecast inputs encompass pharmaceutical pipeline stage advancement rates and Indian specialty chemical export growth trajectories.
Underlying measurement precision varies by segment; pharmaceutical reagent applications carry tighter precision than commodity catalyst procurement given documentation transparency requirements. Forecasts reflect documented assumptions regarding ECHA authorization timeline adherence and electrochemical capacity expansion schedules. Substitution technology advancement, raw material price volatility, and regulatory enforcement intensity constitute primary revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Thioacetic Acid Market
Chemicals
Acetophenone Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Para Cresol Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Aerosol Insecticides Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Anhydrides Market
Chemicals
Triethylenediamine Market