
 North America Isopropyl Alcohol Market | 2026-2036
North America Isopropyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Isopropyl Alcohol Market Intelligence
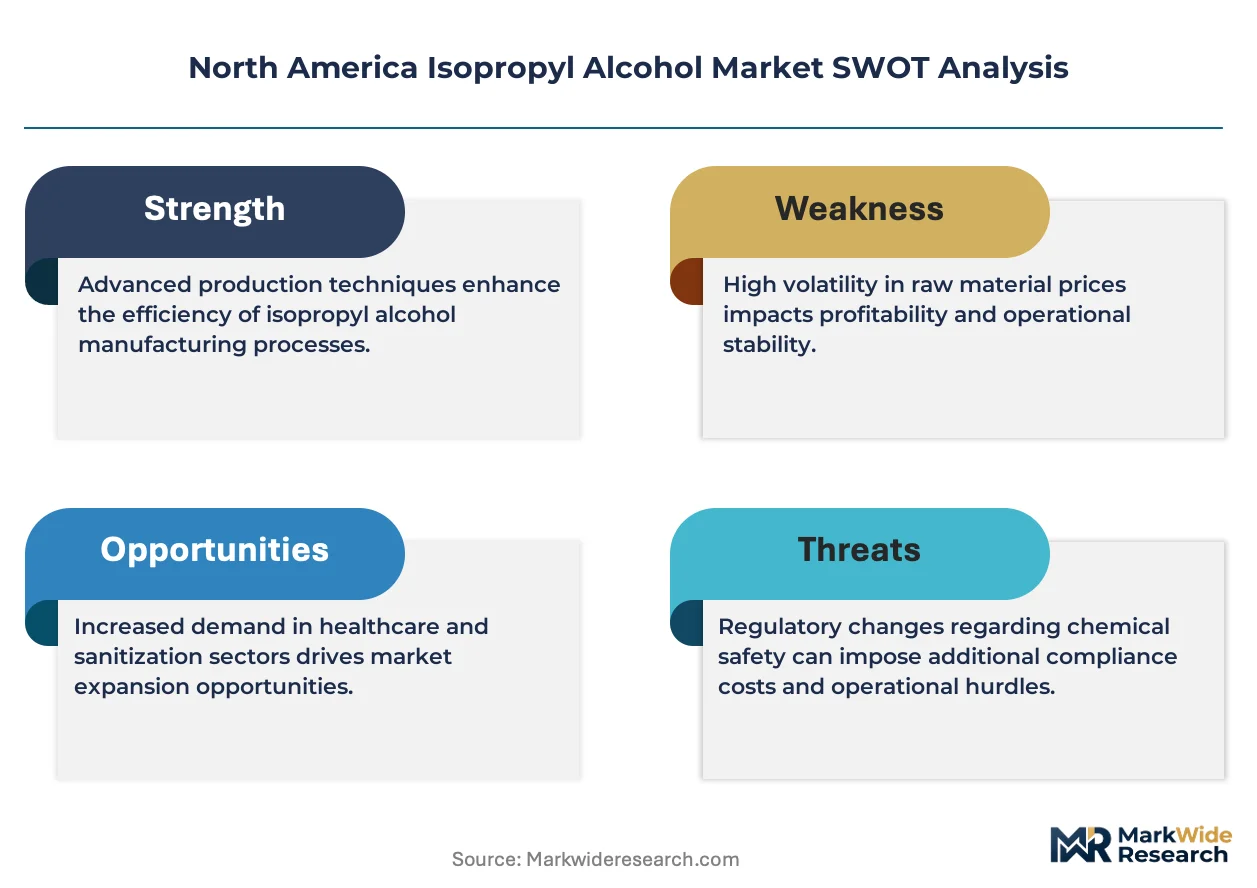
The gap between pharmaceutical-grade and industrial-grade specifications is restructuring procurement across North America. INEOS leverages its Texas Gulf Coast propylene integration to sustain cost leadership in bulk industrial volumes. Dow Chemical anchors the premium tier through electronic-grade purification for semiconductor wafer cleaning. LyondellBasell Industries differentiates via propylene oxide co-product streams that tighten cost spreads against acetone-based rivals.
Isopropyl alcohol is a secondary alcohol with the formula C₃H₈O, typically manufactured through direct hydration of propylene or hydrogenation of acetone, and it functions as a versatile solvent, disinfectant, and chemical intermediate across industrial and consumer applications. Pharmaceutical grade commands the widest margin pool due to USP monograph compliance and batch certification overhead, while electronic grade is the fastest-growing category as domestic semiconductor fabrication expands. Industrial grade remains the volume backbone for automotive coatings and metal degreasing, though pricing power erodes during propylene oversupply cycles.
EPA registration under FIFRA governs disinfectant claims and drives reformulation costs for suppliers serving healthcare and institutional cleaning channels. FDA oversight of drug monographs and USP-NF standards constrains which grades qualify for pharmaceutical and personal care applications, creating a compliance moat around validated producers. OSHA permissible exposure limits and state-level volatile organic compound rules in California and Texas further segment regional supply requirements. Stakeholders must monitor propylene feedstock contract structures and acetone-price arbitrage to assess margin durability across the forecast horizon.
Market Dynamics
Propylene contract volatility and acetone-price arbitrage cycles are compressing margin spreads across North American isopropyl alcohol production, forcing producers to renegotiate feedstock structures and grade-mix strategies quarterly.
Growth Catalysts
- EPA FIFRA Registration Tightening:Surface disinfectant purity thresholds are rising, locking out non-validated suppliers and concentrating volume among registered producers serving hospital networks.
- Semiconductor Fabrication Expansion:Domestic chip manufacturing investments are pulling electronic-grade IPA volumes at rates outpacing industrial-grade consumption.
- USP-NF Pharmaceutical Compliance:Batch certification overhead creates compliance moats that protect margin pools for validated Gulf Coast producers.
Market Restraints
- Propylene Feedstock Volatility:Crude-linked propylene contract pricing erodes cost predictability for direct-hydration producers during energy market swings.
- Acetone-Based Competition:Hydrogenation of acetone offers alternative supply economics that cap pricing power during propylene oversupply cycles.
- Texas-Louisiana Concentration Risk:Chemical corridor weather disruptions and pipeline constraints expose buyers to single-geography supply interruptions.
Strategic Opportunities
- Compounding Pharmacy Channel:Hospital outsourcing of sterile compounding creates dedicated pharmaceutical-grade offtake agreements with multi-year visibility.
- California VOC Rule Alignment:State-level volatile organic compound limits favor low-emission IPA formulations in automotive coatings and metal degreasing.
- Bioprocessing Equipment Cleaning:Cell and gene therapy manufacturing expansion demands USP-grade solvent volumes for single-use bioreactor sterilization protocols.
Industry Challenges
- USP Batch Certification Timeline:FDA drug monograph validation cycles extend 12-18 months, delaying new entrant qualification for pharmaceutical channels.
- OSHA Exposure Limit Compliance:Permissible exposure monitoring and ventilation retrofit requirements strain legacy production facilities.
- Electronic-Grade Purity Scaling:Semiconductor wafer cleaning specifications below 100 parts-per-billion metal content demand capital-intensive distillation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Isopropyl Alcohol Market |
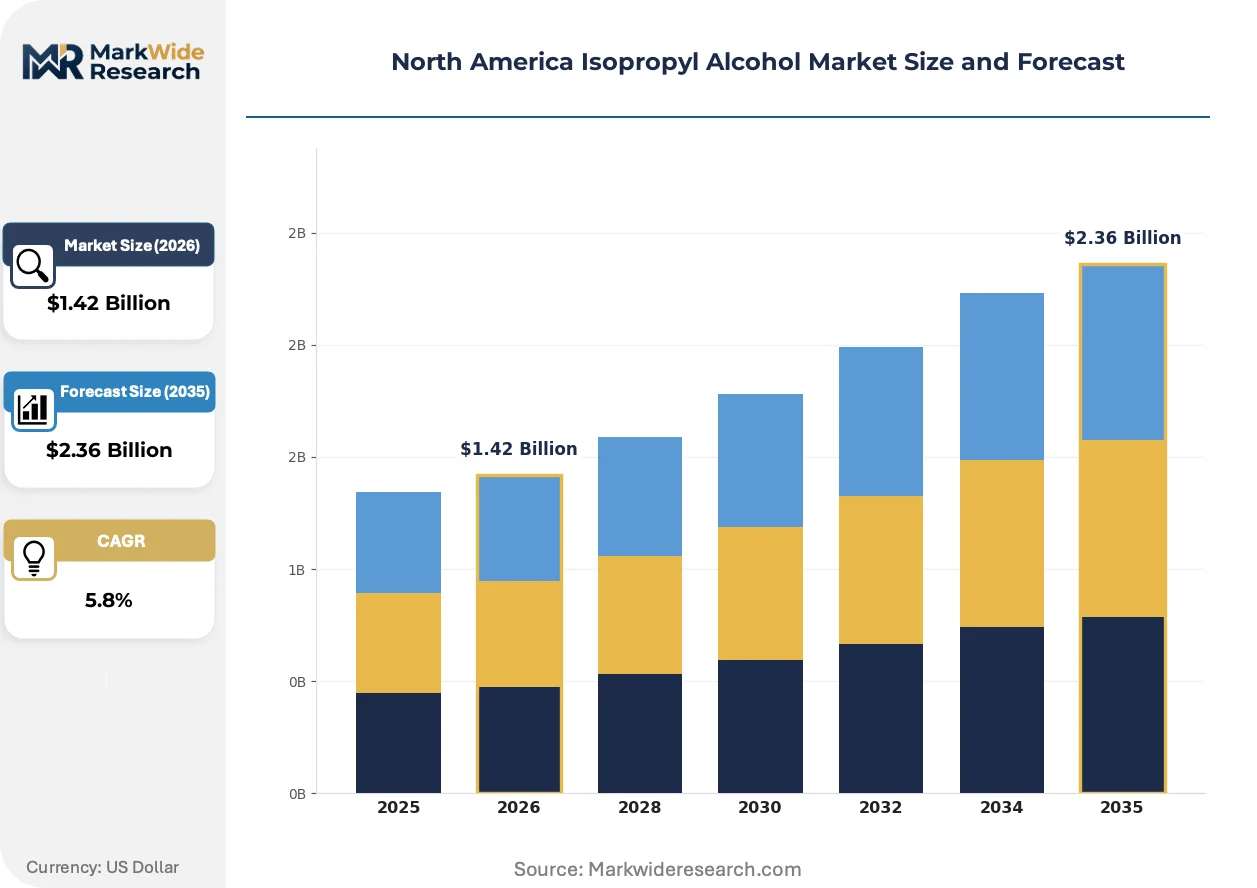
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Industrial Grade, Electronic Grade, Cosmetics Grade Application: Cleansing, Disinfecting, Solvent, Antiseptic End User: Healthcare, Automotive, Manufacturing, Personal Care Packaging Type: Bulk Containers, Drums, Bottles, Sachets |
| Companies Covered | INEOS, Eastman, Dow Chemical, LCY Chemical, Ecolab, ExxonMobil, LyondellBasell Industries, Linde plc, Shell USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Isopropyl Alcohol Market Strategic Shifts & Innovations
Process intensification and regulatory precision are converging to reshape how North American producers compete on grade purity, energy efficiency, and channel-specific certification speed.
Membrane-based propylene hydration is overtaking conventional fixed-bed catalytic reactors in new capacity installations. Specialty chemical producers in Texas are adopting this technology to cut steam consumption and reduce carbon intensity scores. The shift is compressing capital recovery timelines for mid-scale facilities while raising barriers for acetone-based rivals.
OSHA permissible exposure limit enforcement is tightening across Texas and Louisiana petrochemical corridors. Inspectors are targeting IPA storage and handling facilities for respiratory protection program audits. Producers are responding with closed-loop transfer systems and real-time atmospheric monitoring to preempt citation exposure.
Hospital procurement consolidation is compressing supplier rosters to three or fewer validated pharmaceutical-grade vendors per network. Group purchasing organizations are unbundling disinfectant contracts from broader janitorial supply agreements. This concentration is most visible in US Southeast health systems expanding through regional acquisition strategies.
North America Isopropyl Alcohol Market Segmentation
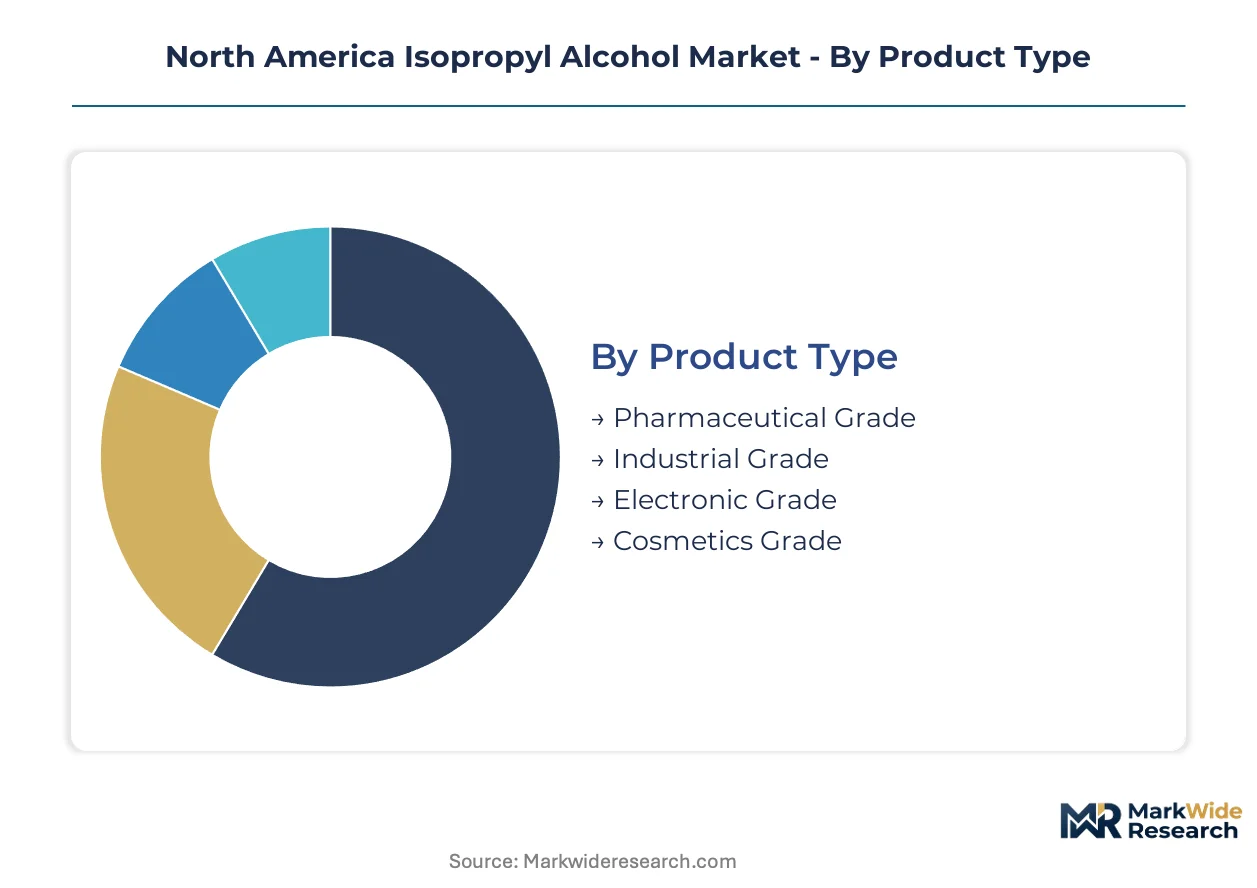
Grade purity specifications and packaging configurations determine pricing power and channel access across North American isopropyl alcohol supply chains. Segmentation discipline separates validated pharmaceutical producers from commodity industrial suppliers.
Product Type:
Customization intensity rises with regulatory stringency, creating four distinct cost-to-serve tiers from batch-certified pharmaceutical to specification-tolerant industrial volumes.
- Pharmaceutical Grade:USP-NF monograph compliance mandates batch certification and validated manufacturing protocols. Hospital networks and compounding pharmacies in the US Gulf Coast corridor concentrate procurement among three or fewer registered suppliers per network, locking out non-validated producers.
- Electronic Grade:Metal content specifications below 100 parts-per-billion for semiconductor wafer cleaning demand capital-intensive distillation infrastructure. Domestic chip fabrication investments in Texas and Arizona are pulling volumes at rates outpacing industrial-grade consumption.
- Industrial Grade:Automotive coatings and metal degreasing absorb the largest volume share with the loosest purity tolerances.
- Cosmetics Grade:Personal care formulators in California drive demand for low-odor, low-residue specifications.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Electronic Grade.
Application:
Functional performance requirements segment procurement between regulated healthcare claims and unregulated industrial processing.
- Cleansing:Precision electronics and optical component manufacturing demand residue-free evaporation profiles. California semiconductor fabs specify ultra-low particulate formulations for wafer pre-treatment protocols.
- Disinfecting:EPA FIFRA registration governs surface disinfectant claims, concentrating hospital procurement among registered producers. Purity thresholds are tightening, elevating reformulation costs for legacy suppliers.
- Solvent:Industrial coatings and resin processing absorb high-volume, specification-flexible supply.
- Antiseptic:FDA drug monograph oversight constrains topical preparation formulations to validated pharmaceutical-grade inputs.
Disinfecting commands the tightest supplier rosters. Solvent maintains the broadest producer base.
End User:
Customer scale and compliance burden stratify pricing power from consolidated hospital purchasing to fragmented metalworking shops.
- Healthcare:Group purchasing organization consolidation in the US Southeast compresses supplier lists to multi-year contractual relationships. Sterile compounding outsourcing creates dedicated pharmaceutical-grade offtake with volume visibility.
- Automotive:California VOC rule alignment favors low-emission IPA formulations in coatings and assembly line cleaning.
- Manufacturing:Metal degreasing and electronics assembly drive drum-scale procurement with specification flexibility.
- Personal Care:Cosmetics formulators demand cosmetics-grade certification for skin-contact applications.
Healthcare captures the highest margin pool. Manufacturing absorbs the largest volume throughput.
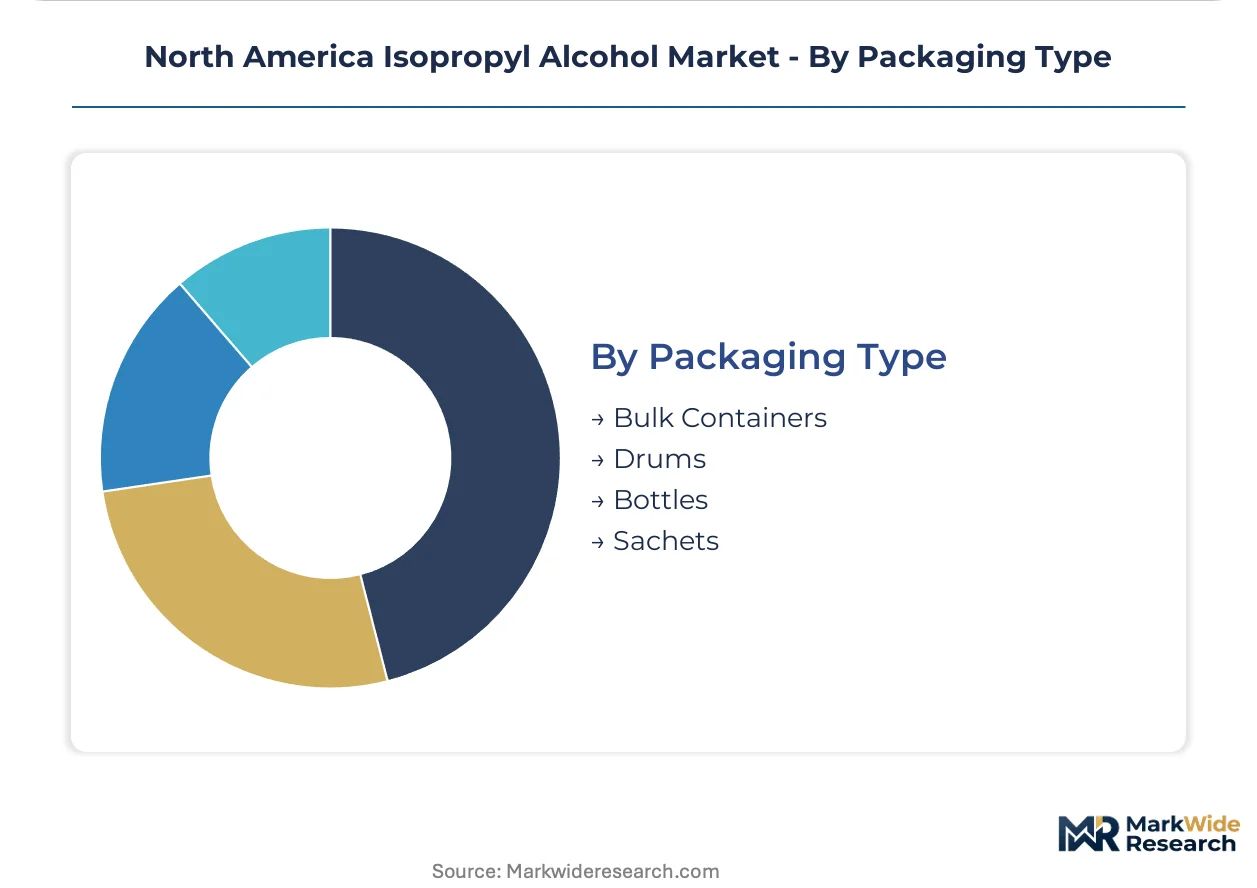
Packaging Type:
Logistics economics and handling safety requirements determine format selection from pipeline-fed bulk to retail-caliber sachets.
- Bulk Containers:Gulf Coast chemical corridor producers serve Texas and Louisiana industrial consumers via tanker truck and railcar delivery.
- Drums:Mid-scale manufacturing and regional distributors favor 55-gallon steel and poly containers for inventory flexibility.
- Bottles:Healthcare and personal care channels require child-resistant closures and lot-coded labeling for point-of-use traceability.
- Sachets:Field-deployed antiseptic wipes and travel-size sanitizers drive single-use pouch demand.
Bulk Containers dominate tonnage movement. Bottles carry the highest unit value realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and process technicians cluster along the US Gulf Coast, anchoring North American isopropyl alcohol production capacity in a narrow corridor between Houston and Baton Rouge.
United States
Texas and Louisiana host the densest concentration of propylene-integrated IPA facilities, with the Houston Ship Channel and Lake Charles chemical complexes processing feedstock from regional refineries. EPA FIFRA registration requirements for surface disinfectants are tightening purity thresholds, locking out non-validated suppliers from hospital procurement networks. Dallas-Fort Worth semiconductor fabs are pulling electronic-grade volumes at rates outpacing industrial-grade consumption.
Canada
Ontario's automotive assembly corridors drive drum-scale demand for metal degreasing and coatings applications, with Toronto-area distributors serving Quebec manufacturing clusters. Health Canada and PMRA oversight of disinfectant claims aligns with US EPA standards, easing cross-border formulation approvals for registered producers. Alberta's petrochemical sector supplies western industrial consumers via railcar distribution from Edmonton-area terminals.
Mexico
Nuevo León's expanding electronics assembly sector near Monterrey demands electronics-grade solvents for precision cleaning operations, pulling imports from US Gulf Coast producers. Mexican regulatory frameworks for industrial chemical handling are converging with OSHA exposure limit standards, streamlining facility certifications for multinational operators. Bajío Region automotive plants consume industrial-grade volumes for paint line maintenance and component preparation.
Southeast United States
Florida and Georgia hospital networks are consolidating procurement through regional group purchasing organizations, compressing pharmaceutical-grade supplier rosters to three or fewer validated vendors per network. USP-NF batch certification overhead creates compliance moats protecting margin pools for Gulf Coast producers with FDA-validated facilities. Atlanta-area compounding pharmacies are outsourcing sterile preparation to dedicated contract manufacturers, creating multi-year offtake agreements.
California
Bay Area semiconductor fabrication investments are accelerating electronic-grade IPA consumption for wafer cleaning protocols requiring metal content below 100 parts-per-billion. California Air Resources Board VOC rules favor low-emission IPA formulations in automotive coatings and metal degreasing, differentiating compliant suppliers. Los Angeles-area personal care formulators drive cosmetics-grade demand for low-odor, low-residue specifications.
North America Isopropyl Alcohol Market Key Industry Players
Capital-heavy producers compete with asset-light distributors across a market structure consolidating around integrated petrochemical majors and specialized purification specialists. Three or four Gulf Coast propylene-integrated operators anchor bulk industrial supply, while electronic-grade and pharmaceutical-grade tiers concentrate among validated purification specialists with FDA and EPA registrations. Competitive positioning hardens around feedstock contract structures, grade-mix flexibility, and channel-specific certification speed rather than scale alone. Producers defend margin durability through backward integration into propylene supply and strategic partnerships with hospital purchasing networks.
Among integrated petrochemical operators, INEOS, Dow Chemical, and LyondellBasell Industries exemplify the capital-intensive archetype leveraging Gulf Coast propylene access. INEOS occupies a position anchored in Texas propylene integration for bulk industrial volumes. Dow Chemical represents the premium-tier purification specialist serving semiconductor and pharmaceutical channels. LyondellBasell Industries sits within the propylene oxide co-product stream archetype, tightening cost spreads against acetone-based rivals. These three anchors demonstrate how feedstock structure and grade certification stratify competitive positioning across the forecast horizon.
| Leading Market Players |
|---|
| INEOS |
| Eastman |
| Dow Chemical |
| LCY Chemical |
| Ecolab |
| ExxonMobil |
| LyondellBasell Industries |
| Linde plc |
| Shell USA |
| Others |
Cost & Logistics Intelligence
Hospital procurement consolidation across the US Southeast is unbundling disinfectant contracts from broader janitorial supply agreements, forcing Gulf Coast producers to restructure service bundles and absorb certification overhead into base pricing.
Pricing Analysis
Bundled service contracts that combined product supply with technical support and regulatory documentation are fragmenting into unbundled transactional arrangements. Pricing stratifies across pharmaceutical-grade, electronic-grade, and industrial-grade tiers, with USP-NF batch certification and EPA FIFRA registration driving premium realization in healthcare channels. Cost compression in industrial-grade volumes is intensifying because acetone-based hydrogenation economics cap pricing power during propylene oversupply cycles. Metalworking shops and automotive coating lines exhibit the highest price sensitivity, while semiconductor fabs and hospital networks prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Baton Rouge, and Dallas-Fort Worth operate on hub-and-spoke patterns radiating from Gulf Coast production complexes. Supply concentrates in the United States, with Canada and Mexico drawing imports via railcar and tanker truck from Texas-Louisiana terminals. Propylene feedstock, acetone, and catalytic hydrogenation equipment constitute critical input dependencies. Single-geography concentration risk from hurricane exposure and pipeline constraints threatens supply continuity. Distribution runs through bulk tanker and railcar networks for industrial volumes, with drum-scale and bottled formats serving healthcare and personal care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American isopropyl alcohol rests on pharmaceutical-grade certification premiums and electronic-grade purity scaling as domestic semiconductor fabrication accelerates.
For Market Incumbents: Cement feedstock cost leadership through propylene contract restructuring and captive supply integration. Lock in multi-year offtake agreements with consolidating hospital purchasing networks before EPA registration timelines extend qualification barriers. Defend against acetone-based rivals by tightening grade-mix flexibility and accelerating USP-NF batch certification turnaround. For New Entrants and Emerging Players: Compounding pharmacy contract manufacturers represent an underserved buyer archetype with dedicated pharmaceutical-grade volume visibility and lower incumbent concentration than hospital networks. Target California semiconductor fabs and bioprocessing equipment cleaning protocols for electronic-grade and USP-grade entry. Pursue toll-manufacturing arrangements with existing Gulf Coast propylene-integrated facilities to bypass 12-18 month FDA validation cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with purification specialists holding dual EPA FIFRA and FDA registrations, positioned to capture healthcare channel consolidation and semiconductor fabrication expansion. Five-to-ten year viability favors assets with backward integration into propylene supply and electronic-grade distillation infrastructure. Monitor Texas-Louisiana chemical corridor weather disruption frequency as an inflection indicator for regional supply reliability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive feedstock from Texas Gulf Coast refineries insulates margin volatility from crude-linked contract swings. |
| Electronic-Grade Distillation Upgrade | Metal content below 100 parts-per-billion unlocks semiconductor wafer cleaning contracts in Arizona and Texas fabs. |
| USP-NF Batch Certification Investment | FDA-validated protocols create compliance moats protecting pharmaceutical-grade margin pools from non-registered rivals. |
| Long-term Supply Agreement with Hospital GPOs | Multi-year contracts with Southeast health systems compress supplier rosters and secure volume visibility. |
| California VOC-Compliant Formulation Development | Low-emission IPA variants capture automotive coatings demand under Air Resources Board rules. |
Research Approach
Multiple input streams — executive interviews with Gulf Coast plant managers and technical R&D directors, procurement lead discussions at downstream pharmaceutical and semiconductor OEMs, and distribution channel partner assessments — were reconciled against customs trade data, American Chemistry Council sector reports, and SEC 10-K filings from integrated petrochemical operators. Bottom-up volume modeling across grade tiers and end-use applications was cross-validated through top-down market sizing from propylene derivative consumption patterns.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning grade purity tier, end-use industry vertical, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and feedstock cost trajectory modeling. Semiconductor fabrication capacity buildouts and EPA registration timeline extensions served as key industry-specific forecast inputs.
Inputs from primary fieldwork and secondary regulatory databases were available through the study window; gaps in real-time propylene contract pricing and acetone-hydrogenation cost spreads introduce uncertainty bands around margin compression scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Power Plant Chemicals Market
Chemicals
Stimulation Materials Market
Chemicals
Peroxyacetic Acid Market
Chemicals
Flooring Chemicals Market
Chemicals
Etidronic Acid Market
Chemicals
Malic Acid Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Asia-Pacific Fluorosilicic Acid Market
Chemicals
Glycerol Carbonate Market
Chemicals
India Ethoxylates Market
Chemicals
Guaiacol Market
Chemicals
Triethanolamine Market
Chemicals
Hexachloroethane Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
North America Methanol Market