
 Premature Ejaculation Treatment Market | 2026-2036
Premature Ejaculation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Premature Ejaculation Treatment Market Outlook
Modular therapy bundles is decoupling the traditional single-modality prescription model, allowing patients to combine topical anesthetics with behavioral counseling under unified care plans. Pfizer leverages its established urology infrastructure to sustain distribution advantages across hospital networks. Eli Lilly and Company anchors its position through psychiatric research pipelines that overlap with off-label SSRI applications. Menarini Group differentiates via European regulatory expertise and specialized men's health portfolios.
Premature ejaculation treatment encompasses pharmacological, topical, and psychotherapeutic interventions designed to extend intravaginal ejaculatory latency time, with topical anesthetics typically containing lidocaine-prilocaine formulations at concentrations between 2.5% and 7.5%. These therapies serve both primary care and specialist urology channels, addressing a condition affecting clinical populations across age demographics. Oral tablet formulations within the delivery mode segment occupy the deepest margin pools due to manufacturing scale and reimbursement familiarity, while counseling approaches represent the fastest-expanding category as telehealth platforms reduce access barriers. Home care end users are reshaping channel economics, diverting volumes from traditional hospital settings toward direct-to-patient distribution.
The FDA governs new drug approvals and labeling claims for premature ejaculation therapeutics, while the EMA oversees centralized marketing authorizations across European member states, with both agencies intensifying scrutiny on combination product classifications. HIPAA compliance requirements shape how telehealth platforms collect and transmit patient data for sexual dysfunction consultations. Stakeholders must monitor evolving pharmacovigilance obligations for off-label SSRI use and anticipate how decentralized clinical trial models will alter evidence-generation pathways for behavioral technique interventions.
Market Dynamics
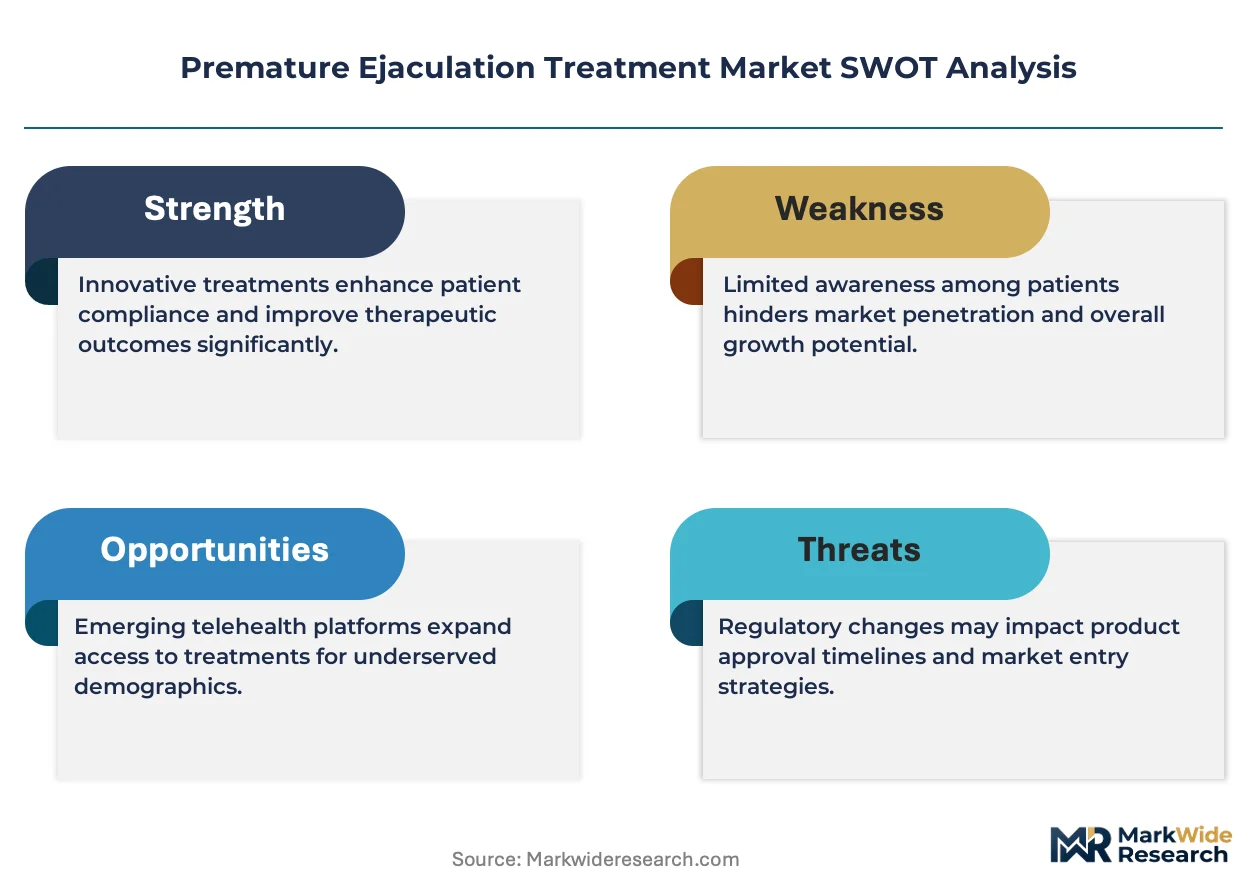
Telehealth platforms are compressing patient acquisition costs and redirecting treatment volumes away from traditional urology clinics toward direct-to-consumer channels, fundamentally restructuring how premature ejaculation therapeutics reach end users.
Growth Catalysts
- FDA Accelerated Review Pathways:Expedited timelines for men's health therapeutics compress product development cycles and reduce regulatory capital requirements for novel topical formulations.
- SSRI Off-Label Utilization:Psychiatric research pipelines generate clinical evidence that expands prescriber comfort with antidepressant applications in sexual dysfunction protocols.
- Home Care Distribution Expansion:Direct-to-patient shipping infrastructure eliminates pharmacy intermediaries and captures margin previously allocated to hospital outpatient settings.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Lidocaine and prilocaine supply chains cluster among Chinese chemical manufacturers, exposing formulation costs to export duty volatility.
- Combination Product Classification Uncertainty:FDA and EMA diverge on whether behavioral-therapeutic bundles constitute single entities or separate regulated products, creating compliance friction.
- Behavioral Technique Substitution:Unregulated pelvic floor training applications and mindfulness protocols compete directly with pharmacological interventions at zero marginal cost.
Strategic Opportunities
- European Regulatory Arbitrage:Menarini Group's established EMA relationships offer template pathways for competitors seeking centralized marketing authorizations across member states.
- Decentralized Clinical Trial Models:Telehealth platforms enable remote endpoint collection for behavioral technique validation, collapsing traditional evidence-generation timelines.
- Modular Therapy Bundling:Unified care plans integrating topical anesthetics with synchronous counseling sessions command premium positioning against single-modality prescriptions.
Industry Challenges
- HIPAA Technical Safeguards:Sexual dysfunction telehealth platforms face heightened audit scrutiny for encryption standards governing intimate health data transmission.
- Pharmacovigilance Integration:Off-label SSRI adverse event reporting requires coordination between psychiatric and urology specialty databases lacking interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premature Ejaculation Treatment Market |
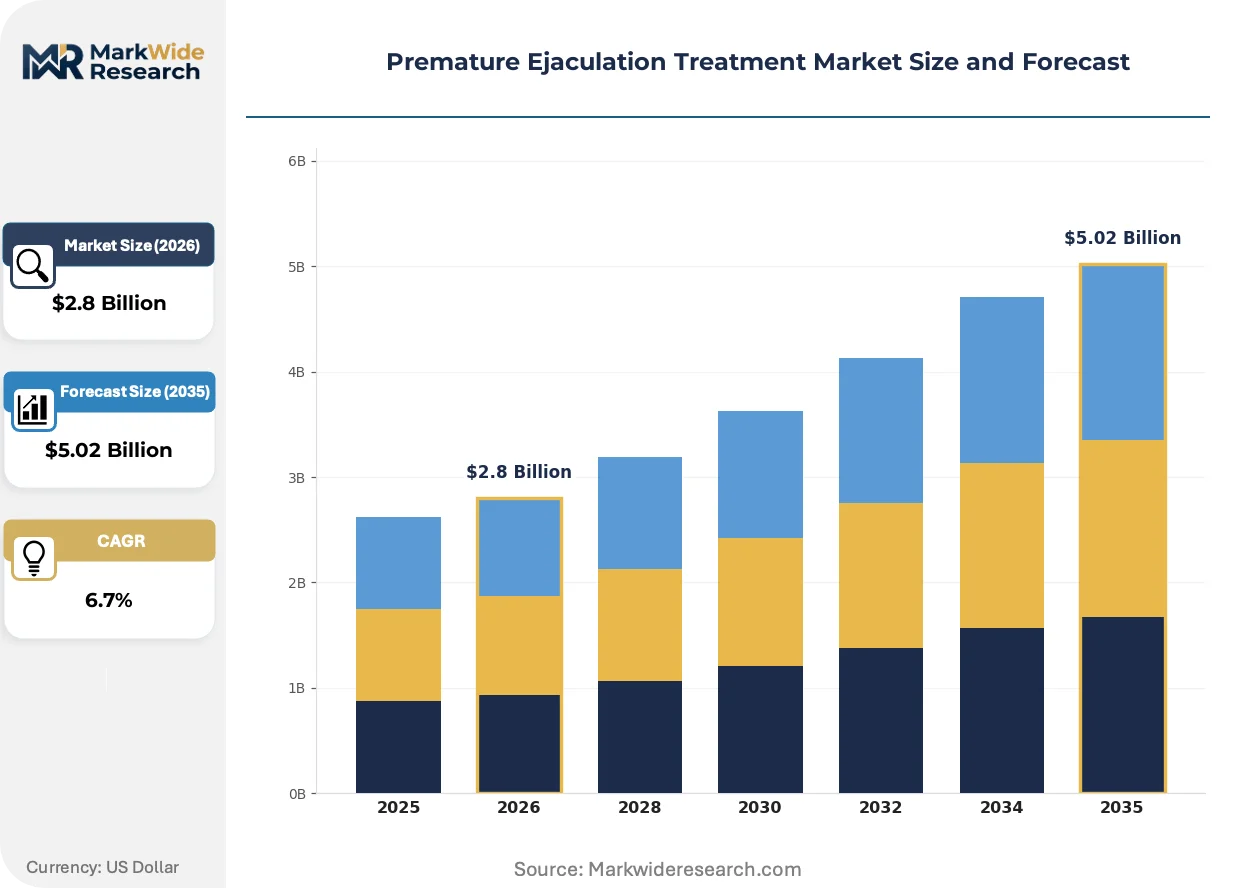
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Anesthetics, SSRIs, PDE5 Inhibitors, Behavioral Techniques Delivery Mode: Oral Tablets, Creams, Injections, Counseling End User: Clinics, Hospitals, Home Care, Pharmacies Therapy Area: Men's Health, Urology, Psychiatry, Sexual Dysfunction |
| Companies Covered | Pfizer, GlaxoSmithKline Plc, Bayer AG, Eli Lilly and Company, Menarini Group, Johnson & Johnson, Alembic Pharmaceuticals Ltd., Absorption Pharmaceuticals, Plethora Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premature Ejaculation Treatment Market Strategic Shifts
Digital health infrastructure is collapsing the traditional separation between diagnostic assessment, therapeutic delivery, and outcome monitoring into continuous patient engagement loops.
Topical anesthetic formulations are converging with connected device delivery systems. Wearable vibration-dampening technologies now coordinate lidocaine-prilocaine application timing with physiological monitoring, enabling real-time dosage adjustment. Urology telehealth platforms are adopting these integrated systems fastest, compressing the gap between symptom reporting and intervention modification.
EMA intensified scrutiny on combination product classifications reshapes how manufacturers structure regulatory submissions. The agency now demands separate clinical evidence for behavioral and pharmacological components when bundled under single brand identities. European urology clinics are responding by unbundling care plans into distinct billable elements to preserve reimbursement pathways.
Subscription-based access models displace per-prescription purchasing across direct-to-consumer channels. Patients now expect unlimited clinician messaging and automated refill logistics bundled into monthly fees. This shift is most visible in United States markets where telehealth platforms compete on retention metrics rather than acquisition volume alone.
Premature Ejaculation Treatment Market Segmentation
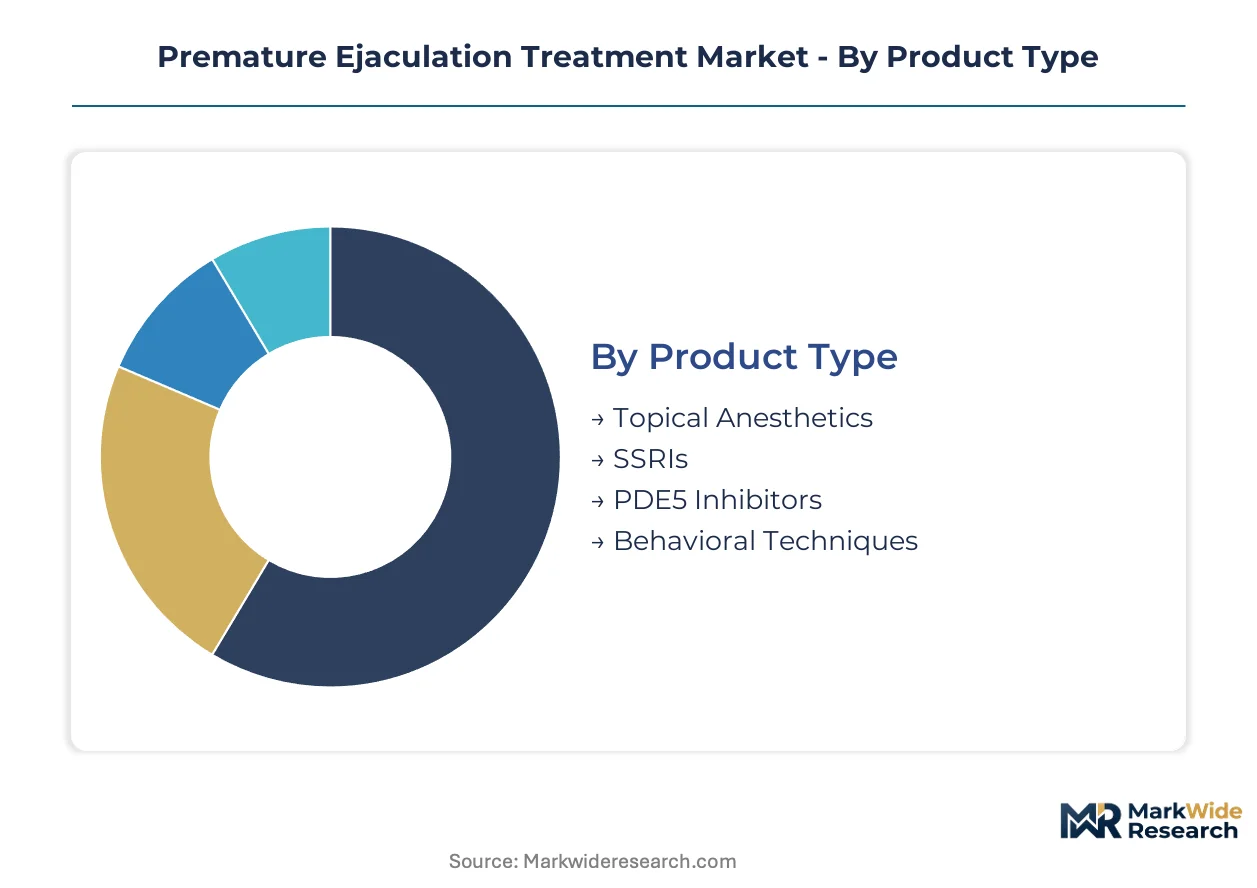
Segmentation in premature ejaculation therapeutics reveals divergent margin structures and access pathways. Product type determines regulatory complexity, while delivery mode shapes patient adherence and reimbursement dynamics.
Product Type:
Standalone pharmacological agents dominate prescription volumes, whereas behavioral techniques increasingly embed within telehealth platforms as bundled service components.
- Topical Anesthetics:Lidocaine-prilocaine formulations at 2.5-7.5% concentrations provide localized desensitization with minimal systemic absorption. Demand clusters in United States direct-to-consumer channels where telehealth platforms bypass traditional urology gatekeeping.
- SSRIs:Sertraline, paroxetine, and fluoxetine deployed off-label extend intravaginal ejaculatory latency through serotonin modulation. Psychiatric prescribing networks in Germany and France generate the deepest prescription pools, though FDA labeling constraints limit formal indication expansion.
- PDE5 Inhibitors:Sildenafil and tadalafil address comorbid erectile dysfunction rather than primary ejaculatory control.
- Behavioral Techniques:Stop-start and squeeze methods delivered via synchronous telehealth counseling.
Volume placements concentrate in SSRIs; the faster expansion belongs to behavioral techniques.
Delivery Mode:
Cost tier stratification separates high-margin oral formulations from labor-intensive counseling services, with device-coordinated topical systems occupying an emerging premium tier.
- Oral Tablets:Compressed dosage forms achieve manufacturing scale economies through existing psychiatric production lines. Hospital outpatient departments in Japan and South Korea maintain the densest prescribing concentrations, supported by national reimbursement formularies.
- Creams:Semi-solid emulsions requiring compounding pharmacy preparation face batch consistency challenges under FDA current good manufacturing practice standards.
- Injections:Intracavernosal and intrapenile delivery routes reserved for refractory cases.
- Counseling:Synchronous video-based behavioral coaching integrated with asynchronous messaging platforms. United Kingdom and Netherlands telehealth providers are gaining share fastest through subscription bundling.
Oral tablets capture the deepest margin pools; counseling climbs the fastest as platform economics reshape patient acquisition.
End User:
Customer type segmentation tracks the migration from institutional reimbursement toward direct-pay consumption, with channel economics diverging sharply across settings.
- Clinics:Specialist urology practices in urban United States markets combine diagnostic workup with procedure-based revenue streams.
- Hospitals:Academic medical centers in France and Italy anchor complex case referrals and combination therapy protocols.
- Home Care:Direct-to-patient shipping infrastructure eliminates pharmacy intermediaries. Australian and Canadian regulatory frameworks for remote prescribing are expanding fastest.
- Pharmacies:Community dispensing faces margin compression from 90-day mail-order substitution and cash-pay telehealth bypass.
Hospital placements retain the highest average revenue per patient; home care is displacing institutional volumes most aggressively.
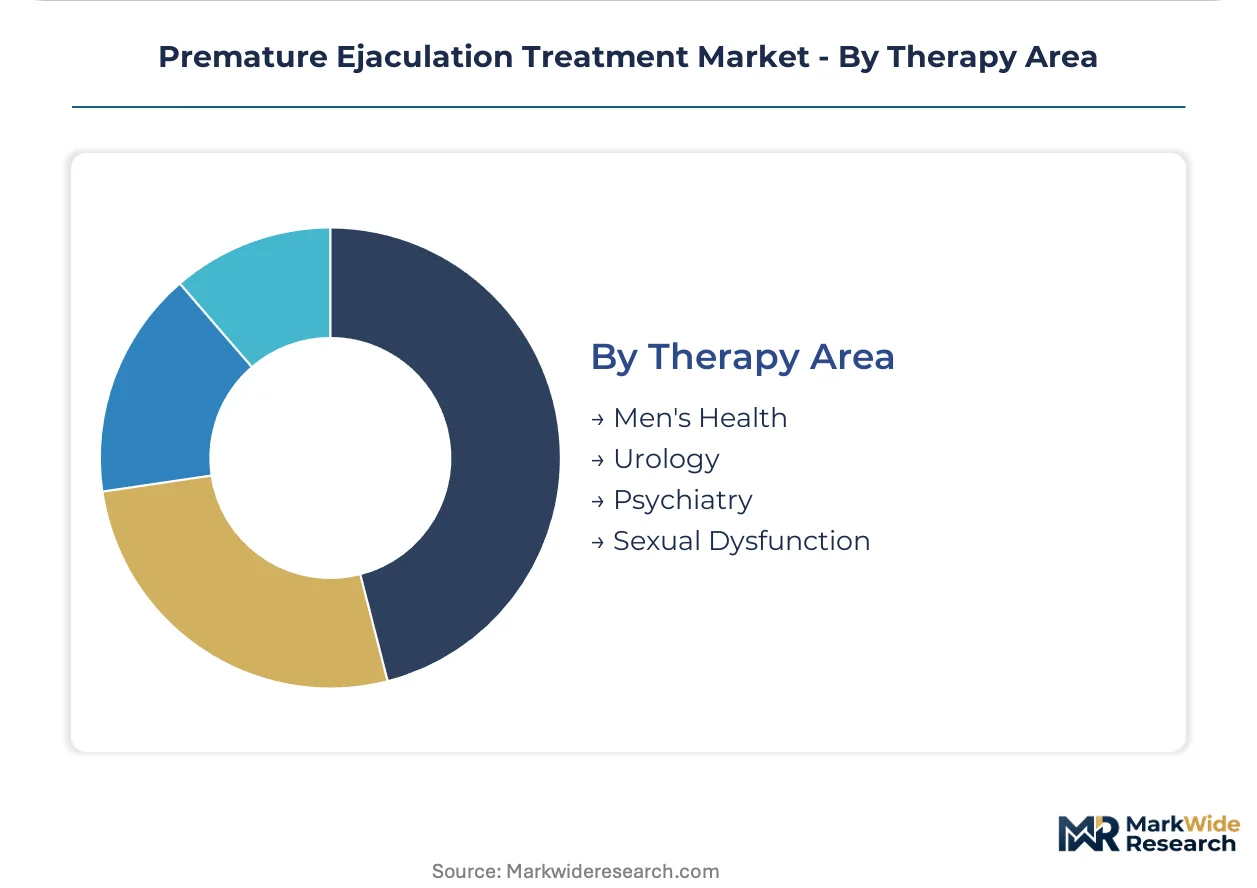
Therapy Area:
Maturity gradients separate established urology channels from emerging psychiatric-sexual medicine convergence, with cross-specialty prescribing reshaping competitive dynamics.
- Men's Health:Dedicated clinics and direct-to-consumer brands aggregate erectile dysfunction, testosterone deficiency, and ejaculatory disorders under unified service models. Brazil and Mexico show the steepest clinic network expansion.
- Urology:Traditional surgical and medical management of male genitourinary conditions. German and Swiss urology societies publish the most influential clinical practice guidelines.
- Psychiatry:SSRI prescribing for anxiety and mood disorders generates off-label spillover into sexual dysfunction protocols.
- Sexual Dysfunction:Emerging specialty bridging urology, gynecology, and psychology with interdisciplinary assessment frameworks.
Urology anchors current prescription volumes; sexual dysfunction specialty services are expanding most quickly as certification programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of active pharmaceutical ingredients clusters in China and India, while consumption concentrates in North American and European markets where telehealth infrastructure enables direct-to-patient distribution. This geographic split shapes regulatory compliance requirements and supply chain risk profiles across the value chain.
United States
Telehealth platforms capture patient volumes through direct-to-consumer marketing, bypassing traditional urology clinic gatekeeping. FDA accelerated review pathways for men's health therapeutics compress development timelines for novel topical formulations. Boston and San Francisco anchor the densest concentrations of digital health startups integrating behavioral counseling with pharmacological delivery.
Germany
Psychiatric prescribing networks generate deep prescription pools for off-label SSRI applications in sexual dysfunction protocols. The national pharmaceutical regulator maintains stringent pharmacovigilance requirements for antidepressant adverse event reporting. Munich and Frankfurt host specialized men's health clinics combining urology services with psychiatric consultation frameworks.
United Kingdom
Subscription-based telehealth providers gain market share through bundled messaging and automated refill logistics. GDPR compliance requirements shape encryption standards for intimate health data transmission on sexual dysfunction platforms. London dominates platform headquarters concentration, with Manchester emerging as a secondary hub for remote counseling service delivery.
Japan
Hospital outpatient departments maintain dense prescribing concentrations for oral tablet formulations, supported by national reimbursement formularies. PMDA oversight governs new drug approvals and labeling claims for premature ejaculation therapeutics. Tokyo and Osaka anchor specialist urology practice networks that combine diagnostic workup with procedure-based revenue streams.
Australia
Remote prescribing regulatory frameworks expand fastest among Commonwealth markets, enabling direct-to-patient shipping infrastructure. TGA governs marketing authorizations for topical anesthetic formulations containing lidocaine-prilocaine. Sydney and Melbourne concentrate telehealth platform operations targeting home care end users with subscription access models.
Premature Ejaculation Treatment Market Competitive Environment
The competitive structure tilts toward pharmaceutical incumbents with established urology and psychiatric prescribing networks. Large multinational drug manufacturers occupy the premium tier through manufacturing scale and regulatory expertise, while specialized telehealth platforms capture growth in direct-to-consumer channels. Three archetypes dominate: legacy pharmaceutical conglomerates with diversified men's health portfolios, regional specialists leveraging regulatory arbitrage across European markets, and digital-native platforms integrating behavioral and pharmacological interventions. M&A activity concentrates on telehealth platform acquisitions by pharmaceutical distributors, and portfolio diversification moves target combination therapy bundling capabilities.
Among pharmaceutical incumbents, Pfizer and Eli Lilly and Company exemplify the diversified archetype, with the former representing established urology infrastructure advantages and the latter anchoring psychiatric research pipeline overlap with off-label SSRI applications. Menarini Group occupies a position exemplifying European regulatory specialization, leveraging centralized EMA relationship templates for competitors seeking marketing authorizations across member states. These three entities represent distinct competitive positioning vectors: manufacturing scale, research pipeline depth, and regional regulatory expertise.
| Leading Market Players |
|---|
| Pfizer |
| GlaxoSmithKline Plc |
| Bayer AG |
| Eli Lilly and Company |
| Menarini Group |
| Johnson & Johnson |
| Alembic Pharmaceuticals Ltd. |
| Absorption Pharmaceuticals |
| Plethora Solutions |
| Others |
Value Chain & Pricing Dynamics
Direct-to-consumer telehealth procurement preferences for subscription-based access are forcing formulation manufacturers to restructure batch production toward smaller, more frequent runs, compressing unit economics and amplifying price sensitivity at the standard tier.
Pricing Analysis
Margin tightening in oral tablet formulations reflects manufacturing scale advantages inherited from psychiatric production lines. Three-tier pricing structure across premium connected-device bundles, standard topical-counseling combinations, and economy standalone anesthetics separates reimbursement-eligible hospital prescriptions from cash-pay telehealth channels. Cost-down pressure on topical anesthetics accelerates because lidocaine-prilocaine API sourcing clusters in Chinese chemical manufacturers exposed to export duty volatility. Home care end users exhibit the highest price sensitivity, while hospital outpatient departments retain negotiating leverage through formulary volume commitments.
Supply Chain Analysis
Dual-sourcing qualification requirements for lidocaine and prilocaine active pharmaceutical ingredients are expanding manufacturer audit obligations across Chinese and Indian chemical suppliers. Raw material dependencies center on petrochemical-derived base compounds, specialized pharmaceutical-grade solvents, and precision dosing device components from Taiwanese electronics manufacturers. Supply chain risk hinges on single-source vulnerability for high-purity API batches meeting FDA current good manufacturing practice standards. Distribution runs through direct-to-patient shipping infrastructure that eliminates traditional pharmacy intermediaries and captures margin previously allocated to hospital outpatient settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected device delivery systems coordinating real-time dosage adjustment with physiological monitoring are displacing standalone topical formulations, compressing development timelines for legacy manufacturers while opening white-space for digital-native platform builders.
For Market Incumbents: Anticipate telehealth platform vertical integration into formulation compounding by securing captive API supply agreements with Indian and Chinese manufacturers. Defensive consolidation should prioritize EMA centralized marketing authorization templates to preempt competitor regulatory arbitrage. Prioritize backward integration into lidocaine-prilocaine synthesis to offset API cost volatility threatening standard-tier margins.
For New Entrants and Emerging Players: Begin with behavioral technique validation through decentralized clinical trial models that collapse evidence-generation timelines for synchronous counseling platforms. The most penetrable segment lies in European markets where GDPR-compliant encryption standards for intimate health data transmission create compliance moats against US-platform expansion. Pursue psychiatric prescriber network partnerships in Germany and France to capture off-label SSRI spillover volumes.
For Investors and Strategic Acquirers: The window for entry favors telehealth platforms with integrated device-formulation bundles and established HIPAA technical safeguard audit trails. Long-term viability rests on acquiring capabilities that bridge pharmacological delivery with continuous patient engagement loops rather than standalone prescription models. Monitor FDA combination product classification rulings as the critical inflection signal for bundled therapy reimbursement eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated review for men's health therapeutics compresses novel topical formulation timelines against standard NDA tracks. |
| Platform Integration | Telehealth platforms embedding connected vibration-dampening devices with lidocaine-prilocaine delivery capture premium positioning. |
| Backward Integration | Captive API manufacturing insulates formulation costs from Chinese export duty volatility affecting prilocaine supply. |
| Strategic Partnership | Psychiatric prescriber network alliances in Germany generate off-label SSRI volumes for sexual dysfunction protocols. |
| Geographic Expansion | EMA centralized marketing authorizations leverage Menarini Group relationship templates across European member states. |
Study Parameters
Independent corroboration across urology clinic prescribing data, telehealth platform operational metrics, and pharmaceutical regulatory filings underwrites the qualitative findings. Primary interviews with drug development executives at topical anesthetic manufacturers, regulatory affairs leads navigating FDA combination product classifications, formulary directors at German psychiatric prescribing networks, and hospital procurement managers in Japanese academic medical centers combined with secondary validation from FDA 510(k) submissions, EMA centralized procedure documentation, ClinicalTrials.gov behavioral technique intervention records, and national reimbursement formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation-specific estimates.
Rate-of-change decomposition across product type, delivery mode, end user, and therapy area dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by reimbursement pathway maturity and telehealth platform penetration curves. Modeled inputs included off-label SSRI prescription spillover rates from psychiatric to urology channels, connected device adoption curves in United States direct-to-consumer markets, and EMA regulatory timeline differentials for centralized versus national marketing authorizations.
Underlying measurement precision varies by segment; telehealth platform operational metrics carry tighter precision than behavioral technique outcome data reliant on patient-reported measures. Forecasts reflect assumptions regarding FDA accelerated review pathway continuity, HIPAA technical safeguard enforcement intensity, and API supply chain stability across Chinese manufacturing clusters. Deviation in EMA combination product classification rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Neurometabolic Disorder Market