
 CARD9 Deficiency Treatment Market | 2026-2036
CARD9 Deficiency Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
CARD9 Deficiency Treatment Market Outlook
Modular combination regimens is rebalancing how clinicians configure CARD9 deficiency protocols, shifting from monotherapy toward bundled immunotherapy-cytokine sequences. Novartis AG leverages its cell therapy infrastructure to anchor European hospital networks. Pfizer Inc competes through manufacturing scale across intravenous and subcutaneous delivery formats. Gilead Sciences differentiates via cytokine therapy specialization in transplant centers.
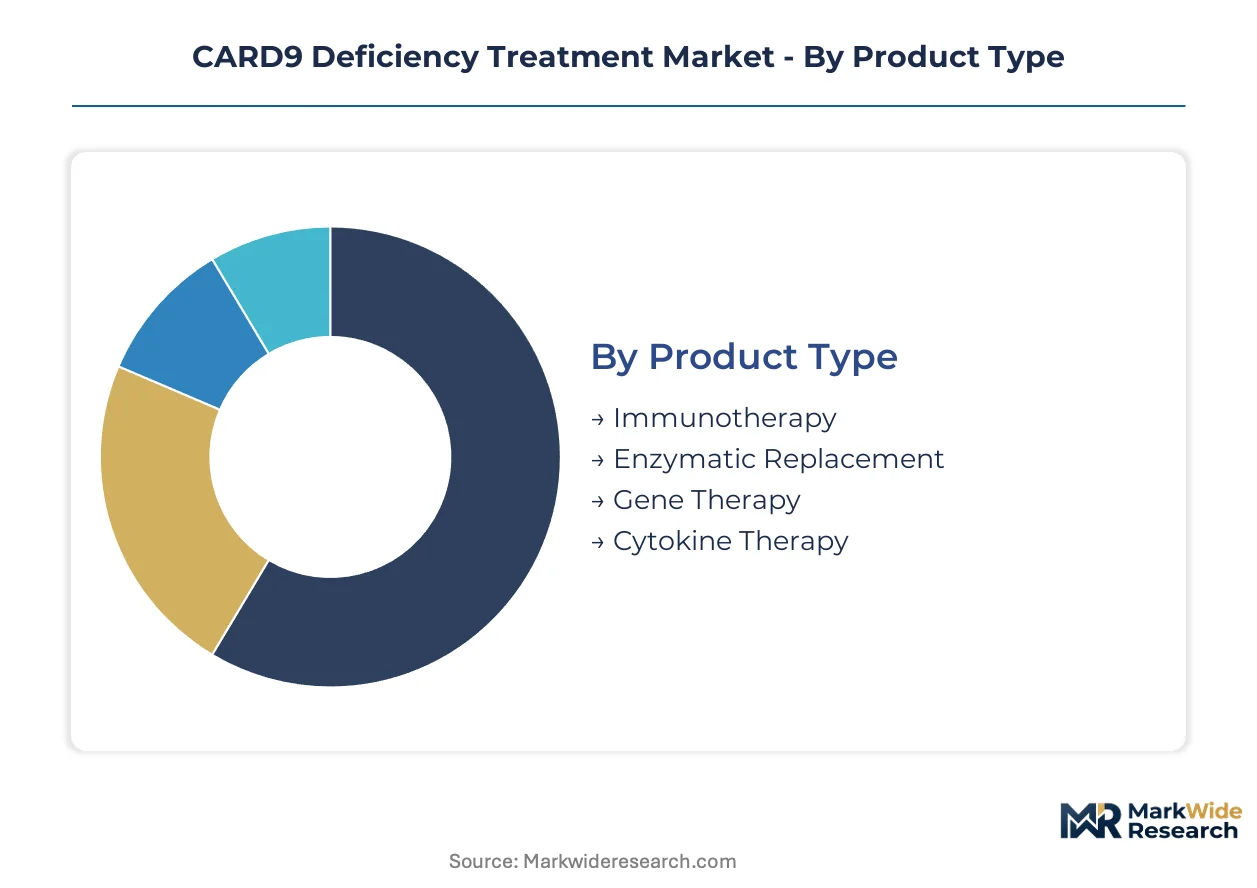
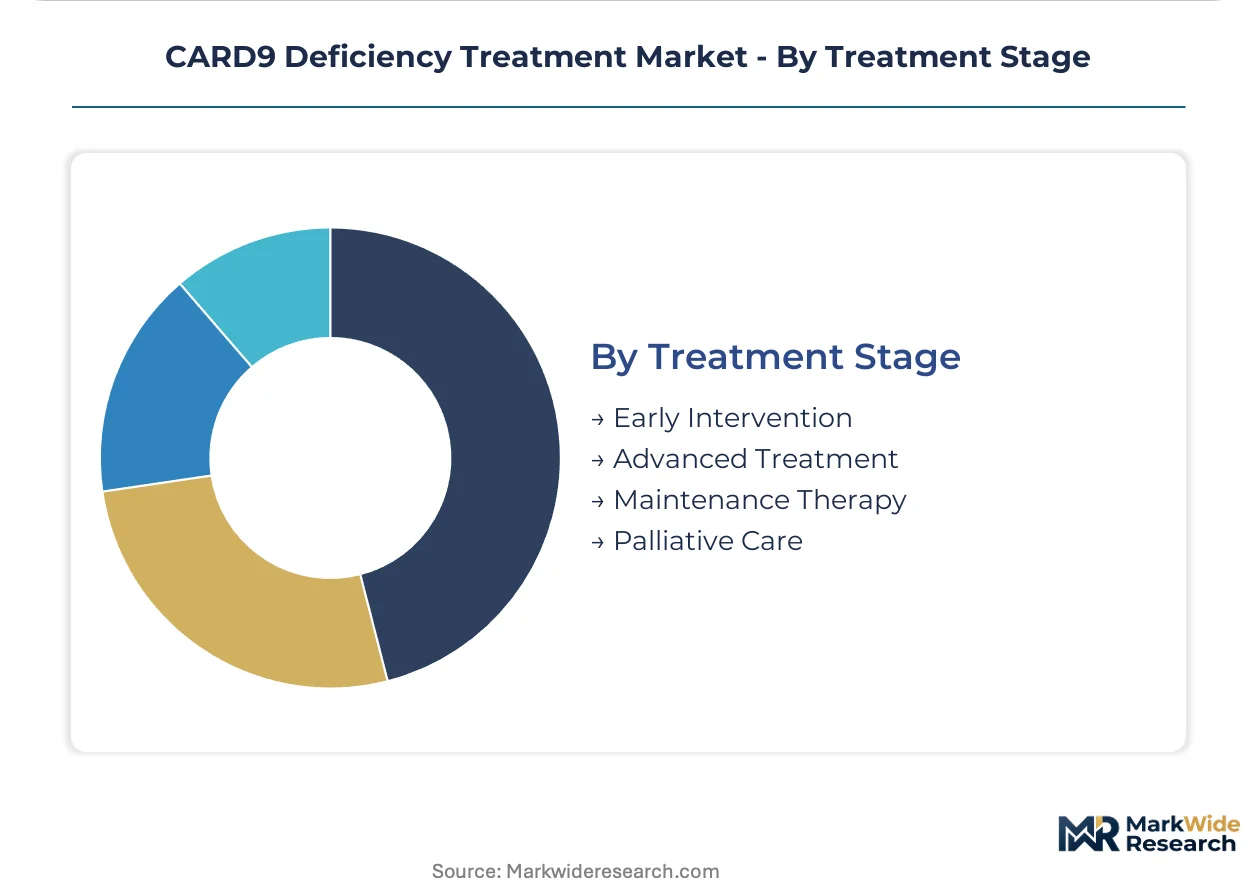
CARD9 deficiency treatment encompasses therapeutic interventions targeting autosomal recessive CARD9 gene mutations that impair antifungal immune signaling, typically involving recombinant cytokine infusions or hematopoietic gene correction delivered through validated viral vectors. The primary purpose is restoring neutrophil-mediated Candida and Aspergillus defense in profoundly immunocompromised patients. Immunotherapy occupies the dominant revenue position due to established hospital reimbursement pathways, while gene therapy represents the fastest-expanding segment as manufacturing yields improve for lentiviral and AAV platforms. Early intervention commands premium pricing relative to maintenance therapy, though palliative care volumes expand with delayed diagnosis in emerging referral networks.
FDA orphan drug designation and EMA's rare disease protocol assistance shape clinical trial design and market exclusivity timelines for developers. ISO 14155 and ICH-GCP standards govern gene therapy investigational protocols, directly influencing site qualification and patient enrollment velocity. Japan's PMDA sakigake designation adds a third regulatory acceleration pathway for prioritized review. Stakeholders must monitor manufacturing capacity constraints for personalized gene therapies against expanding eligible patient identification through newborn sequencing programs.
Market Dynamics
Hospital-based immunotherapy adoption is consolidating around modular cytokine-gene therapy combinations, driven by transplant center demand for antifungal prophylaxis protocols and FDA orphan drug incentives compressing development timelines.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market exclusivity and tax credits accelerate clinical trial enrollment for CARD9-targeted therapies, reducing sponsor risk capital requirements.
- Newborn Sequencing Expansion:State-level genomic screening programs in the United States identify presymptomatic CARD9-deficient infants, expanding addressable patient pools before invasive fungal infection onset.
- Lentiviral Manufacturing Scale-Up:Contract development organizations in Germany and Switzerland achieve GMP-compliant viral vector yields exceeding prior-generation platforms by an order of magnitude.
Market Restraints
- AAV Capsid Supply Concentration:Three North American suppliers control majority GMP-grade viral vector capacity, creating queue bottlenecks for gene therapy sponsors.
- Reimbursement Uncertainty:CMS and commercial payers lack established coding for single-administration gene therapies, forcing provisional payment mechanisms that delay site adoption.
- Plasmid DNA Cost Volatility:Raw material pricing for transfection-grade plasmids fluctuates with mRNA vaccine manufacturing demand cycles.
Strategic Opportunities
- Japan PMDA Sakigake Pathway:Priority review designation for rare disease gene therapies enables six-month approval timelines, attracting sponsor investment ahead of European market entry.
- Subcutaneous Cytokine Formulations:Self-administration potential outside hospital settings addresses patient convenience gaps in maintenance therapy protocols.
- CRISPR Base Editing Convergence:Integration of precision editing with ex vivo stem cell modification offers permanent correction without viral vector immunogenicity risks.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:GMP-compliant cell culture and viral vector purification expertise concentrates in Boston, Basel, and Singapore hubs, constraining site qualification velocity.
- ICH-GCP Protocol Complexity:Multi-year pediatric follow-up requirements for gene therapy trials extend study durations and inflate per-patient costs.
- Cross-Border Sample Logistics:Temperature-controlled transport of patient-derived hematopoietic stem cells across regulatory jurisdictions introduces customs clearance friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CARD9 Deficiency Treatment Market |
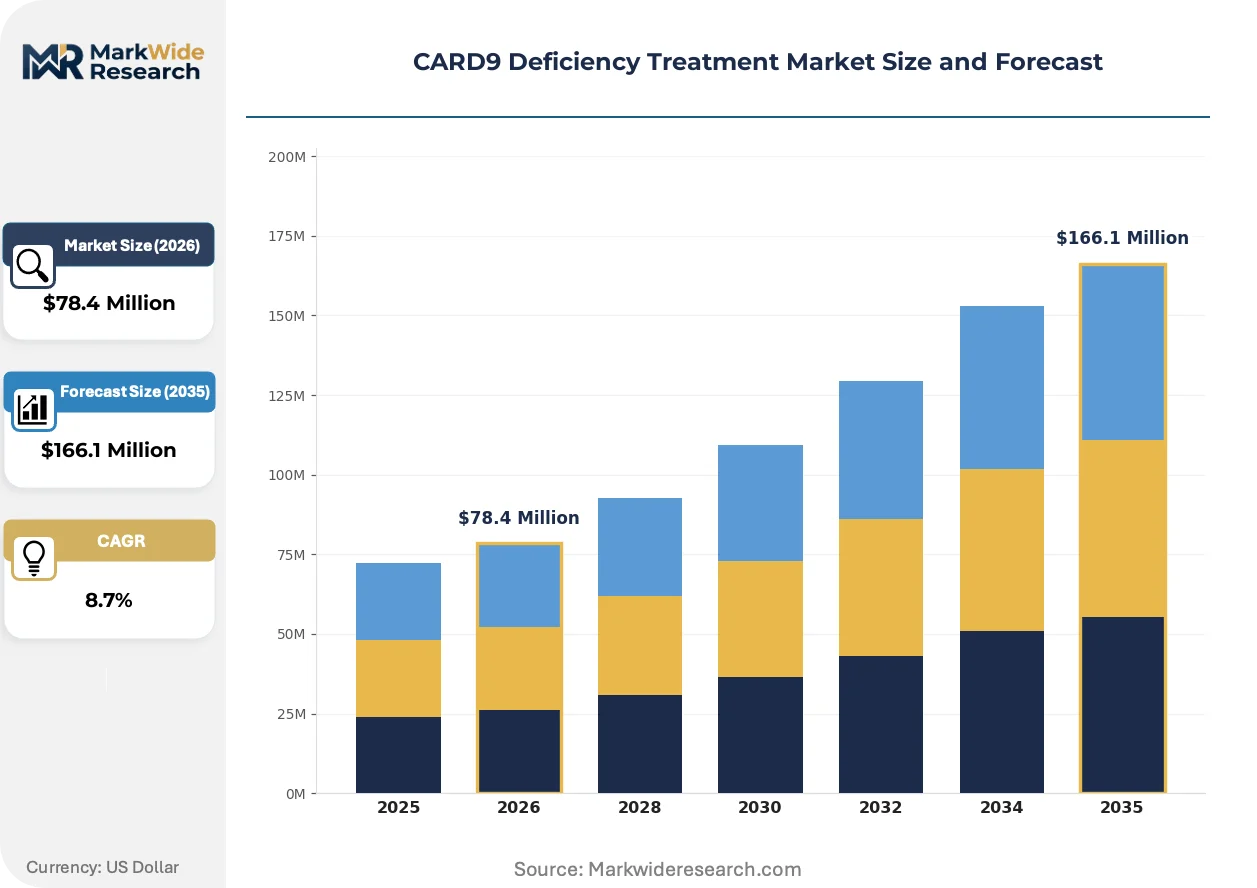
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $166.1 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Enzymatic Replacement, Gene Therapy, Cytokine Therapy Delivery Mode: Intravenous, Subcutaneous, Oral, Local End User: Hospitals, Specialty Clinics, Research Laboratories, Homecare Treatment Stage: Early Intervention, Advanced Treatment, Maintenance Therapy, Palliative Care |
| Companies Covered | Novartis AG, Pfizer Inc, GlaxoSmithKline plc, Biogen Inc, Gilead Sciences, AbbVie Inc, Sanofi, Merck & Co, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CARD9 Deficiency Treatment Market Strategic Shifts
Modular immunotherapy-cytokine sequencing is displacing monotherapy protocols across transplant centers, while regulatory acceleration pathways and vector manufacturing advances compress development-to-commercialization timelines.
Lentiviral vector production is consolidating as the dominant gene delivery platform for CARD9 deficiency, replacing earlier gamma-retroviral approaches due to superior transduction efficiency in hematopoietic stem cells. European contract manufacturers in Germany and Switzerland are expanding GMP suites dedicated to autoimmunity and primary immunodeficiency indications. This platform consolidation is compressing cost-per-dose estimates and enabling sponsor portfolio expansion beyond oncology into rare immunology.
EMA's rare disease protocol assistance framework is reshaping clinical trial design requirements, mandating adaptive enrollment structures and real-world evidence integration for post-authorization follow-up. Sponsors must now incorporate patient-reported outcome measures and long-term safety registries into Phase I/II protocols. Gene therapy developers targeting CARD9 deficiency are responding by establishing European reference centers in Paris and Munich to anchor multinational trial networks.
Academic medical center procurement patterns are pivoting toward bundled cytokine-immunotherapy contracts, displacing single-product purchasing agreements that dominated prior reimbursement cycles. Transplant pharmacy directors at US News-ranked hospitals now negotiate multi-year supply commitments spanning prophylaxis through salvage therapy. This concentration is most visible in the Northeastern United States, where consolidated health systems leverage volume commitments against specialty pharmacy distributors.
CARD9 Deficiency Treatment Market Segmentation
CARD9 deficiency treatment configurations diverge sharply by clinical setting and patient immunological status. Product selection hinges on fungal infection severity, transplant history, and vector manufacturing availability.
Product Type:
Hospital pharmacy directors prioritize reimbursement certainty and manufacturing reliability when selecting therapeutic platforms.
- Immunotherapy:Recombinant cytokine infusions and monoclonal antibody protocols restore neutrophil-mediated antifungal signaling. Demand concentrates in United States transplant centers where CMS-established billing codes accelerate procurement. Established hospital reimbursement pathways anchor revenue concentration despite premium pricing.
- Gene Therapy:Lentiviral and AAV-mediated CARD9 gene correction delivered through validated viral vectors offers permanent functional restoration. Manufacturing yields in Germany and Switzerland are climbing fastest, compressing cost-per-dose estimates as GMP suites expand. Vector immunogenicity risks and multi-year follow-up requirements constrain near-term adoption velocity.
- Enzymatic Replacement:Exogenous enzyme supplementation for downstream signaling pathway restoration.
- Cytokine Therapy:Targeted interleukin administration to bypass defective CARD9-dependent signaling cascades.
Immunotherapy leads on scale; gene therapy leads on momentum.
Delivery Mode:
Route selection tracks patient acuity, vascular access status, and outpatient versus inpatient care settings.
- Intravenous:Hospital-administered infusion for acute invasive fungal infections requiring rapid therapeutic levels. United States oncology and transplant centers dominate procurement volumes. Vascular access complications and infusion center capacity constraints limit scalability.
- Subcutaneous:Self-administration potential outside hospital settings addresses convenience gaps in maintenance protocols. European homecare nursing networks in Germany and France are piloting patient-training programs. Reimbursement coding ambiguity delays broad payer coverage.
- Oral:Small-molecule formulations for prophylactic use in presymptomatic patients identified through newborn screening.
- Local:Topical or intralesional administration for isolated mucocutaneous candidiasis presentations.
Intravenous dominates current volumes; subcutaneous gains share fastest.
End User:
Procurement authority and reimbursement complexity shape site-level adoption patterns across care settings.
- Hospitals:Transplant and oncology centers with specialized immunology infrastructure anchor demand. United States academic medical centers in Boston and New York negotiate bundled cytokine-immunotherapy contracts spanning prophylaxis through salvage therapy. Consolidated health systems leverage volume commitments against specialty pharmacy distributors.
- Specialty Clinics:Dedicated primary immunodeficiency centers in Munich and Paris coordinate multinational trial networks. EMA rare disease protocol assistance mandates adaptive enrollment structures and real-world evidence integration. Long-term safety registry requirements inflate per-patient study costs.
- Research Laboratories:Academic gene therapy development sites and contract manufacturing organizations.
- Homecare:Outpatient nursing services for stable maintenance therapy patients.
Hospitals command procurement volume; specialty clinics anchor clinical evidence generation.
Treatment Stage:
Timing of intervention relative to fungal infection onset determines therapeutic intensity and pricing tier.
- Early Intervention:Presymptomatic treatment of infants identified through state-level genomic screening programs. United States newborn sequencing expansion in California and New York is enlarging addressable pools before invasive infection onset. Premium pricing reflects prevention of irreversible immunological damage.
- Advanced Treatment:Intensive salvage therapy for disseminated Candida or Aspergillus infections in profoundly immunocompromised patients. Japan's PMDA sakigake designation is accelerating approval timelines for gene therapies targeting this population. Mortality risk justifies experimental protocol enrollment.
- Maintenance Therapy:Chronic prophylaxis to prevent recurrence following acute resolution.
- Palliative Care:Symptom management in delayed-diagnosis cases with irreversible end-organ damage.
Early intervention captures pricing premiums; advanced treatment drives enrollment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CARD9 deficiency treatment industry traces its commercial origins to European immunology research clusters in Basel and Munich, where early cytokine replacement protocols were standardized for transplant center networks.
United States
Academic medical centers in Boston and New York anchor procurement volumes through bundled cytokine-immunotherapy contracts spanning prophylaxis through salvage therapy. FDA orphan drug designation provides seven-year market exclusivity and tax credits that compress development timelines. State-level newborn sequencing programs in California and New York are expanding addressable patient pools before invasive fungal infection onset.
Germany
Contract development organizations in Germany and Switzerland achieve GMP-compliant viral vector yields exceeding prior-generation platforms by an order of magnitude. EMA's rare disease protocol assistance mandates adaptive enrollment structures and real-world evidence integration for post-authorization follow-up. European reference centers in Munich anchor multinational trial networks for gene therapy developers.
Japan
PMDA's sakigake designation enables six-month approval timelines for rare disease gene therapies, attracting sponsor investment ahead of European market entry. Mortality risk in disseminated Candida or Aspergillus infections justifies experimental protocol enrollment. The Kanto region concentrates specialized immunology infrastructure and transplant center demand.
Switzerland
GMP suites in Basel dedicated to autoimmunity and primary immunodeficiency indications are expanding lentiviral manufacturing capacity. Swissmedic regulates gene therapy investigational protocols under ICH-GCP standards that directly influence site qualification velocity. The Basel hub concentrates GMP-compliant cell culture and viral vector purification expertise.
France
European reference centers in Paris coordinate multinational trial networks under EMA rare disease framework requirements. Long-term safety registry requirements inflate per-patient study costs for gene therapy trials. The Île-de-France region anchors clinical evidence generation through dedicated primary immunodeficiency centers.
CARD9 Deficiency Treatment Market Competitive Environment
Premium-margin players sit above commodity-margin players across manufacturing reliability and regulatory navigation capabilities. The vendor base organizes into three tiers: multinational pharmaceutical conglomerates with cell therapy infrastructure, specialized biotechnology firms with cytokine therapy focus, and emerging gene therapy developers with viral vector platforms. Consolidation pressures favor players with captive GMP manufacturing capacity. Dominant competitive moves include strategic partnerships with European contract manufacturers and portfolio diversification into modular combination regimens.
Within the multinational conglomerate tier, Novartis AG and Pfizer Inc exemplify scale-driven positioning across intravenous and subcutaneous delivery formats. Gilead Sciences occupies a distinct position through cytokine therapy specialization in transplant centers. These three companies anchor the competitive structure while representing divergent strategic archetypes: platform infrastructure leverage, manufacturing scale deployment, and therapeutic area concentration.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc |
| GlaxoSmithKline plc |
| Biogen Inc |
| Gilead Sciences |
| AbbVie Inc |
| Sanofi |
| Merck & Co |
| AstraZeneca plc |
| Others |
Value Chain & Pricing Dynamics
EMA's rare disease protocol assistance gates qualified supply access for CARD9 deficiency therapies, permitting premium-tier pricing only to sponsors demonstrating adaptive enrollment structures and real-world evidence integration. FDA orphan drug designation and Japan's PMDA sakigake pathway create parallel qualification tracks that segment pricing power by regulatory geography.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates gene therapy from cytokine replacement from palliative supportive care. Price differentiation rests on manufacturing complexity and follow-up duration, with lentiviral vector products commanding the highest tier. Cost compression in standard-tier cytokine protocols is intensifying as subcutaneous formulations expand manufacturing scale. Academic medical centers in the United States demonstrate lowest price sensitivity due to bundled contract structures, while emerging referral networks in Asia-Pacific remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with North American AAV capsid suppliers, where three GMP-grade manufacturers control majority viral vector capacity. Geographic supply concentration centers on Germany, Switzerland, and the United States for lentiviral production and cytokine manufacturing. Raw material dependencies include transfection-grade plasmid DNA, recombinant protein media, and cryopreservation reagents. Tariff exposure on European-sourced vector components introduces customs clearance friction for cross-border stem cell logistics. Distribution runs through specialty pharmacy networks anchored by consolidated health systems in the Northeastern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as transplant centers pivot toward modular cytokine-gene therapy combinations that demand higher specification tiers. The shift from monotherapy to bundled prophylaxis protocols elevates premium-tier positioning.
For Market Incumbents: Extend manufacturing scale advantages into subcutaneous cytokine formulations before emerging gene therapy developers achieve cost parity. Lock in multi-year supply commitments with European contract manufacturers to defend against AAV vector queue bottlenecks. Invest in CRISPR base editing capabilities as a hedge against lentiviral immunogenicity risks.
For New Entrants and Emerging Players: Specialty clinics in Japan's Kanto region present an underserved buyer archetype where PMDA sakigake designation accelerates approval timelines ahead of European entry. Target homecare nursing networks in Germany and France piloting patient-training programs for maintenance therapy. Pursue licensing partnerships with Basel-based GMP suites to bypass captive capacity constraints.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap gene therapy developers with validated viral vector platforms because manufacturing talent scarcity in Boston, Basel, and Singapore constrains organic expansion. Five-to-ten year viability hinges on permanent correction technologies displacing chronic cytokine dependence. Monitor newborn sequencing expansion in California and New York as the signal indicating addressable patient pool inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP-compliant lentiviral yields in Germany and Switzerland compress cost-per-dose estimates for gene therapy sponsors. |
| Regulatory Approval Pathway | PMDA sakigake designation in Japan enables six-month timelines that attract sponsor investment ahead of European entry. |
| Clinical Trial Advancement | Adaptive enrollment structures mandated by EMA rare disease protocol assistance reshape Phase I/II protocol design requirements. |
| Pipeline Diversification | CRISPR base editing integration offers permanent CARD9 correction without viral vector immunogenicity risks. |
| Strategic Partnership | European reference centers in Paris and Munich anchor multinational trial networks under EMA framework requirements. |
Study Parameters
Coverage spans the United States, Germany, Japan, Switzerland, and France, with primary inputs from each combining drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation. Sources include FDA orphan drug filings, EMA rare disease protocol submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up patient pool estimates and top-down revenue triangulation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include treatment stage, delivery mode, end user, and regional regulatory cluster. CAGRs derive from patient identification velocity through newborn screening, manufacturing yield improvements, and reimbursement pathway establishment. Forecast inputs incorporate vector manufacturing capacity expansion timelines and transplant center procurement pattern shifts.
Underlying measurement precision varies by segment; early intervention and gene therapy carry tighter precision than palliative care due to established newborn screening data and clinical trial enrollment tracking. Forecasts reflect assumptions about regulatory acceleration pathway utilization and vector manufacturing yield trajectories that could revise with plasmid DNA cost volatility or reimbursement coding delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Open Angle Glaucoma Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Dementia Management Market