
 Griffin Beaker Market | 2026-2036
Griffin Beaker Market Size, Share, and Industry Trends Forecast 2026-2036
Griffin Beaker Market Foresight
Capital-intensity divergence between automated borosilicate forming lines and manual glassblowing operations is redrawing competitive boundaries in the Griffin Beaker Market. Corning Inc. leverages captive fusion-draw technology to sustain cost leadership in thin-walled borosilicate formats. Thermo Fisher Scientific Inc. anchors its position through integrated distribution across academic and pharmaceutical channels. DWK Life Sciences differentiates via European manufacturing scale and private-label flexibility.
Griffin beakers are cylindrical laboratory vessels with a flat bottom, pouring spout, and approximate volume graduations, typically manufactured from borosilicate glass for thermal shock resistance or polypropylene for cost-sensitive disposability. They serve as the foundational mixing and measurement container across analytical chemistry, educational instruction, and quality-control workflows. Standard beakers retain the largest volume share, though graduated beakers command margin premiums in pharmaceutical quality-assurance labs where volumetric precision matters. Borosilicate glass dominates material selection in high-heat applications, while polypropylene is displacing glass in K-12 teaching environments where breakage rates drive replacement economics.
FDA cGMP guidelines and ISO 3819 dimensional standards govern product specifications for clinical and analytical applications, respectively, with the former mandating traceable material certification for drug-manufacturing contact surfaces. EPA methods for water and soil analysis implicitly require borosilicate compatibility, reinforcing glass demand in environmental testing laboratories. Stakeholders must monitor evolving state-level restrictions on single-use plastics in educational settings, as these could accelerate material substitution timelines without warning.
Market Dynamics
REACH regulation tightening chemical compatibility standards is compressing supplier margins while forcing rapid material certification cycles across European manufacturing clusters.
Growth Catalysts
- Academic procurement expansion:Undergraduate chemistry programs in the United States are scaling borosilicate glassware volumes for laboratory instruction modernization.
- EPA environmental testing mandates:Water and soil analysis protocols implicitly require borosilicate compatibility, sustaining replacement demand in analytical laboratories.
- Precision glass manufacturing clusters:German industrial concentration serves export markets across Central and Eastern Europe with short lead times.
Market Restraints
- Borosilicate raw material volatility:Specialty sand and boron compound prices fluctuate with energy costs, squeezing forming operation margins.
- Single-supplier concentration risk:Automated fusion-draw technology remains captive to a limited set of equipment vendors in North America and Europe.
- Polypropylene substitution in education:K-12 breakage economics favor plastic disposability over glass durability in cost-constrained districts.
Strategic Opportunities
- Indian pharmaceutical quality assurance:CDSCO cGMP enforcement is expanding certified glassware demand in generic drug manufacturing hubs.
- Private-label channel expansion:Distributor consolidation creates white-space for flexible manufacturing partnerships with mid-scale laboratory suppliers.
- Biopharma single-use integration:Hybrid workflows combining reusable glass with disposable consumables open premium positioning in cell culture applications.
Industry Challenges
- Manual glassblowing skill attrition:Master craftsmen retirement rates exceed apprenticeship pipeline capacity in traditional European manufacturing centers.
- ISO 3819 certification timeline compression:Third-party dimensional verification queues extend lead times for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Griffin Beaker Market |
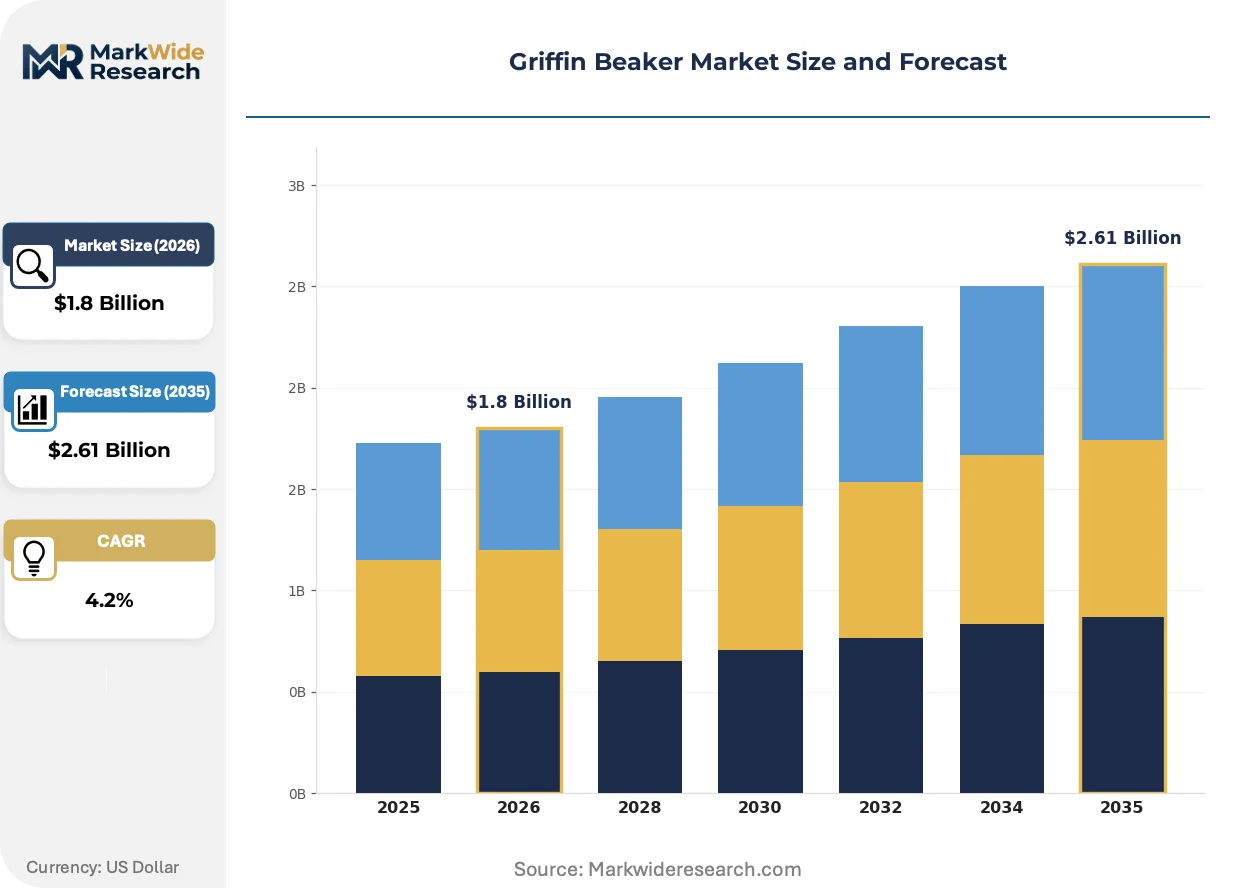
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Beakers, Graduated Beakers, Mixing Beakers, Pouring Beakers Material: Glass, Plastic, Borosilicate, Polypropylene Size: 50 mL, 100 mL, 250 mL, 1000 mL Application: Chemical Analysis, Laboratory Experiments, Teaching, Sample Preparation |
| Companies Covered | Corning Inc., Thermo Fisher Scientific Inc., DWK Life Sciences, Kimble Chase Life Science and Research Products LLC, Borosil Scientific Glass Works Ltd., Eisco Scientific, Pyrex, United Scientific, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Griffin Beaker Market Shifts & Advancements
Material science advances and regulatory stringency are reconfiguring competitive advantage around thermal performance certification and supply chain traceability.
Thin-walled borosilicate forming via automated fusion-draw lines is displacing traditional manual blowing for high-volume standard beaker formats. Pharmaceutical quality-assurance laboratories are adopting these formats for rapid thermal cycling protocols. The shift is compressing price premiums for legacy thick-walled designs while elevating lot-to-lot consistency requirements.
REACH substance restriction updates are mandating expanded chemical compatibility documentation for laboratory consumables entering European customs zones. Manufacturers must now maintain material safety data sheets traceable to raw batch records. Analytical chemistry segments are absorbing compliance costs through supplier qualification audits, while educational buyers are shifting toward pre-certified import channels.
Consolidated distributor procurement is compressing vendor counts in North American academic channels. University system purchasing cooperatives are replacing individual department orders with framework agreements covering multi-year glassware supply. California and Texas public university systems are pioneering this consolidation, squeezing regional specialty distributors from approved vendor lists.
Griffin Beaker Market Segmentation
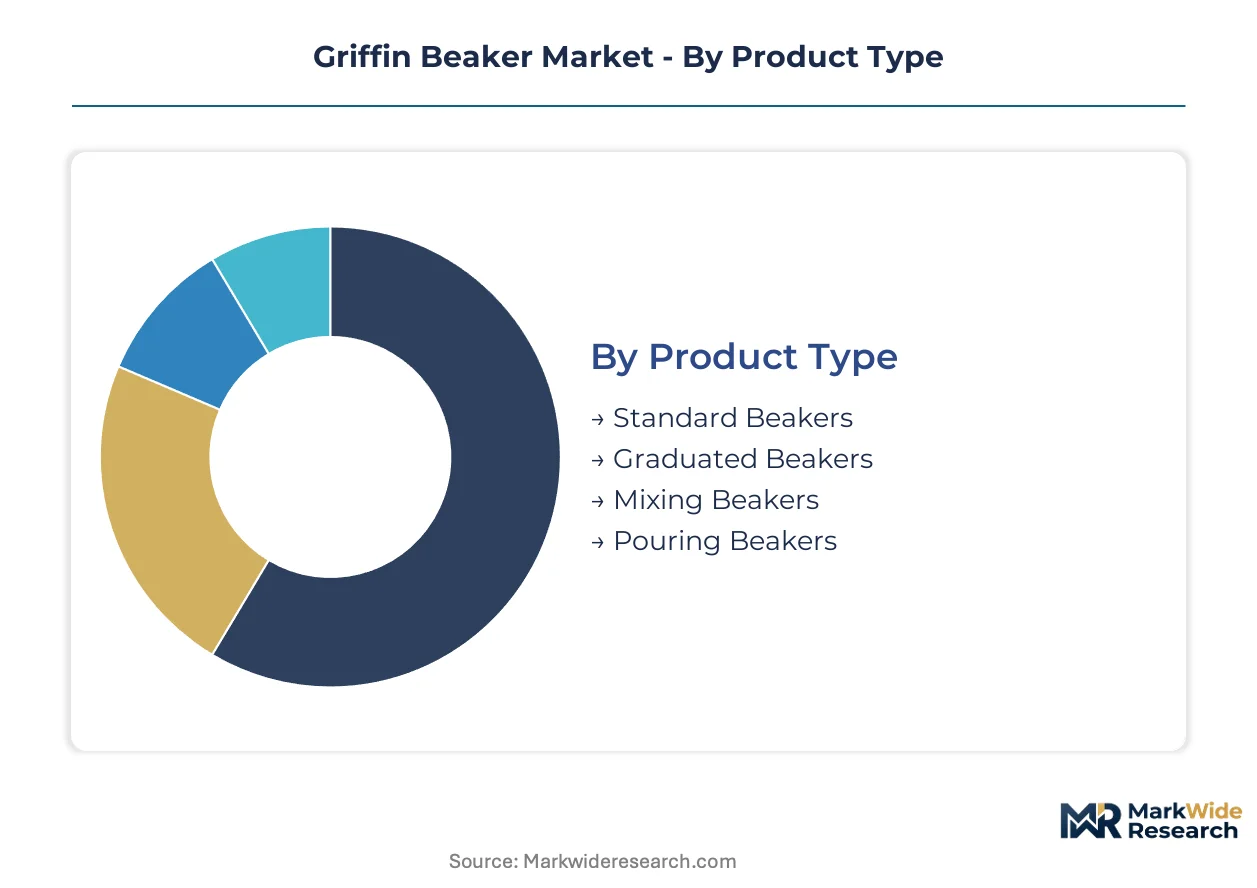
Griffin beaker segmentation reveals divergent vulnerability profiles across material and format categories. Substitution dynamics, regulatory exposure, and end-use durability requirements create distinct strategic imperatives for each segment cluster.
Product Type:
Graduated formats face intensifying displacement from disposable volumetric alternatives in high-throughput pharmaceutical workflows.
- Standard Beakers:Cylindrical vessels with flat bottoms and pouring spouts carry approximate volume markings only. Demand concentrates in undergraduate chemistry programs across United States public university systems where cost-per-unit drives procurement decisions. Breakage replacement cycles sustain steady volume despite lower per-unit margins.
- Graduated Beakers:Precision-etched volumetric graduations enable direct measurement without secondary transfer. Pharmaceutical quality-assurance laboratories in Germany and Switzerland absorb premium pricing for ISO 3819-certified formats that eliminate pipetting steps in analytical protocols. CDSCO cGMP enforcement in India is expanding addressable market for certified graduated vessels.
- Mixing Beakers:Reinforced rim designs withstand mechanical agitation and magnetic stirring bar impact. Serve process development and scale-up chemistry in contract research organizations.
- Pouring Beakers:Extended spout geometries minimize drip transfer during liquid decanting. Common in environmental testing laboratories executing EPA water and soil analysis methods.
Standard beakers retain volume leadership; graduated beakers hold the steepest expansion curve.
Material:
Cost tier stratification separates thermal-performance premiums from disposability economics.
- Glass:Soda-lime formulations dominate legacy educational procurement in budget-constrained districts. Thermal shock limitations restrict use to ambient-temperature applications, creating replacement demand from borosilicate upgrades.
- Plastic:Polystyrene and polycarbonate variants serve single-use biopharma workflows where cross-contamination protocols mandate disposal. European REACH substance restrictions are compressing supplier margins through expanded chemical compatibility documentation requirements.
- Borosilicate:Low thermal expansion coefficient enables direct flame heating and rapid thermal cycling. Automated fusion-draw manufacturing lines in Germany and United States deliver thin-walled formats with lot-to-lot dimensional consistency. EPA analytical methods implicitly mandate borosilicate compatibility for environmental testing applications.
- Polypropylene:Injection-molded disposability answers K-12 breakage economics where replacement labor costs exceed material premiums. California and Texas public school districts are shifting procurement toward certified polypropylene channels as state plastic restriction timelines tighten.
Borosilicate commands margin premiums; polypropylene is gaining share fastest in education channels.
Size:
Application scale determines volume concentration across the milliliter range.
- 50 mL:Micro-scale synthesis and analytical sample preparation in pharmaceutical discovery laboratories. Limited thermal mass enables rapid temperature equilibration.
- 100 mL:Standard instructional format in undergraduate organic chemistry sequences. United States academic procurement cooperatives negotiate framework agreements at this scale.
- 250 mL:Versatile workhorse capacity bridging analytical and preparative applications. German precision glass clusters optimize forming line economics around this midpoint specification.
- 1000 mL:Bulk reagent preparation and environmental sample compositing. Environmental testing laboratories in United States absorb higher per-unit costs for EPA method compliance.
250 mL formats anchor procurement volumes; 50 mL sizes are climbing the fastest in biopharma discovery.
Application:
End-use maturity separates regulated analytical demand from price-sensitive educational markets.
- Chemical Analysis:Quantitative and qualitative procedures requiring material certification and traceable calibration. FDA cGMP guidelines mandate documented material origins for drug-manufacturing contact surfaces.
- Laboratory Experiments:Research and development workflows spanning discovery through process development. Flexibility in material specification allows supplier switching based on lead time and pricing.
- Teaching:Primary, secondary, and undergraduate instructional environments. K-12 plastic substitution is accelerating as breakage rates drive replacement economics in cost-constrained districts.
- Sample Preparation:Pre-analytical processing for chromatography, spectroscopy, and microscopy. Environmental testing laboratories prioritize borosilicate compatibility for EPA method adherence.
Teaching applications dominate unit volumes; chemical analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in precision glassware tilt toward manufacturing clusters with captive fusion-draw capability. Germany and the United States anchor outbound shipment volumes. Import dependency concentrates in markets lacking domestic borosilicate forming infrastructure.
United States
Academic procurement cooperatives in California and Texas public university systems are consolidating multi-year framework agreements for undergraduate chemistry glassware. EPA water and soil analysis methods implicitly mandate borosilicate compatibility, sustaining replacement demand in environmental testing laboratories clustered around Research Triangle Park and Boston metro areas.
Germany
Precision glass manufacturing clusters in Bavaria and Thuringia serve export markets across Central and Eastern Europe with short lead times. REACH substance restriction updates from ECHA mandate expanded chemical compatibility documentation, compressing supplier margins through rapid certification cycles. DWK Life Sciences anchors European manufacturing scale from these industrial concentrations.
India
CDSCO cGMP enforcement is expanding certified glassware demand in generic drug manufacturing hubs around Hyderabad and Ahmedabad. Central government PLI scheme incentives for pharmaceutical production are indirectly lifting quality-assurance equipment procurement. Borosil Scientific Glass Works Ltd. represents domestic fabrication capacity serving this regulated demand.
China
Environmental testing laboratory expansion under MEE pollution monitoring mandates is sustaining borosilicate import volumes despite domestic soda-lime production dominance. Yangtze River Delta analytical services clusters source certified graduated beakers for ISO 3819-compliant workflows. NMPA pharmaceutical manufacturing standards are gradually converging toward FDA-level material traceability requirements.
Japan
Biopharma single-use integration trends in Kanto region cell culture facilities are creating hybrid workflow demand combining reusable borosilicate with disposable consumables. METI industrial standards for laboratory equipment maintain stringent dimensional tolerance specifications. PMDA pharmaceutical quality guidelines reinforce traceable material certification for drug-manufacturing contact surfaces.
Griffin Beaker Market Competitive Landscape
Concentration sits with diversified laboratory equipment conglomerates possessing captive distribution networks. Mid-scale specialists compete on private-label flexibility and regional certification speed. Three archetypes dominate: integrated life-science conglomerates with global channel control, European precision glass specialists with REACH-compliant manufacturing scale, and regional fabricators serving cost-sensitive educational procurement. Competitive moves center on distributor consolidation partnerships and automated forming line investments to compress lot-to-lot variance.
Within the integrated conglomerate tier, Corning Inc. and Thermo Fisher Scientific Inc. exemplify channel-anchored positioning. Corning leverages captive fusion-draw technology for thin-walled thermal performance certification. Thermo Fisher anchors academic and pharmaceutical segments through integrated distribution density. DWK Life Sciences occupies the European specialist position with private-label flexibility and German manufacturing concentration. Kimble Chase Life Science and Research Products LLC represents mid-scale North American fabrication serving framework agreement procurement channels.
| Leading Market Players |
|---|
| Corning Inc. |
| Thermo Fisher Scientific Inc. |
| DWK Life Sciences |
| Kimble Chase Life Science and Research Products LLC |
| Borosil Scientific Glass Works Ltd. |
| Eisco Scientific |
| Pyrex |
| United Scientific |
| Saint-Gobain |
| Others |
Supply & Pricing Matrix
Forty-five-day lead times for REACH-compliant graduated beakers from German precision glass clusters concentrate pricing power with automated fusion-draw operators while squeezing manual glassblowing margins. This inventory-to-delivery spread separates thin-walled thermal performance certification premiums from commodity replacement economics in educational procurement channels.
Pricing Analysis
Configured-to-order pricing for ISO 3819-certified graduated formats commands spreads of three-to-four times over standard beaker baselines. Contract-based long-term offtake dominates pharmaceutical quality-assurance procurement, with price differentiation resting on certification grade and volume scale. Cost compression in K-12 education channels is intensifying because polypropylene substitution eliminates breakage labor premiums. Educational buyers exhibit highest price sensitivity; biopharma single-use integration workflows show least.
Supply Chain Analysis
Strategic stockpile preferences concentrate borosilicate raw material inventories around German and United States forming clusters to buffer specialty sand and boron compound volatility. Supply draws from Germany, United States, and China for finished glassware, with raw material dependencies on Turkish specialty sand, Chilean boron compounds, and German precision forming equipment. Single-source vulnerability sits with automated fusion-draw technology vendors. Distribution runs through consolidated academic purchasing cooperatives and pharmaceutical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polypropylene substitution in K-12 education represents an existential material threat that borosilicate incumbents must navigate through certification anchoring and thermal performance differentiation.
For Market Incumbents: Fortify position through backward integration into captive borosilicate raw material sourcing and accelerated CDSCO certification investment in Indian pharmaceutical hubs. Threat from polypropylene breakage economics demands channel control reinforcement in consolidated academic procurement cooperatives. Thermal performance certification anchors defensible premium positioning against disposable substitution. For New Entrants and Emerging Players: Differentiate on private-label flexibility and rapid REACH compliance turnaround for mid-scale European laboratory distributors. White-space concentrates in Indian generic drug manufacturing quality-assurance equipment and hybrid biopharma workflows combining reusable glass with single-use consumables. Go-to-market leverage rests on framework agreement qualification with California and Texas public university systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life-science conglomerates seeking to divest non-core glassware manufacturing units with stranded certification assets. Long-term viability favors automated fusion-draw capability with European regulatory compliance infrastructure. Signal to monitor: CDSCO enforcement intensity crossing thresholds that trigger certified glassware procurement acceleration in Indian pharmaceutical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Raw Materials | Captive supply of specialty sand and boron compounds insulates margin compression from energy-linked commodity volatility. |
| CDSCO Certification Fast-Track Investment | Accelerated compliance timelines capture expanding quality-assurance equipment procurement in Indian generic drug hubs. |
| Automated Fusion-Draw Capacity Expansion | Thin-walled thermal performance certification displaces manual glassblowing in high-volume standard beaker formats. |
| Private-Label Channel Partnership | Flexible manufacturing contracts with mid-scale distributors exploit consolidated procurement white-space in European markets. |
| Hybrid Workflow Product Development | Reusable borosilicate integration with single-use biopharma consumables opens premium positioning in cell culture applications. |
Research Methodology
A spread of perspectives from laboratory procurement managers, pharmaceutical quality-assurance directors, precision glass manufacturing engineers, and distributor channel heads converged on the working assumptions. Primary interview intelligence combined with secondary validation from EPA method documentation, REACH substance restriction updates, FDA cGMP guidance filings, and ISO 3819 dimensional standards. Bottom-up volume triangulation against top-down market sizing anchored projection integrity.
Segmentation dimensions modeled include material grade tier, product format precision level, end-use application maturity, and regional regulatory cluster intensity across the analysis window. CAGRs derived from shipment volume trajectories cross-referenced with pricing band movements. Forecast inputs incorporated academic procurement cooperative framework agreement coverage rates and pharmaceutical manufacturing capacity expansion pipelines.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity and CDSCO cGMP adoption curves would require recalibration. Forecasts reflect assumptions on substitution elasticity in education channels and raw material cost pass-through coefficients. Revision becomes warranted when polypropylene restriction legislation crosses implementation thresholds in major state-level educational procurement jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Spain Feed Additives Market
Others
Port Replicator Market
Others
Senior Cat Food Market
Others
Thiamethoxam Market
Others
Cloud-Based Streaming Services Market
Others
Europe Battery Packaging Market
Others
Disposable Non Woven Sponge Market
Others
Military Image Intensifier Market
Others
Bio-Imaging Technologies Market
Others
Edible Insects for Animal Feed Market
Others
Gym Wipes Market
Others
Inorganic Tin Chemicals Market
Others
IT Device Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Cellular-Connected Laptops Market
Others
Moonstone Market