
 Biopharma Plastics Market | 2026-2036
Biopharma Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharma Plastics Market Intelligence
A shift from stainless-steel reusable systems toward single-use disposable assemblies is recalibrating procurement strategies across biopharma manufacturing networks. Dow, Inc. leverages its medical-grade polyethylene portfolio to anchor supply relationships with large-scale biologics producers. DuPont de Nemours, Inc. differentiates through fluoropolymer barrier technologies that sustain performance under gamma sterilization. BASF SE competes on copolymer customization for extractables-sensitive drug-contact applications.
Biopharma plastics encompass medical-grade polymers engineered for biocompatibility, low extractables profiles, and gamma or autoclave sterilization resilience, typically formulated with tight molecular-weight distributions and additive packages compliant with USP Class VI and ISO 10993 standards. These materials serve primarily as containment, delivery, and processing interfaces for sterile drug products and biological substances. Polypropylene dominates the material segment due to its thermal stability and leachables performance in bioreactor film applications, while polyethylene leads in tubing and bag constructions where flexibility and weldability matter. Drug delivery represents the fastest-expanding application segment, driven by prefilled syringe and wearable injector formats that demand precision-molded cyclic olefin polymers.
FDA's Container Closure Guidance, EMA's Annex 1 revision on sterile manufacturing, and ISO 15378 pharmaceutical packaging standards collectively elevate barrier performance and traceability requirements for polymer converters. These frameworks compel material suppliers to invest in dedicated cleanroom compounding and batch-level extractables documentation. Stakeholders must monitor evolving regulatory divergence between FDA extractables thresholds and EMA's risk-based leachables assessment protocols to align qualification timelines with product development cycles.
Market Dynamics
The migration from stainless-steel bioreactors to single-use disposable systems constitutes the dominant structural force in biopharma plastics, recalibrating material specifications toward extractables-tested polymers and gamma-stable formulations across manufacturing networks.
Growth Catalysts
- FDA Container Closure Guidance:Extractables and leachables testing mandates are compelling biologics manufacturers to qualify medical-grade polymers with documented batch-level compliance, expanding procurement of USP Class VI certified materials.
- Cell and gene therapy manufacturing:Viral vector production facilities are adopting single-use bioprocessing assemblies at scale, driving demand for fluoropolymer barrier films that withstand aggressive cleaning chemistries.
- Prefilled syringe and wearable injector formats:Drug delivery device manufacturers are specifying cyclic olefin polymers for precision-molded components, creating new volume channels for low-extractables thermoplastics.
Market Restraints
- Specialized resin supply concentration:Medical-grade polypropylene and fluoropolymer production concentrates among a limited set of petrochemical complexes, exposing converters to feedstock allocation volatility.
- Extractables documentation burden:EMA's risk-based leachables assessment protocols require extensive analytical chemistry investment, extending material qualification timelines and freezing supplier switches.
- Stainless-steel system residual demand:Continuous processing advocates in mAb manufacturing retain preference for reusable equipment, capping single-use penetration in high-volume biologics segments.
Strategic Opportunities
- Chinese biologics capacity expansion:NMPA regulatory harmonization with ICH guidelines is accelerating domestic CDMO buildouts, creating demand for imported medical-grade polymer specifications.
- Closed-system transfer device integration:Oncology pharmacy compounding regulations are driving adoption of needle-free connector systems that require engineered polymer barrier technologies.
- Bio-based polymer development:EU Green Deal sustainable chemistry incentives are opening qualification pathways for renewable-content medical polymers meeting ISO 10993 biocompatibility thresholds.
Industry Challenges
- Extractables chemist talent scarcity:Specialized analytical chemistry expertise for polymer qualification remains concentrated among contract laboratories, creating bottlenecks in supplier onboarding.
- Cleanroom compounding capital requirements:Dedicated ISO Class 7 polymer compounding facilities demand substantial infrastructure investment, constraining mid-tier material suppliers.
- Legacy equipment integration friction:Single-use assemblies must interface with existing stainless-steel infrastructure, requiring custom adapter development and validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharma Plastics Market |
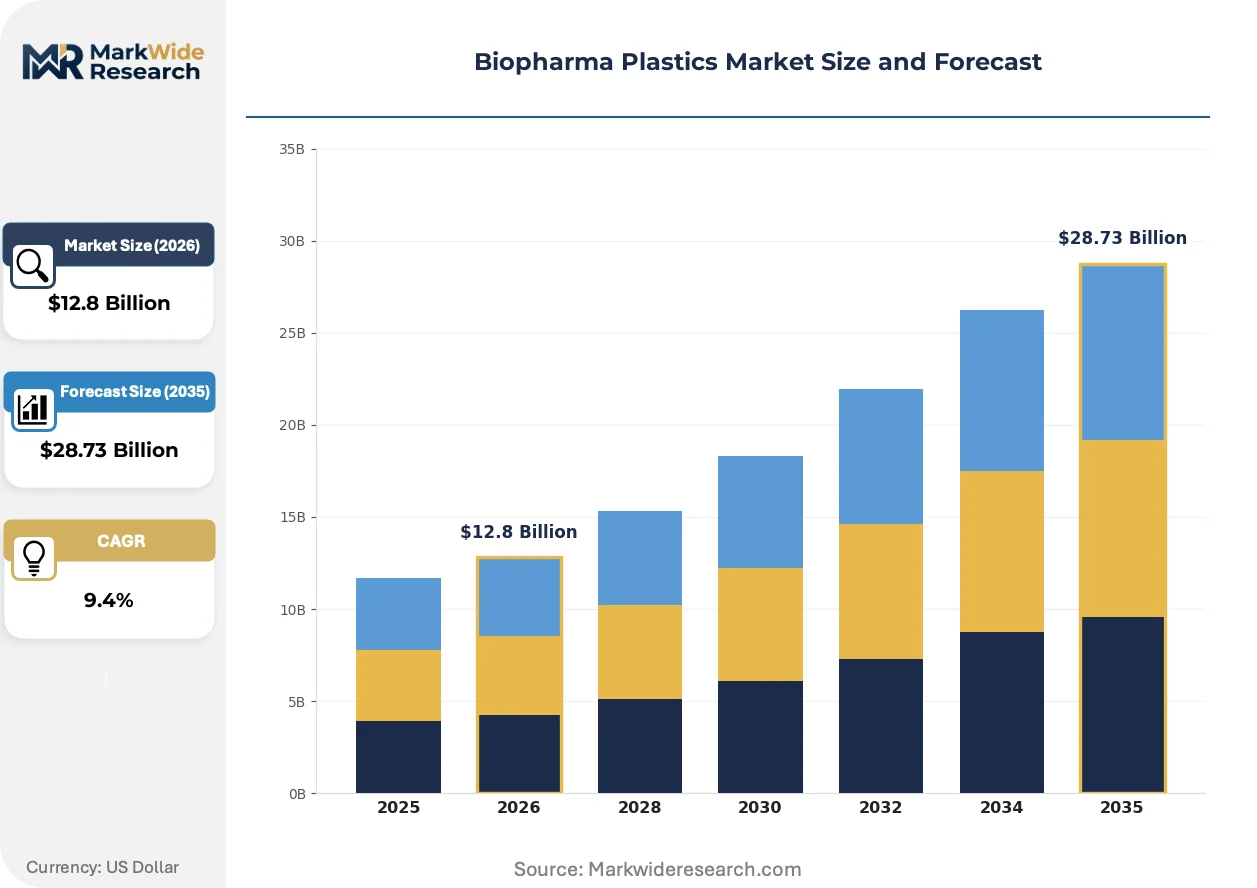
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Syringes, Vials, Bags Application: Drug Delivery, Biologics Packaging, Medical Devices, Laboratory Use Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Copolymer End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals |
| Companies Covered | Dow, Inc., DuPont de Nemours, Inc., BASF SE, Covestro AG, Toray Industries, Inc., LyondellBasell Industries Holdings B.V., Solvay, Saint-Gobain Performance Plastics, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharma Plastics Market Strategic Shifts & Innovations
Material science advances and regulatory precision are converging to redefine performance benchmarks for pharmaceutical-contact polymers, with sterilization resilience and molecular purity becoming non-negotiable specifications rather than differentiated features.
Multi-layer coextrusion technology is consolidating bioprocessing film architectures, replacing monolayer constructions with engineered barrier structures that combine ethylene vinyl alcohol oxygen barriers with polyethylene seal layers. Bioreactor bag manufacturers are adopting these films at accelerating rates to meet EMA Annex 1 sterility assurance requirements. This consolidation is compressing the supplier base toward compounders with integrated film extrusion capabilities and dedicated medical-grade cleanrooms.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of traditional fluoropolymer barrier technologies used in aggressive chemical containment. European converters are accelerating qualification of alternative high-performance polymers that maintain chemical resistance without PFAS content. The drug-contact tubing segment faces the most acute substitution pressure, with gamma-stable thermoplastic elastomers emerging as the primary replacement pathway.
Biologics manufacturers are consolidating supplier relationships around full-system providers capable of delivering extractables-tested assemblies rather than discrete components. CDMO procurement teams are reducing approved vendor lists from dozens of specialized converters to integrated solution partners. This concentration is most visible in the United States, where large-scale biologics producers are negotiating multi-year supply agreements with polymer converters offering dedicated quality agreements and batch traceability systems.
Biopharma Plastics Market Segmentation
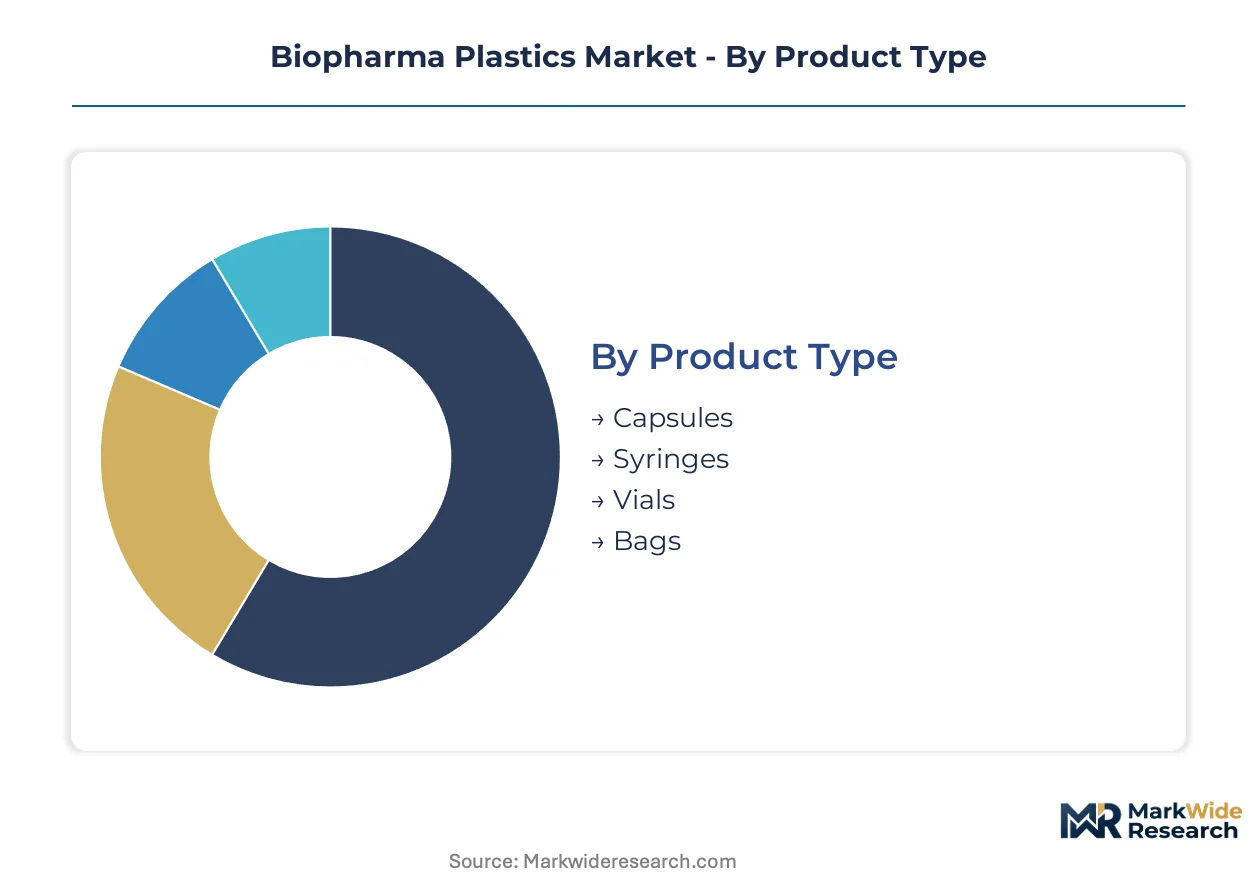
Biopharma plastics procurement varies sharply by product format and sterilization modality, with drug delivery systems commanding premium specifications against commodity packaging tiers. Material selection cascades through regulatory qualification burdens, end-use sterility requirements, and gamma-stability thresholds that reshape supplier relationships across each segment boundary.
Product Type:
Upgrade cycles from glass to polymer containment are accelerating replacement timelines, particularly where break resistance and design flexibility unlock new delivery formats.
- Capsules:Hard gelatin and HPMC shells incorporate medical-grade colorants and lubricants compliant with USP Class VI extractables limits. Demand concentrates in oral solid dose manufacturing across Germany and India, where high-speed filling lines reward dimensional consistency and moisture barrier performance.
- Syringes:Prefilled formats specify cyclic olefin polymers or clarified polypropylene for barrel clarity and plunger glide force precision. The fastest expansion belongs to wearable injector platforms in the United States, where chronic disease management protocols favor patient-administered biologics.
- Vials:Cyclic olefin copolymer and polypropylene vials displace borosilicate glass in protein-based therapeutics requiring low-sodium leachables profiles. Lyophilization compatibility and seal integrity under deep-cold storage drive specification decisions.
- Bags:Multi-layer polyethylene and ethylene vinyl alcohol coextrusions form bioreactor containment and intravenous solution reservoirs. Cell therapy manufacturing in China is scaling single-use bag procurement for closed-system fluid transfer applications.
Volume placements concentrate in Bags; the faster expansion belongs to Syringes.
Application:
Cost tier stratification separates commodity packaging from precision-molded delivery systems, with regulatory burden and performance margins widening the spread between tiers.
- Drug Delivery:Autoinjectors, prefilled pens, and inhalation devices demand tight-tolerance molding with documented extractables profiles for each polymer lot. Wearable patch pump adoption in the United States and Germany is expanding cyclic olefin polymer consumption for reservoir and fluid path components.
- Biologics Packaging:Container closure systems for monoclonal antibodies and vaccines require oxygen barrier performance and sub-visible particle control. Cold chain distribution requirements in China and India are accelerating qualification of alternative polymer vials to glass.
- Medical Devices:Diagnostic cartridges, surgical instruments, and implantable components utilize radiopaque fillers and lubricious surface modifications. ISO 10993 biocompatibility testing protocols govern material selection for blood-contact and tissue-contact applications.
- Laboratory Use:Cell culture vessels, filtration manifolds, and sample storage containers prioritize optical clarity and autoclavability. Research institutions in the United States and Germany are consolidating procurement around certified RNase-free and DNase-free polymer grades.
Procurement volumes cluster in Biologics Packaging; steepest expansion trajectory appears in Drug Delivery.
Material:
Supply concentration among petrochemical complexes shapes converter access to medical-grade resin streams, with specialized additive packages and narrow molecular-weight distributions commanding allocation priority.
- Polyethylene:Low-density and linear low-density grades dominate tubing, film, and bag constructions where flexibility and heat-sealability matter. Bioreactor bag manufacturers in the United States and China are securing multi-year supply agreements for gamma-stable polyethylene with antioxidant packages validated for extractables performance.
- Polypropylene:Clarified and nucleated grades offer transparency and dimensional stability for syringe barrels, vial bodies, and diagnostic components. Random copolymer variants with ethylene content provide impact resistance for cold-chain applications.
- Polyvinyl Chloride:Plasticized formulations persist in intravenous tubing and blood bag applications despite DEHP substitution pressures. Non-phthalate plasticizer alternatives are gaining qualification traction under EU REACH and FDA guidance.
- Copolymer:Cyclic olefin copolymers and terpolymers deliver glass-like clarity with polymer processability for high-precision drug delivery components. Moisture barrier performance and low protein adsorption properties support biologics containment applications.
Polyethylene anchors current volume; Copolymer segments are climbing the fastest on precision-molding demand.
End User:
Customer type determines qualification depth and contract structure, with pharmaceutical companies driving integrated supply agreements against transactional spot purchasing from research institutions.
- Pharmaceutical Companies:Large-scale biologics producers specify extractables-tested materials with batch-level documentation and dedicated quality agreements. Multi-year supply contracts with polymer converters are consolidating in the United States and Germany.
- Contract Manufacturers:CDMOs demand flexible volume commitments and rapid material qualification pathways to serve diverse client portfolios. Single-use assembly suppliers are embedding polymer sourcing within turnkey bioprocessing system offerings.
- Research Institutions:Academic and government laboratories prioritize catalog availability and competitive pricing over deep qualification packages. Standard USP Class VI certification suffices for most cell culture and analytical applications.
- Hospitals:Pharmacy compounding and point-of-care preparation drive demand for ready-to-use sterile containers and closed-system transfer devices. Oncology pharmacy regulations in the United States are accelerating needle-free connector adoption.
Contract Manufacturers are capturing volume growth fastest; Pharmaceutical Companies retain the largest absolute procurement positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast anchors North American medical-grade polymer production, while German chemical complexes and Chinese coal-to-olefins infrastructure shape competing supply basins for biopharma-grade resins.
United States
FDA Container Closure Guidance and EMA Annex 1 alignment pressures are driving extractables documentation investments by biologics manufacturers in Massachusetts and North Carolina. The National Institute for Innovation in Manufacturing Biopharmaceuticals (NIIMBL) funds domestic polymer qualification initiatives. Boston-Cambridge biotech clusters are consolidating single-use assembly procurement around multi-year supply agreements with certified converters.
Germany
EMA's risk-based leachables protocols and REACH PFAS restrictions are accelerating fluoropolymer reformulation programs across Baden-Württemberg chemical complexes. The EU Green Deal sustainable chemistry incentives support bio-based medical polymer development. Frankfurt-Rhine-Main logistics hubs are expanding cold-chain distribution infrastructure for polymer vial alternatives to glass.
China
NMPA regulatory harmonization with ICH Q3D and Q5A guidelines is enabling domestic CDMO qualification of imported medical-grade polymer specifications. Dual carbon goals are pressuring coal-to-olefins producers in Ningxia and Inner Mongolia to decarbonize. Shanghai-Suzhou biologics manufacturing corridors are scaling single-use bag procurement for viral vector production facilities.
India
CDSCO's adoption of ICH M7 guidelines for extractables and leachables is elevating material qualification standards for domestic injectables manufacturers. PLI scheme incentives for active pharmaceutical ingredients extend to polymer containment systems. Hyderabad and Ahmedabad pharmaceutical clusters are qualifying cyclic olefin polymers for prefilled syringe exports to regulated markets.
Japan
PMDA's emphasis on container closure integrity for biologics is tightening polymer vial qualification timelines for domestic mAb producers. METI's healthcare industry revitalization program supports precision molding capabilities for drug delivery devices. Osaka-Kobe chemical industry zones maintain specialized compounding capacity for gamma-stable polyethylene grades.
Biopharma Plastics Market Key Industry Players
Global majors compete with regional champions across resin supply and conversion capabilities, creating a tiered structure where petrochemical conglomerates anchor upstream supply while specialized converters capture downstream value. Integrated polymer producers with medical-grade cleanroom compounding assets command preferred supplier status against commodity resin traders. Three archetypes dominate: diversified chemical conglomerates with healthcare divisions, specialized medical polymer compounders, and single-use system integrators with captive polymer sourcing. Competitive moves concentrate on backward integration into resin production and strategic partnerships with CDMOs for co-development of extractables-tested assemblies.
Among diversified chemical conglomerates, Dow, Inc., DuPont de Nemours, Inc., and BASF SE exemplify the integrated archetype, occupying positions that span feedstock access through medical-grade compounding. These entities anchor supply relationships through dedicated quality agreements and batch-level documentation systems rather than transactional resin sales. Their geographic footprints—Midland, Michigan; Wilmington, Delaware; and Ludwigshafen, Germany respectively—reflect historical petrochemical infrastructure concentration that shapes competitive positioning in biopharma-grade polymer markets.
| Leading Market Players |
|---|
| Dow, Inc. |
| DuPont de Nemours, Inc. |
| BASF SE |
| Covestro AG |
| Toray Industries, Inc. |
| LyondellBasell Industries Holdings B.V. |
| Solvay |
| Saint-Gobain Performance Plastics |
| SABIC |
| Others |
Cost & Logistics Intelligence
Specialized extractables chemist concentration in Massachusetts and North Carolina creates labor-cost differentials that widen pricing-tier spreads between premium USP Class VI certified materials and standard catalog grades.
Pricing Analysis
Extractables documentation bundling separates premium-tier polymer supply from unbundled economy alternatives. Three-tier pricing structure across premium, standard, and economy levels hinges on certification depth, with batch-level USP Class VI documentation and dedicated quality agreements commanding substantial premiums over catalog-grade materials. Pricing pressure stems from EMA's risk-based leachables protocols extending qualification timelines and freezing supplier switches. Contract manufacturers exhibit highest price sensitivity due to flexible volume commitments, while large pharmaceutical companies prioritize qualification reliability over unit economics.
Supply Chain Analysis
Medical-grade polypropylene and fluoropolymer supply rests on petrochemical complexes in the United States, Germany, and China. Raw material dependencies include ethylene and propylene feedstocks, gamma-stable antioxidant packages, and narrow molecular-weight distribution resins. Single-source vulnerability concentrates in specialized fluoropolymer barrier technologies facing REACH PFAS restrictions. Distribution runs through integrated polymer converters with dedicated ISO Class 7 cleanroom compounding facilities rather than commodity resin traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractables-tested polymer capacity bottlenecks prop pricing power for qualified suppliers, with cleanroom compounding infrastructure scarcity limiting mid-tier expansion.
For Market Incumbents: Hedge against REACH PFAS restrictions accelerating fluoropolymer reformulation by qualifying alternative high-performance polymers in German chemical complexes. Anchor supply relationships through multi-year quality agreements with batch traceability systems. Defensive moves center on backward integration into resin production and captive cleanroom compounding capacity additions in the United States and Germany. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cyclic olefin copolymers opens white-space targeting of precision-molded drug delivery components for wearable injector platforms. Chinese CDMO buildouts present the most penetrable geography given NMPA regulatory harmonization with ICH guidelines. Go-to-market leverage should emphasize rapid material qualification pathways and flexible volume commitments. For Investors and Strategic Acquirers: Re-rating potential sits with specialized medical polymer compounders possessing dedicated cleanroom assets given EMA Annex 1 sterility assurance requirements tightening. Long-term viability favors integrated solution providers over discrete component suppliers. Watch for NMPA regulatory harmonization completion as inflection indicator for Chinese biologics capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Compounding Capacity Expansion | ISO Class 7 facilities meet tightening EMA extractables documentation requirements for bioreactor film supply. |
| PFAS-Free Fluoropolymer Reformulation | REACH-compliant barrier technologies substitute legacy chemistries in aggressive chemical containment applications. |
| Multi-Year Quality Agreement Structuring | Batch traceability systems anchor preferred supplier status with large-scale biologics producers in Massachusetts. |
| Chinese CDMO Partnership Development | NMPA harmonization enables qualification of imported medical-grade polymer specifications for viral vector facilities. |
| Cyclic Olefin Polymer Precision Molding Investment | Prefilled syringe and wearable injector formats demand tight-tolerance components with documented extractables profiles. |
Research Approach
Regulatory filings, customs and trade data, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews involving polymer procurement managers at CDMOs, regulatory affairs leads at biologics manufacturers, technical R&D directors at compounders, and GPO contracts managers at hospital systems. Bottom-up volume modeling triangulated against top-down petrochemical feedstock flow analysis.
Historical trendline analysis of medical-grade resin pricing and qualification timeline patterns informed projection frameworks across the analysis window. Segmentation dimensions encompassed product format, sterilization modality, material grade tier, end-use application, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand modeling incorporating biologics capacity expansion trajectories and single-use penetration rates.
Underlying measurement precision varies by segment; drug delivery systems and biologics packaging carry tighter precision than laboratory use categories. Forecasts incorporate assumptions regarding regulatory harmonization progress and feedstock allocation stability. Supply concentration risks, REACH restriction timelines, and extractables chemist availability warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Silicone Molding Machinery Market
Others
Rope Market
Others
Thermal Energy Flow Metering Solutions Market
Others
North America Healthcare Flexible Packaging Market
Others
Computer on Module Market
Others
High Frequency Vibrator Market
Others
Radiation Detection Monitoring and Safety Market
Others
Fire Sprinkler Market
Others
Global Lavender Extracts Market
Others
Europe Digital Experience Platform Market
Others
Augmented Reality in Energy and Utilities Market
Others
Smart Home Platforms Market
Others
North America Compressor Oil Market
Others
Spend Analytics Market
Others
Taiwan Retail Market
Others
Mobile Social Networks Market