
 Port Replicator Market | 2026-2036
Port Replicator Market Size, Share, and Industry Trends Forecast 2026-2036
Port Replicator Market Analytics
Chinese electronics manufacturing is restructuring port replicator supply chains as OEMs diversify final assembly beyond single-country dependence. Dell Technologies leverages direct enterprise relationships to sustain high-volume corporate contracts across North America. HP Inc. anchors its position through bundled workstation solutions that integrate docking hardware with service agreements. Lenovo Group Limited dominates commercial channel distribution in Asia-Pacific markets through its ThinkPad ecosystem lock-in.
A port replicator is a peripheral device that expands a host computer's connectivity through a single cable interface, typically supporting video output at 4K/60Hz or higher, multiple USB data lanes, and power delivery up to 100W. It serves commercial and institutional buyers by converting thin laptops into full desktop equivalents without repeated cable swapping. The USB-C segment leads volume shipments as Power Delivery standardization eliminates proprietary charging barriers across device brands. The corporate end-user category occupies the deepest margin pools due to multi-year fleet contracts and IT-managed standardization. The workstation use case segment differentiates on Thunderbolt bandwidth where video editing and CAD workflows require sustained throughput.
The USB Implementers Forum certification framework and IEC 62368-1 safety standards govern electrical and thermal performance requirements for multi-port docking hardware sold in major economies. The European Union's Common Charger Directive mandates USB-C interoperability, directly accelerating dock replacement cycles as legacy proprietary connectors phase out. Stakeholders must monitor semiconductor availability for USB4/Thunderbolt controllers and evaluate regional compliance timelines to align product roadmaps with enforcement windows.
Market Dynamics
The European Union's Common Charger Directive is forcing dock replacement cycles as legacy proprietary connectors phase out, while USB-C Power Delivery standardization simultaneously eliminates charging barriers across device brands and compresses procurement timelines for corporate IT fleets.
Growth Catalysts
- USB-C Power Delivery Standardization:The IEC 62368-1 safety framework governs electrical performance requirements, enabling cross-brand compatibility and reducing IT procurement friction for multi-vendor laptop fleets.
- Enterprise IT Refresh Cycles:Corporate hybrid work policies sustain peripheral ecosystem investments as organizations standardize docking hardware across distributed workstations in Germany, the United States, and Japan.
- Thunderbolt 4 Certification:Intel's bandwidth certification requirements in North America and Europe are reshaping compatibility mandates for video editing and CAD workstation deployments.
Market Restraints
- Semiconductor Controller Concentration:USB4/Thunderbolt controller availability bottlenecks constrain production scaling, with fabrication capacity concentrated among advanced foundry operators in Taiwan and South Korea.
- Proprietary Legacy Infrastructure:Locked-in corporate investments in vendor-specific docking solutions create switching costs that delay standardization adoption despite regulatory pressure.
- Thermal Design Constraints:Multi-port power delivery above 100W requires active cooling architectures that increase bill-of-materials complexity and unit economics pressure.
Strategic Opportunities
- Workstation Bandwidth Convergence:Thunderbolt 4 and USB4 controller integration enables single-cable solutions for 8K video output and external GPU enclosures, capturing premium positioning in creative professional segments.
- Asia-Pacific Commercial Channel Expansion:Underserved small and medium enterprise docking penetration in India and Southeast Asia offers volume growth outside saturated North American and European corporate markets.
- Managed Service Bundling:Hardware-as-a-service distribution models allow OEMs to capture recurring revenue streams through integrated docking deployments with enterprise device management platforms.
Industry Challenges
- Certification Timeline Compression:USB Implementers Forum validation queues and regional safety testing backlogs delay product launches, compressing revenue recognition windows against fiscal planning cycles.
- Supply Chain Reconfiguration Friction:Chinese electronics manufacturing diversification efforts create qualification overhead for alternative final assembly sites in Vietnam, Mexico, and India.
- Legacy System Integration Complexity:Corporate IT environments with mixed-generation laptops require backward-compatible dock portfolios that fragment engineering resources across multiple connectivity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Replicator Market |
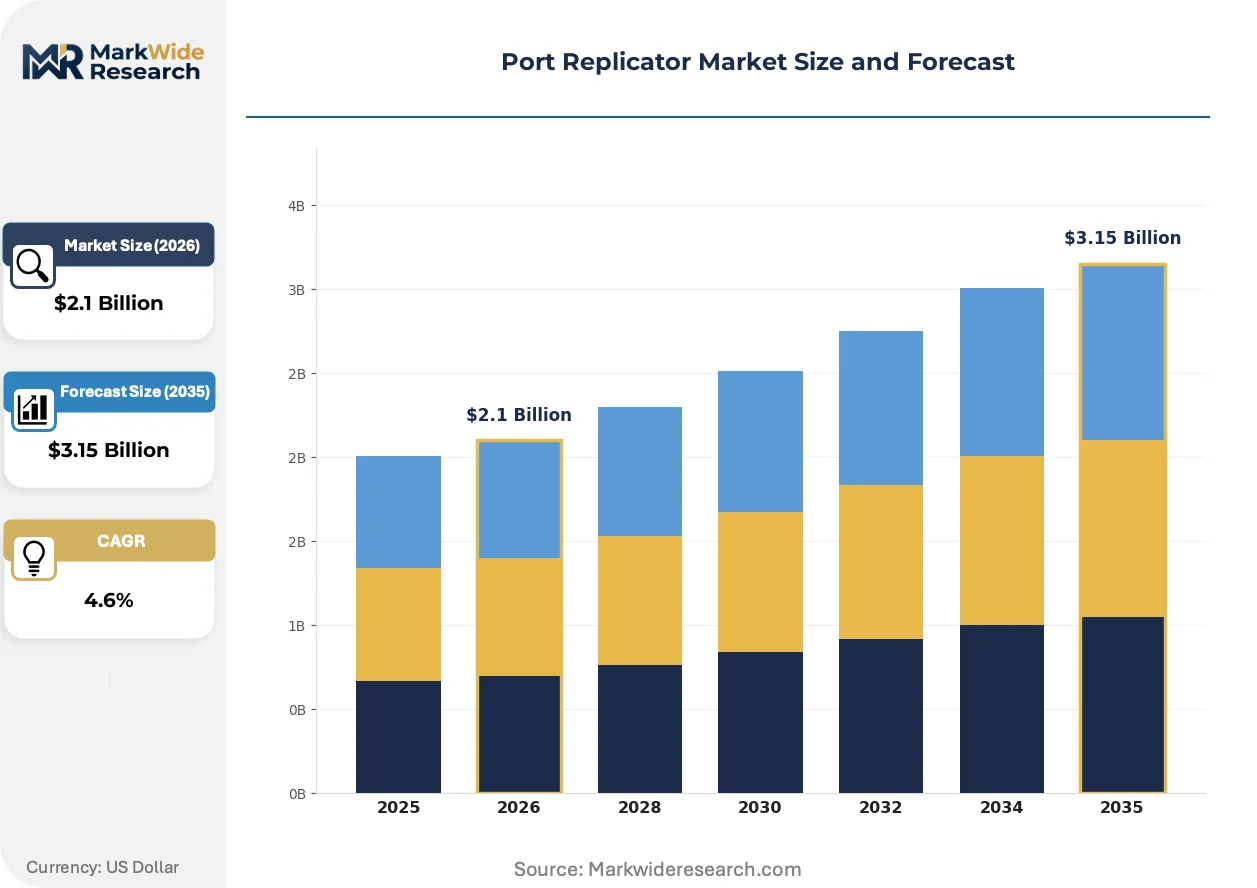
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB-C, Thunderbolt, HDMI, Ethernet End User: Corporate, Education, Healthcare, Home Office Connector Type: DisplayPort, VGA, DVI, Serial Use Case: Workstation, Gaming, Multimedia, Data Transfer |
| Companies Covered | Dell Technologies, HP Inc., Lenovo Group Limited, Targus, Kensington, StarTech.com, Plugable Technologies, Belkin International, Anker Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Replicator Market Evolving Landscape
Docking hardware is automating configuration management and power negotiation protocols, reducing IT deployment overhead while regulatory mandates accelerate connector standardization across major economies.
Thunderbolt 4 controller silicon is automating bandwidth allocation between video, data, and power delivery lanes. Enterprise workstation buyers are adopting these solutions for 4K/60Hz multi-monitor and external storage arrays. This automation is compressing the technical specification gap between premium and mid-tier dock segments.
REACH substance restrictions and RoHS compliance deadlines in Europe are tightening material specifications for printed circuit boards and connector housings. Manufacturers must reformulate halogen-free flame retardants and validate supply chain documentation. The corporate end-user segment bears compliance cost pass-throughs most acutely due to multi-year fleet contract pricing lock-ins.
Enterprise buyers are consolidating vendor relationships through single-source procurement frameworks that bundle docking hardware with laptop fleet purchases. Value-added distributors and direct OEM channels are displacing retail and e-commerce volumes for commercial-grade SKUs. Germany and Japan exhibit the strongest concentration of this behavior, where IT-managed standardization policies dominate hybrid work infrastructure decisions.
Port Replicator Market Segmentation
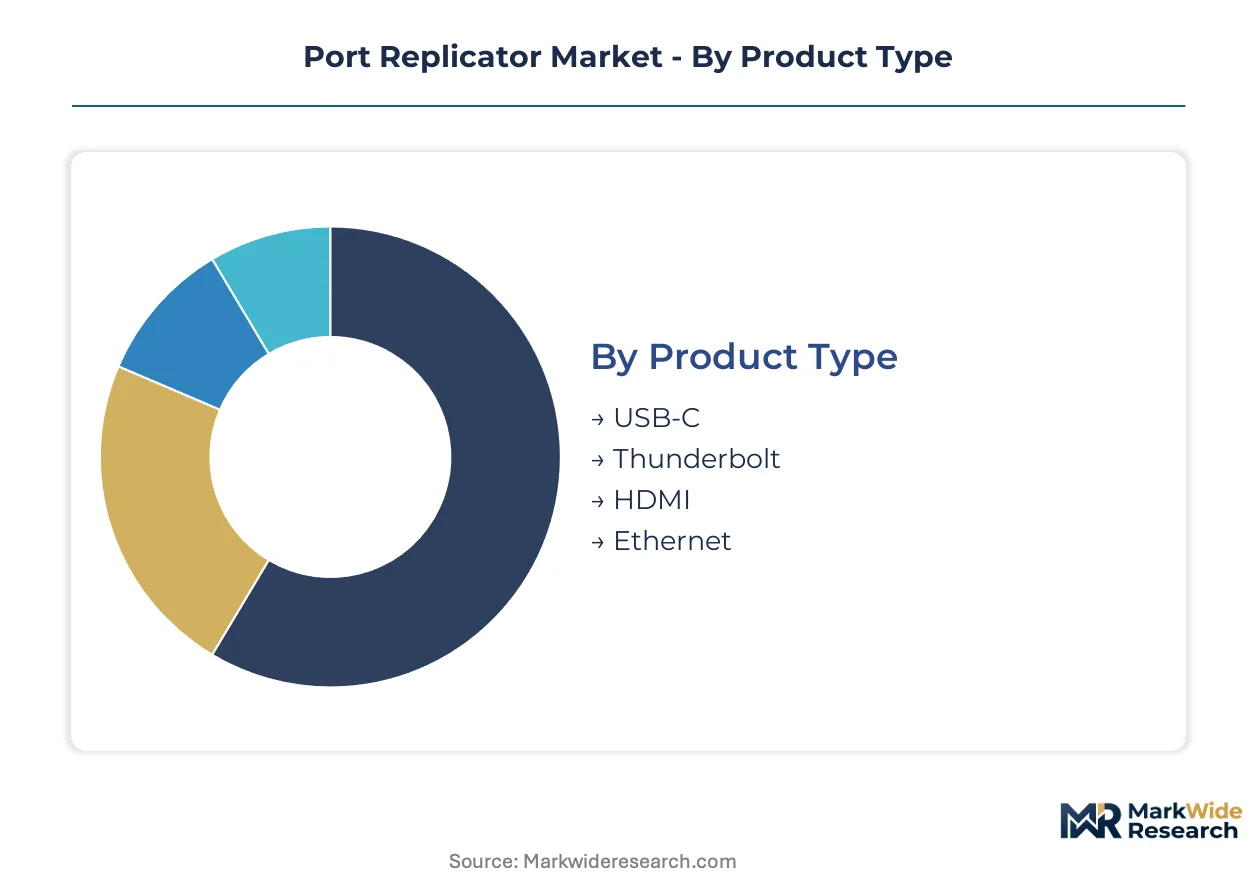
Port replicator procurement patterns diverge sharply across connectivity standards and institutional buyer profiles. Corporate IT standardization mandates and regulatory connector phase-outs are compressing replacement cycles unevenly across segment boundaries.
Product Type:
Upgrade cycles accelerate where Power Delivery standardization eliminates proprietary charging fragmentation.
- USB-C:This interface consolidates power delivery up to 100W, data transfer, and video output through a reversible connector. Procurement concentrates in Germany and the United States where corporate hybrid work policies mandate single-cable standardization across multi-vendor laptop fleets; IEC 62368-1 safety certification requirements compress vendor qualification timelines.
- Thunderbolt:Intel's bandwidth certification enables 40Gbps throughput for external GPU enclosures and 8K video arrays. Demand clusters in North American creative professional segments where video editing and CAD workflows require sustained throughput; controller silicon availability from Taiwan and South Korea foundries constrains production scaling.
- HDMI:Legacy video connectivity persists in education sector deployments where backward compatibility with existing display infrastructure governs procurement decisions.
- Ethernet:Wired network reliability requirements sustain this segment in financial services and healthcare IT environments where wireless security policies restrict connectivity options.
Volume placements concentrate in USB-C; the faster expansion belongs to Thunderbolt.
End User:
Cost tier stratification separates multi-year fleet contracts from transactional retail purchases.
- Corporate:Multi-year standardization agreements with IT-managed procurement frameworks lock in docking hardware across distributed workstation deployments. Margin pools deepen here due to bundled service agreements and volume pricing structures.
- Education:Budget-constrained institutional buyers prioritize backward compatibility and ruggedized designs for shared computing labs; procurement cycles align with semester-based refresh schedules.
- Healthcare:HIPAA compliance requirements and medical-grade EMI shielding specifications constrain vendor qualification; procurement concentrates through group purchasing organizations.
- Home Office:Individual buyers drive transactional retail volumes with price-sensitive purchasing behavior and minimal standardization requirements.
Revenue concentration sits with Corporate; the steepest expansion trajectory belongs to Healthcare as clinical workstation digitization accelerates.
Connector Type:
Maturity gradients separate legacy infrastructure replacement from next-generation display protocol adoption.
- DisplayPort:High-refresh-rate monitor support drives adoption in gaming and professional visualization segments where 4K/144Hz specifications dominate.
- VGA:Analog connectivity persists in legacy projector installations and industrial control systems where infrastructure replacement cycles extend beyond a decade.
- DVI:Digital video interface installations concentrate in government and defense environments where security certification requirements delay connector modernization.
- Serial:Industrial automation and point-of-sale equipment sustain demand for RS-232 compatibility in manufacturing and retail verticals.
Shipments concentrate in DisplayPort; the fastest volume decline belongs to VGA as European e-waste regulations accelerate legacy equipment retirement.
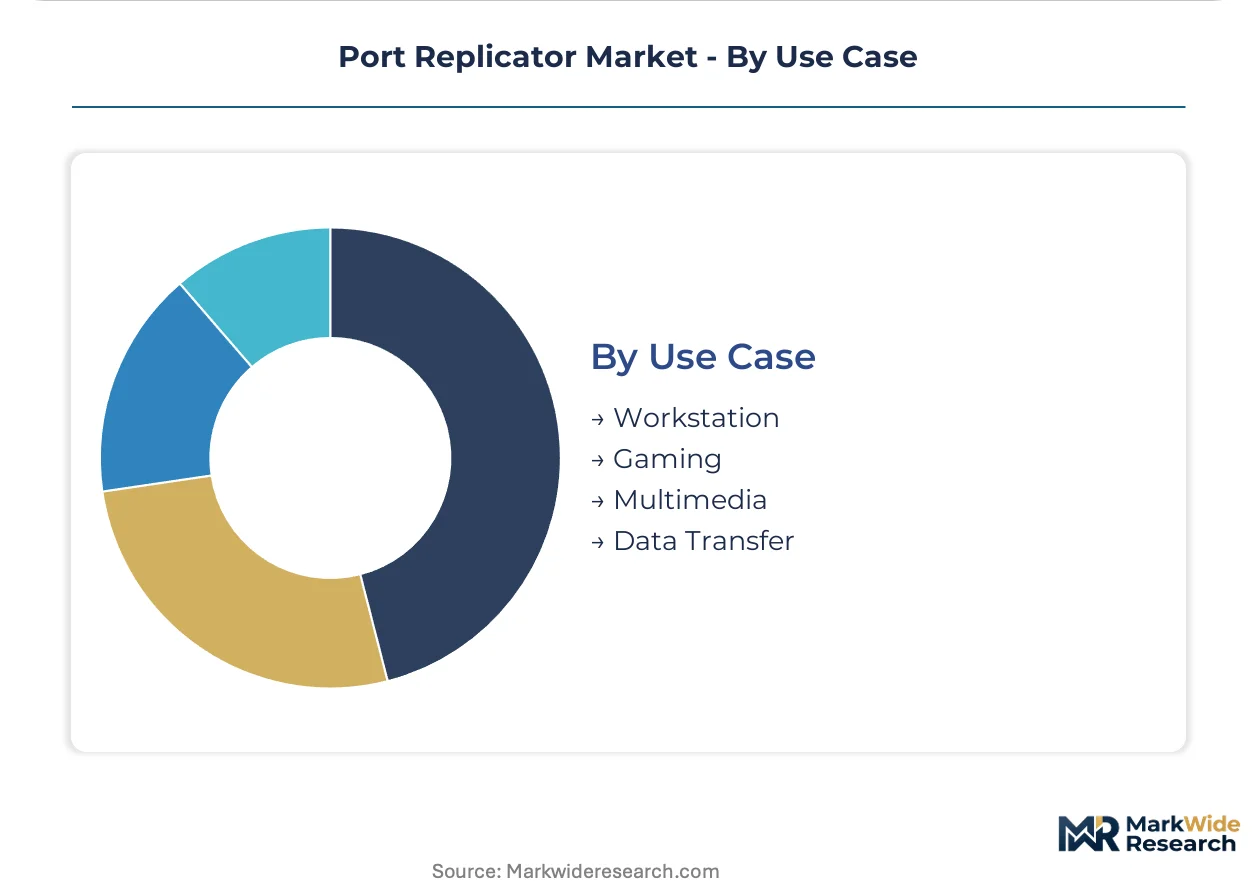
Use Case:
Application-specific bandwidth requirements fragment engineering resources across performance tiers.
- Workstation:Thunderbolt 4 certification and external PCIe enclosure support differentiate premium positioning for software development and data science workflows.
- Gaming:Low-latency peripheral connectivity and RGB synchronization protocols drive product differentiation in enthusiast retail channels.
- Multimedia:Consumer streaming and content consumption applications prioritize cost-optimized HDMI and USB-C solutions with minimal power delivery requirements.
- Data Transfer:High-volume storage synchronization and backup workflows demand sustained throughput for external NVMe arrays.
Engineering investment concentrates in Workstation; the fastest share gain belongs to Gaming as peripheral ecosystem integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese foundry capacity for USB4/Thunderbolt controllers anchors semiconductor supply for docking hardware, while final assembly operations diversify across Vietnam, Mexico, and India to reduce single-country manufacturing risk.
United States
Corporate hybrid work policies and IT fleet standardization drive dock procurement across Fortune 500 distributed workstations. FCC equipment authorization requirements govern electromagnetic compatibility certification for commercial-grade peripherals. Austin, Texas and the San Francisco Bay Area concentrate enterprise technology procurement decision-making for North American docking deployments.
Germany
Industrial workstation digitization and engineering software workflows sustain Thunderbolt 4 demand for CAD and simulation applications. REACH substance restrictions and RoHS compliance deadlines tighten material specifications for printed circuit board assemblies. Bavaria's automotive and machinery engineering clusters anchor high-performance docking requirements for technical computing environments.
Japan
Corporate IT refresh cycles and workstation standardization policies sustain peripheral ecosystem investments across Tokyo and Osaka enterprise markets. METI industrial standards and JIS certification requirements govern electrical safety and interoperability specifications. The Kanto region's concentration of electronics manufacturing headquarters drives procurement framework decisions for Asia-Pacific commercial channels.
China
Domestic electronics manufacturing restructuring and supply chain diversification efforts reshape final assembly geography for export-oriented docking hardware. MIIT equipment certification and GB standards compliance govern product market access requirements. The Pearl River Delta and Yangtze River Delta industrial corridors concentrate PCB fabrication and connector component production for global port replicator supply chains.
India
Small and medium enterprise IT modernization and government digital workplace initiatives create underserved docking penetration opportunities outside saturated Western markets. BIS certification requirements and PLI scheme incentives for electronics manufacturing influence local production investment decisions. Karnataka's Bangalore technology corridor and Maharashtra's Mumbai-Pune industrial zone concentrate emerging commercial channel demand for standardized connectivity solutions.
Port Replicator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular and specialty docking configurations. The vendor base stratifies across three tiers: multinational OEMs with enterprise service bundling capabilities, mid-scale specialists with certification depth, and cost-optimized assemblers serving transactional retail channels. Strategic archetypes include ecosystem-locked workstation bundlers, certification-heavy standards specialists, and geography-focused channel consolidators. Competitive moves concentrate on strategic partnerships for controller silicon access and portfolio diversification across USB-C and Thunderbolt performance tiers.
Within the multinational OEM tier, Dell Technologies exemplifies enterprise direct-relationship positioning, HP Inc. anchors workstation bundling archetypes, and Lenovo Group Limited occupies commercial channel distribution leadership. These three entities represent distinct competitive vectors: Dell Technologies through corporate contract scale, HP Inc. through integrated service agreements, and Lenovo Group Limited through Asia-Pacific ecosystem penetration. Their collective presence defines margin benchmarks and certification timelines that constrain specialist competitor positioning.
| Leading Market Players |
|---|
| Dell Technologies |
| HP Inc. |
| Lenovo Group Limited |
| Targus |
| Kensington |
| StarTech.com |
| Plugable Technologies |
| Belkin International |
| Anker Innovations |
| Others |
Value Network & Pricing Analysis
Copper futures pricing and PCB substrate cost indices cascade through port replicator manufacturing, compressing margin structures differently across warranty-bundled enterprise tiers versus transactional retail SKUs as OEMs absorb commodity volatility through multi-year fleet contract lock-ins.
Pricing Analysis
Warranty and service-bundling coverage separates enterprise procurement tiers from stripped retail offerings. Three-tier pricing structure across premium Thunderbolt, standard USB-C, and economy legacy tiers reflects certification grade differentiation and volume scale. Cost compression in mid-tier segments is intensifying because Thunderbolt 4 controller silicon scarcity concentrates supply leverage with Taiwanese foundries. Corporate IT buyers exhibit lowest price sensitivity due to total-cost-of-ownership frameworks, while home office purchasers drive transactional price elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for finished dock inventory. Controller silicon fabrication concentrates in Taiwan and South Korea, while final assembly draws from Vietnam, Mexico, and India diversification sites. Bill-of-materials rests on USB4 retimer chips, halogen-free PCB laminates, and GaN power components. Single-source vulnerability in Thunderbolt controller supply creates qualification bottlenecks. Distribution runs through value-added distributors and direct OEM enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European Union's Common Charger Directive and IEC 62368-1 safety certification requirements erect compliance moats that favor incumbent OEMs with established validation infrastructure and enterprise service bundling capabilities.
For Market Incumbents: Cement ecosystem lock-in through ThinkPad-style commercial channel control and deepen backward integration into Thunderbolt controller allocation agreements with Taiwanese foundries. Defend against modular dock startups by accelerating USB4/Thunderbolt convergence roadmaps that fragment engineering resources for specialist competitors. For New Entrants and Emerging Players: Launch via hardware-as-a-service distribution models targeting India's underserved SME IT modernization wave outside saturated Western corporate markets. Exploit certification timeline compression gaps by pre-qualifying designs against India's BIS requirements and European REACH substance restrictions before incumbent refresh cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor certification-heavy standards specialists with deep USB-IF validation relationships in Germany and Japan where IT-managed standardization policies concentrate procurement decisions. Long-term viability hinges on controller silicon access security. Monitor USB Implementers Forum validation queue lengths as inflection indicator for revenue recognition compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Thunderbolt 4 Controller Allocation Agreement | Secures fabrication priority with TSMC or Samsung Foundry for bandwidth-certified silicon. |
| Hardware-as-a-Service Platform Launch | Captures recurring revenue through Dell-style enterprise device management integration. |
| REACH/RoHS Compliance Certification | Unlocks German automotive and machinery engineering cluster procurement frameworks. |
| Asia-Pacific Commercial Channel Expansion | Penetrates India's Bangalore and Mumbai-Pune technology corridors outside Western saturation. |
| USB4/Thunderbolt Portfolio Convergence | Compresses specification gaps between premium and mid-tier dock segments for workstation buyers. |
Research Methodology
SEC 10-K filings, USB Implementers Forum certification databases, and customs/trade data formed the secondary backbone, supplemented by primary interviews with docking hardware product managers, enterprise IT procurement officers, and value-added distribution channel partners. Bottom-up shipment modeling and top-down OEM revenue triangulation validated segment splits across connectivity standards and end-user categories.
Historical trendline analysis of refresh cycle patterns and regulatory enforcement windows anchored CAGR derivation across the projection horizon. Segmentation dimensions modeled include product interface type, institutional buyer profile, performance tier, and regional compliance cluster. Forecast inputs incorporated semiconductor foundry capacity utilization rates and corporate hybrid work policy adoption curves.
Controller silicon supply disruptions, regulatory timeline accelerations, and enterprise budget freeze triggers are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cloud Gaming Baas Market
Others
Industrial PC Market
Others
Global ESD Protection Devices Market
Others
Profilometer Market
Others
Advertising Intelligence Solution Market
Others
Industrial Tablet PC Market
Others
Enterprise Video Content Management Market
Others
Brazil Cane Sugar Market
Others
Ceramic Machinery Market
Others
Solar Panel Testers Market
Others
Smart Plug Market
Others
Consumer Video Feedback Software Market
Others
Interference Mitigation Filters Market
Others
Europe Travel Retail Market
Others
Hot Air System Market
Others
Magnetic Stripe Readers Market