
 IT Device Market | 2026-2036
IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
IT Device Market Outlook
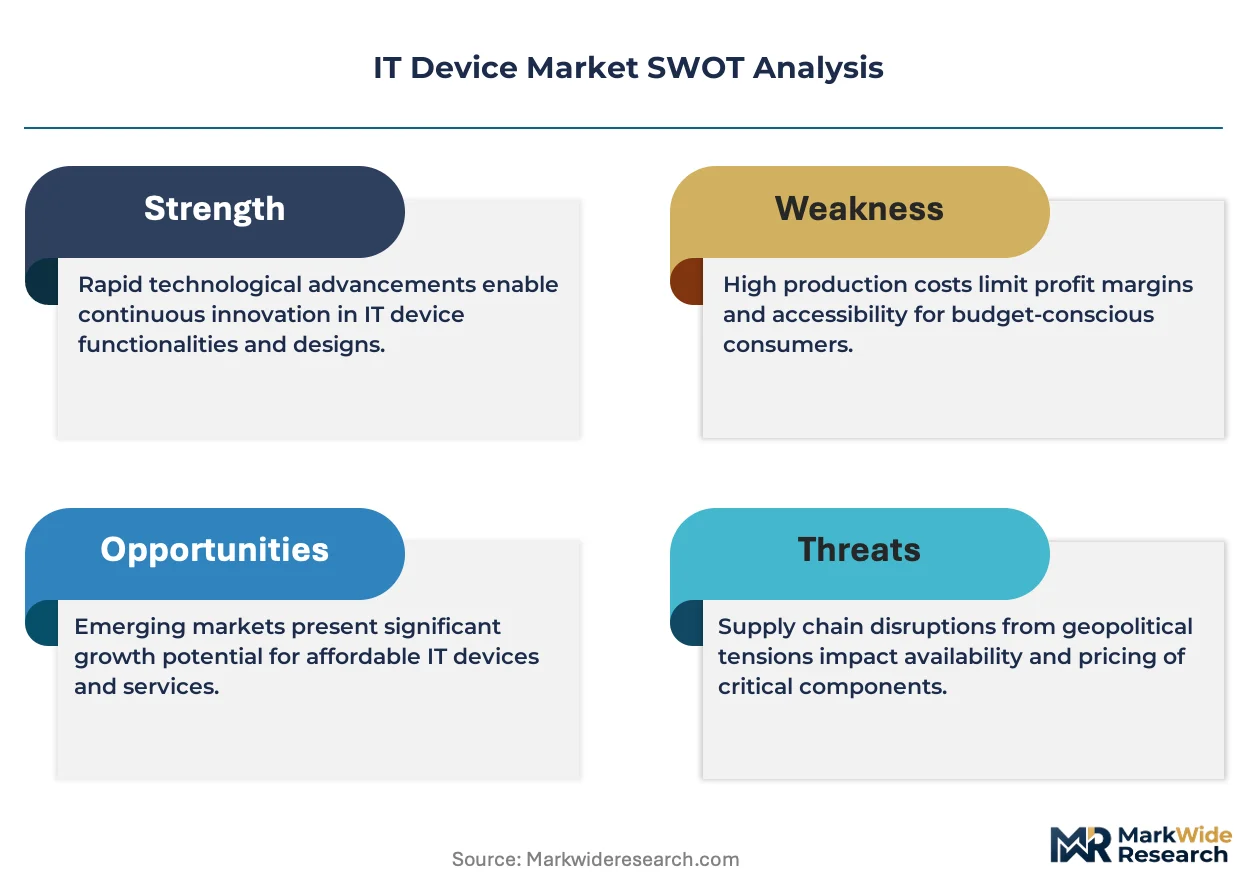
Premium enterprise-grade specifications is reorganizing procurement patterns across the IT Device Market. Apple sustains exceptional margin structures through silicon-level control and vertical integration of its M-series processors. Samsung Electronics dominates display and memory supply chains, leveraging captive production of OLED panels and NAND flash to secure component availability.
IT devices encompass computing, communication, and peripheral hardware engineered to process, store, or transmit digital information, typically operating on architectures with clock speeds exceeding 2 GHz and memory configurations scaling from 8 GB to 128 GB depending on workload intensity. Smartphones anchor volume demand but face margin compression as replacement cycles extend beyond four years in mature markets. Laptops generate disproportionate profit contribution within business and educational usage scenarios, where fleet standardization and security certifications command pricing premiums. Convertible form factors are gaining share in enterprise deployments, displacing dedicated tablets as hybrid work protocols stabilize.
The FCC governs electromagnetic emissions and wireless spectrum allocation for devices sold in the United States, while the EU AI Act and Ecodesign for Sustainable Products Regulation impose algorithmic transparency and circularity requirements on intelligent systems and hardware sold across Europe. India's BIS certification mandates safety and interoperability testing for imported electronics, creating compliance friction for unbranded manufacturers. Stakeholders must monitor how divergent repairability mandates and right-to-repair legislation across jurisdictions reshape product architecture decisions and aftermarket service economics.
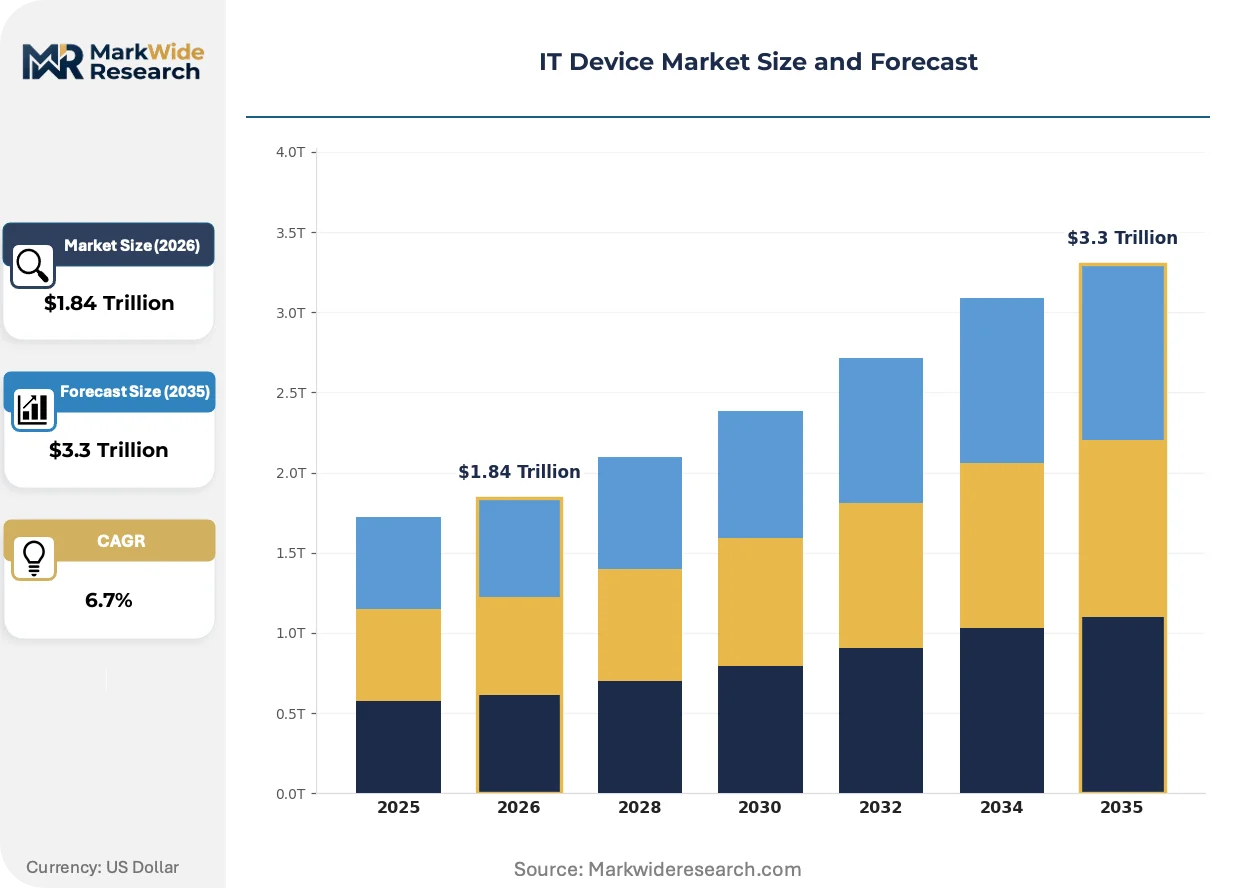
Market Dynamics
Enterprise cloud migration is compressing refresh cycles for data center infrastructure while endpoint hardware faces extended replacement timelines in mature economies, creating divergent demand pulses across the IT Device Market value chain.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandated repairability scores and recycled content thresholds are accelerating circular economy investments across European supply chains, creating premium positioning for compliant manufacturers.
- India PLI scheme:Production-linked incentives for electronics manufacturing are expanding domestic assembly capacity for smartphones and servers, reducing import dependency for government digitization programs.
- On-device AI inference:Neural processing unit integration into laptops and smartphones is pulling memory and compute upgrades across enterprise and consumer segments.
Market Restraints
- Memory supply concentration:Captive production of NAND flash and DRAM by Korean and Taiwanese semiconductor houses creates allocation risk during demand spikes.
- EU AI Act compliance friction:Algorithmic transparency requirements for intelligent systems impose documentation burdens that extend product development timelines.
- Extended smartphone replacement cycles:Device longevity improvements in mature markets compress annual unit volumes despite stable installed base expansion.
Strategic Opportunities
- India government digitization:Bureaucratic workflow modernization and rural connectivity programs are expanding procurement pipelines for domestic-assembled servers and tablets.
- Convertible form factor convergence:Hybrid work stabilization is displacing dedicated tablet deployments in enterprise fleets, opening attach-rate opportunities for stylus and docking peripherals.
- Right-to-repair legislation:State-level repair access mandates in the United States and EU directives are creating aftermarket service and spare parts revenue streams.
Industry Challenges
- Silicon design talent scarcity:Competition for chip architecture expertise between hyperscalers and traditional OEMs is inflating R&D compensation costs.
- Multi-jurisdiction certification timelines:Divergent BIS, FCC, and CE marking requirements delay product launches across target markets.
- Legacy fleet integration complexity:Zero-trust security architectures require hardware attestation features incompatible with depreciated endpoint generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Device Market |
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.3 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartphones, Laptops, Tablets, Desktops Operating System: Windows, macOS, Linux, Android Form Factor: Convertible, Ultrabook, All-in-One, Tower Usage Scenario: Personal, Educational, Business, Gaming |
| Companies Covered | Sony Group Corporation, Qualcomm Incorporated, Apple, Amphenol Corporation, Arista Networks, Microsoft, Intel Corporation, Texas Instruments Incorporated, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Device Market Strategic Shifts
Compute architecture specialization and regulatory circularity mandates are fragmenting product roadmaps, forcing simultaneous investment in high-performance silicon and modular repairable designs.
ARM-based processors are bifurcating the laptop market between power-efficient thin clients and performance workstations. Enterprise procurement teams are segmenting fleets by workload intensity, with knowledge workers receiving passively cooled designs and creative professionals retaining x86 compatibility. This architectural split is compressing margin pools for undifferentiated mid-range configurations.
The EU Ecodesign for Sustainable Products Regulation is mandating standardized fastener access and software update guarantees across hardware categories. Manufacturers must redesign chassis for component-level serviceability and establish decade-long spare parts commitments. Premium enterprise segments are absorbing compliance costs through certified sustainable procurement programs, while consumer lines face margin compression from redesign expenses.
Fleet standardization contracts are consolidating purchasing authority within enterprise IT departments, displacing individual department hardware autonomy. Device-as-a-service providers are capturing multi-year agreements that bundle hardware, management software, and end-of-life recovery. This concentration is most visible in North American and Western European education and healthcare verticals, where security certification requirements favor single-vendor relationships.
IT Device Market Segmentation
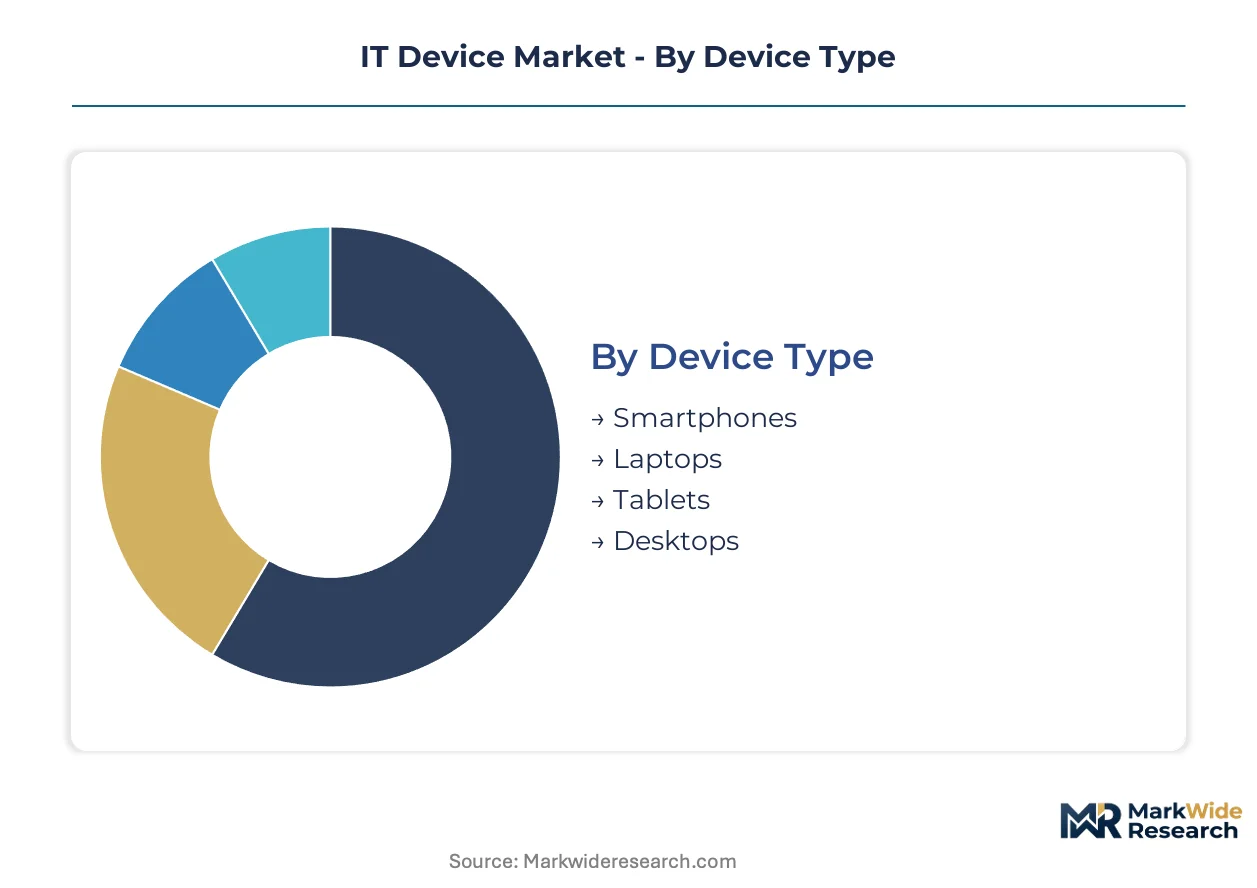
Segmentation in the IT Device Market reveals how procurement authority, workload intensity, and regulatory compliance reshape hardware specifications across customer tiers. Understanding these divides exposes where margin pools concentrate and which configurations face commoditization pressure.
Device Type:
Margin pools concentrate disproportionately in enterprise-grade laptops and premium smartphones, while desktop and tablet segments face volume-driven pricing compression.
- Smartphones:ARM-based SoCs with integrated NPUs now dominate flagship tiers, with memory configurations scaling to 12GB to support on-device AI inference. Demand concentrates in India under PLI scheme incentives, where local assembly capacity is expanding for government digitization procurement pipelines.
- Laptops:x86 and ARM architectures now bifurcate procurement patterns, with enterprise fleets segmenting between passively cooled thin clients for knowledge workers and performance workstations for creative professionals. Security certification requirements and fleet standardization contracts command pricing premiums in North American education and healthcare verticals.
- Tablets:Dedicated tablet deployments face displacement pressure as convertible form factors absorb hybrid work demand, compressing standalone volume in enterprise segments.
- Desktops:Tower configurations retain niche demand in workstation and gaming segments where thermal headroom enables discrete GPU expansion, though all-in-one designs capture space-constrained office environments.
The dominant share belongs to Smartphones, while Laptops are closing the gap fastest through enterprise fleet standardization and security certification premiums.
Operating System:
Volume distribution across this category tracks enterprise procurement authority and developer ecosystem concentration, with licensing economics creating divergent margin structures.
- Windows:Dominates enterprise fleet deployments through Active Directory integration and legacy application compatibility, with Microsoft extracting recurring revenue through subscription-based licensing models that bundle management tooling.
- macOS:Silicon-level control through Apple-designed processors enables exceptional margin structures, with vertical integration of hardware and software capturing premium positioning in creative professional and education segments.
- Linux:Open-source licensing eliminates per-unit software costs, attracting cloud-native enterprise workloads and developer-centric deployments where customization requirements outweigh commercial support preferences.
- Android:Google Mobile Services licensing creates revenue concentration at the platform level, while OEM competition in hardware tiers compresses device-level margins across mass-market smartphone segments.
Windows retains procurement dominance in regulated industries, though macOS is expanding fastest through education vertical standardization and silicon-level performance differentiation.
Form Factor:
Physical configuration choices increasingly reflect workspace constraints and thermal design power requirements rather than pure portability preferences.
- Convertible:Hinge mechanisms enabling 360-degree rotation are displacing dedicated tablet deployments in enterprise fleets, with stylus and docking peripheral attach rates expanding revenue per seat.
- Ultrabook:Sub-15mm chassis designs with passively cooled or low-TDP processors target knowledge worker segments where battery endurance and acoustic discretion outweigh raw compute requirements.
- All-in-One:Integrated display and system board designs reduce cable clutter in space-constrained office environments, though repairability mandates under EU Ecodesign regulations complicate service access.
- Tower:Expandable chassis configurations retain workstation and gaming demand where discrete GPU thermal envelopes and storage scalability justify physical footprint tradeoffs.
Convertible designs are gaining share fastest as hybrid work protocols stabilize, while Tower configurations defend niche positioning in performance-intensive workloads.
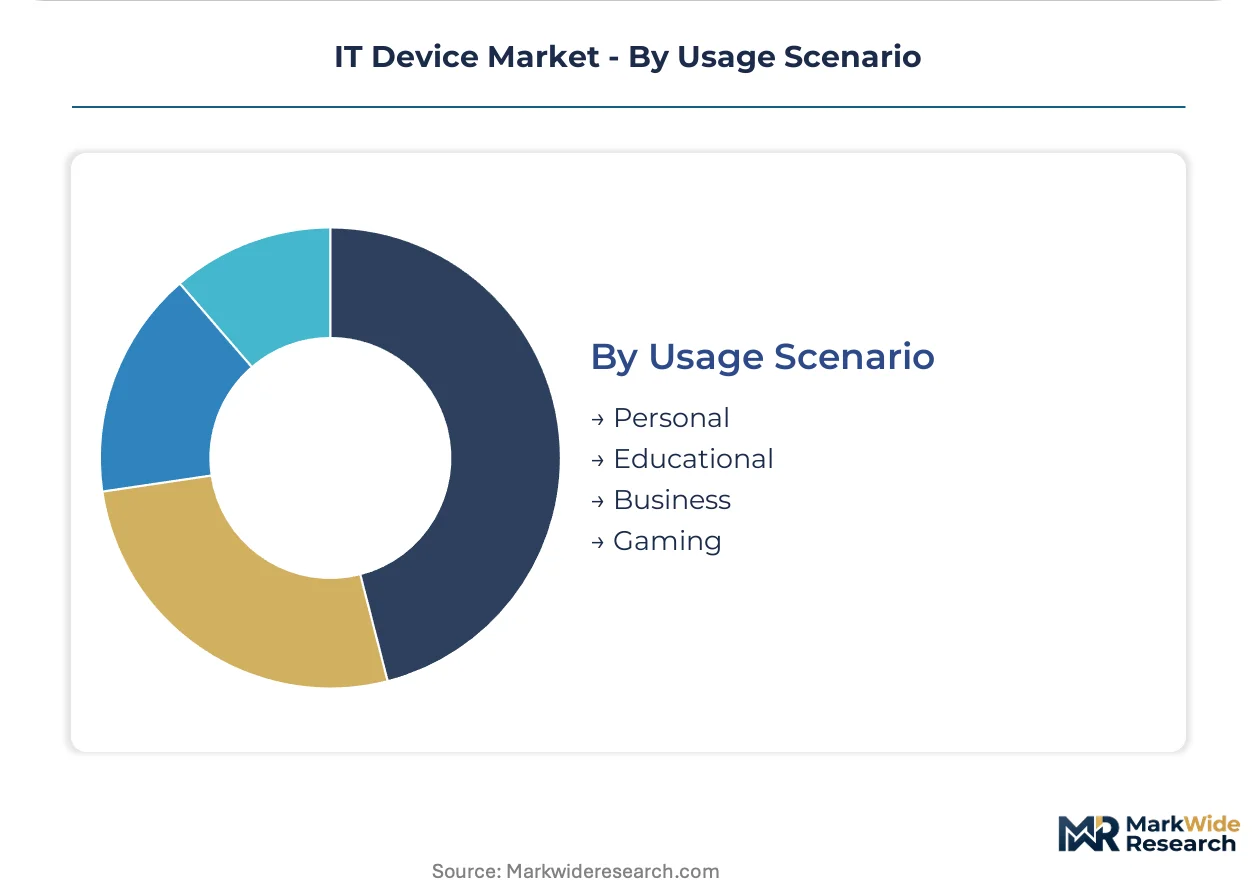
Usage Scenario:
End-use context determines security certification requirements, support contract structures, and hardware refresh cycle timing across the value chain.
- Personal:Consumer procurement faces extended replacement cycles beyond four years in mature markets, with device longevity improvements compressing annual unit volumes despite stable installed base expansion.
- Educational:K-12 and higher education verticals in North America and Western Europe are consolidating purchasing authority through multi-year device-as-a-service agreements that bundle hardware, management software, and end-of-life recovery.
- Business:Enterprise IT departments are capturing fleet standardization contracts that displace individual department hardware autonomy, with zero-trust security architectures requiring hardware attestation features incompatible with depreciated endpoint generations.
- Gaming:Discrete GPU thermal requirements and high-refresh display specifications sustain tower and performance laptop demand, though semiconductor allocation volatility creates supply friction during demand spikes.
Business usage commands the dominant procurement value, while Educational verticals are expanding fastest through consolidated purchasing authority and subscription-based service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping IT device manufacturing geography. Nations with domestic assembly capacity and favorable trade terms are capturing production migration from traditional hubs, while import-dependent markets face currency and compliance friction.
United States
Enterprise fleet refresh cycles and hyperscaler data center expansion drive hardware procurement. FCC electromagnetic emissions standards and spectrum allocation rules govern wireless device certification. Austin and Phoenix host expanding semiconductor fabrication clusters where advanced node production is scaling.
China
Domestic consumption and export manufacturing sustain dual demand channels for components and finished devices. MIIT equipment certification and GB standards mandate interoperability testing for network infrastructure. Shenzhen and Dongguan anchor the Pearl River Delta electronics manufacturing corridor where module assembly concentrates.
India
Government digitization programs and PLI scheme incentives are accelerating domestic smartphone and server assembly capacity. BIS safety and interoperability certification creates compliance gates for imported electronics. Tamil Nadu and Karnataka states host expanding contract manufacturing parks where export-oriented production is scaling.
Germany
Industrial automation and enterprise IT modernization sustain demand for ruggedized computing hardware. EU Ecodesign for Sustainable Products Regulation mandates repairability scores and recycled content thresholds for devices sold across Europe. Bavaria's Munich-Stuttgart corridor hosts precision engineering clusters where industrial computing specifications are developed.
South Korea
Captive memory and display production secures component allocation for domestic device manufacturers. MFDS and Korean Agency for Technology and Standards govern product safety and electromagnetic compatibility. Seoul Capital Area and Busan-Ulsan region host vertically integrated semiconductor and display fabrication facilities.
IT Device Market Competitive Environment
Concentration sits with semiconductor designers and systems integrators that control silicon architecture and software ecosystems. The vendor base spans vertically integrated hardware-software stacks, component specialists with captive production, and contract assemblers serving brand labels. Three archetypes dominate: silicon architects with processor-level control, display-memory conglomerates with component captive supply, and platform operators extracting recurring revenue through services. Competitive moves center on silicon design talent acquisition and multi-year enterprise fleet standardization contracts.
Among semiconductor architecture specialists, Qualcomm Incorporated and Intel Corporation exemplify the silicon-design archetype, each occupying positions where instruction set control and fabrication partnerships determine downstream device capabilities. Samsung Electronics anchors the component-captive tier through in-house production of OLED panels and NAND flash. Apple represents the integrated hardware-software stack, where processor design and operating system control capture premium positioning.
| Leading Market Players |
|---|
| Sony Group Corporation |
| Qualcomm Incorporated |
| Apple |
| Amphenol Corporation |
| Arista Networks |
| Microsoft |
| Intel Corporation |
| Texas Instruments Incorporated |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Ninety-day NAND flash lead times compress margin flexibility for device OEMs, binding pricing power to memory allocation priority from Korean and Taiwanese foundries while EU repairability mandates add chassis redesign costs.
Pricing Analysis
Enterprise IT buyers anchor three-tier pricing structure across premium, standard, and economy levels, with security certification tiers and silicon architecture generation driving differentiation. Apple and Microsoft extract subscription-based recurring revenue through bundled management tooling, while unbranded Android OEMs face cost compression from Google Mobile Services licensing fees. Pricing pressure stems from extended smartphone replacement cycles beyond four years in mature markets. Consumer segments exhibit highest price sensitivity, whereas healthcare and education verticals absorb premiums for fleet standardization and hardware attestation features.
Supply Chain Analysis
Inventory concentration in South Korea, Taiwan, and China governs component availability for global device assembly. Captive OLED panel and NAND flash production by Samsung Electronics and SK Hynix creates allocation bottlenecks during demand spikes. Memory supply draws from advanced node fabrication clusters in Hsinchu and Pyeongtaek, with lithography equipment dependencies tethered to ASML's EUV tool availability. Tariff exposure on Chinese-assembled modules threatens cost structures for US-bound shipments. Distribution runs through contract manufacturers in Shenzhen and contract assembly parks in Tamil Nadu for regional fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
On-device AI inference is accelerating memory and compute upgrades across enterprise and consumer segments, creating a high-growth disruption window for silicon architects and fleet service providers.
For Market Incumbents: Shield enterprise fleet relationships through multi-year device-as-a-service contracts that bundle hardware attestation, management software, and end-of-life recovery. Deepen backward integration into neural processing unit design to differentiate against Qualcomm and MediaTek alternatives. Prioritize BIS and FCC pre-certification investments to compress India and US launch timelines.
For New Entrants and Emerging Players: Aftermarket spare parts logistics represents a service-layer gap where incumbents under-serve, particularly under EU Ecodesign decade-long repairability mandates. Target state-level right-to-repair compliance in the US and modular chassis retrofit for depreciated enterprise fleets. Pursue certified refurbishment partnerships with education verticals seeking sustainability procurement credentials.
For Investors and Strategic Acquirers: Long-term, this sits as a silicon-design scarcity play because ARM architecture licensing and NPU integration expertise concentrate among fewer than ten global houses. Acquisition targets should display captive foundry relationships or hyperscaler co-development agreements. Watch hyperscaler capex disclosure shifts toward edge inference hardware as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Processing Unit Integration | On-device AI inference pulls memory upgrades across Qualcomm and Apple silicon roadmaps. |
| EU Ecodesign Compliance Program | Standardized fastener access and spare parts commitments reshape chassis engineering at Dell and HP. |
| India PLI Manufacturing Scale-Up | Foxconn and Dixon expand Tamil Nadu assembly capacity for government tablet procurement pipelines. |
| Enterprise Fleet Standardization Contract | Multi-year DaaS agreements consolidate purchasing authority within North American healthcare IT departments. |
| Right-to-Repair Service Network | Aftermarket parts distribution captures recurring revenue from EU repairability score mandates. |
Study Parameters
A standing panel of semiconductor procurement directors, enterprise IT fleet managers, contract manufacturing executives, and regulatory compliance officers provided ongoing calibration across primary interviews. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign implementing measure drafts, BIS certification registries, and hyperscaler capital expenditure disclosures. Bottom-up unit shipment modeling and top-down semiconductor revenue triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions included device type, operating system architecture, form factor mechanics, and usage scenario intensity. CAGRs derived from shipment elasticity coefficients and replacement cycle regression analysis. Forecast inputs incorporated PLI scheme capacity buildout schedules and EU AI Act compliance timeline assumptions.
Underlying assumptions cover stable memory pricing and foundry allocation priority, with deviation risk concentrated in geopolitical export controls and extended replacement cycle adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Indoor LBS Market
Others
Middle East and Africa Home Care Packaging Market
Others
Quadrant Scale Market
Others
Handheld Mobile Computers Market
Others
Hypersensitivity Market
Others
Legal Services Market
Others
Android STB and TV Market
Others
Global Aircraft Sensors Market
Others
Internet of Things Testing Market
Others
AI in Home Automation Market
Others
Storage Dewars Market
Others
France Smart Home Market
Others
Communication Base Station Body Market
Others
Digital Media Adaptor (DMA) Market
Others
Video Encoder Market
Others
Cremation Furnace Market